
Market Overview:
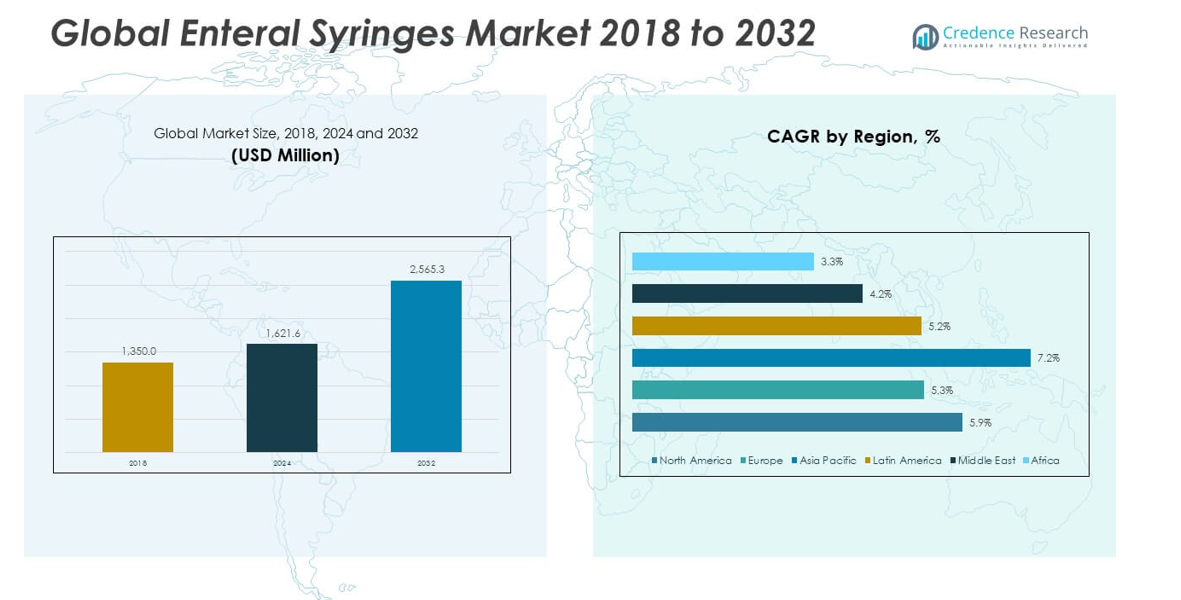
The Global Enteral Syringes Market size was valued at USD 1,350.00 million in 2018 to USD 1,621.62 million in 2024 and is anticipated to reach USD 2,565.31 million by 2032, at a CAGR of 5.94% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Enteral Syringes Market Size 2024 | USD 1,621.62 million |
| Enteral Syringes Market, CAGR | 5.94% |
| Enteral Syringes Market Size 2032 | USD 2,565.31 million |
The market is driven by the rising prevalence of chronic diseases requiring long-term nutritional support, growing neonatal and paediatrics care demand, and increasing adoption of enteral feeding in home healthcare settings. Advancements in syringe design to enhance accuracy, safety, and patient comfort, along with stringent regulations for preventing cross-contamination, further stimulate growth. Additionally, the shift toward disposable enteral syringes due to infection control awareness and supportive reimbursement policies bolsters market expansion.
North America leads the global market due to its advanced healthcare infrastructure, higher awareness levels, and early adoption of innovative enteral feeding solutions. Europe follows, supported by established clinical guidelines and robust government initiatives. The Asia-Pacific region is emerging rapidly, driven by expanding healthcare access, rising chronic disease incidence, and growing investments in hospital infrastructure, particularly in China and India.
Market Insights:
- The Global Enteral Syringes Market size was valued at USD 1,350.00 million in 2018, reached USD 1,621.62 million in 2024, and is projected to attain USD 2,565.31 million by 2032, registering a CAGR of 5.94% during the forecast period.
- Growing prevalence of chronic diseases and long-term nutritional support requirements are driving adoption in hospitals, home care, and long-term care facilities.
- Rising demand for disposable, single-use enteral syringes to prevent infections is propelling market expansion across developed and developing economies.
- High costs of advanced syringes and limited access in low-income regions remain major restraints affecting widespread adoption.
- North America leads the market due to advanced healthcare infrastructure, strong clinical guidelines, and early adoption of safety-compliant products.
- Europe follows closely, supported by stringent regulatory frameworks and established clinical protocols for enteral feeding.
- The Asia-Pacific region shows the fastest growth, driven by expanding healthcare infrastructure, rising chronic disease incidence, and increasing investments in hospital facilities.
Market Drivers:
Rising Chronic Disease Prevalence and Long-Term Nutritional Support Needs:
The Global Enteral Syringes Market benefits significantly from the growing burden of chronic illnesses such as cancer, neurological disorders, and gastrointestinal conditions that require long-term nutritional intervention. Hospitals and home care providers increasingly rely on enteral feeding to maintain patient health when oral intake is not possible. The demand for accurate and safe nutrient delivery drives the preference for advanced enteral syringes with precise volume control. Rising geriatric populations across developed and developing countries also contribute to the sustained requirement for enteral nutrition. Manufacturers respond by innovating syringe designs to improve safety and ease of use. Growing awareness about malnutrition management in vulnerable groups, including paediatrics and geriatrics, further supports adoption. Enhanced infection control protocols and single-use device mandates add to product demand. These factors collectively sustain the strong market momentum in this segment.
- For instance, Growing awareness about malnutrition management in vulnerable groups, including paediatrics and geriatrics, further supports adoption. Enhanced infection control protocols and single-use device mandates add to product demand, collectively sustaining strong market momentum.
Expanding Home Healthcare and Post-Hospital Care Requirements:
The increasing focus on reducing hospital stays and promoting recovery at home fuels the uptake of enteral syringes for post-discharge care. Patients with long-term feeding needs benefit from the convenience and cost-effectiveness of home-based enteral nutrition. The Global Enteral Syringes Market responds to this trend through products designed for easy handling by caregivers and patients. Training initiatives by healthcare providers improve confidence in at-home feeding administration. Rising insurance coverage for home enteral feeding enhances patient affordability. Government programs in various countries promote home care solutions to reduce healthcare system strain. This shift creates consistent demand for disposable, safe, and user-friendly syringes. The expanding network of home healthcare services strengthens product penetration in both urban and rural markets.
- For instance, Patients with long-term feeding needs benefit from the convenience and cost-effectiveness of home-based enteral nutrition.
Regulatory Standards and Infection Control Mandates:
Strict regulatory guidelines on enteral feeding devices encourage manufacturers to meet high safety and quality benchmarks. The Global Enteral Syringes Market gains traction from compliance-driven innovations such as ENFit connectors to prevent misconnections. Hospitals prioritize devices that meet ISO standards to reduce the risk of cross-contamination. Rising global campaigns to prevent healthcare-associated infections drive the replacement of reusable devices with single-use syringes. These standards also push suppliers to adopt high-grade materials and manufacturing processes. Improved labeling and color-coding systems further enhance patient safety. Governments support the enforcement of these guidelines through audits and inspections. Compliance with such standards strengthens consumer trust and supports sustained market growth.
Technological Advancements in Syringe Design and Material Innovation:
Advances in syringe design, materials, and manufacturing techniques improve functionality, durability, and patient comfort. The Global Enteral Syringes Market sees increased adoption of devices with clear volume markings, ergonomic grips, and smooth plunger actions. Innovations in biocompatible plastics and recyclable materials align with environmental goals. Manufacturers develop syringes compatible with multiple feeding systems to expand their usability. New production methods improve precision and reduce defects, ensuring consistent performance. User feedback influences ergonomic and operational improvements. These innovations not only enhance patient outcomes but also improve caregiver efficiency. Continuous R&D investments by market leaders ensure a steady pipeline of improved products.
Market Trends:
Shift Toward Sustainable and Eco-Friendly Materials:
Sustainability becomes a prominent factor influencing procurement decisions in healthcare. The Global Enteral Syringes Market sees rising interest in syringes made from recyclable and biodegradable materials. Hospitals and suppliers adopt eco-friendly devices to align with environmental targets. Manufacturers invest in reducing packaging waste and incorporating renewable raw materials. This trend reflects broader industry goals of lowering carbon footprints while maintaining safety standards. Government sustainability mandates influence purchasing preferences. Healthcare institutions adopt green procurement policies that favor environmentally responsible suppliers. Eco-friendly syringe adoption also strengthens corporate branding for manufacturers. This shift creates new competition parameters beyond cost and performance.
- For instance, Manufacturers are increasingly investing in reducing packaging waste and renewable raw materials, responding to government sustainability mandates and green procurement policies adopted by hospitals globally.
Digital Integration and Smart Enteral Syringe Systems:
Digital technologies increasingly enhance the accuracy and monitoring capabilities of enteral feeding devices. The Global Enteral Syringes Market witnesses the emergence of smart syringes integrated with sensors for dosage tracking. These systems connect to digital platforms, enabling remote monitoring by healthcare providers. Integration with hospital information systems supports better treatment records. Caregivers benefit from alerts and reminders for scheduled feeding sessions. Technological advancements also help reduce dosage errors and improve patient compliance. Hospitals view such systems as tools to enhance efficiency and reduce risks. Manufacturers collaborate with health-tech firms to accelerate product development. This trend aligns with the broader adoption of IoT-enabled medical devices.
- For instance, IoT-enabled devices integrate with hospital information systems, offering alerts and reminders, supporting caregivers, and reducing dosage errors, thus increasing operational efficiency in healthcare settings.
Expansion of Pediatric and Neonatal Care Applications:
Specialized care for pediatric and neonatal patients drives demand for small-volume, precise enteral syringes. The Global Enteral Syringes Market responds with products designed for delicate feeding needs in newborns and infants. These syringes feature soft tips, minimal dead space, and clear measurement markings. Rising investments in neonatal intensive care units boost demand. Pediatric care protocols emphasize gentle, accurate nutrient delivery, further supporting adoption. Parents and caregivers receive training to handle home-based pediatric feeding. Manufacturers introduce vibrant color-coding to prevent medication errors in pediatric settings. This segment benefits from higher awareness of early nutrition’s impact on long-term health.
Strategic Collaborations and Distribution Expansion:
Collaborations between syringe manufacturers and healthcare distributors enhance market reach. The Global Enteral Syringes Market experiences growth through partnerships that expand supply chains into underserved regions. Joint ventures with local firms support compliance with regional regulations. Distribution agreements improve product availability in emerging markets. Hospitals prefer suppliers with reliable delivery networks and technical support. Training programs conducted by suppliers improve product adoption rates. These collaborations also facilitate bulk purchasing agreements that benefit both parties. Market leaders use strategic alliances to strengthen brand recognition and secure competitive advantages.
Market Challenges:
High Cost of Advanced Syringes and Limited Access in Low-Income Regions:
The Global Enteral Syringes Market faces constraints due to the high cost of advanced devices, which limits adoption in price-sensitive markets. Hospitals in low-income regions often rely on basic products with fewer safety features. Limited healthcare budgets and inadequate reimbursement policies hinder access to high-quality syringes. Manufacturers struggle to balance affordability with compliance to international safety standards. Import restrictions and tariffs further increase costs in some countries. Healthcare providers in rural areas face difficulties in maintaining steady supply chains. This cost-access imbalance slows market penetration in underdeveloped healthcare systems. Without targeted subsidy programs, adoption rates may remain uneven globally.
Regulatory Complexity and Supply Chain Vulnerabilities:
Diverse regulatory requirements across countries create hurdles for market expansion. The Global Enteral Syringes Market must navigate varying certification processes, which delay product launches. Changes in international safety standards require costly modifications to manufacturing processes. Geopolitical tensions and pandemic-related disruptions expose supply chain weaknesses. Delays in raw material procurement affect production timelines. Manufacturers face challenges in securing consistent quality across global operations. Disruptions in transportation increase delivery lead times for critical medical devices. These factors contribute to operational inefficiencies that impact market competitiveness.
Market Opportunities:
Growing Demand in Emerging Healthcare Systems:
Emerging economies present significant growth potential due to rising healthcare investments and improving infrastructure. The Global Enteral Syringes Market can expand by catering to increasing hospital construction and modernization projects. Governments in these regions invest in programs to improve access to essential medical devices. Rising disposable incomes and better insurance coverage increase patient affordability. Partnerships with local distributors can improve product reach. Tailored product offerings designed for local needs enhance acceptance. Targeted awareness campaigns help overcome cultural and knowledge barriers in enteral feeding adoption.
Product Differentiation Through Innovation and Customization:
Manufacturers have opportunities to gain competitive advantage by offering customized solutions for specific patient groups. The Global Enteral Syringes Market can benefit from syringes tailored for pediatric, geriatric, or critical care use. Incorporating ergonomic designs, improved material safety, and enhanced measurement accuracy can create differentiation. Collaborations with healthcare providers for co-developed products improve adoption rates. Integrating digital tracking features can attract technologically advanced healthcare facilities. Focusing on ease of use and safety can increase loyalty among end users. This approach can also support premium pricing strategies in developed markets.
Market Segmentation Analysis:
By Type
The Global Enteral Syringes Market is segmented into plastic, glass, and pre-filled enteral syringes. Plastic syringes lead due to affordability, ease of disposal, and strong infection control compliance. Glass syringes maintain relevance in specialized applications requiring high chemical resistance. Pre-filled syringes are witnessing increased adoption in critical care settings for their convenience, accuracy, and reduced preparation time.
- For instance, Terumo leads in plastic enteral syringes known for infection control compliance and affordability, whereas specialized glass syringes are reserved for chemical-resistant applications.
By Application
Feeding dominates the market, driven by the rising prevalence of patients with swallowing difficulties or gastrointestinal conditions. Medication administration and enteral nutrition are expanding segments, supported by home-based healthcare growth. Water and flush administration serves a vital role in routine feeding tube maintenance, ensuring optimal functionality and hygiene.
- For instance, Feeding is the dominant application, with Fresenius Kabi’s enteral nutrition systems widely used for patients with swallowing or gastrointestinal issues. Medication administration and flush water roles are also expanding in the growing home healthcare environment.
By End-user
Hospitals hold the largest share due to advanced infrastructure and high patient inflows. Homecare settings are experiencing strong growth as healthcare systems shift toward recovery outside hospital environments. Long-term care facilities and ambulatory surgical centers contribute consistently, meeting diverse patient care requirements.
By Size
Available sizes include 1 mL, 5 mL, 10 mL, 20 mL, and other sizes. Smaller syringes are used extensively in pediatric and neonatal care, while larger capacities meet adult feeding and hydration demands. This range enables precision dosing across age groups and medical needs.
By Distribution Channel
Direct sales dominate institutional procurement, ensuring reliable supply and compliance. Online retailers are gaining momentum in homecare markets. Medical supply stores and pharmacies provide wide accessibility for both institutional and individual buyers, strengthening overall product availability.
Segmentation:
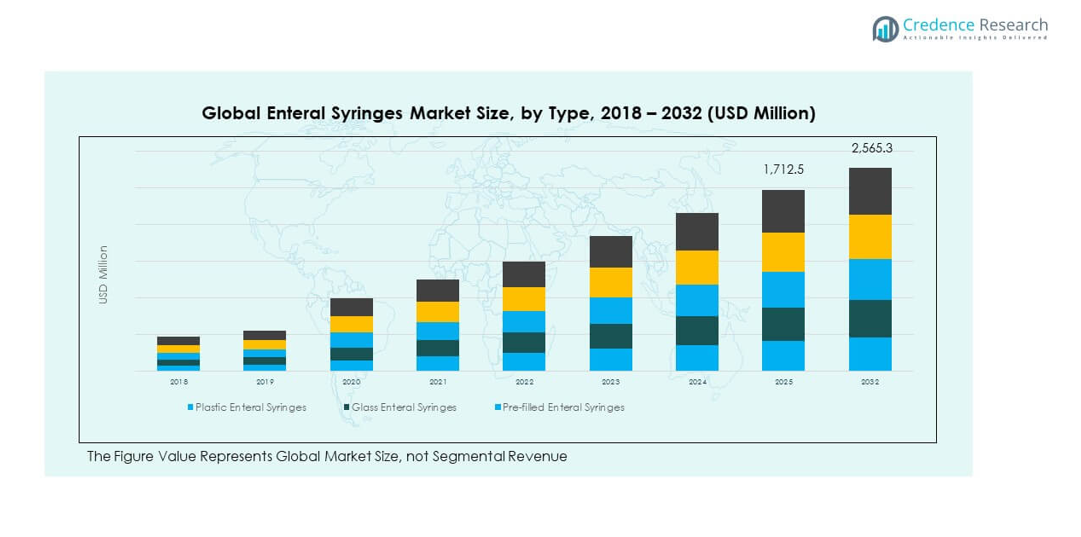
By Type
- Plastic Enteral Syringes
- Glass Enteral Syringes
- Pre-filled Enteral Syringes
By Application
- Feeding
- Medication Administration
- Enteral Nutrition
- Water and Flush Administration
By End-user
- Hospitals
- Homecare Settings
- Long-term Care Facilities
- Ambulatory Surgical Centers
By Size
- 1 mL Enteral Syringes
- 5 mL Enteral Syringes
- 10 mL Enteral Syringes
- 20 mL Enteral Syringes
- Other Sizes
By Distribution Channel
- Direct Sales
- Online Retailers
- Medical Supply Stores
- Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Enteral Syringes Market size was valued at USD 440.10 million in 2018 to USD 521.50 million in 2024 and is anticipated to reach USD 823.73 million by 2032, at a CAGR of 5.9% during the forecast period. It accounts for approximately 32.17% of the global market in 2024. Strong healthcare infrastructure, advanced clinical protocols, and early adoption of innovative feeding solutions drive growth in this region. The United States leads the market, supported by high healthcare expenditure and robust homecare adoption rates. Hospitals and long-term care facilities consistently upgrade to ENFit-compliant devices to meet safety regulations. The prevalence of chronic illnesses and a rapidly aging population further fuels demand. Direct sales channels dominate institutional procurement, while online platforms serve the homecare segment. Manufacturers focus on product differentiation and strategic partnerships to maintain market leadership. This region remains a primary hub for product innovation and regulatory standard setting.
Europe
The Europe Enteral Syringes Market size was valued at USD 384.08 million in 2018 to USD 444.77 million in 2024 and is anticipated to reach USD 667.63 million by 2032, at a CAGR of 5.3% during the forecast period. It holds around 27.40% of the global market in 2024. Strong emphasis on patient safety and adherence to ISO-compliant designs drive widespread adoption across hospitals and care facilities. Countries such as Germany, the UK, and France lead demand, with supportive government policies for enteral feeding devices. Homecare adoption is increasing as healthcare systems promote shorter hospital stays. The region benefits from mature distribution networks and specialized suppliers. Growth in pediatric and geriatric patient care fuels diverse size requirements. Reimbursement policies in several European nations enhance patient access to high-quality devices. The market is also influenced by environmental regulations encouraging sustainable syringe materials.
Asia Pacific
The Asia Pacific Enteral Syringes Market size was valued at USD 348.30 million in 2018 to USD 435.97 million in 2024 and is anticipated to reach USD 757.54 million by 2032, at a CAGR of 7.2% during the forecast period. It represents about 26.83% of the global market in 2024. Rapid urbanization, rising healthcare investments, and increasing chronic disease prevalence drive strong regional demand. China, Japan, and India are the primary growth engines due to expanding hospital networks and government health programs. The adoption of home-based enteral feeding is growing in metropolitan areas. Local manufacturing capabilities are improving, reducing dependency on imports. Pediatric and elderly patient populations present significant growth opportunities for tailored syringe sizes. Competitive pricing strategies make products more accessible in middle-income segments. Partnerships between international brands and local distributors strengthen market reach.
Latin America
The Latin America Enteral Syringes Market size was valued at USD 112.32 million in 2018 to USD 133.93 million in 2024 and is anticipated to reach USD 200.27 million by 2032, at a CAGR of 5.2% during the forecast period. It contributes approximately 8.24% of the global market in 2024. Brazil dominates the region, supported by expanding hospital infrastructure and rising healthcare awareness. Economic improvements in several countries are increasing healthcare expenditure. Demand is concentrated in urban centers where specialized care facilities operate. Import dependence remains high, with regulatory approval timelines affecting product availability. Growing awareness of infection control measures drives preference for disposable syringes. The homecare segment is gradually expanding with improved patient education. Manufacturers focus on competitive pricing and targeted distribution partnerships to strengthen presence.
Middle East
The Middle East Enteral Syringes Market size was valued at USD 39.83 million in 2018 to USD 43.94 million in 2024 and is anticipated to reach USD 60.56 million by 2032, at a CAGR of 4.2% during the forecast period. It holds roughly 2.70% of the global market in 2024. Demand is concentrated in GCC countries, driven by advanced healthcare facilities and high per capita healthcare expenditure. Hospitals prioritize ISO-compliant and ENFit-compatible products to meet international standards. Government healthcare modernization programs support market expansion. Private sector investment in specialty care facilities also boosts demand. Import reliance is high, creating opportunities for global manufacturers to enter through distribution partnerships. The pediatric and geriatric care segments present growing opportunities. Price sensitivity in non-GCC countries requires tailored product offerings.
Africa
The Africa Enteral Syringes Market size was valued at USD 25.38 million in 2018 to USD 41.52 million in 2024 and is anticipated to reach USD 55.59 million by 2032, at a CAGR of 3.3% during the forecast period. It accounts for about 3.66% of the global market in 2024. Growth is supported by improving healthcare infrastructure and increasing awareness of enteral feeding benefits. South Africa leads adoption due to relatively advanced healthcare services. Limited access in rural areas and budget constraints hinder wider market penetration. Donor-funded healthcare programs and non-governmental initiatives improve product availability in underserved areas. Most products are imported, with few local manufacturers. Hospital demand is primarily for basic plastic syringes due to cost considerations. Gradual improvements in public health funding are expected to create opportunities for higher-quality products.
Key Player Analysis:
- Braun Melsungen
- BD
- Cardinal Health
- Terumo
- Koninklijke Philips
- Thermo Fisher Scientific
- GBUK Enteral
- Baxter International
- Vygon SA
Competitive Analysis:
The Global Enteral Syringes Market features a competitive landscape dominated by established medical device companies. It includes major players such as B. Braun, BD, Cardinal Health, Terumo, Thermo Fisher Scientific, Baxter International, Koninklijke Philips, GBUK Enteral, and Vygon. Each player competes through differentiation in product features, such as ENFit connector design, dosage accuracy, and ergonomics. It balances compliance with global safety standards, cost-efficiency, and innovation. Market entry requires strong distribution networks, regulatory clearance, and brand trust. Institutional buyers such as hospitals and homecare providers favor suppliers with proven quality and supply reliability. It rewards companies that deliver tailored value-whether via specialized syringe types, multiple size formats, or home-use adaptable options-while maintaining high production standards.
Recent Developments:
- In July 2025, B. Braun Melsungen expanded its product portfolio to include seven Heparin Premixed Sodium Injection products, reinforcing its commitment to critical IV fluid supply in the US healthcare market. This expansion enhances their critical care offerings, although it is not specific to enteral syringes, it reflects ongoing innovation relevant to its medical device segment including enteral care equipment.
- In June 2023, Cardinal Health began distributing a new version of its Monoject enteral syringes with changed dimensions and a new contract manufacturer. However, in February 2024, Cardinal Health issued a recall for certain Monoject syringes due to potential issues with syringe pump compatibility that could affect dosage accuracy with enteral feeding pumps, emphasizing the company’s active quality control and regulatory responsiveness in this area.
Market Concentration & Characteristics:
The Global Enteral Syringes Market maintains moderate concentration. A few large multinational players control significant shares by leveraging R&D, broad distribution, and regulatory expertise, while numerous smaller manufacturers serve niche hospital and homecare segments. It reflects varied customer needs-from cost-sensitive markets to high-compliance environments-enabling both scale economies and localized innovation. It emphasizes safety and usability, driving product enhancements and strategic alliances.
Report Coverage:
The research report offers an in-depth analysis based on type, application, end-user, size, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global demand for enteral feeding solutions will support steady product adoption across hospital and homecare settings.
- Increased healthcare investments in emerging economies will expand market penetration in underserved regions.
- Technological innovations in syringe materials and design will enhance safety, accuracy, and ease of use.
- Sustainable and recyclable material adoption will align product development with environmental goals.
- Digital integration and smart monitoring capabilities will improve dosage accuracy and compliance tracking.
- Pediatric and geriatric care requirements will drive demand for specialized sizes and designs.
- Regulatory harmonization across regions will streamline product approvals and accelerate market entry.
- Strategic partnerships between global manufacturers and regional distributors will improve supply chain efficiency.
- Expansion of telehealth and remote care models will boost home-use syringe demand.
- Competitive differentiation will increasingly focus on user experience, ergonomics, and infection control features.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases and Long-Term Nutritional Needs
Increasing rates of cancer, neurological, and gastrointestinal disorders are driving demand for enteral syringes as more patients require long-term nutritional support, both in hospitals and homecare settings.
Expansion of Home Healthcare and Post-Hospital Care
Healthcare systems are shifting toward shorter hospital stays and greater use of home-based care, boosting demand for user-friendly, disposable enteral syringes that enable safe and convenient feeding outside clinical environments.
Stringent Regulatory Standards and Infection Control Mandates
Tighter regulations and infection control protocols, such as requirements for ENFit connectors and single-use devices, are accelerating the adoption of advanced enteral syringes that minimize cross-contamination risks.
Technological Advancements in Syringe Design and Materials
Innovations in syringe ergonomics, biocompatible and recyclable materials, and digital integration for dosage tracking are enhancing safety, accuracy, and patient comfort, supporting broader market adoption.
Growing Pediatric and Geriatric Care Demand
Rising awareness of malnutrition management and the need for precise, gentle feeding solutions in pediatric and elderly populations are fueling demand for specialized enteral syringes in various sizes and designs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Enteral Syringes Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Enteral Syringes Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Global Enteral Syringes Market?
What are the major challenges in the enteral syringes market?
Who are the leading companies in the Global Enteral Syringes Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Size
- 1.2.1 1 mL Enteral Syringes
- 1.2.2 5 mL Enteral Syringes
- 1.2.3 10 mL Enteral Syringes
- 1.2.4 20 mL Enteral Syringes
- 1.2.5 Other Sizes
- 1.3 By Type
- 1.3.1 Plastic Enteral Syringes
- 1.3.2 Glass Enteral Syringes
- 1.3.3 Pre-filled Enteral Syringes
- 1.4 By End-user
- 1.4.1 Hospitals
- 1.4.2 Homecare Settings
- 1.4.3 Long-term Care Facilities
- 1.4.4 Ambulatory Surgical Centers
- 1.5 By Application
- 1.5.1 Feeding
- 1.5.2 Medication Administration
- 1.5.3 Enteral Nutrition
- 1.5.4 Water and Flush Administration
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,350.00 million → 2032: USD 2,565.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enteral Syringes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enteral Syringes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Enteral Syringes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Enteral Syringes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enteral Syringes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enteral Syringes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enteral Syringes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enteral Syringes Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,350.00 million → 2032: USD 2,565.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enteral Syringes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Size - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 1 mL Enteral Syringes
- 12.3.7.2 5 mL Enteral Syringes
- 12.3.7.3 10 mL Enteral Syringes
- 12.3.7.4 20 mL Enteral Syringes
- 12.3.7.5 Other Sizes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plastic Enteral Syringes
- 12.4.7.2 Glass Enteral Syringes
- 12.4.7.3 Pre-filled Enteral Syringes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Homecare Settings
- 12.5.7.3 Long-term Care Facilities
- 12.5.7.4 Ambulatory Surgical Centers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Feeding
- 12.6.7.2 Medication Administration
- 12.6.7.3 Enteral Nutrition
- 12.6.7.4 Water and Flush Administration
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enteral Syringes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Enteral Syringes Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Enteral Syringes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Enteral Syringes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 B. Braun Melsungen
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BD (Becton, Dickinson and Company)
- 18.4 Cardinal Health
- 18.5 Terumo
- 18.6 Koninklijke Philips
- 18.7 Thermo Fisher Scientific
- 18.8 GBUK Enteral
- 18.9 Baxter International
- 18.10 Vygon SA
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

