
OTC Cough, Cold And Allergy Medicine Market Overview:
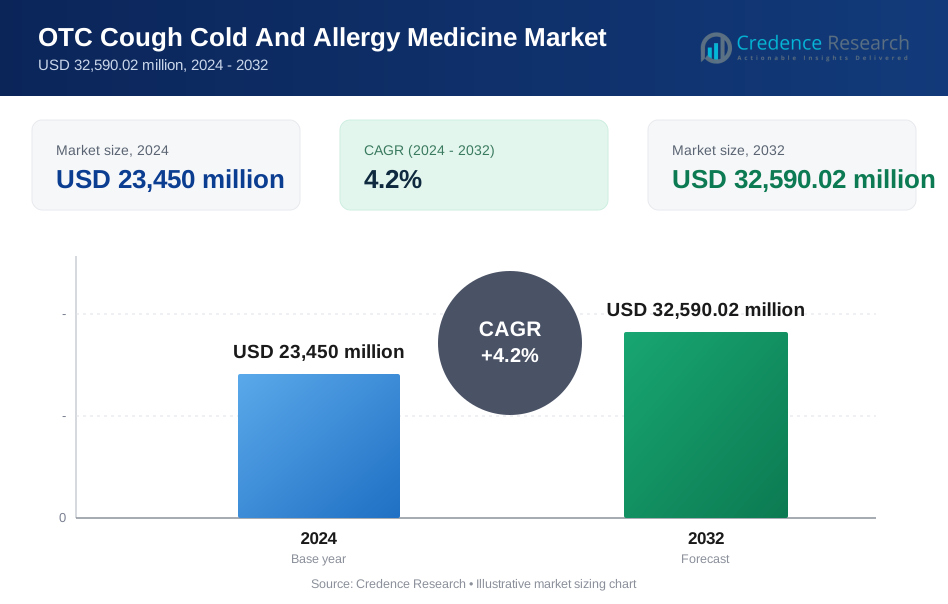
The global OTC cough, cold, and allergy medicine market was valued at USD 23,450 million in 2024 and is projected to reach USD 32,590.02 million by 2032, expanding at a compound annual growth rate (CAGR) of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| OTC Cough, Cold And Allergy Medicine Market Size 2024 | USD 23,450 million |
| OTC Cough, Cold And Allergy Medicine Market, CAGR | 4.2% |
| OTC Cough, Cold And Allergy Medicine Market Size 2032 | USD 32,590.02 million |
OTC Cough, Cold And Allergy Medicine Market Insights
- Market growth is driven by rising prevalence of respiratory infections and allergies, increasing air pollution, and a strong shift toward self-medication, with OTC antihistamines dominating by drug type at around 35% share due to frequent allergy incidence.
- Key market trends include growing demand for non-drowsy and combination formulations, expanding online pharmacy sales, and increased preference for adult multi-symptom products, with adults accounting for nearly 58% of total application demand.
- The competitive landscape is moderately consolidated, led by multinational players leveraging strong brand portfolios, extensive pharmacy distribution, aggressive marketing, and frequent line extensions across cough, cold, and allergy categories.
- Regionally, North America leads with about 37% market share, followed by Europe at nearly 27%, while Asia-Pacific holds around 23% and remains the fastest-growing region due to urbanization, pollution exposure, and expanding OTC access.

OTC Cough, Cold And Allergy Medicine Market Segmentation Analysis:
By Drug Type:
By drug type, OTC antihistamines represent the dominant sub-segment, accounting for an estimated 34-36% of total market share. Their leadership is driven by the high prevalence of allergic rhinitis, seasonal allergies, and pollution-induced respiratory symptoms, particularly in urban populations. Second-generation, non-drowsy antihistamines are widely preferred due to improved safety profiles and once-daily dosing convenience. OTC expectorants hold a significant secondary position, supported by demand for productive cough relief, while bronchodilators and OTC antibiotics maintain limited but steady uptake, primarily in markets with permissive OTC regulations.
- For instance, Bayer’s Claritin® (loratadine) is formulated at a 10 mg once-daily oral dose with minimal blood-brain barrier penetration, a property demonstrated in controlled pharmacokinetic studies showing negligible sedation at therapeutic concentrations.
By OTC Channel:
By OTC channel, pharmacies dominate distribution with approximately 38-41% market share, supported by strong consumer trust, pharmacist recommendations, and immediate access to branded and generic products. Pharmacies play a critical role in guiding self-medication decisions, particularly for pediatric and elderly patients. Drug stores follow closely, benefiting from dense urban penetration and extended operating hours. Modern trade channels continue to gain visibility through bundled promotions and seasonal displays, while online channels are the fastest-growing, driven by digital health adoption, subscription refills, and doorstep delivery convenience.
- For instance, Walgreens Boots Alliance operates more than 8,700 retail pharmacies in the U.S. alone, with in-store pharmacists trained to conduct medication therapy management sessions that typically last 15-30 minutes per patient encounter.
By Application:
By application, adults form the dominant sub-segment, contributing nearly 56-59% of overall demand, due to higher exposure to workplace stress, pollution, smoking-related irritation, and recurring seasonal allergies. Adults also exhibit greater self-medication behavior and purchasing frequency for multi-symptom relief products. School-age children represent a sizable secondary segment, supported by recurrent viral infections and school-related exposure. The babies segment remains smaller but stable, constrained by stricter formulation requirements, dosage limitations, and strong parental reliance on pediatrician and pharmacist guidance.
Key Growth Drivers
Rising Prevalence of Allergies and Respiratory Infections
The increasing incidence of allergic rhinitis, seasonal flu, common cold, and pollution-related respiratory conditions is a primary driver of growth in the OTC cough, cold, and allergy medicine market. Urbanization, worsening air quality, and climate variability have significantly expanded the at-risk population across both developed and emerging economies. Longer allergy seasons and higher pollen counts have increased recurring medication use, particularly antihistamines and combination therapies. Additionally, frequent viral exposure in schools and workplaces sustains year-round demand beyond traditional winter peaks. Consumers increasingly rely on readily available OTC therapies for early symptom management, reducing physician visits for mild conditions and reinforcing repeat purchases.
- For instance, IQAir’s air quality monitoring network reported that several major metropolitan cities consistently recorded annual average PM2.5 concentrations exceeding 50 µg/m³, levels associated with higher rates of upper respiratory symptoms requiring symptomatic treatment.
Strong Consumer Shift Toward Self-Medication
Growing consumer awareness, improved health literacy, and cost sensitivity have accelerated the shift toward self-medication using OTC products. Easy access to labeled dosing instructions, pharmacist guidance, and trusted branded formulations enables consumers to manage cough, cold, and allergy symptoms independently. Rising healthcare costs and longer wait times for primary care consultations further support this trend. Adults, in particular, prefer OTC multi-symptom products that offer quick relief and convenience. The expansion of retail pharmacies and digital health information platforms has strengthened confidence in self-treatment, making OTC solutions a first-line choice for non-chronic respiratory and allergic conditions.
- For instance, Haleon’s Panadol® and Otrivin® OTC respiratory care products follow standardized dosing labels aligned with regulatory monographs. Otrivin® 0.1% xylometazoline metered-dose nasal sprays deliver a precisely metered 0.14 mg dose per actuation. These products utilize advanced pump systems, such as Aptar Pharma's Lateral Control System, validated for delivering a consistent mist volume across their usable lifespan.
Broad Product Availability and Brand Expansion
Continuous expansion of product portfolios by leading consumer healthcare companies is driving sustained market growth. Manufacturers actively introduce line extensions across syrups, tablets, nasal sprays, and pediatric formulations to address diverse consumer needs. Flavor improvements, sugar-free variants, non-drowsy profiles, and age-specific dosing have increased adoption across applications. Strong brand recognition and advertising investments reinforce consumer trust, particularly during seasonal demand spikes. Widespread availability across pharmacies, drug stores, modern trade, and online platforms ensures high product visibility and accessibility, supporting consistent sales volumes and brand loyalty.
Key Trends & Opportunities
Growth of Non-Drowsy and Combination Formulations
Consumer preference is shifting toward non-sedating antihistamines and combination products that deliver multi-symptom relief in a single dose. Products combining antihistamines, decongestants, and cough suppressants reduce pill burden and improve compliance. This trend creates opportunities for manufacturers to differentiate through optimized formulations and extended-release technologies. Demand is particularly strong among working adults and students seeking symptom relief without impairing alertness. As regulatory frameworks evolve, innovation in combination dosing and delivery formats offers attractive growth potential across mature and emerging markets.
- For instance, Sanofi’s Allegra® (fexofenadine) is formulated at a 120 mg and 180 mg once-daily dose, with clinical pharmacology data confirming negligible central nervous system penetration and no measurable impairment in psychomotor performance tests at therapeutic levels.
Expansion of Online and Digital Health Channels
The rapid growth of e-commerce and digital pharmacies presents a significant opportunity for OTC cough, cold, and allergy medicines. Online platforms enable convenient purchasing, discreet delivery, and access to product comparisons and reviews. Subscription models for recurring allergy medications and seasonal reminders are gaining traction. Digital marketing and tele-pharmacy consultations further enhance consumer engagement and education. This shift allows brands to reach younger, tech-savvy consumers while expanding penetration in semi-urban and underserved regions with limited physical retail access.
- For instance, Amazon Pharmacy operates automated fulfillment centers equipped with high-speed dispensing and packaging lines capable of processing tens of thousands of medication orders per day, supporting same-day or next-day delivery for OTC respiratory products in multiple metropolitan regions.
Key Challenges
Regulatory Constraints and Product Reclassification Risks
Regulatory oversight remains a major challenge in the OTC cough, cold, and allergy medicine market. Authorities frequently review safety profiles, dosing guidelines, and ingredient combinations, particularly for pediatric use. Changes in regulations can lead to product reformulations, label updates, or reclassification from OTC to prescription status, disrupting market continuity. Variability in OTC regulations across countries further complicates global product launches and increases compliance costs. Manufacturers must continuously invest in pharmacovigilance and regulatory monitoring to maintain product approvals and market access.
Safety Concerns and Consumer Mistrust in Certain Segments
Rising awareness of potential side effects, misuse, and drug interactions poses challenges for sustained market growth. Concerns around antibiotic resistance, misuse of decongestants, and inappropriate pediatric dosing have increased scrutiny from healthcare professionals and consumers. Negative publicity or product recalls can quickly erode brand trust. Educating consumers on responsible usage while balancing marketing efforts remains critical. Failure to address safety perceptions may limit adoption, particularly among parents and elderly consumers who rely heavily on professional guidance.
Regional Analysis
North America:
North America holds the largest share of the OTC cough, cold, and allergy medicine market, accounting for approximately 36-38% of global revenue. High prevalence of seasonal allergies, strong self-medication culture, and widespread access to retail pharmacies drive market leadership. The United States dominates the region due to high consumer spending on branded OTC products, extensive advertising, and pharmacist-supported purchasing. Product innovation in non-drowsy antihistamines, combination therapies, and pediatric formulations further supports demand. Canada contributes steady growth, supported by cold climate conditions and strong regulatory clarity around OTC drug availability.
Europe:
Europe represents around 26-28% of the global market share, supported by high allergy incidence, aging populations, and strong pharmacy-led distribution networks. Countries such as Germany, the UK, France, and Italy drive regional demand due to established OTC consumption habits and robust healthcare awareness. Seasonal influenza outbreaks and rising pollen exposure sustain recurring product use. Pharmacist counseling plays a key role in consumer decision-making, particularly for pediatric and elderly patients. Regulatory harmonization across the EU supports cross-border brand expansion, while growing demand for natural and low-sedation formulations shapes product strategies.
Asia-Pacific:
Asia-Pacific accounts for approximately 22-24% of global market share and is the fastest-growing regional market. Rapid urbanization, increasing air pollution, and high population density contribute to rising respiratory and allergy-related conditions. Markets such as China, India, Japan, and South Korea drive volume growth due to expanding middle-class populations and improving access to OTC medicines. Growing health awareness, increasing retail pharmacy penetration, and rising e-commerce adoption support demand. While traditional remedies remain relevant in parts of the region, branded OTC Western medicines are gaining strong acceptance in urban centers.
Latin America:
Latin America holds an estimated 7-9% share of the global OTC cough, cold, and allergy medicine market. Growth is supported by frequent respiratory infections, humid climatic conditions, and expanding access to retail pharmacies. Brazil and Mexico dominate regional demand due to large populations and growing urban healthcare consumption. Self-medication is common, supported by relatively flexible OTC regulations. However, price sensitivity remains high, driving demand for generic and value-oriented products. Modern trade and pharmacy chains are strengthening distribution reach, while online sales are gradually emerging in urban markets.
Middle East & Africa:
The Middle East & Africa region accounts for approximately 4-6% of global market share, reflecting lower penetration but steady growth potential. Rising urbanization, increasing dust-related allergies, and expanding healthcare access support demand. The Gulf Cooperation Council (GCC) countries lead regional consumption due to higher disposable incomes and well-developed pharmacy networks. In Africa, growth is constrained by limited OTC access and affordability challenges, though improving healthcare infrastructure supports gradual uptake. International brands dominate urban centers, while pharmacist recommendations play a critical role in guiding OTC medicine usage.
OTC Cough, Cold And Allergy Medicine Market Segmentations:
By Drug Type
- OTC Antihistamine
- OTC Expectorants
- OTC Bronchodilators
- OTC Antibiotics
By OTC Channel
- Pharmacies
- Drug Stores
- Modern Trade
- Online
By Application
- Babies
- Adults
- School-age Children
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the OTC cough, cold, and allergy medicine market is characterized by the presence of large multinational consumer healthcare companies alongside strong regional and local players. Leading companies compete through well-established brand portfolios, extensive retail penetration, and continuous product innovation across antihistamines, decongestants, expectorants, and combination formulations. Market participants emphasize brand trust, advertising intensity, and pharmacist engagement to strengthen consumer loyalty, particularly during peak seasonal demand. Portfolio expansion through line extensions, pediatric variants, and non-drowsy formulations remains a key competitive strategy. Companies also focus on packaging differentiation, flavor enhancements, and sugar-free or alcohol-free options to address evolving consumer preferences. Strategic partnerships with retail chains, growing investments in e-commerce visibility, and selective acquisitions of regional brands further intensify competition. Regulatory compliance, strong supply chain capabilities, and effective distribution across pharmacies, drug stores, and online platforms are critical determinants of sustained competitive positioning.
Key Player Analysis
- Sanofi-Aventis
- Johnson & Johnson Services, Inc.
- Reckitt Benckiser Group Plc.
- Novartis AG
- GlaxoSmithKline Plc.
- AstraZeneca Plc.
- Pfizer Inc.
- Sun Pharmaceutical Industries Ltd.
- Prestige Brands Holdings Inc.
- Procter & Gamble Co.
Recent Developments
- In August 2025, Sanofi Consumer Healthcare India Limited introduced an OTC version of Allegra-D combining fexofenadine with pseudoephedrine for comprehensive allergy relief and nasal decongestion, addressing both allergic symptoms and congestion simultaneously in a single dosage form.
- In Jul 2025 & Oct 2025, Novartis reported double-digit sales growth and strengthened pipeline execution, reaffirming FY 2025 guidance and core operating income performance. Though Novartis’s core OTC footprint is limited compared to Rx portfolios, these results underwrite sustained R&D capacity that supports adjacent consumer health collaboration and licensing pipelines.
Report Coverage
The research report offers an in-depth analysis based on Drug type, OTC channel, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will remain stable as seasonal allergies and respiratory infections continue to affect large global populations.
- Non-drowsy and multi-symptom formulations will gain wider adoption among working adults and students.
- Product innovation will focus on safer ingredients, improved dosing accuracy, and age-specific formulations.
- Online and digital pharmacy channels will expand their share through convenience and subscription-based models.
- Pharmacies will continue to play a critical advisory role in guiding appropriate OTC product selection.
- Pediatric and sugar-free variants will see gradual uptake due to rising safety awareness among consumers.
- Manufacturers will increase investments in brand extensions and packaging differentiation to strengthen visibility.
- Regulatory scrutiny will encourage clearer labeling and responsible marketing practices.
- Asia-Pacific will contribute the fastest volume growth driven by urbanization and pollution exposure.
- Strategic acquisitions and partnerships will support portfolio expansion and geographic reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for OTC cough, cold, and allergy medicine, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the OTC cough, cold, and allergy medicine market projected to grow between 2024 and 2032?
Which OTC cough, cold, and allergy medicine segment held the largest share in 2024?
What are the primary factors fueling the growth of the OTC cough, cold, and allergy medicine market?
Who are the leading companies in the OTC cough, cold, and allergy medicine market?
Which region commanded the largest share of the OTC cough, cold, and allergy medicine market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 OTC Cough Cold And Allergy Medicine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global OTC Cough Cold And Allergy Medicine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 23,450 million → 2032: USD 32,590.02 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 OTC Cough Cold And Allergy Medicine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. OTC Cough Cold And Allergy Medicine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 OTC Cough Cold And Allergy Medicine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 OTC Cough Cold And Allergy Medicine Market Drivers
- 3.3 OTC Cough Cold And Allergy Medicine Market Restraints & Challenges
- 3.4 OTC Cough Cold And Allergy Medicine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 OTC Cough Cold And Allergy Medicine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 OTC Cough Cold And Allergy Medicine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, OTC Cough Cold And Allergy Medicine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 OTC Cough Cold And Allergy Medicine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. OTC Cough Cold And Allergy Medicine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the OTC Cough Cold And Allergy Medicine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 OTC Cough Cold And Allergy Medicine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 OTC Cough Cold And Allergy Medicine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 OTC Cough Cold And Allergy Medicine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in OTC Cough Cold And Allergy Medicine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New OTC Cough Cold And Allergy Medicine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global OTC Cough Cold And Allergy Medicine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America OTC Cough Cold And Allergy Medicine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe OTC Cough Cold And Allergy Medicine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific OTC Cough Cold And Allergy Medicine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America OTC Cough Cold And Allergy Medicine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East OTC Cough Cold And Allergy Medicine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa OTC Cough Cold And Allergy Medicine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. OTC Cough Cold And Allergy Medicine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
