
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pharmaceutical Drug Delivery MarketcSize 2024 | USD 1,900,025 million |
| Pharmaceutical Drug Delivery Market, CAGR | 6.8% |
| Pharmaceutical Drug Delivery Market Size 2032 | USD 3,216,098.46 million |
Market Overview:
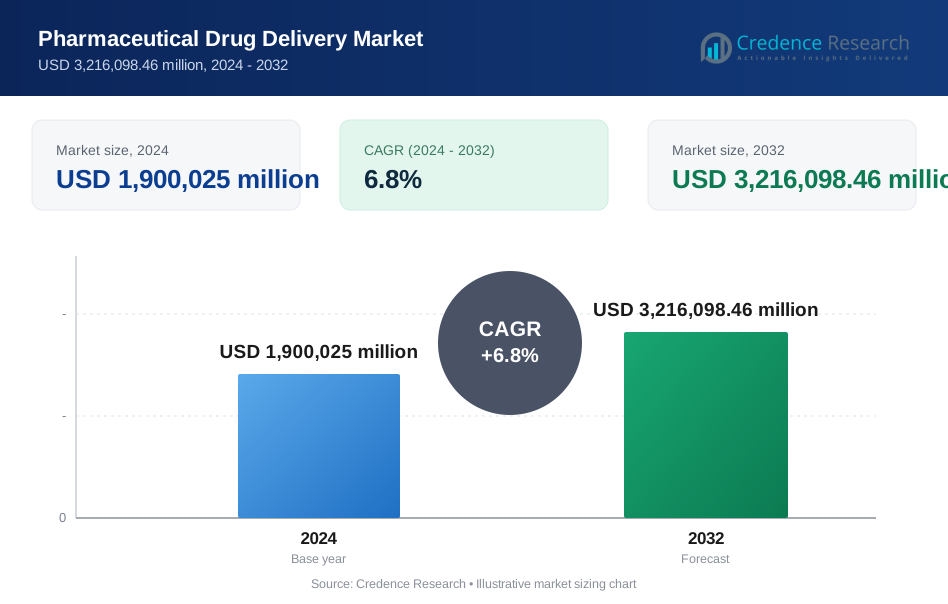
The Pharmaceutical Drug Delivery Market is projected to grow from USD 1,900,025 million in 2024 to an estimated USD 3,216,098.46 million by 2032, with a compound annual growth rate (CAGR) of 6.8% from 2024 to 2032.
Key drivers of the pharmaceutical drug delivery market include the increasing demand for personalized medicine, advancements in nanotechnology, and the growing need for targeted drug delivery systems that improve the efficacy and reduce the side effects of treatments. Additionally, the rise in chronic diseases such as cancer, diabetes, and cardiovascular disorders is fueling the demand for more effective drug delivery methods.
The development of biologics and monoclonal antibodies is further driving the market, as these therapies often require specialized delivery systems to ensure stability and bioavailability. Additionally, innovations in controlled-release formulations and the growing popularity of injectable and implantable drug delivery systems are contributing to market growth. Regionally, North America holds a dominant position in the pharmaceutical drug delivery market, driven by a strong healthcare infrastructure, significant investments in R&D, and high demand for advanced drug delivery technologies. Europe follows closely, with increasing investments in healthcare innovation and a growing focus on patient-centric solutions. In Asia Pacific, rapid industrialization, an aging population, and rising healthcare needs are expected to drive significant growth in the market. The growing adoption of advanced drug delivery systems in emerging economies such as China and India is also expected to boost market expansion in the region.
Market Insights:
- The Pharmaceutical Drug Delivery Market is expected to grow from USD 1,900,025 million in 2024 to USD 3,216,098.46 million by 2032, with a CAGR of 6.8% from 2024 to 2032.
- Rising demand for personalized medicine, targeted drug delivery systems, and advancements in nanotechnology are key market drivers.
- The increasing prevalence of chronic diseases such as cancer and diabetes is pushing the need for more effective drug delivery methods.
- High development costs and complex regulatory requirements are major restraints hindering the market growth.
- North America leads the market due to its strong healthcare infrastructure and significant investments in drug delivery technologies.
- Europe is also a major player, with ongoing advancements in healthcare and increased adoption of patient-centric solutions.
- In Asia Pacific, rapid industrialization, an aging population, and increasing healthcare needs are driving market growth, particularly in China and India.
Market Drivers:
Increasing Demand for Personalized Medicine:
The demand for personalized medicine is growing due to its potential to enhance treatment outcomes. For instance, the U.S. National Institutes of Health (NIH) allocated approximately $1.9 billion in 2021 towards precision medicine initiatives. The aim is to expand research on personalized therapies that consider genetic and environmental factors, significantly improving patient outcomes. Major companies such as Roche and Novartis are aligning their R&D strategies with this growing trend. For instance, Roche’s personalized oncology medicines, such as Tecentriq, target specific genetic profiles, highlighting the shift towards more tailored therapeutic approaches.
Advancements in Nanotechnology:
Nanotechnology is a critical innovation for improving drug delivery systems. For instance, the U.S. Department of Energy invested $80 million in 2020 to accelerate the development of nanotechnology for medical applications, including drug delivery. Additionally, Pfizer has been using nanotechnology in their COVID-19 vaccine, which leverages lipid nanoparticles for more effective drug delivery. This technology enables more precise targeting of treatments, which is critical in managing complex diseases. Furthermore, the National Cancer Institute (NCI) allocated approximately $225 million in 2020 towards the development of nanomedicine for cancer treatment, showcasing the importance of this technology in pharmaceutical advancements.
Rise in Chronic Diseases:
Chronic diseases like diabetes and cardiovascular diseases are contributing to the growing need for advanced drug delivery systems. The Centers for Disease Control and Prevention (CDC) reported that approximately 34.2 million Americans had diabetes in 2020, with numbers expected to rise as the population ages. The CDC’s National Diabetes Prevention Program, which received $29.4 million in 2020 funding, focuses on strategies to prevent and manage diabetes, which increasingly relies on innovative drug delivery methods like long-acting injectables and implantables.
Regulatory Support and Government Initiatives:
Governments are playing a vital role in fostering the growth of pharmaceutical drug delivery systems. The European Medicines Agency (EMA) approved 98 new medicines in 2020, many of which featured advanced delivery technologies. In the United States, the FDA allocated over $8 billion in 2020 for regulatory science to accelerate the approval of innovative drug delivery systems. This funding is part of a broader effort to enhance the development of cutting-edge treatments and delivery technologies. The FDA's approval of long-acting injectable medications, such as for HIV treatment, reflects regulatory support aimed at improving treatment adherence through advanced drug delivery systems.
Market Trends:
Adoption of Advanced Drug Delivery Systems:
There is a growing trend toward the adoption of advanced drug delivery systems, particularly those that enhance drug bioavailability and reduce side effects. The World Health Organization (WHO) has noted a 60% increase in the global demand for biologic drugs, which often require specialized delivery methods, such as injectables and implantables. The U.S. National Institutes of Health (NIH) has also committed over $1.2 billion in funding towards the development of advanced drug delivery systems for chronic diseases, such as cancer and cardiovascular diseases. These systems are designed to offer more precise delivery of therapeutic agents, improving patient outcomes and reducing the risk of side effects.
Integration of Smart Drug Delivery Devices:
The integration of smart drug delivery devices is an emerging trend in the pharmaceutical industry. Smart devices, which can monitor and adjust drug delivery in real-time, are gaining attention for their potential to improve patient compliance and treatment effectiveness. The U.S. Food and Drug Administration (FDA) approved 15 new smart devices in 2021, many of which are designed to monitor patients' health and optimize drug delivery in real time. The growing focus on patient-centric solutions is driving the development of these devices, as they can provide continuous data for healthcare providers, enhancing treatment management.
Rise in Injectable Drug Delivery Systems:
Injectable drug delivery systems, particularly those used for biologics and monoclonal antibodies, are becoming more prevalent. For Instance, The European Medicines Agency (EMA) has reported that injectable therapies accounted for approximately 20% of all new drug approvals in 2020. As more patients require injectable treatments for chronic conditions, such as rheumatoid arthritis and cancer, the demand for these systems is expected to rise. Governments, such as the European Union, have invested heavily in research and development programs to support the growth of injectable drug delivery technologies.
Focus on Sustainability in Drug Delivery Sustainability is becoming an important focus in the development of pharmaceutical drug delivery systems. For Instance, Government agencies like the U.S. Environmental Protection Agency (EPA) have allocated $25 million in 2021 to encourage the adoption of environmentally friendly drug delivery methods. This includes the development of biodegradable materials for injectable systems and packaging that reduces environmental impact. Pharmaceutical companies, including those in collaboration with government agencies, are investing in sustainable technologies to meet stricter environmental regulations and consumer demand for greener solutions.
Market Challenges Analysis:
Challenges in the Pharmaceutical Drug Delivery Market:
The pharmaceutical drug delivery market faces several challenges that impact its growth and development. One of the primary obstacles is the complexity and cost of developing advanced drug delivery systems. As the demand for personalized medicine and novel therapeutic formulations increases, pharmaceutical companies are under pressure to design systems that can precisely target specific sites within the body while minimizing side effects. For instance, the development of biologics and targeted therapies requires sophisticated technologies such as nanoparticles, liposomes, and micro-needles, all of which involve high production costs and regulatory hurdles. These factors can slow the pace of innovation and increase the financial burden on companies.
Regulatory and Compliance Challenges:
The regulatory landscape is another significant challenge in the drug delivery market. Regulatory authorities such as the FDA, EMA, and other national bodies impose strict guidelines on the approval of new drug delivery systems. Meeting these regulatory requirements can be time-consuming and expensive, especially for companies developing complex or novel delivery technologies. The approval of gene therapies or combination products, which involve both drugs and devices, often requires extensive clinical trials and lengthy approval processes. The dynamic nature of regulations across different regions also poses difficulties for companies looking to enter multiple markets, as they must navigate a variety of regulatory frameworks and ensure compliance with local standards.
Market Opportunities:
The pharmaceutical drug delivery market presents significant opportunities driven by the continuous advancements in drug delivery technologies and the growing emphasis on personalized medicine. One of the most promising opportunities lies in the development of targeted drug delivery systems that improve treatment outcomes while minimizing side effects. Innovations such as nanoparticle-based drug carriers, biologics, and controlled-release formulations are expected to transform the market, offering precision treatments that cater to individual patient needs. The expansion of biologic drugs, which often require specialized delivery systems to ensure bioavailability and stability, presents an additional opportunity for market players to innovate and create new drug delivery solutions. As patients increasingly demand more effective and efficient treatments, the adoption of these advanced drug delivery technologies is likely to rise, driving substantial growth in the market.
Additionally, the rise in chronic diseases, particularly cancer, cardiovascular disorders, and diabetes, opens new avenues for growth in the pharmaceutical drug delivery market. With the global aging population and an increase in lifestyle-related diseases, there is a growing need for drug delivery systems that can address these complex health challenges. The increasing focus on home-based healthcare and self-administered injectable systems also presents opportunities for market expansion, as patients seek more convenient treatment options. Furthermore, emerging markets, particularly in Asia Pacific and Latin America, offer significant growth potential as healthcare infrastructure improves and access to advanced treatments expands. Companies that can develop cost-effective and regionally tailored drug delivery solutions are poised to capture a larger share of these expanding markets.
Market Segmentation Analysis:
By Route of Administration, the market includes oral, injectable, topical, nasal, and ocular drug delivery methods. Injectable drug delivery dominates this segment due to its effectiveness in delivering medications for chronic and life-threatening conditions such as cancer and autoimmune diseases. Oral drug delivery remains popular for its convenience and patient compliance, while topical and nasal methods cater to specific therapeutic needs.
By Application, the market spans various disease areas, including cancer, diabetes, cardiovascular diseases, and infectious diseases. Cancer applications hold the largest market share, driven by the demand for targeted therapies such as chemotherapy and immunotherapy. Diabetes and cardiovascular applications are also significant, reflecting the growing global burden of these conditions.
By Facility of Use, the market is divided into hospitals, home care settings, and specialty clinics. Hospitals lead this segment due to their advanced infrastructure and ability to handle complex drug delivery systems. Home care settings are gaining traction, supported by the increasing availability of user-friendly drug delivery devices that enable self-administration.
Segmentations:
By Route of Administration:
- Oral Drug Delivery
- Injectable Drug Delivery
- Topical Drug Delivery
- Ocular Drug Delivery
- Pulmonary Drug Delivery
- Nasal Drug Delivery
- Transmucosal Drug Delivery
- Implantable Drug Delivery
By Application:
- Infectious Diseases
- Cancer
- Cardiovascular Diseases
- Diabetes
- Respiratory Diseases
- Central Nervous System Disorders
- Autoimmune Diseases
- Others
By Facility of Use:
- Hospitals
- Ambulatory Surgery Centers/Clinics
- Home Care Settings
- Diagnostic Centers
- Others
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is the dominant region in the pharmaceutical drug delivery market, accounting for approximately 40% of the global market share. The region’s leadership is driven by the presence of major pharmaceutical companies, advanced healthcare infrastructure, and high healthcare spending. The United States, in particular, plays a significant role, with continuous investments in research and development of advanced drug delivery systems. Additionally, the rising prevalence of chronic diseases such as diabetes and cardiovascular conditions is driving the market for injectable and oral drug delivery systems. The region's stringent regulatory environment and emphasis on drug safety and efficacy also contribute to its market share.
Europe
Europe holds a substantial share of around 30% of the global pharmaceutical drug delivery market. The region is experiencing steady growth due to its established healthcare systems, increasing demand for personalized medicine, and strong presence of pharmaceutical manufacturers. Countries like Germany, the United Kingdom, and France are at the forefront of adopting innovative drug delivery technologies such as microneedle systems and controlled-release formulations. Regulatory approvals in Europe are also more streamlined for certain drug delivery technologies, supporting market growth.
Asia Pacific
The Asia Pacific region is the fastest-growing market for pharmaceutical drug delivery systems, projected to expand at a compound annual growth rate (CAGR) of 8-10%. This region accounts for approximately 20% of the global market share. Key markets in Asia Pacific include China, Japan, India, and South Korea, where rapid industrialization, improving healthcare infrastructure, and a rising focus on biotechnology are driving the market. India’s growing pharmaceutical industry and China’s increasing investment in advanced drug delivery technologies are expected to contribute significantly to the regional growth. Additionally, the rising incidence of chronic diseases and an increasing preference for self-administered drug delivery devices, such as insulin pumps and inhalers, are fueling demand. Government initiatives to improve healthcare access and reduce drug delivery costs in countries like India and China further enhance the market potential.
Key Player Analysis:
- Johnson & Johnson
- Becton, Dickinson and Company (BD)
- Pfizer Inc.
- Roche Holding AG
- Novartis AG
- Merck & Co., Inc.
- Medtronic PLC
- Sanofi S.A.
- Bayer Medicine Products AG
- Sandoz International GmbH (A Novartis Division)
- GlaxoSmithKline (GSK)
- AbbVie Inc.
Competitive Analysis:
The pharmaceutical drug delivery market is highly competitive, with key players constantly innovating to develop advanced delivery systems that cater to the growing demand for personalized and effective treatments. Major companies like Johnson & Johnson, Pfizer, and Roche are focusing on the development of targeted drug delivery technologies, such as nanoparticles and biologics, to address complex medical conditions. Johnson & Johnson’s recent advancements in its needle-free injection technology highlight the shift towards non-invasive drug delivery solutions. Additionally, companies like Medtronic and Becton, Dickinson and Company are investing in smart devices and wearables to offer real-time drug delivery and monitoring. As regulatory pressures rise, companies are also prioritizing compliance with stringent standards to ensure the safety and efficacy of their products. This intense competition, combined with rapid technological advancements, is pushing the market towards continuous innovation, creating both opportunities and challenges for pharmaceutical manufacturers.
Recent Developments:
- In March 2024, Johnson & Johnson completed the acquisition of Ambrx Biopharma, reinforcing its commitment to innovation in prostate cancer therapies and enhancing its pipeline of next-generation antibody-drug conjugates and targeted oncologic therapeutics.
- In September 2024, BD expanded its capacity for advanced prefillable syringes and enhanced the injection experience for the next generation of biologics with the commercial release of the BD Neopak™ XtraFlow™ Glass Prefillable Syringe.
- In October 2024, BD showcased its latest drug delivery innovations at CPhI Milan 2024, emphasizing its commitment to advancing healthcare through cutting-edge drug delivery solutions.
- In July 2024, Roche raised its full-year earnings outlook based on strong sales growth in the first half of 2024, reflecting high demand for its innovative medicines and diagnostics.
Market Concentration & Characteristics:
The pharmaceutical drug delivery market exhibits moderate to high concentration, with a few major players dominating the landscape while numerous smaller companies contribute through niche innovations. Leading players such as Johnson & Johnson, Pfizer, and Roche hold significant market share due to their extensive product portfolios and investment in advanced drug delivery technologies. These companies are often involved in strategic mergers, acquisitions, and partnerships to enhance their market position. However, the market is also characterized by the presence of specialized firms focused on innovative drug delivery solutions, such as nanotechnology, microneedles, and controlled-release systems, which cater to specific therapeutic areas. This dynamic environment fosters healthy competition and drives continuous innovation, particularly in the development of personalized and targeted drug delivery systems. As the market evolves, a mix of both large pharmaceutical firms and agile biotech companies will continue to shape the future growth and direction of the industry.
Report Coverage:
The research report offers an in-depth analysis Based on By Route of Administration, By Application, and By Facility of Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for personalized medicine is expected to increase, prompting the development of drug delivery systems tailored to individual patient needs.
- Continued innovation in nanotechnology will enable more precise and efficient drug delivery, enhancing drug bioavailability and minimizing side effects.
- The rise in chronic diseases such as diabetes, cancer, and cardiovascular conditions will drive the need for long-acting and targeted drug delivery systems.
- There will be increased adoption of non-invasive drug delivery methods, such as needle-free injectors and transdermal patches, to improve patient comfort and compliance.
- The expansion of biologic and biosimilar drug production will foster the growth of advanced delivery systems, particularly injectable and sustained-release formulations.
- The development of smart drug delivery systems, which incorporate sensors and real-time monitoring, will enable more personalized treatment regimens and improve patient outcomes.
- Regulatory frameworks will continue to evolve, promoting the approval of novel drug delivery technologies while ensuring patient safety and efficacy.
- The growing focus on global healthcare accessibility will drive efforts to reduce production costs, making advanced drug delivery solutions more affordable in emerging markets.
- Digital health technologies and wearable devices will increasingly integrate with drug delivery systems, enhancing patient monitoring and medication adherence.
- Strategic collaborations between pharmaceutical companies, biotech firms, and tech innovators will accelerate the pace of innovation and bring novel drug delivery solutions to market faster.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the pharmaceutical drug delivery market?
What are the key drivers of the pharmaceutical drug delivery market?
Which regions are leading the pharmaceutical drug delivery market?
What opportunities exist in emerging markets for drug delivery technologies?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pharmaceutical Drug Delivery Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pharmaceutical Drug Delivery Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,900,025 million → 2032: USD 3,216,098.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pharmaceutical Drug Delivery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pharmaceutical Drug Delivery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pharmaceutical Drug Delivery Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pharmaceutical Drug Delivery Market Drivers
- 3.3 Pharmaceutical Drug Delivery Market Restraints & Challenges
- 3.4 Pharmaceutical Drug Delivery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pharmaceutical Drug Delivery Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pharmaceutical Drug Delivery Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pharmaceutical Drug Delivery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pharmaceutical Drug Delivery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pharmaceutical Drug Delivery Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pharmaceutical Drug Delivery market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pharmaceutical Drug Delivery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pharmaceutical Drug Delivery Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pharmaceutical Drug Delivery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pharmaceutical Drug Delivery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pharmaceutical Drug Delivery Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pharmaceutical Drug Delivery Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pharmaceutical Drug Delivery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pharmaceutical Drug Delivery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pharmaceutical Drug Delivery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pharmaceutical Drug Delivery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pharmaceutical Drug Delivery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pharmaceutical Drug Delivery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pharmaceutical Drug Delivery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
