
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Philippines Grid Modernization Market Size 2023 | USD 81.43 million |
| Philippines Grid Modernization Market, CAGR | 17.02% |
| Philippines Grid Modernization Market Size 2032 | USD 286.42 million |
Market Overview
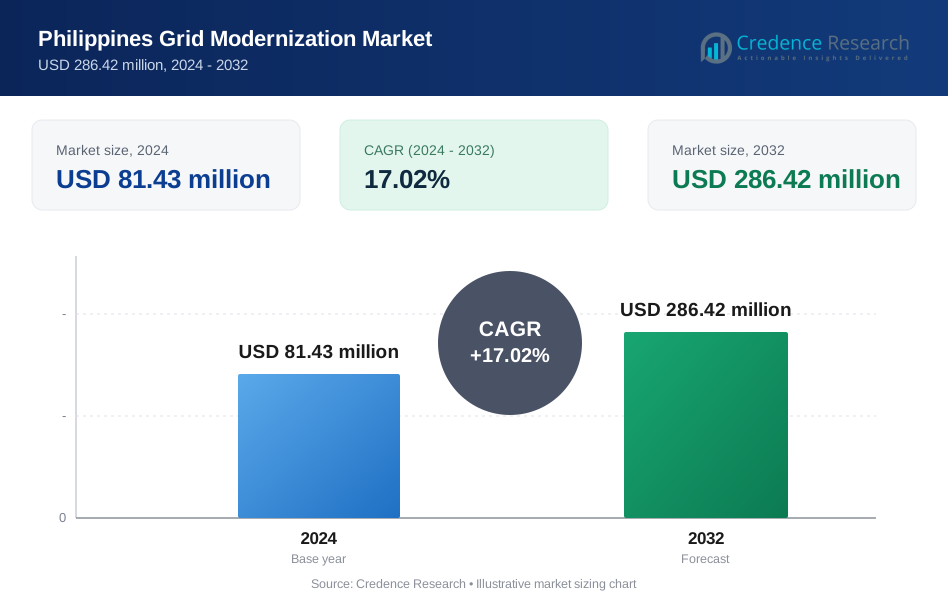
Philippines Grid Modernization market size was valued at USD 81.43 million in 2024 and is anticipated to reach USD 286.42 million by 2032, at a CAGR of 17.02% during the forecast period (2024-2032).
The Philippines Grid Modernization Market is driven by increasing electricity demand, the integration of renewable energy sources, and government-led initiatives to enhance grid efficiency. Rising investments in smart grid infrastructure, including automated distribution networks and smart meters, are improving energy management and reliability. The growing adoption of advanced technologies, such as artificial intelligence (AI) and Internet of Things (IoT)-enabled grid monitoring systems, is further optimizing operations. Additionally, the shift toward decentralized energy generation and battery storage solutions is enhancing grid stability. Trends indicate a surge in public-private partnerships aimed at accelerating modernization efforts, while regulatory support for clean energy transitions is fostering market expansion. The demand for resilient, real-time grid solutions is rising as extreme weather events challenge power infrastructure. With utilities prioritizing grid automation and digital transformation, the market is set for robust growth, ensuring a more secure, efficient, and sustainable power supply across the Philippines.
The Philippines Grid Modernization Market is characterized by significant investments across key regions, with a focus on urban centers like Metro Manila, Cebu, Davao, and Northern Luzon, where grid efficiency and renewable energy integration are top priorities. Key players such as ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, and General Electric Philippines are at the forefront of providing advanced grid solutions, including smart grid infrastructure, automation systems, and energy storage technologies. These companies collaborate with local utilities and government bodies to enhance grid reliability, reduce energy losses, and integrate renewable energy sources. Additionally, players like Alstom SA, Toshiba Philippines, and Eaton Philippines contribute to the market by supplying power management solutions and microgrid technologies. As the country moves towards more sustainable and resilient energy systems, these key players will continue to shape the future of grid modernization through technological innovations and strategic partnerships.
Market Insights
- The Philippines Grid Modernization Market was valued at USD 81.43 million in 2024 and is projected to reach USD 286.42 million by 2032, growing at a CAGR of 17.02% during the forecast period.
- Increasing demand for smart grid technologies and renewable energy integration is driving market growth.
- The shift toward AI-driven energy management systems and grid automation is a key market trend.
- Key players like ABB, Siemens, and Schneider Electric dominate the market with their advanced grid solutions.
- Cybersecurity concerns and high initial investments act as significant market restraints.
- Metro Manila and Cebu are leading regions for grid modernization, driven by urban expansion and renewable energy projects.
- Government support, along with the rise in private-public partnerships, is accelerating the market's development in various regions, especially in Davao and Northern Luzon.
Market Drivers
Government Initiatives and Policy Support
The Philippines government is actively driving grid modernization through strategic policies, regulatory reforms, and substantial investments. For instance, the National Grid Corporation of the Philippines (NGCP) has outlined plans to invest over three times its past investments (over PhP 900 billion) in the Philippines grid by 2034. Programs such as the National Smart Grid Roadmap and the Renewable Energy Act promote infrastructure upgrades, smart grid implementation, and enhanced energy efficiency. Financial incentives, including subsidies and tax benefits for power utilities adopting modern technologies, further accelerate market expansion. Additionally, collaborations between the public and private sectors are facilitating large-scale grid enhancements, ensuring a stable and reliable electricity supply across the country. These measures are crucial in addressing power distribution challenges and reducing the frequency of outages, thus supporting the country’s growing energy demand.
Rising Demand for Renewable Energy Integration
The rapid adoption of renewable energy sources, including solar, wind, and hydropower, is a major driver of grid modernization in the Philippines. For instance, the NGCP has outlined an extensive plan to expand and modernize the transmission infrastructure across the Luzon, Visayas, and Mindanao grids, including island interconnection projects, to meet the country’s increasing electricity demand and facilitate RES integration. With the government aiming to increase renewable energy’s share in the energy mix, the need for an advanced grid capable of managing variable power generation is becoming critical. Smart grid technologies, such as real-time monitoring systems and demand-response mechanisms, are enabling efficient integration of renewables while minimizing power fluctuations. Additionally, energy storage solutions are being increasingly adopted to enhance grid stability and support continuous power supply, even during peak demand periods.
Advancements in Smart Grid Technologies
The deployment of smart meters, automated distribution systems, and IoT-based grid monitoring solutions is transforming the country’s power infrastructure. These technologies enable real-time data collection, predictive maintenance, and efficient load management, reducing operational costs and improving service reliability. The integration of artificial intelligence (AI) and blockchain technology in grid operations is also enhancing cybersecurity, preventing data breaches, and ensuring transparent energy transactions. As utilities continue investing in digital transformation, the adoption of intelligent grid solutions is set to increase, driving long-term efficiency and sustainability in the power sector.
Increasing Electricity Demand and Grid Reliability Challenges
The Philippines' rising population and expanding industrial sector are driving higher electricity consumption, necessitating upgrades in transmission and distribution infrastructure. Frequent power disruptions caused by extreme weather events, outdated grid systems, and distribution inefficiencies highlight the urgent need for modernization. Investments in resilient power networks, underground cabling, and automation are addressing these issues, ensuring uninterrupted power supply. Moreover, initiatives to improve energy efficiency through smart grid deployment and demand-side management programs are further strengthening grid reliability, reducing energy losses, and enhancing overall system performance.
Market Trends
Growing Adoption of Smart Grid Infrastructure
The Philippines is witnessing a rapid shift toward smart grid deployment as utilities invest in advanced technologies to improve energy distribution and management. For instance, the Manila Electric Company (Meralco) has embarked on its advanced smart grid roadmap, integrating "smart intelligence" into the electric distribution network to help consumers better manage their electricity consumption. The adoption of smart meters, automated substations, and real-time monitoring systems is enhancing grid efficiency and reducing energy losses. These technologies enable better demand forecasting, load balancing, and quick identification of faults, minimizing outages and improving service reliability. Additionally, investments in grid automation and digital transformation are helping power utilities streamline operations, optimize resource allocation, and reduce operational costs.
Increasing Investments in Energy Storage Solutions
With the growing share of renewable energy sources, energy storage systems are becoming an essential component of grid modernization. The deployment of battery energy storage systems (BESS) is improving grid stability by managing intermittent power supply from solar and wind sources. These storage solutions help store excess electricity during periods of low demand and release it during peak hours, ensuring a continuous and reliable power supply. Government initiatives supporting energy storage adoption, along with declining battery costs, are driving investment in large-scale storage projects across the country.
Integration of Artificial Intelligence and IoT
Artificial Intelligence (AI) and the Internet of Things (IoT) are revolutionizing grid management in the Philippines. AI-driven analytics enable predictive maintenance, fault detection, and demand forecasting, allowing utilities to proactively address issues before they escalate. IoT-enabled sensors and automated systems provide real-time grid monitoring, ensuring efficient energy distribution and reducing downtime. These innovations not only improve operational efficiency but also enhance cybersecurity, protecting the grid from potential threats. As digital transformation gains momentum, AI and IoT will play a crucial role in optimizing grid performance and resilience.
Rising Focus on Decentralized Energy Systems
Decentralized energy generation, including microgrids and distributed renewable energy systems, is emerging as a key trend in the Philippines’ grid modernization efforts. For instance, the Department of Energy (DOE) has awarded contracts to develop microgrid systems in eight unserved areas of the country through its Microgrid Systems Service Provider – Special Bids and Awards Committee (MGSP-SBAC). These systems enhance energy access in remote and off-grid areas, reducing dependency on centralized power plants. Microgrids equipped with solar panels, wind turbines, and battery storage provide localized energy solutions, improving energy security and reliability. As the country moves toward sustainable energy development, decentralized power generation will play a significant role in building a resilient and self-sufficient electricity network.
Market Challenges Analysis
High Initial Investment and Infrastructure Limitations
The modernization of the Philippines’ power grid requires substantial capital investment, which poses a significant challenge for utilities and stakeholders. Upgrading outdated transmission and distribution networks, deploying smart grid technologies, and integrating renewable energy solutions demand high upfront costs. Many power companies, especially smaller players, struggle with securing adequate funding for large-scale grid modernization projects. Additionally, the country’s existing infrastructure is not fully equipped to support advanced technologies, leading to delays in implementation. Limited availability of skilled professionals to operate and maintain modernized grid systems further adds to the challenge, slowing down the transition to a more efficient and resilient electricity network.
Cybersecurity Risks and Regulatory Barriers
As the power sector becomes increasingly digitized, the risk of cyberattacks on the grid is a growing concern. For instance, the NGCP has come under attack "a hundred times already" in the preceding two weeks alone, highlighting the vulnerability of the grid to cyber threats. The integration of IoT, AI, and cloud-based energy management systems exposes power networks to potential hacking attempts, data breaches, and operational disruptions. Utilities must invest in robust cybersecurity measures to protect grid infrastructure and ensure uninterrupted power supply. Additionally, regulatory and policy barriers can hinder market growth. While the government supports grid modernization, complex approval processes, inconsistent policies, and bureaucratic delays can slow down project execution. Coordinating efforts between public and private stakeholders is crucial to overcoming these challenges and fostering a secure, efficient, and technologically advanced power grid in the Philippines.
Market Opportunities
The Philippines Grid Modernization Market presents significant opportunities driven by the rising demand for smart grid infrastructure and renewable energy integration. As the government prioritizes the transition to a more efficient and sustainable power system, there is a growing need for investments in advanced grid technologies, automation, and energy storage solutions. The increasing adoption of smart meters, AI-driven analytics, and IoT-enabled grid management systems creates avenues for technology providers and energy companies to expand their presence. Additionally, the push toward decentralized energy systems, including microgrids and distributed generation, offers opportunities for companies specializing in solar, wind, and battery storage solutions. These advancements enhance energy access in remote areas, reduce dependency on fossil fuels, and improve grid resilience, making modernization efforts highly attractive for investors and stakeholders.
Moreover, public-private partnerships (PPPs) and foreign investments are expected to accelerate the country’s grid modernization efforts. International energy companies and financial institutions are increasingly collaborating with local utilities to fund and implement smart grid projects. The declining cost of energy storage systems and digital grid technologies makes modernization initiatives more economically viable, encouraging further adoption. Additionally, the rising focus on cybersecurity and grid resilience opens up opportunities for companies specializing in grid security solutions, AI-powered threat detection, and blockchain-based energy transactions. As regulatory frameworks continue to evolve, businesses offering compliance-driven smart grid solutions will play a crucial role in shaping the future of the Philippines’ energy landscape, ensuring a more sustainable, efficient, and secure power supply.
Market Segmentation Analysis:
By Component:
The Philippines Grid Modernization Market is segmented into hardware, software, and services, each playing a crucial role in improving grid efficiency and reliability. The hardware segment dominates the market, driven by the increasing deployment of smart meters, automated substations, and grid communication devices. These components enable real-time data collection and efficient energy distribution, enhancing overall grid performance. The software segment is also witnessing significant growth, as utilities invest in AI-driven analytics, predictive maintenance solutions, and IoT-enabled grid management platforms. These technologies improve demand forecasting, fault detection, and energy optimization, reducing operational costs and improving grid security. Additionally, the services segment, which includes consulting, system integration, and maintenance, is gaining traction due to the rising demand for expertise in deploying and managing modern grid infrastructure. As utilities and power companies focus on digital transformation and automation, investment in software and service solutions is expected to increase, further driving the market’s expansion.
By Application:
Grid modernization in the Philippines is transforming the residential, commercial, and industrial sectors by improving energy efficiency and power reliability. The residential segment is growing due to the increasing adoption of smart meters and home energy management systems (HEMS), enabling households to monitor and optimize electricity usage. Rising consumer awareness about energy conservation and government initiatives promoting smart grid adoption further support this segment. The commercial sector is also experiencing rapid growth, with businesses investing in automated energy management systems and demand-response programs to reduce energy costs and improve operational efficiency. Additionally, the industrial segment is a key driver of grid modernization, as manufacturing facilities and large-scale industries require uninterrupted power supply and advanced grid solutions to optimize production. The increasing adoption of microgrids, energy storage systems, and AI-based grid monitoring solutions in industrial settings is enhancing grid resilience and sustainability. With growing electricity demand across all sectors, investments in modern grid infrastructure are expected to rise, driving further advancements in the market.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Application:
- Residential
- Commercial
- Industrial
Based on End-User:
- Utilities
- Independent Power Producers (IPPs)
- Government and Municipalities
Based on the Geography:
- Metro Manila
- Cebu
- Davao
- Northern Luzon
Regional Analysis
Metro Manila
Metro Manila, the Philippines' capital region, holds the largest market share in the Philippines Grid Modernization Market, accounting for approximately 40% of the total market share. The region’s dominance is attributed to its dense population, rapid urbanization, and high electricity demand. Metro Manila is also home to the country's largest commercial and industrial hubs, making it a focal point for energy consumption. In response to these demands, utilities in the region are investing heavily in grid modernization technologies such as smart meters, automated distribution systems, and energy storage solutions. Additionally, government policies promoting renewable energy integration and smart grid infrastructure are further accelerating market growth in Metro Manila. As the capital of the country, Metro Manila is also at the forefront of technological advancements, making it an ideal location for testing and implementing cutting-edge grid solutions.
Cebu
Cebu, one of the key economic regions in the Philippines, holds a market share of approximately 25% in the grid modernization efforts. Cebu’s rapidly growing population, combined with the expansion of its industrial and tourism sectors, is driving significant demand for reliable and efficient energy systems. As a result, there is an increasing need for grid infrastructure upgrades, including the deployment of smart grid technologies, energy storage systems, and renewable energy integration. Cebu’s strategic position as a key business hub for industries such as manufacturing, retail, and services makes it an attractive market for energy companies and technology providers. With increasing urbanization and government support for green energy transitions, Cebu is poised to experience continued growth in grid modernization investments in the coming years.
Davao
Davao, located in the southern part of the Philippines, accounts for 15% of the market share in grid modernization. This region is experiencing rapid urbanization, particularly in its industrial and agricultural sectors, which has led to a steady rise in energy demand. Davao is investing in modern grid solutions to address power supply challenges, improve grid reliability, and facilitate the integration of renewable energy sources. The local government has been supportive of initiatives to modernize the grid, enhancing the region's energy infrastructure to meet the growing demands of both residential and commercial consumers. With the growing emphasis on renewable energy integration, microgrids, and battery storage systems, Davao is becoming a key player in the Philippines’ grid modernization market.
Northern Luzon
Northern Luzon, comprising provinces such as Pangasinan, Tarlac, and La Union, holds a market share of approximately 20% in the grid modernization space. This region is undergoing significant development, particularly in its agricultural, commercial, and manufacturing sectors. Although it does not have the same level of demand as Metro Manila or Cebu, Northern Luzon’s rapidly expanding population and industries are creating new opportunities for grid improvements. With government initiatives promoting energy efficiency, renewable energy integration, and smart grid solutions, the region is gradually transitioning toward a more modernized energy infrastructure. The adoption of solar energy and battery storage technologies in Northern Luzon is expected to increase, driving future growth in the region’s grid modernization efforts.
Key Player Analysis
- ABB Ltd.
- Siemens AG
- Schneider Electric SE
- Hitachi Energy
- General Electric Philippines
- Alstom SA
- Toshiba Philippines
- Landis+Gyr AG
- Siemens Gamesa
- Eaton Philippines
Competitive Analysis
The Philippines Grid Modernization Market is highly competitive, with major players like ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric Philippines, Alstom SA, Toshiba Philippines, Landis+Gyr AG, Siemens Gamesa, and Eaton Philippines leading the way. These companies offer a wide range of solutions, including smart grid infrastructure, energy storage systems, grid automation, and renewable energy integration technologies. For instance, the Manila Electric Company (Meralco) has embarked on its advanced smart grid roadmap, integrating "smart intelligence" into the electric distribution network to help consumers better manage their electricity consumption. Companies in the market focus on offering solutions that enhance grid efficiency, resilience, and reliability. The leading players are continuously innovating, developing AI-driven energy management systems, grid automation, and advanced distribution networks to meet the growing demand for more sustainable and efficient electricity networks. Competition is fueled by the increasing adoption of IoT-enabled grid management systems and predictive maintenance technologies aimed at reducing energy loss and improving grid performance. Companies are also competing to provide power management solutions that can optimize energy usage and enhance grid security. Another critical factor is the integration of renewable energy sources like solar and wind power, with many companies investing in solutions to handle the variable nature of renewable energy generation. Regional adaptation plays a crucial role in the competitive landscape, with companies tailoring their solutions to meet the specific needs of different areas, especially in urban regions like Metro Manila and Cebu. The growing emphasis on cybersecurity for digital grid solutions and private-public partnerships will continue to shape the competitive dynamics in the market, pushing companies to stay ahead with cutting-edge technology and tailored services.
Recent Developments
- In October 2024, Hitachi Energy introduced Grid-enSure in India to advance the country's transition to sustainable energy. The company also announced plans to invest around INR 2,000 crore over the next four to five years in capacity expansion and upgrades for various transformer factories.
- In August 2024, Hitachi Energy called for urgent action to expand global power grids, reduce connection bottlenecks, and accelerate the energy transition. They launched Grid-enSure™ at the CIGRE 2024 Paris Session, a portfolio of solutions to enhance grid flexibility, resilience, and stability.
- In May 2024, Siemens revealed the Gridscale X software, a "co-pilot" for flexible low voltage grid management, aiming to reduce outages by up to 30%.
Market Concentration & Characteristics
The Philippines Grid Modernization Market is moderately concentrated, with several key players dominating the landscape, but also offering opportunities for emerging companies to capitalize on the growing demand for advanced grid solutions. The market is characterized by high technological innovation, with a focus on smart grid infrastructure, energy storage systems, and AI-driven energy management platforms. Established global players have a significant presence, leveraging their vast experience, resources, and extensive product portfolios to maintain competitive advantages. These companies often form strategic alliances with local utilities and government bodies to accelerate grid modernization efforts.
However, the market also exhibits a trend of increasing regional adaptation, with companies developing solutions tailored to local needs, such as microgrids and distributed energy generation systems. This has led to a diverse market where both large multinational corporations and local firms can succeed, depending on their ability to meet specific regional requirements. The demand for cybersecurity in grid management and the integration of renewable energy have further shaped the market’s dynamics. Additionally, private-public partnerships (PPPs) and government incentives play a pivotal role in driving market growth, encouraging both established and emerging players to invest in innovative solutions. As grid modernization continues to evolve, the market will likely see an increase in competition and collaboration between global and local entities.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Philippines Grid Modernization Market is expected to experience sustained growth due to increasing demand for efficient energy distribution and renewable energy integration.
- Adoption of smart grid technologies will rise, improving grid reliability, efficiency, and reducing energy losses.
- Advanced AI-driven energy management systems will become integral to managing real-time data and optimizing electricity usage.
- The focus on renewable energy sources like solar and wind will drive investments in grid infrastructure capable of handling variable power generation.
- Battery energy storage systems (BESS) will play a crucial role in stabilizing the grid and supporting intermittent renewable energy generation.
- Government initiatives promoting sustainability and smart grid adoption will continue to incentivize investments in modernized grid infrastructure.
- The market will witness increased adoption of microgrids to ensure a more reliable energy supply in remote and off-grid areas.
- The integration of cybersecurity solutions into grid management will be essential to safeguard against potential digital threats and vulnerabilities.
- Public-private partnerships (PPPs) will play a significant role in accelerating the modernization of the energy grid across various regions.
- As the market matures, competition will intensify, pushing companies to innovate and offer more customized, region-specific grid solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Philippines Grid Modernization Market?
What factors are driving the growth of the Philippines Grid Modernization Market?
What are the key segments within the Philippines Grid Modernization Market?
Who are the major players in the Philippines Grid Modernization Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Philippines Grid Modernization Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Philippines Grid Modernization Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 81.43 million → 2032: USD 286.42 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Philippines Grid Modernization Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Philippines Grid Modernization Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Philippines Grid Modernization Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Philippines Grid Modernization Drivers
- 3.3 Philippines Grid Modernization Restraints & Challenges
- 3.4 Philippines Grid Modernization Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Philippines Grid Modernization Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Philippines Grid Modernization Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Philippines Grid Modernization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Philippines Grid Modernization Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Philippines Grid Modernization Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Philippines Grid Modernization in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Philippines Grid Modernization Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Philippines Grid Modernization Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Philippines Grid Modernization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Philippines Grid Modernization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Philippines Grid Modernization
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Philippines Grid Modernization – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Philippines Grid Modernization – Priority Domestic Market 1
Chapter 10. Philippines Grid Modernization – Priority Domestic Market 2
Chapter 11. Philippines Grid Modernization – Priority Domestic Market 3
Chapter 12. Philippines Grid Modernization – Priority Domestic Market 4
Chapter 13. Philippines Grid Modernization Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
