
Market Overview:
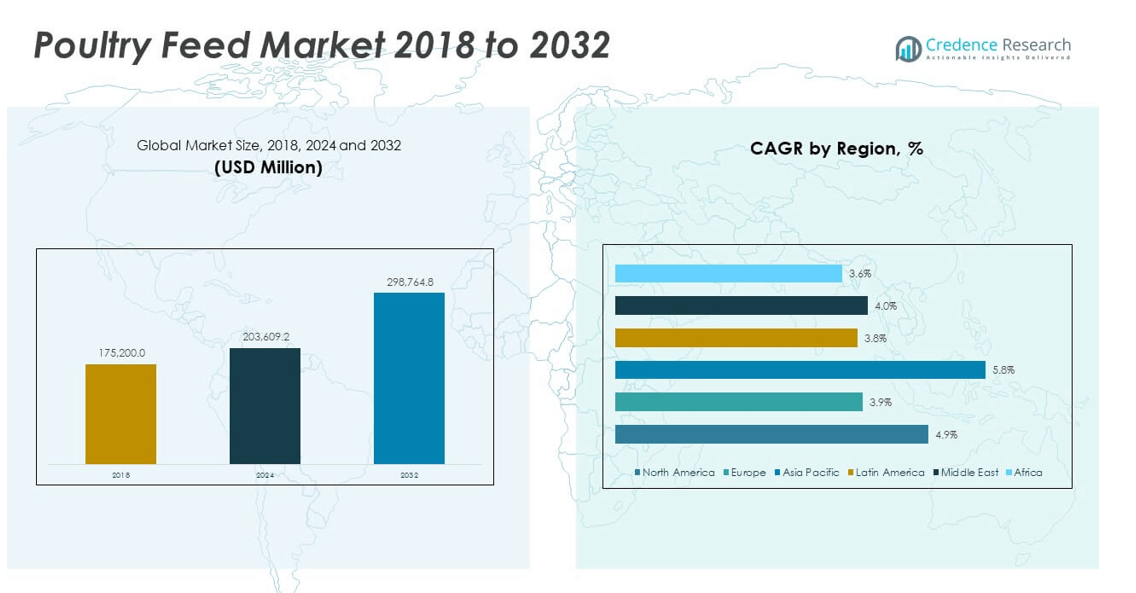
The Poultry Feed Market size was valued at USD 1,75,200.0 million in 2018 to USD 2,03,609.2 million in 2024 and is anticipated to reach USD 2,98,764.8 million by 2032, at a CAGR of 4.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Poultry Feed Market Size 2024 | USD 2,03,609.2 million |
| Poultry Feed Market, CAGR | 4.9% |
| Poultry Feed Market Size 2032 | USD 2,98,764.8 million |
The market is expanding due to the rising global demand for poultry products, driven by increasing meat consumption and a growing preference for protein-rich diets. Producers are focusing on nutritional enhancements in poultry feed formulations, integrating additives such as enzymes, vitamins, and probiotics to improve bird health and productivity. Sustainability goals are also influencing feed innovations, with a shift toward natural and organic ingredient to meet consumer and regulatory expectations. Advances in feed technology and precision nutrition are further shaping the industry’s growth trajectory.
Regionally, Asia-Pacific leads the poultry feed market, supported by its large population base, rising disposable incomes, and strong poultry production in countries like China and India. North America and Europe remain significant markets, driven by established poultry industries and stringent quality regulations. Emerging markets in Latin America and Africa are witnessing rapid growth, fueled by expanding poultry farming activities and rising food security needs. These dynamics highlight both mature markets maintaining dominance and new regions gaining momentum due to shifting dietary patterns and increasing poultry consumption.
Market Insights:
- The Poultry Feed Market was valued at USD 1,75,200.0 million in 2018, reached USD 2,03,609.2 million in 2024, and is projected to reach USD 2,98,764.8 million by 2032, growing at a CAGR of 4.9%.
- Asia Pacific (35.9%), North America (32.1%), and Europe (18.0%) held the largest shares in 2024, driven by large-scale poultry production, advanced feed technologies, and strong regulatory frameworks.
- Asia Pacific, with a 9% share, is the fastest-growing region, supported by rising poultry consumption, expanding retail networks, and modernization of poultry farming.
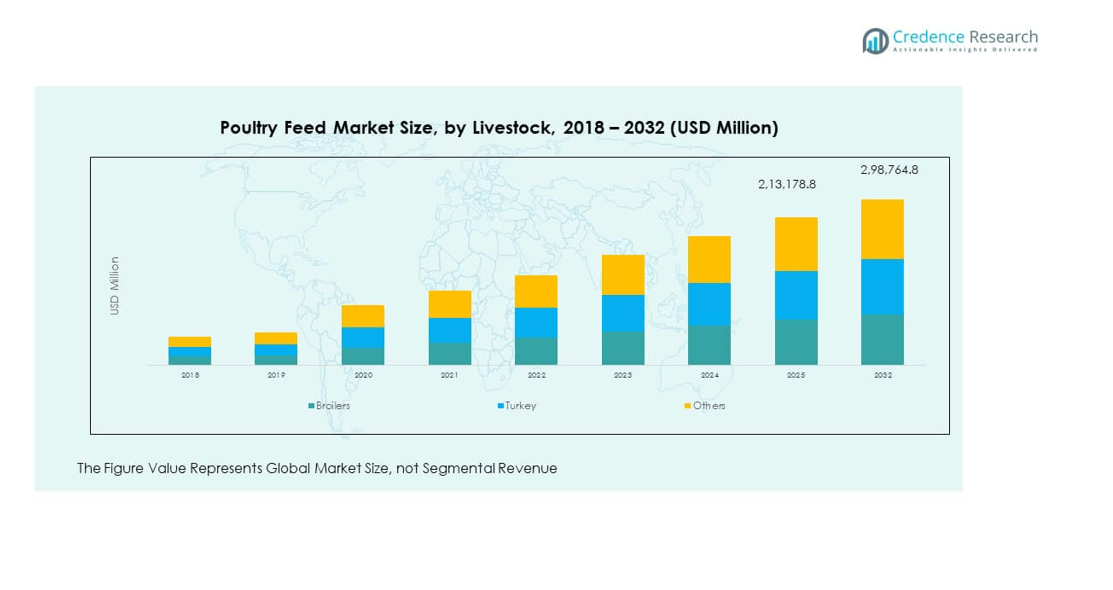
- By livestock, broilers dominated with 62% share in 2024, reflecting their role as the primary protein source in global diets.
- Turkey accounted for 20% and others held 18% in 2024, highlighting steady contributions from niche poultry segments across regional markets.
Market Drivers:
Rising Global Demand for Poultry Protein and Nutritional Efficiency
The Poultry Feed Market is growing due to a sharp increase in global demand for poultry meat and eggs as consumers seek affordable, protein-rich food. It benefits from demographic expansion, urbanization, and rising incomes that stimulate poultry consumption in both emerging and developed economies. Producers are focused on efficiency in feed formulations to improve bird weight gain and optimize conversion rates. Nutritional strategies are designed to enhance growth performance while ensuring cost-effective production. The integration of specialized amino acids, vitamins, and minerals strengthens bird immunity and reduces mortality. Rising consumer focus on food quality and animal welfare also drives innovation in formulations. Governments support the industry through subsidies and research incentives, further boosting feed demand. It positions the sector as a critical link in meeting global protein requirements.
Expanding Technological Advancements in Feed Formulations
Technology is shaping the Poultry Feed Market with innovations in feed formulation and precision nutrition. It leverages advanced feed enzymes that optimize nutrient absorption and reduce feed costs for producers. Developments in probiotics, prebiotics, and organic acids are driving healthier flocks and reducing dependency on antibiotics. Manufacturers are adopting microencapsulation and pelletizing techniques that improve nutrient stability and feed efficiency. Automation and digital platforms allow farmers to track feed intake and adjust diets in real time. These advancements help reduce production costs and improve bird health outcomes. Consumer demand for sustainable, residue-free poultry products is encouraging producers to embrace technology-driven solutions. It ensures competitive advantage for companies investing in innovation.
- For instance, in September 2024, DSM-Firmenich received EU authorization for its new generation phytase enzyme HiPhorius™, which increases phosphorus digestibility in poultry, allowing substantial reduction in costly inorganic phosphorus supplementation while improving feed efficiency for large-scale producers.
Rising Focus on Sustainable and Organic Feed Solutions
Sustainability is driving significant transformation in the Poultry Feed Market as producers align with environmental and consumer preferences. It encourages the use of natural and organic feed ingredients, reducing reliance on synthetic additives. The push for carbon footprint reduction promotes feed formulations that use locally sourced raw materials. Organic certifications are increasingly valued by poultry producers seeking to differentiate their products. Feed companies invest in eco-friendly solutions that balance bird performance with environmental responsibility. Producers also explore insect protein and algae-based ingredients to support sustainability goals. Regulatory frameworks reinforce the adoption of cleaner, eco-friendly practices in feed production. It helps establish long-term resilience in the industry.
- For instance, in May 2024, Goterra-the Australian insect protein specialist-partnered with Skretting Australia to conduct the country’s first large-scale insect rendering trial, producing insect meal with over 70% protein, a level exceeding the performance of conventional soymeal and supporting sustainable poultry nutrition at commercial scale
Growing Role of Government Policies and Regulatory Standards
The Poultry Feed Market is also shaped by strong government policies that promote feed quality and food safety. It is impacted by international standards ensuring compliance with hygiene and nutrition norms. Subsidies and farmer support schemes encourage adoption of advanced feed products across developing nations. Public health concerns are prompting tighter regulations on antibiotic growth promoters, driving alternatives in feed. Farmers benefit from training programs and incentives that emphasize efficient feed utilization. Regulatory focus on transparency is compelling companies to adopt traceability in feed production. Collaborations between governments and industry bodies foster innovation and improve feed availability. It supports global expansion and strengthens consumer confidence in poultry products.
Market Trends:
Rising Adoption of Alternative Protein Ingredients in Poultry Feed
The Poultry Feed Market is witnessing a strong shift toward alternative protein sources driven by sustainability and cost-efficiency. It is influenced by the growing interest in insect-based protein, algae meals, and oilseed byproducts. Feed companies are expanding research to evaluate digestibility and nutrient composition of these alternatives. Rising demand for soymeal substitutes reduces reliance on traditional raw materials. These ingredients are proving effective in meeting nutritional requirements without compromising bird growth. Manufacturers are scaling production of novel protein sources to reduce supply chain risks. Consumer preference for sustainable and eco-friendly practices accelerates this transition. It establishes a long-term trend that diversifies the feed ingredient base.
Increasing Digitalization and Smart Farming Integration in Feed Management
Technology is redefining how the Poultry Feed Market functions, with digital tools driving efficiency. It benefits from smart sensors and automated feeders that optimize bird nutrition and reduce waste. Farmers are using AI-based platforms to predict flock requirements and adjust feed strategies. Precision farming practices enhance resource efficiency, lowering operational costs. Data analytics supports better decision-making in feed composition and nutrient allocation. IoT-enabled systems allow real-time monitoring of poultry health linked with feed consumption. Companies are investing in cloud-based solutions to connect suppliers, farmers, and distributors. It creates an ecosystem of integrated, data-driven feed management.
- For example, Evonik’s Porphyrio® platform is an internationally adopted precision livestock farming tool for poultry. It provides cloud-based data management that allows farms to monitor key parameters such as feed and water intake, body weight, weight gain, egg production, and environmental conditions. By applying big data analytics and self-learning algorithms, the system helps producers improve flock management, optimize production efficiency, and support data-driven decision-making across poultry operations.
Growing Popularity of Functional Feed Additives and Value-Added Solutions
The Poultry Feed Market is experiencing rising adoption of functional additives that enhance bird health and productivity. It includes enzymes, antioxidants, and immune boosters that strengthen poultry against disease. Consumer awareness about safe and healthy poultry products is encouraging demand for value-added feed. Manufacturers are investing in feed fortification to align with premium product positioning. The integration of natural ingredients enhances product differentiation in competitive markets. Probiotic and prebiotic formulations are becoming central to reducing disease outbreaks. Companies are also promoting branded specialty feed to meet specific consumer and farm needs. It signals a long-term trend toward value-driven poultry nutrition.
- For example, in September 2024, DSM-Firmenich received EU authorization for its next-generation phytase enzyme HiPhorius™, approved for use in all poultry species. The enzyme improves phosphorus digestibility by enabling more efficient phytate degradation, which allows producers to reduce reliance on inorganic phosphorus supplements, improve feed conversion, and support growth performance while lowering environmental impact.
Expanding Emphasis on Supply Chain Resilience and Global Trade Dynamics
The Poultry Feed Market is influenced by shifts in global supply chains, driving emphasis on resilience and stability. It is shaped by volatility in grain prices and trade restrictions that impact raw material availability. Producers are diversifying sourcing strategies to ensure consistent feed supply. Partnerships across international markets are strengthening to stabilize ingredient procurement. Companies focus on building regional supply networks that reduce dependency on single sources. Sustainability concerns also affect cross-border trade practices. The pandemic experience highlighted the importance of supply chain flexibility and localization. It redefines industry strategies for long-term stability.
Market Challenges Analysis:
Volatile Raw Material Prices and Supply Constraints
The Poultry Feed Market faces significant challenges due to volatility in raw material prices and limited supply availability. It depends heavily on corn, soy, and other grains, which are vulnerable to climatic conditions and geopolitical disruptions. Price fluctuations increase production costs, placing pressure on farmers and feed manufacturers. Currency variations across international markets further complicate procurement and pricing strategies. Farmers in developing nations face difficulty accessing affordable, high-quality feed. Rising competition for resources between biofuel and feed industries intensifies the challenge. Feed companies must balance cost efficiency with nutritional adequacy in this complex environment. It makes price stability and reliable supply crucial for sustained growth.
Stringent Regulations and Rising Pressure on Sustainability Compliance
The Poultry Feed Market is also challenged by stringent regulations that restrict certain additives and antibiotic use. It is under pressure to comply with evolving standards in food safety and animal welfare. Meeting sustainability goals increases production costs for manufacturers. Small and medium enterprises often struggle to adopt eco-friendly practices due to resource limitations. Consumer demand for transparency compels companies to invest in traceable supply chains. Shifting trade policies add complexity for exporters navigating multiple regulations. Innovation is required to balance compliance with profitability. It highlights the importance of strategic planning in overcoming regulatory and environmental challenges.
Market Opportunities:
Rising Consumer Shift Toward Protein-Rich Diets and Expanding Poultry Production
The Poultry Feed Market presents opportunities fueled by the global demand for protein-rich diets and rising poultry consumption. It is supported by urbanization, changing food habits, and expanding middle-class populations. Poultry products offer affordable and versatile protein sources compared to red meat. Emerging markets are witnessing strong poultry sector investments that increase feed demand. Companies can expand their presence by introducing cost-effective, nutritionally advanced formulations. Technological innovation allows manufacturers to launch premium feed targeting specific poultry breeds. It creates multiple revenue streams in both developed and emerging economies.
Expansion of Sustainable and Specialty Feed Segments Across Global Markets
The Poultry Feed Market is opening avenues through the expansion of sustainable and specialty feed categories. It benefits from rising consumer awareness of organic, antibiotic-free, and eco-friendly poultry products. Companies investing in natural additives, alternative proteins, and traceable ingredients gain competitive advantage. Opportunities also exist in catering to niche markets such as free-range and premium poultry segments. Regional markets are opening new growth channels for customized feed offerings. Strategic partnerships with farms strengthen distribution networks and market penetration. It enables companies to align business models with future food system requirements.
Market Segmentation Analysis:
By livestock, the Poultry Feed Market demonstrates strong growth across livestock categories, with broilers holding the largest share due to rising global consumption of poultry meat. Layers also contribute significantly as egg demand strengthens across both developed and emerging economies. Turkey feed represents a niche but steadily growing segment, particularly in North America and Europe. Other poultry categories, including ducks and specialty breeds, provide additional opportunities for market expansion supported by regional dietary preferences and diversified farming practices.
By nature, conventional feed dominates due to its affordability and widespread adoption in high-volume poultry production systems. Organic feed, while smaller in share, is gaining traction as consumer preference shifts toward chemical-free and sustainable poultry products. It benefits from rising awareness of food safety, creating premium growth opportunities in developed markets.
- For example, in 2024, Nutrena, a Cargill brand, expanded its certified organic poultry feed portfolio in the United States to address rising consumer demand for chemical-free eggs and poultry products.
By feed type analysis highlights corn as the primary input, driven by its high energy content and global availability. Wheat contributes to market expansion where regional production is strong, particularly in Europe. Barley plays a supportive role in specific geographies, offering cost-efficient alternatives for balanced nutrition. It underlines the dependence of the industry on reliable grain supply chains.
By form, pellets account for significant adoption due to their digestibility, ease of handling, and efficiency in large-scale operations. Granules maintain importance in certain poultry diets, while powdered feed serves smaller farms and niche applications. It reflects how formulation and delivery methods are tailored to livestock requirements, cost structures, and regional farming practices, shaping long-term growth opportunities.
- For example, Skretting, the aquaculture feed division of Nutreco, continues to advance feed technology and sustainability through innovation initiatives highlighted in its 2024 Impact Report. The company emphasizes improving efficiency, reducing environmental impact, and supporting large-scale operations across global markets, including Europe.
Segmentation:
By Livestock
- Layers
- Broilers
- Turkey
- Others
By Nature
- Conventional
- Organic
By Feed Type
- Corn
- Wheat
- Barley
By Form
- Granules
- Pellets
- Powder
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Poultry Feed Market size was valued at USD 57,115.2 million in 2018 to USD 65,479.5 million in 2024 and is anticipated to reach USD 95,911.9 million by 2032, at a CAGR of 4.9% during the forecast period. Market share: 32.1% in 2024. North America sustains a mature value chain with advanced milling technologies and efficient grain supply. The Poultry Feed Market here is supported by large integrated operations, particularly in the U.S., where broilers dominate production. Canada drives growth through specialty and organic feed segments, reflecting consumer demand for premium poultry products. Mexico contributes through modernized farming infrastructure and rising consumption. Producers invest in probiotics, amino acids, and enzyme-based feed to improve flock performance and comply with antibiotic-reduction regulations. Retailers demand consistent quality and traceability, accelerating adoption of digital batch tracking. Industry focus on sustainability and precision nutrition is reshaping feed strategies. It strengthens the market’s long-term competitiveness.
Europe
The Europe Poultry Feed Market size was valued at USD 33,288.0 million in 2018 to USD 36,603.4 million in 2024 and is anticipated to reach USD 49,521.1 million by 2032, at a CAGR of 3.9% during the forecast period. Market share: 18.0% in 2024. Europe’s growth is driven by stringent regulatory frameworks, consumer preference for non-GMO feed, and rapid adoption of specialty additives. The Poultry Feed Market prioritizes sustainability and welfare, pushing producers toward organic and natural formulations. Western Europe supports premium demand, while Central and Eastern Europe expand low-cost production using regional grain flows. Feed mills invest in energy-efficient technologies and advanced pelleting processes to improve efficiency. Strict environmental policies encourage innovation in circular feed ingredients. Traceability and transparency remain critical as retailers impose rigorous quality audits. It positions Europe as a hub for premium, eco-conscious poultry production.
Asia Pacific
The Asia Pacific Poultry Feed Market size was valued at USD 60,969.6 million in 2018 to USD 73,064.3 million in 2024 and is anticipated to reach USD 114,854.4 million by 2032, at a CAGR of 5.8% during the forecast period. Market share: 35.9% in 2024. Asia Pacific leads the global landscape, powered by population scale, rapid urbanization, and evolving dietary patterns. The Poultry Feed Market is shaped by China and India, which dominate both broiler and layer segments. Southeast Asian nations such as Vietnam and Indonesia show accelerating demand, supported by modern retail and fast-food penetration. Regional grain variability drives dynamic feed formulations, balancing corn and wheat imports. Producers deploy advanced enzymes, probiotics, and precision nutrition to raise feed efficiency and control costs. Governments support modernization through subsidies, disease surveillance, and farmer training programs. International and regional players continue to invest in large-scale feed mills and distribution networks. It strengthens Asia Pacific’s leadership role.
Latin America
The Latin America Poultry Feed Market size was valued at USD 9,495.8 million in 2018 to USD 10,911.4 million in 2024 and is anticipated to reach USD 14,663.4 million by 2032, at a CAGR of 3.8% during the forecast period. Market share: 5.4% in 2024. Latin America benefits from abundant corn and soybean supplies, enabling competitive feed costs. The Poultry Feed Market is anchored by Brazil, which operates large integrated poultry complexes targeting global exports. Argentina supports growth through efficient grain processing and regional trade flows. Chile and Colombia add momentum through rising domestic poultry consumption. Producers emphasize high-quality pelleting, toxin control, and amino acid optimization to meet international standards. Certification for halal and export compliance opens new trade opportunities. Investment in port and rail logistics enhances competitiveness and improves export readiness. It reinforces the region’s role as a cost-advantaged supplier in global trade.
Middle East
The Middle East Poultry Feed Market size was valued at USD 8,935.2 million in 2018 to USD 9,894.1 million in 2024 and is anticipated to reach USD 13,475.9 million by 2032, at a CAGR of 4.0% during the forecast period. Market share: 4.9% in 2024. The region relies heavily on grain imports but invests in domestic milling capacity and integrated poultry projects. The Poultry Feed Market is supported by GCC initiatives aimed at food security and local production. Formulators adapt feed rations to address heat stress and optimize flock health with electrolytes and antioxidants. Vertical integration ensures quality control across feed-to-meat value chains. Specialty premix and additive hubs expand in Saudi Arabia and the UAE to reduce import dependency. Halal certification requirements reinforce strict compliance and product consistency. Government-backed infrastructure for logistics and cold chains enhances market resilience. It positions the Middle East as a rising growth hub with strong domestic demand.
Africa
The Africa Poultry Feed Market size was valued at USD 5,396.2 million in 2018 to USD 7,656.5 million in 2024 and is anticipated to reach USD 10,338.2 million by 2032, at a CAGR of 3.6% during the forecast period. Market share: 3.8% in 2024. Africa shows steady growth, led by Nigeria, South Africa, and Egypt, where poultry production is expanding to meet urban protein demand. The Poultry Feed Market faces challenges in access to quality maize and soy, creating supply volatility. Smallholder farmers increasingly adopt premixes and fortified feed to improve flock performance. Cold chain development supports processed poultry, reducing post-harvest losses. Regional trade corridors are vital for grain imports and intra-African feed distribution. Disease management and biosecurity remain critical in driving productivity gains. Governments and private investors are funding local milling projects to reduce dependency on imports. It strengthens Africa’s role as an emerging growth frontier.
Key Player Analysis:
- Tetra Laval International S.A.
- GEA Group
- John Bean Technologies Corporation (JBT)
- SPX Corporation
- Hosokawa Micron Corp.
- Anko Food Machine Co. Ltd.
- Berkshire Hathaway Inc.
- Bucher Industries
- Mallet & Company, Inc.
- NICHIMO CO., LTD.
Competitive Analysis:
The Poultry Feed Market is highly competitive with the presence of global corporations and regional players focusing on product innovation, capacity expansion, and sustainability initiatives. Leading companies such as Cargill, ADM, Alltech, De Heus, and Nutreco dominate through integrated operations and advanced feed formulations. It emphasizes differentiation through nutritional additives, organic feed solutions, and precision nutrition technologies. Regional firms strengthen their position by leveraging local grain supplies and cost efficiencies. Strategic partnerships, acquisitions, and investments in digital feed management tools are reshaping the competitive landscape. Producers concentrate on balancing cost efficiency with high-quality output to meet diverse consumer expectations. Innovation, regulatory compliance, and supply chain resilience remain central to maintaining market leadership.
Recent Developments:
- In August 2025, Cargill announced the launch of a new retail feed facility in Granger, Washington, aimed at expanding its production capacity and creating new jobs in the region. This new plant is designed to enhance local feed production and meet growing demand for advanced poultry feed, representing Cargill’s commitment to supporting U.S. farmers and processors with improved efficiency.
- In August 2025, Saudi Arabia’s First Mills completed the acquisition of Al-Manar Feed Company Ltd. for $20.52 million, marking a major strategic expansion in the animal and poultry feed sector. This acquisition is expected to increase First Mills’ total daily feed production capacity by 420 tonnes, bringing the company’s total output to 1,320 tonnes per day.
Market Concentration & Characteristics:
The Poultry Feed Market demonstrates moderate to high concentration, with multinational corporations holding significant shares alongside strong regional competitors. It reflects characteristics of scale-driven growth, continuous innovation, and evolving sustainability standards. Market leaders invest in R&D to enhance feed conversion ratios, reduce environmental impact, and support antibiotic-free production. Regional dynamics create opportunities for mid-tier players to capture niche segments such as organic and specialty feed. The industry is shaped by high entry barriers, global trade dependencies, and regulatory oversight, which collectively drive consolidation and long-term strategic positioning.
Report Coverage:
The research report offers an in-depth analysis based on Livestock, Nature, Feed Type and Form. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Poultry Feed Market is expected to witness steady growth as global demand for affordable and protein-rich poultry products continues to rise, supported by changing dietary preferences.
- Precision nutrition will become more prominent, with digital platforms, AI, and real-time monitoring enabling farmers to optimize feed efficiency and reduce waste.
- Sustainability goals will push producers toward eco-friendly ingredients, circular economy practices, and low-carbon feed formulations to align with environmental commitments.
- Organic and antibiotic-free feed will expand as consumer health awareness strengthens, driving a shift toward cleaner and safer poultry production.
- Regional supply chain integration will gain momentum, ensuring stable grain access and reducing risks linked to raw material price volatility.
- Functional feed additives such as probiotics, prebiotics, and enzymes will evolve as core components of advanced poultry diets.
- Emerging economies will fuel rapid growth through modernization of poultry farms, expanding capacity, and rising disposable incomes.
- Stronger partnerships between feed producers, integrators, and retailers will ensure consistency, traceability, and long-term competitiveness.
- R&D will accelerate innovation in alternative protein sources, including insect meal, algae, and plant-based substitutes.
- Regulatory frameworks will shape market strategies by enforcing strict compliance on quality, safety, and sustainability standards.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Demand for Poultry Protein and Nutritional Efficiency
Increasing meat and egg consumption, driven by population growth, urbanization, and rising incomes, is fueling demand for poultry feed. Producers are optimizing feed formulations to improve bird growth and feed conversion, supporting efficient and cost-effective poultry production.
Expanding Technological Advancements in Feed Formulations
Innovations such as advanced enzymes, probiotics, and precision nutrition technologies are enhancing nutrient absorption, reducing feed costs, and improving flock health. Digital tools and automation enable real-time monitoring and adjustment of feed strategies, boosting productivity and sustainability.
Rising Focus on Sustainable and Organic Feed Solutions
Consumer and regulatory pressure for eco-friendly, residue-free poultry products is driving the adoption of natural, organic, and locally sourced feed ingredients. Companies are investing in alternative proteins like insect meal and algae to reduce environmental impact and differentiate their offerings.
Growing Role of Government Policies and Regulatory Standards
Government subsidies, research incentives, and stricter regulations on antibiotic use are encouraging the adoption of advanced, compliant feed products. Regulatory frameworks are also pushing for greater transparency and traceability, supporting market growth and consumer confidence.
Increasing Adoption of Functional Feed Additives and Value-Added Solutions
The integration of enzymes, antioxidants, and immune-boosting additives is improving bird health and productivity, meeting consumer demand for safer and higher-quality poultry products. This trend supports premiumization and value-driven growth in the poultry feed market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Poultry Feed Market from 2024 to 2032?
What are the key drivers behind the growth of the Poultry Feed Market?
How is the poultry feed market being influenced by government policies?
Which regions are seeing the highest growth in the Poultry Feed Market?
What innovations in poultry feed are driving market demand?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Granules
- 1.2.2 Pellets
- 1.2.3 Powder
- 1.3 By Nature
- 1.3.1 Conventional
- 1.3.2 Organic
- 1.4 By Feed Type
- 1.4.1 Corn
- 1.4.2 Wheat
- 1.4.3 Barley
- 1.5 By Livestock
- 1.5.1 Broilers
- 1.5.2 Layers
- 1.5.3 Turkey
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,03,609.2 million → 2032: USD 2,98,764.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Poultry Feed Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Poultry Feed Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Poultry Feed Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Poultry Feed Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Poultry Feed Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Poultry Feed Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Poultry Feed Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Poultry Feed Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,03,609.2 million → 2032: USD 2,98,764.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Poultry Feed Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Granules
- 12.3.7.2 Pellets
- 12.3.7.3 Powder
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Nature - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional
- 12.4.7.2 Organic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Feed Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Corn
- 12.5.7.2 Wheat
- 12.5.7.3 Barley
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Livestock - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Broilers
- 12.6.7.2 Layers
- 12.6.7.3 Turkey
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Poultry Feed Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Poultry Feed Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Poultry Feed Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cargill
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 ADM (Archer Daniels Midland)
- 17.4 Alltech
- 17.5 Nutreco
- 17.6 De Heus
- 17.7 DSM-Firmenich
- 17.8 Skretting
- 17.9 Tetra Laval International S.A.
- 17.10 Berkshire Hathaway Inc.
- 17.11 GEA Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

