
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Poultry Farming Equipment Market Size 2024 | USD 3530 Million |
| Poultry Farming Equipment Market, CAGR | 6% |
| Poultry Farming Equipment Market Size 2032 | USD 5626.28 Million |
Market Overview:
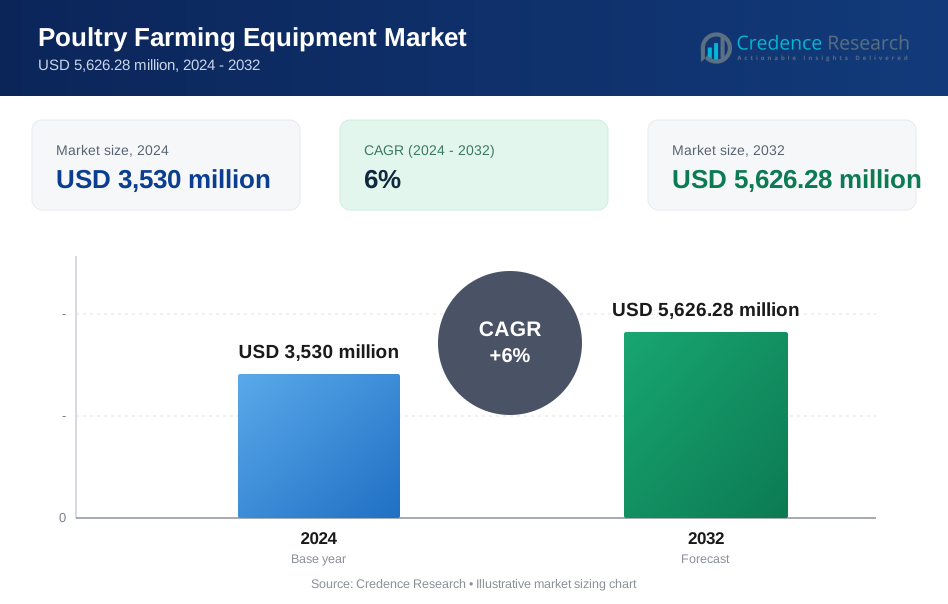
The Poultry Farming Equipment Market size was valued at USD 3530 million in 2024 and is anticipated to reach USD 5626.28 million by 2032, at a CAGR of 6% during the forecast period (2024-2032).
Key drivers contributing to market expansion include the increasing global demand for eggs and poultry meat, growing concerns over biosecurity, and the shift towards large-scale, intensive poultry farming practices. Automation and IoT-enabled systems are revolutionizing poultry management by optimizing feed distribution, egg collection, and disease monitoring. Additionally, stringent regulatory standards for food safety and animal welfare are compelling poultry farmers to invest in advanced equipment that ensures hygiene and efficient waste management. The rising awareness of energy-efficient solutions, such as solar-powered ventilation systems and water-saving technologies, is also promoting market growth. The integration of artificial intelligence (AI) in precision livestock farming is further enhancing poultry production efficiency. Additionally, innovations in vaccine delivery and automated disease control systems are helping to reduce mortality rates and improve overall poultry health.
Regionally, Asia-Pacific dominates the poultry farming equipment market, supported by the rapid expansion of poultry farms in countries like China, India, and Indonesia. Increasing population, urbanization, and rising disposable income in these regions are driving poultry consumption, thereby boosting equipment demand. North America and Europe are witnessing strong adoption of precision poultry farming technologies due to stringent animal welfare regulations and the presence of well-established poultry producers. Meanwhile, Latin America and the Middle East & Africa are gradually increasing their investments in modern poultry farming infrastructure, supported by government initiatives and foreign investments in agribusiness. The increasing penetration of contract farming in developing economies is accelerating the demand for modern poultry equipment. Additionally, the expansion of cold chain logistics and storage infrastructure is enabling better poultry product distribution, further supporting market growth.
Market Insights:
- The poultry farming equipment market was valued at USD 3,530 million in 2024 and is projected to reach USD 5,626.28 million by 2032, driven by increasing poultry consumption and technological advancements.
- Rising global demand for eggs and poultry meat is accelerating the adoption of automated farming solutions, ensuring efficiency and higher production rates in large-scale operations.
- Automation and IoT-enabled systems are transforming poultry farming, optimizing feed distribution, egg collection, and disease monitoring, significantly improving productivity and biosecurity.
- Stringent food safety and animal welfare regulations are compelling poultry farmers to invest in advanced equipment such as climate control, automated cleaning, and biosecurity solutions.
- Energy-efficient and sustainable farming solutions, including solar-powered ventilation and waste-to-energy systems, are gaining traction to reduce operational costs and environmental impact.
- Asia-Pacific leads the market with 44% share, fueled by increasing poultry farm expansions in China, India, and Indonesia, while North America (28%) and Europe (19%) are driving precision farming adoption.
- The expansion of cold chain logistics and contract farming models is supporting better poultry product distribution, making advanced equipment more accessible to poultry producers worldwide.
Market Drivers:
Rising Global Demand for Poultry Products:
The increasing consumption of poultry meat and eggs is a primary driver of the poultry farming equipment market. Poultry is one of the most affordable and protein-rich food sources, making it a staple in global diets. For instance, Rabobank projects a robust growth year for the global poultry industry in 2025, fueled by affordability and strong demand in emerging markets. With growing populations, urbanization, and changing consumer preferences toward lean protein, the demand for efficient poultry farming solutions is rising. The expanding fast-food industry and the growing popularity of ready-to-eat poultry products are further fueling production, necessitating advanced equipment for large-scale operations.
Advancements in Automation and Smart Farming Technologies:
Technological advancements, including automation, artificial intelligence (AI), and IoT-enabled systems, are revolutionizing poultry farming. Automated feeding, climate control, and disease monitoring systems enhance productivity and reduce operational costs. For instance, the use of SmartFarm technology by companies like Big Dutchman allows farmers to monitor flock health and optimize feeding schedules through real-time data analytics. Precision farming tools, such as smart sensors and real-time analytics, help farmers track bird health, optimize feed consumption, and improve overall efficiency. The integration of AI in predictive maintenance and automated egg collection systems is streamlining operations and reducing labor dependency.
Stringent Food Safety and Animal Welfare Regulations:
Governments and regulatory bodies worldwide are implementing stringent standards to ensure food safety and animal welfare in poultry farming. Compliance with hygiene protocols, biosecurity measures, and humane handling practices has become a priority, driving the demand for advanced farming equipment. For instance, the USDA's new guidelines on poultry processing are encouraging farms like Perdue Farms to adopt enhanced biosecurity measures and improve animal welfare protocols. Automated cleaning, waste management, and vaccination systems help maintain high biosecurity levels and reduce disease outbreaks. Moreover, the push for antibiotic-free poultry farming is encouraging the adoption of controlled environments and precision health monitoring solutions.
Growing Adoption of Sustainable and Energy-Efficient Solutions:
The poultry industry is increasingly embracing sustainable farming practices to reduce environmental impact. Energy-efficient ventilation systems, solar-powered incubators, and water-efficient cooling technologies are gaining traction. For instance, Pilgrim's Pride has invested in solar energy solutions across their facilities, significantly reducing their reliance on fossil fuels and lowering operational costs. The rising awareness of carbon footprint reduction and resource conservation is pushing poultry farmers to invest in eco-friendly equipment. Additionally, waste-to-energy solutions, such as manure processing and biogas generation, are contributing to sustainability while improving farm profitability.
Market Trends:
Integration of Smart Farming Technologies:
The adoption of smart farming solutions is transforming poultry operations, enhancing efficiency and productivity. For instance, at the University of Alberta, researchers developed precision feeding stations with RFID technology that monitor individual bird bodyweight and feed intake patterns, serving as an early warning system for disease outbreaks. IoT-enabled sensors, AI-driven monitoring systems, and cloud-based data analytics are helping farmers optimize feeding schedules, detect diseases early, and improve flock management. Automated climate control systems ensure optimal temperature and humidity, reducing mortality rates and improving poultry health.
Growing Demand for Energy-Efficient and Sustainable Equipment:
Sustainability is becoming a key focus in poultry farming, driving the demand for energy-efficient equipment. For instance, an Ontario egg farm implemented a solar pre-heating wall system that provided heated air volume for the barn and demonstrated significant energy savings. Solar-powered incubators, LED lighting solutions, and water-efficient cooling systems are reducing operational costs and minimizing environmental impact. Farmers are also adopting waste management solutions such as manure processing systems and biogas generation, aligning with global sustainability initiatives and regulatory compliance.
Increased Adoption of Automated Feeding and Egg Collection Systems:
The shift toward automation is accelerating, with advanced feeding systems ensuring precise nutrition management while reducing feed wastage. For instance, Retech Farming has implemented automated egg collection systems that utilize conveyor belts and egg elevators to efficiently collect eggs while minimizing labor costs. Automated egg collection and sorting systems are improving efficiency and minimizing human intervention, leading to higher productivity. Robotics and AI-driven solutions are further enhancing flock management by automating repetitive tasks such as vaccination, cleaning, and disease detection.
Rising Focus on Biosecurity and Disease Prevention:
The growing emphasis on disease control and biosecurity is prompting the adoption of advanced disinfection systems, air filtration units, and biosecure housing designs. For instance, the implementation of the Biosecurity Assurance System (BAS) in Italian broiler breeders demonstrated a significant reduction in veterinary costs and increased egg production, resulting in an excellent cost-benefit ratio. Strict regulations on antibiotic use are driving investments in vaccination delivery systems and real-time health monitoring technologies. Poultry farms are increasingly implementing closed-environment rearing methods to minimize disease outbreaks and ensure consistent poultry production.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs:
One of the primary challenges in the poultry farming equipment market is the significant capital investment required for automation and modern infrastructure. Advanced equipment such as automated feeding systems, climate control units, and disease monitoring solutions involve high upfront costs, making it difficult for small and medium-scale farmers to adopt them. Additionally, the ongoing maintenance and operational expenses, including software updates, energy consumption, and periodic servicing, add to the financial burden. Many farmers in developing regions rely on traditional methods due to limited access to financing options and subsidies, which further slows down the adoption of advanced poultry farming technologies.
Regulatory Compliance and Biosecurity Risks:
Stringent regulations related to food safety, animal welfare, and environmental sustainability pose significant challenges for poultry farmers and equipment manufacturers. Compliance with evolving global and regional standards requires continuous investment in upgraded equipment and biosecurity measures. Additionally, the poultry industry faces ongoing risks from disease outbreaks such as avian influenza, which can lead to severe production losses and increased biosecurity costs. Implementing effective disease prevention strategies, such as advanced disinfection systems and vaccination technologies, is essential but adds complexity to farm operations. The growing restrictions on antibiotic use and the need for alternative health management solutions further increase operational challenges for poultry farmers, necessitating greater research and innovation in disease prevention and poultry health management.
Market Opportunities:
The poultry farming equipment market presents significant growth opportunities, driven by the increasing adoption of automation and precision farming technologies. As poultry producers seek to enhance efficiency and productivity, the demand for advanced feeding, watering, and climate control systems is rising. The integration of artificial intelligence (AI), Internet of Things (IoT), and data analytics in poultry management is creating new avenues for equipment manufacturers to develop smart solutions that optimize production while reducing operational costs. Additionally, the growing focus on animal welfare and biosecurity regulations is encouraging investment in automated monitoring and disease prevention systems, providing an opportunity for companies to innovate in health management solutions.
Expanding poultry consumption in emerging economies further strengthens the market potential, as rising urbanization and changing dietary preferences drive higher demand for poultry products. Government initiatives promoting sustainable and energy-efficient farming practices are also creating opportunities for the adoption of eco-friendly equipment such as solar-powered incubators, waste recycling systems, and water-efficient cooling solutions. The expansion of contract farming models, where large poultry integrators provide modern equipment to smaller farms, is facilitating the transition toward advanced farming techniques. Additionally, the increasing penetration of e-commerce and digital platforms is streamlining equipment sales and distribution, making modern poultry solutions more accessible to farmers worldwide. With ongoing technological advancements and supportive policies, the poultry farming equipment market is well-positioned for sustained growth in the coming years.
Market Segmentation Analysis:
By Product Type
The poultry farming equipment market is segmented into feeding systems, watering systems, climate control systems, egg collection equipment, and waste management systems. Feeding and watering systems hold a significant share due to the rising demand for automated solutions that ensure precise nutrition management and minimize feed wastage. Climate control systems, including ventilation and temperature regulation equipment, are gaining traction as poultry farmers prioritize optimal environmental conditions to improve bird health and productivity. Additionally, advancements in waste management solutions, such as manure processing and biosecurity-enhancing disinfection systems, are driving adoption across large-scale poultry farms.
By Poultry
Based on poultry type, the market is categorized into broilers, layers, and breeders. The broiler segment dominates the market, driven by the increasing global demand for poultry meat. Large-scale commercial broiler farming requires efficient feeding, climate control, and disease management systems to ensure high productivity. The layer segment is also experiencing growth, supported by the rising consumption of eggs and the adoption of automated egg collection and sorting systems. The breeder segment, essential for maintaining poultry production cycles, is witnessing increased investment in advanced incubation and vaccination technologies to enhance hatchability and flock health.
By Operation
The market is further segmented into manual, semi-automatic, and fully automatic operations. Fully automated poultry farming equipment is experiencing strong demand due to its ability to enhance efficiency, reduce labor dependency, and improve biosecurity measures. Semi-automatic systems remain widely used in mid-sized farms, offering a balance between automation and affordability. Meanwhile, manual operations persist in small-scale poultry farms, particularly in developing regions where financial constraints limit the adoption of modern farming technologies.
Segmentations:
By Product Type:
- Incubators & Brooder
- Hatchers
- Watering & Feeding System
- Egg Handling Equipment
- Egg Collecting Equipment
- Cage System
- Vaccination System
- Washers & Waste Removal Systems
- House System
- Ventilation
- Lighting
- Others
By Poultry:
- Chicken
- Turkey
- Duck
- Others
By Operation:
- Automatic
- Manual
- Semi-automatic
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds 44% of the poultry farming equipment market share, making it the leading region due to the high demand for poultry products and the rapid expansion of commercial poultry farming. Countries such as China, India, and Indonesia are experiencing strong growth in poultry consumption, driven by rising incomes, population growth, and increasing urbanization. Government initiatives supporting large-scale poultry farming and investments in automated feeding, climate control, and disease monitoring systems are further propelling market expansion. Additionally, the region is witnessing a shift toward precision farming, with an increasing number of farmers adopting IoT-enabled equipment and energy-efficient technologies to enhance production efficiency and sustainability. The rising influence of international poultry integrators and foreign investments in advanced farming solutions is also contributing to market growth.
North America
North America accounts for 28% of the poultry farming equipment market share, supported by high poultry consumption, stringent animal welfare regulations, and strong technological adoption. The United States and Canada lead the market with well-established poultry farming operations that prioritize automation and biosecurity. The demand for fully automated feeding, egg collection, and climate control systems is rising as poultry producers seek to optimize efficiency while complying with strict food safety standards. The region is also a hub for research and innovation in sustainable poultry farming, with companies developing solar-powered incubators, AI-driven disease detection, and robotic monitoring solutions. Additionally, the presence of large poultry integrators and contract farming models is enabling small and mid-sized farms to transition toward advanced farming equipment, further driving market expansion.
Europe
Europe holds 19% of the poultry farming equipment market share, driven by increasing regulatory compliance related to animal welfare, environmental sustainability, and antibiotic-free poultry production. The European Union enforces strict biosecurity measures, compelling poultry farmers to invest in automated disinfection systems, climate-controlled housing, and precision feeding equipment. Countries such as Germany, France, and the Netherlands are leading adopters of smart poultry farming solutions, integrating AI-based monitoring, real-time data analytics, and renewable energy solutions to improve efficiency. The rising consumer preference for organic and free-range poultry farming is also shaping equipment demand, with a focus on sustainable waste management and eco-friendly farming practices. Furthermore, the expansion of cold chain logistics and advanced storage solutions is supporting the efficient distribution of poultry products across the region.
Key Player Analysis:
- Vencomatic Group
- Tecno Poultry Equipment
- Petersime NV
- Jamesway Incubator Company
- Big Dutchman International GmbH
- Valco Companies, Inc.
- OFFICINE FACCO & C. Spa
- LUBING
- Jansen Poultry Equipment
- ME International Installation GMBH
Competitive Analysis:
The poultry farming equipment market is highly competitive, with key players focusing on technological advancements, product innovation, and strategic partnerships to strengthen their market position. For instance, Cumberland Poultry launched Scout, a pioneering ceiling-suspended robot system that increases farm production and animal welfare by continuously monitoring broiler chickens and poultry house conditions. Leading companies are investing in automation, IoT-enabled monitoring systems, and energy-efficient solutions to enhance farm productivity and biosecurity. The growing demand for fully automated feeding, egg collection, and climate control systems is driving competition among established manufacturers and emerging players. Market leaders are expanding their global footprint through mergers, acquisitions, and collaborations with poultry integrators and contract farmers. Regional players are gaining traction by offering cost-effective and customized solutions tailored to specific farming needs. Additionally, companies are focusing on sustainability initiatives, such as solar-powered equipment and waste management solutions, to align with evolving regulatory standards. As poultry consumption rises globally, competition is expected to intensify, leading to further innovation and market expansion.
Recent Developments:
- In November 2024, Tecno Poultry Equipment became part of the Grain and Protein Technologies Group following AGCO's acquisition by American Industrial Partners.
- In November 2024, Tecno Poultry Equipment announced strategic investments in workforce and partnerships to enhance egg production systems.
- In September 2024, Petersime NV completed a major broiler hatchery upgrade project for Delmon Poultry Company in Bahrain, installing 18 X-Streamer 8S HD setters and 6 X-Streamer 4H HD hatchers.
Market Concentration & Characteristics:
The poultry farming equipment market is moderately concentrated, with a mix of global manufacturers and regional players competing to meet the growing demand for automation and efficiency in poultry farming. Leading companies dominate the market with advanced technologies, including IoT-enabled monitoring systems, automated feeding solutions, and climate control equipment, while smaller players focus on cost-effective and customized solutions. The market is characterized by continuous innovation, driven by the need for improved biosecurity, sustainability, and production efficiency. Regulatory compliance, particularly concerning animal welfare and food safety, is shaping product development and adoption trends. Additionally, the increasing penetration of contract farming and large-scale poultry integrations is fostering demand for standardized and scalable equipment solutions. As sustainability gains prominence, manufacturers are investing in energy-efficient and eco-friendly technologies to align with industry trends and regulatory requirements, further influencing market dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Poultry, Operation and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The poultry farming equipment market is expected to witness strong growth as automation and precision farming technologies become integral to improving productivity and efficiency.
- The adoption of AI-driven monitoring systems, smart feeding solutions, and real-time health tracking will enhance poultry farm management, reducing operational costs and optimizing production.
- Increasing investments in sustainable and energy-efficient equipment, such as solar-powered incubators and water-saving cooling systems, will drive market expansion and align with global sustainability goals.
- Rising consumer demand for antibiotic-free and organic poultry products will encourage the development of advanced biosecurity solutions and disease prevention technologies.
- Government regulations on animal welfare and food safety will accelerate the adoption of automated climate control, waste management, and hygiene systems in poultry farms.
- Growth in contract farming models and integrated poultry operations will create demand for standardized, scalable, and high-efficiency farming equipment.
- The expansion of e-commerce and digital sales channels will improve access to modern poultry farming equipment, particularly for small and medium-sized farmers in developing regions.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will experience increased adoption of automated poultry farming solutions due to rising poultry consumption and economic growth.
- Technological advancements in robotics and automation will lead to increased deployment of robotic egg collection, AI-powered disease detection, and automated cleaning systems.
- Strategic collaborations between equipment manufacturers and poultry producers will drive innovation and accelerate the integration of smart farming technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Automation and IoT
The integration of automation, IoT-enabled systems, and artificial intelligence is transforming poultry farming by optimizing feed distribution, egg collection, and disease monitoring, which significantly improves productivity and reduces labor costs.
Stringent Food Safety and Animal Welfare Regulations
Increasingly strict regulations on food safety and animal welfare are compelling poultry farmers to invest in advanced equipment such as automated cleaning, climate control, and biosecurity solutions to ensure compliance and minimize disease outbreaks.
Shift Toward Large-Scale and Intensive Poultry Farming
The global trend toward large-scale, intensive poultry operations is driving demand for high-efficiency, automated equipment that can support higher production volumes and consistent quality, especially in rapidly urbanizing regions.
Rising Focus on Sustainability and Energy Efficiency
Growing awareness of environmental impact and operational costs is encouraging the adoption of energy-efficient solutions like solar-powered ventilation and waste-to-energy systems, supporting both sustainability goals and profitability.
Expansion of Contract Farming and Cold Chain Logistics
The increasing prevalence of contract farming models and improved cold chain infrastructure is making advanced poultry equipment more accessible to producers, enabling better product distribution and supporting market growth in emerging economies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the poultry farming equipment industry?
What factors are driving the growth of the poultry farming equipment market?
How is technology impacting poultry farming equipment?
Which region holds the largest share in the poultry farming equipment market?
How is sustainability influencing poultry farming equipment adoption?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Poultry
- 1.2.1 Chicken
- 1.2.2 Turkey
- 1.2.3 Duck
- 1.2.4 Others
- 1.3 By Operation
- 1.3.1 Automatic
- 1.3.2 Manual
- 1.3.3 Semi-automatic
- 1.4 By Product Type
- 1.4.1 Incubators & Brooder
- 1.4.2 Hatchers
- 1.4.3 Watering & Feeding System
- 1.4.4 Egg Handling Equipment
- 1.4.5 Egg Collecting Equipment
- 1.4.6 Cage System
- 1.4.7 Vaccination System
- 1.4.8 Washers & Waste Removal Systems
- 1.4.9 House System
- 1.4.10 Ventilation
- 1.4.11 Lighting
- 1.4.12 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,530 million → 2032: USD 5,626.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Poultry Farming Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Poultry Farming Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Poultry Farming Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Poultry Farming Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Poultry Farming Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Poultry Farming Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Poultry Farming Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Poultry Farming Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,530 million → 2032: USD 5,626.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Poultry Farming Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Poultry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chicken
- 12.3.7.2 Turkey
- 12.3.7.3 Duck
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Operation - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automatic
- 12.4.7.2 Manual
- 12.4.7.3 Semi-automatic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Incubators & Brooder
- 12.5.7.2 Hatchers
- 12.5.7.3 Watering & Feeding System
- 12.5.7.4 Egg Handling Equipment
- 12.5.7.5 Egg Collecting Equipment
- 12.5.7.6 Cage System
- 12.5.7.7 Vaccination System
- 12.5.7.8 Washers & Waste Removal Systems
- 12.5.7.9 House System
- 12.5.7.10 Ventilation
- 12.5.7.11 Lighting
- 12.5.7.12 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Poultry Farming Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Poultry Farming Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Poultry Farming Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Vencomatic Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Tecno Poultry Equipment
- 17.4 Petersime NV
- 17.5 Jamesway Incubator Company
- 17.6 Big Dutchman International GmbH
- 17.7 Valco Companies, Inc.
- 17.8 OFFICINE FACCO & C. Spa
- 17.9 LUBING
- 17.10 Jansen Poultry Equipment
- 17.11 ME International Installation GMBH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

