
Market Overview:
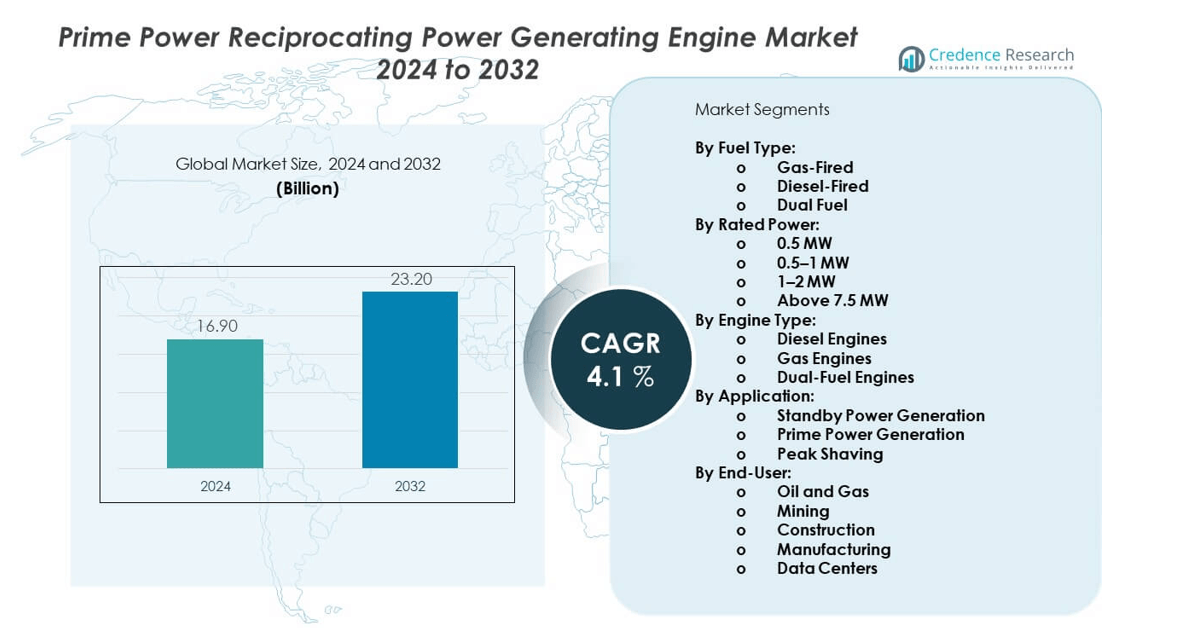
The prime power reciprocating power generating engine market is projected to grow from USD 16.9 billion in 2024 to USD 23.2 billion by 2032, reflecting a compound annual growth rate (CAGR) of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Prime Power Reciprocating Power Generating Engine Market Size 2024 | USD 16.9 billion |
| Prime Power Reciprocating Power Generating Engine Market, CAGR | 4.1% |
| Prime Power Reciprocating Power Generating Engine Market Size 2032 | USD 23.2billion |
The market is driven by several key factors including growing industrialization in emerging economies, rapid infrastructure expansion, and rising electricity consumption in developing regions. Enterprises are investing in prime power solutions to overcome grid instability and ensure operational continuity. Increasing focus on energy efficiency and adoption of engines with lower emissions further supports market expansion. The market also benefits from advances in fuel flexibility, with engines capable of operating on natural gas, diesel, or dual-fuel configurations, ensuring cost-effectiveness and environmental compliance.
Geographically, Asia-Pacific leads the prime power reciprocating power generating engine market, driven by strong electricity demand from industrial hubs and rapid urban growth in countries such as China, India, and Southeast Asia. North America and Europe remain important markets due to advanced infrastructure and stringent emission standards, pushing demand for efficient and clean prime power solutions. Meanwhile, Latin America and the Middle East & Africa are emerging as high-growth regions, supported by limited grid connectivity, high reliance on distributed generation, and increased investments in mining, oil, and gas sectors. This regional diversity underlines the global reliance on reciprocating engines for reliable prime power generation.
Market Insights:
- The prime power reciprocating power generating engine market is valued at USD 16.9 billion in 2024 and is projected to reach USD 23.2 billion by 2032, growing at a CAGR of 4.1%.
- Rising industrialization and urbanization increase demand for continuous and reliable prime power solutions across developing economies.
- Grid instability and frequent power outages drive adoption of reciprocating engines in off-grid and remote regions.
- High operating costs, fuel price volatility, and maintenance needs act as restraints on wider adoption.
- Strict emission regulations in North America and Europe challenge diesel-based engines but support a shift toward cleaner gas-based systems.
- Asia-Pacific leads the market due to industrial expansion and rural electrification, while Latin America and Africa emerge with rising distributed generation demand.
- North America and Europe remain important markets, shaped by technological advancements and sustainability-driven regulations.
Market Drivers:
Rising Energy Demand and Industrial Expansion:
The prime power reciprocating power generating engine market is supported by rising global energy demand, particularly in developing economies. Rapid industrialization across Asia and Africa creates strong requirements for continuous and reliable electricity supply. Industries such as manufacturing, mining, and oil and gas depend on prime power engines for stable operations in off-grid or unstable grid regions. Urbanization and the expansion of commercial hubs drive additional need for distributed generation. Governments in emerging markets are investing in infrastructure, which fuels higher electricity consumption. The versatility of reciprocating engines makes them suitable for different industries with varied energy needs. Rising production facilities in rural areas highlight the importance of dependable power solutions. This widespread adoption strengthens the role of these engines in ensuring uninterrupted electricity access.
- For instance, Caterpillar’s new C13D engine platform, launching production in 2026, offers power ratings from 340 to 515 kW and peak torque up to 3,200 Nm, making it suitable for heavy-duty off-highway applications such as mining and manufacturing operations in areas with unstable grids.
Grid Reliability Issues and Off-Grid Applications:
Frequent power outages and grid instability are key growth drivers for the prime power reciprocating power generating engine market. Developing countries continue to face underdeveloped grid infrastructure, leading to heavy dependence on prime power systems. Off-grid regions, especially in remote or rural areas, rely on reciprocating engines as the primary energy source. Mining projects, construction sites, and oil exploration activities further require self-sufficient power systems. These sectors prioritize engines due to fast start-up capability and robust performance in harsh conditions. The technology ensures continuous operations without reliance on weak grid connections. Fuel flexibility also allows operators to adapt engines to available energy sources. It enables enterprises to maintain productivity and reduce downtime risks.
- For instance, Caterpillar’s engines are designed to start up quickly and perform robustly in harsh conditions, with the C13D platform able to use renewable fuels such as 100% hydrotreated vegetable oil (HVO), enhancing flexibility and reliability in areas with limited fuel options.
Growing Need for Reliable Power in Critical Infrastructure:
Healthcare, data centers, and telecom networks demand uninterrupted power supply, which strengthens adoption in the prime power reciprocating power generating engine market. Hospitals and emergency facilities require fail-safe power sources to protect lives and ensure critical medical functions. Data centers handle enormous volumes of digital information and cannot risk outages. Telecom towers and networks need prime power solutions in regions with unstable grids. Increasing digital connectivity amplifies electricity usage in communication systems. Enterprises choose reciprocating engines for their reliability and ability to run for long periods. Public sector projects also adopt them to support essential services. These critical infrastructure applications reinforce demand for advanced reciprocating power solutions.
Fuel Flexibility and Emission Reduction Capabilities:
The ability to operate on multiple fuels is a major driver of growth in the prime power reciprocating power generating engine market. Operators value the flexibility to switch between diesel, natural gas, and dual-fuel systems. This adaptability helps manage costs and enhances energy security. Rising pressure to reduce greenhouse gas emissions pushes demand for cleaner engine technologies. Manufacturers are designing engines with lower emissions while maintaining high efficiency. Stricter regulations in Europe and North America encourage adoption of advanced fuel options. Emerging economies are also shifting toward gas-based engines to reduce dependence on oil imports. Companies investing in hybrid fuel engines attract users looking for long-term sustainability. It ensures both compliance and operational cost efficiency for diverse industries.
Market Trends:
Digitalization and Integration of Smart Monitoring Systems:
The prime power reciprocating power generating engine market is witnessing strong adoption of digital technologies and smart monitoring solutions. Operators use remote monitoring tools to optimize performance and ensure predictive maintenance. Digital integration improves real-time performance analysis and reduces costly downtime. Internet of Things (IoT) applications enhance data collection and system management. Companies integrate automation and control systems to maximize operational efficiency. The adoption of advanced sensors strengthens maintenance schedules and reliability. Smart monitoring also supports compliance with emission norms through real-time tracking. Digitalization creates new growth opportunities by modernizing reciprocating engine operations globally.
- For instance, Caterpillar integrates remote monitoring and advanced diagnostics into its industrial engines, enabling predictive maintenance and minimizing downtime, supported by their global dealer network and aftermarket services extending engine lifecycles.
Hybrid Systems and Renewable Energy Integration:
Hybrid power systems are emerging as a prominent trend within the prime power reciprocating power generating engine market. Businesses combine reciprocating engines with renewable energy sources such as solar or wind to create stable hybrid systems. These setups provide both sustainability and reliability in energy generation. Hybrid models reduce reliance on fossil fuels while maintaining backup stability. Industries in remote regions benefit from pairing renewables with reciprocating engines for continuous power. Governments encourage adoption of hybrid energy systems with policy support. Manufacturers develop engines that seamlessly integrate with renewable energy grids. This trend aligns with global sustainability goals while maintaining operational resilience.
- For instance, Caterpillar showcased a new series hybrid power expansion powertrain that combines diesel engines with battery-electric systems, allowing zero-exhaust emissions operation on battery power and improved fuel consumption across heavy applications.
Modular and Scalable Engine Designs:
The demand for modular solutions is growing within the prime power reciprocating power generating engine market. Modular engine systems allow operators to scale capacity quickly as electricity demand rises. This flexibility attracts industries with fluctuating energy needs. Construction firms and remote industrial projects prefer scalable solutions due to cost efficiency. Modular designs also simplify installation and reduce commissioning time. Companies use modular systems to ensure faster deployment in critical projects. Flexibility in capacity helps organizations manage both short-term and long-term requirements. The trend of modularity strengthens the overall appeal of reciprocating power engines in diverse applications.
Advances in Noise and Vibration Reduction Technologies:
Manufacturers are focusing on noise and vibration control technologies in the prime power reciprocating power generating engine market. Urban and commercial applications require engines that meet stringent noise regulations. Advances in engine housing and damping systems reduce environmental impact. Quieter operations enable broader use in populated regions without community resistance. Vibration reduction also extends equipment life and lowers maintenance costs. Companies invest in engineering solutions that balance efficiency with reduced noise emissions. Noise-controlled systems strengthen adoption in offices, hospitals, and urban developments. This trend reflects the rising importance of environmental and community-friendly engine technologies.
Market Challenges Analysis:
High Operational Costs and Maintenance Needs:
The prime power reciprocating power generating engine market faces significant challenges from high operating costs and maintenance requirements. Engines consume large amounts of fuel, which can drive expenses for industrial users. Maintenance requires specialized skills and frequent checks, adding further costs. Small and medium-sized enterprises often hesitate to adopt due to limited budgets. Fuel price fluctuations create additional uncertainty for long-term operations. Availability of skilled technicians in remote areas also limits adoption. Downtime during repairs can affect productivity in critical applications. It makes cost optimization a pressing challenge for widespread deployment.
Emission Regulations and Competition from Alternatives:
The prime power reciprocating power generating engine market also struggles with stricter emission standards and rising competition. Governments in developed regions enforce strict environmental policies that limit diesel engine adoption. Companies must invest heavily in emission-control technologies to meet compliance. This raises costs for manufacturers and end users. Alternatives such as gas turbines, fuel cells, and renewable systems present competitive threats. Their efficiency and cleaner performance attract environmentally focused buyers. Technological advances in renewables reduce reliance on reciprocating engines. It forces the market to evolve continuously to maintain competitiveness in cleaner energy landscapes.
Market Opportunities:
Rising Electrification in Emerging Economies:
The prime power reciprocating power generating engine market offers strong opportunities in rapidly electrifying economies. Countries in Asia and Africa continue expanding their industrial and residential power infrastructure. Growing populations and urbanization push electricity demand beyond grid capacity. Governments support distributed power systems to fill supply gaps. Reciprocating engines provide a quick, reliable, and scalable solution. Their use in construction, healthcare, and telecom strengthens adoption further. Companies entering these regions can capture untapped growth by offering advanced and efficient power solutions.
Expansion of Gas-Based and Dual-Fuel Engines:
The prime power reciprocating power generating engine market also benefits from opportunities in gas-based and dual-fuel engine adoption. Rising natural gas availability makes gas engines more attractive in cost-sensitive regions. Cleaner emissions help meet tightening regulations and sustainability goals. Dual-fuel systems enable flexibility in fuel sourcing and pricing. Industrial buyers prefer solutions that balance efficiency with lower environmental impact. Manufacturers developing hybrid-compatible and gas-based engines strengthen their global position. Emerging demand in urban hubs and industrial projects creates long-term growth opportunities for this market.
Market Segmentation Analysis:
By Fuel Type
In the prime power reciprocating power generating engine market, diesel-fired engines hold a strong position due to reliability in industrial and remote applications. Gas-fired engines are gaining share as industries prioritize lower emissions and natural gas availability expands. Dual-fuel engines attract users seeking flexibility to alternate between fuels, helping manage operational costs and ensure energy security.
- For instance, Caterpillar’s Stage V engine lineup includes diesel engines from 8 to 2100 hp, delivering more power and more torque while meeting strict emissions standards globally, illustrating balanced performance and environmental compliance.
By Rated Power
Engines in the 0.5–1 MW and 1–2 MW categories dominate installations across industrial and commercial facilities because of their efficiency and adaptability. Units above 7.5 MW serve large projects in oil, gas, and mining sectors that require continuous heavy-duty operations. Smaller engines below 0.5 MW find use in localized or temporary power generation where scalability is not critical.
- For example, Caterpillar’s modular 4-cylinder C2.8 and C3.6 engines deliver efficient power within these ranges while reducing installation complexity and operational costs, suited for varied industrial power needs.
By Engine Type
Diesel engines continue to lead the prime power reciprocating power generating engine market, supported by widespread availability and established infrastructure. Gas engines are expanding quickly in regions with stringent emission standards and strong natural gas networks. Dual-fuel engines meet demand from industries seeking versatile solutions that balance efficiency with environmental compliance.
By Application and End-User
Prime power generation is the leading application, fueled by demand in off-grid regions and areas with unreliable grids. Standby power generation plays a critical role in healthcare, commercial, and data center facilities, while peak shaving supports utilities and large industries during demand spikes. Among end-users, oil and gas, mining, and construction dominate due to high reliance on dependable onsite power. Manufacturing and data centers emerge as fast-growing segments, reflecting industrial modernization and rising digital infrastructure needs.
Segmentation:
- By Fuel Type:
- Gas-Fired
- Diesel-Fired
- Dual Fuel
- By Rated Power:
- 5 MW
- 5–1 MW
- 1–2 MW
- Above 7.5 MW
- By Engine Type:
- Diesel Engines
- Gas Engines
- Dual-Fuel Engines
- By Application:
- Standby Power Generation
- Prime Power Generation
- Peak Shaving
- By End-User:
- Oil and Gas
- Mining
- Construction
- Manufacturing
- Data Centers
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
- North America
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the prime power reciprocating power generating engine market at 38%. Strong industrial expansion, rapid urbanization, and growing rural electrification programs drive demand in China, India, and Southeast Asia. Mining, construction, and oil and gas projects in remote locations strengthen adoption of prime power systems. Governments in the region prioritize energy security, which fuels investments in distributed power solutions. The region benefits from rising demand for both diesel and gas engines to meet flexible requirements. It maintains dominance due to the scale of industrialization and the push for reliable power in fast-growing economies.
North America and Europe
North America accounts for 27% of the market, supported by high adoption across data centers, manufacturing, and critical infrastructure. Strong emphasis on emission compliance increases demand for gas-based and dual-fuel systems. The United States leads with extensive investments in digital infrastructure and standby power solutions. Europe captures 20% of the share, driven by strict environmental regulations and the shift toward sustainable energy generation. Demand in Europe is further supported by modernization of industrial infrastructure and the growth of hybrid systems integrating renewables. Both regions emphasize advanced technologies, digital monitoring, and efficiency improvements to align with policy frameworks.
Latin America and Middle East & Africa
Latin America contributes 8% of the prime power reciprocating power generating engine market, with Brazil and Mexico leading demand from industrial and commercial sectors. The Middle East & Africa account for 7%, with strong adoption in oil and gas projects, mining, and infrastructure development. These regions rely heavily on prime power solutions due to limited grid connectivity in rural and remote areas. Rising investments in energy and industrial projects fuel further growth in distributed generation. It demonstrates strong potential as industries expand and governments support power reliability initiatives. Market penetration continues to increase as operators seek efficient, scalable, and flexible power solutions.
Key Player Analysis:
- Caterpillar Inc.
- Cummins Inc.
- Mitsubishi Heavy Industries Ltd.
- Honda Motor Co. Ltd.
- AB Volvo Penta
- Rolls-Royce Holdings plc
- Kohler Co.
- Wärtsilä Corporation
- MTU Friedrichshafen GmbH
- DEUTZ AG
Competitive Analysis:
The prime power reciprocating power generating engine market is highly competitive, with global players and regional manufacturers focusing on performance, reliability, and compliance. Leading companies such as Caterpillar, Cummins, Wärtsilä, and Rolls-Royce dominate through diverse product portfolios and advanced technologies. It is shaped by innovations in gas and dual-fuel systems, addressing both efficiency and emission norms. Regional firms in Asia-Pacific, Latin America, and the Middle East target cost-sensitive buyers with compact and robust solutions. Market leaders invest heavily in R&D to enhance engine efficiency, digital monitoring, and hybrid compatibility. Strategic partnerships and global distribution networks further strengthen competitive positions. New entrants face barriers from brand recognition, technology standards, and regulatory compliance, reinforcing the dominance of established players.
Recent Developments:
- Rolls-Royce Holdings plc, in early 2025, received European Commission approval for the joint acquisition and control of Rolls-Royce SMR Limited with CEZ Holdings. The acquisition supports research, development, and deployment of compact modular nuclear reactor technology as part of Rolls-Royce’s strategic initiatives toward low-carbon energy solutions.
- In June 2025, Mitsubishi Heavy Industries Ltd. signed a framework agreement for business collaboration with Elomatic Oy, a Finnish maritime engineering consulting firm. The partnership focuses on utilizing decarbonization and digital technologies to enhance maritime engineering services in Japan and Europe. Additionally, Mitsubishi Heavy Industries made a strategic investment in Infosys-led joint venture HIPUS to advance digital procurement processes in Japan, expanding its footprint in digital transformation (April-June 2025).
- Honda Motor Co. Ltd., in its May 2025 business briefing, outlined a strategic realignment emphasizing hybrid electric vehicles (HEVs) alongside electric vehicles (EVs), with a focus on applying intelligent technologies and enhancing competitiveness. Honda plans to strengthen its HEV lineup from 2027 onward while continuing to pursue electrification, particularly in markets like China through partnerships focused on next-generation advanced driver assistance systems (ADAS).
- In 2025, Caterpillar Inc. celebrated its centennial year with significant innovations showcased at CES 2025 and bauma Munich 2025. During CES, Caterpillar highlighted its investments in autonomy, connectivity, digital technologies, alternative fuels, and electrification aimed at tackling the energy transition and building the future jobsite. At bauma, the company exhibited new industrial engines compatible with renewable fuels such as hydrotreated vegetable oils (HVO), including new models like the C13D and C3.6, alongside demonstrations of a series hybrid power expansion powertrain and hydrogen engine testing, reinforcing its commitment to innovation and sustainability in power solutions (January-April 2025).
Market Concentration & Characteristics:
The prime power reciprocating power generating engine market demonstrates moderate-to-high concentration, with a few global leaders holding significant shares. It is defined by technology-driven competition, where efficiency, reliability, and emission compliance determine leadership. Established players benefit from scale, strong brand value, and global service networks. Regional manufacturers focus on affordability and adaptability to local fuel availability. Product innovation in hybrid integration, digital monitoring, and emission reduction shapes market differentiation. Strong competition drives continuous R&D investments, while compliance with regulatory frameworks remains a defining factor.
Report Coverage:
The research report offers an in-depth analysis based on fuel type, rated power, engine type, application, end-user, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for distributed power solutions will expand adoption across developing economies.
- Gas-based and dual-fuel engines will see accelerated uptake due to emission compliance.
- Hybrid systems integrating renewable energy will gain prominence in urban and industrial sectors.
- Digital monitoring and IoT integration will strengthen operational efficiency and predictive maintenance.
- Data centers and telecom infrastructure will emerge as critical end-users for prime power solutions.
- Large-scale industrial projects in mining and oil and gas will sustain demand for high-capacity engines.
- Emission standards will continue to drive innovation in cleaner and more efficient engines.
- Modular and scalable designs will increase adoption in construction and manufacturing sectors.
- Regional players will expand market presence by offering cost-effective and fuel-flexible systems.
- Global leaders will strengthen competitiveness through partnerships and expansion in emerging markets.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Industrialization and Urbanization in Emerging Economies
Rapid industrial growth and urban expansion in Asia-Pacific and Africa are increasing the need for reliable, continuous power, especially in regions where grid infrastructure is underdeveloped or unstable. This drives demand for prime power reciprocating engines to support manufacturing, mining, and construction activities.
Grid Instability and Off-Grid Power Needs
Frequent power outages and unreliable grid connections in developing regions make reciprocating engines essential for off-grid and remote applications. Industries such as mining, oil and gas, and construction rely on these engines to ensure operational continuity and productivity.
Fuel Flexibility and Emission Compliance
The ability of modern reciprocating engines to operate on diesel, natural gas, or dual-fuel configurations allows operators to manage costs and adapt to local fuel availability. Increasingly strict emission regulations, especially in North America and Europe, are accelerating the shift toward cleaner gas-based and dual-fuel systems.
Growth in Critical Infrastructure and Data Centers
Sectors like healthcare, telecom, and data centers require uninterrupted power for critical operations. The expansion of digital infrastructure and the need for reliable backup and prime power solutions are boosting adoption of reciprocating engines in these high-demand applications.
Advancements in Digital Monitoring and Hybrid Integration
The integration of IoT, remote monitoring, and hybrid systems with renewable energy sources is enhancing operational efficiency, predictive maintenance, and sustainability. These technological advancements are making reciprocating engines more attractive for modern, resilient power generation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Prime power reciprocating power generating engine market, and what is its projected size in 2032?
Which Prime power reciprocating power generating engine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Prime power reciprocating power generating engine market?
Who are the leading companies in the Prime power reciprocating power generating engine market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Oil and Gas
- 1.2.2 Mining
- 1.2.3 Construction
- 1.2.4 Manufacturing
- 1.2.5 Data Centers
- 1.3 By Fuel Type
- 1.3.1 Gas-Fired
- 1.3.2 Diesel-Fired
- 1.3.3 Dual Fuel
- 1.4 By Application
- 1.4.1 Standby Power Generation
- 1.4.2 Prime Power Generation
- 1.4.3 Peak Shaving
- 1.5 By Rated Power
- 1.5.1 Below 0.5 MW
- 1.5.2 0.5–1 MW
- 1.5.3 1–2 MW
- 1.5.4 Above 7.5 MW
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16.9 billion → 2032: USD 23.2 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Prime Power Reciprocating Power Generating Engine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Prime Power Reciprocating Power Generating Engine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Prime Power Reciprocating Power Generating Engine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Prime Power Reciprocating Power Generating Engine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Prime Power Reciprocating Power Generating Engine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Prime Power Reciprocating Power Generating Engine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Prime Power Reciprocating Power Generating Engine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Prime Power Reciprocating Power Generating Engine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16.9 billion → 2032: USD 23.2 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Prime Power Reciprocating Power Generating Engine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oil and Gas
- 12.3.7.2 Mining
- 12.3.7.3 Construction
- 12.3.7.4 Manufacturing
- 12.3.7.5 Data Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gas-Fired
- 12.4.7.2 Diesel-Fired
- 12.4.7.3 Dual Fuel
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Standby Power Generation
- 12.5.7.2 Prime Power Generation
- 12.5.7.3 Peak Shaving
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Rated Power - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Below 0.5 MW
- 12.6.7.2 0.5–1 MW
- 12.6.7.3 1–2 MW
- 12.6.7.4 Above 7.5 MW
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Prime Power Reciprocating Power Generating Engine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Prime Power Reciprocating Power Generating Engine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Prime Power Reciprocating Power Generating Engine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Prime Power Reciprocating Power Generating Engine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cummins Inc.
- 18.4 Mitsubishi Heavy Industries Ltd.
- 18.5 Honda Motor Co. Ltd.
- 18.6 AB Volvo Penta
- 18.7 Rolls-Royce Holdings plc
- 18.8 Kohler Co.
- 18.9 Wärtsilä Corporation
- 18.10 MTU Friedrichshafen GmbH
- 18.11 DEUTZ AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

