
Propylene Glycol Market Overview:
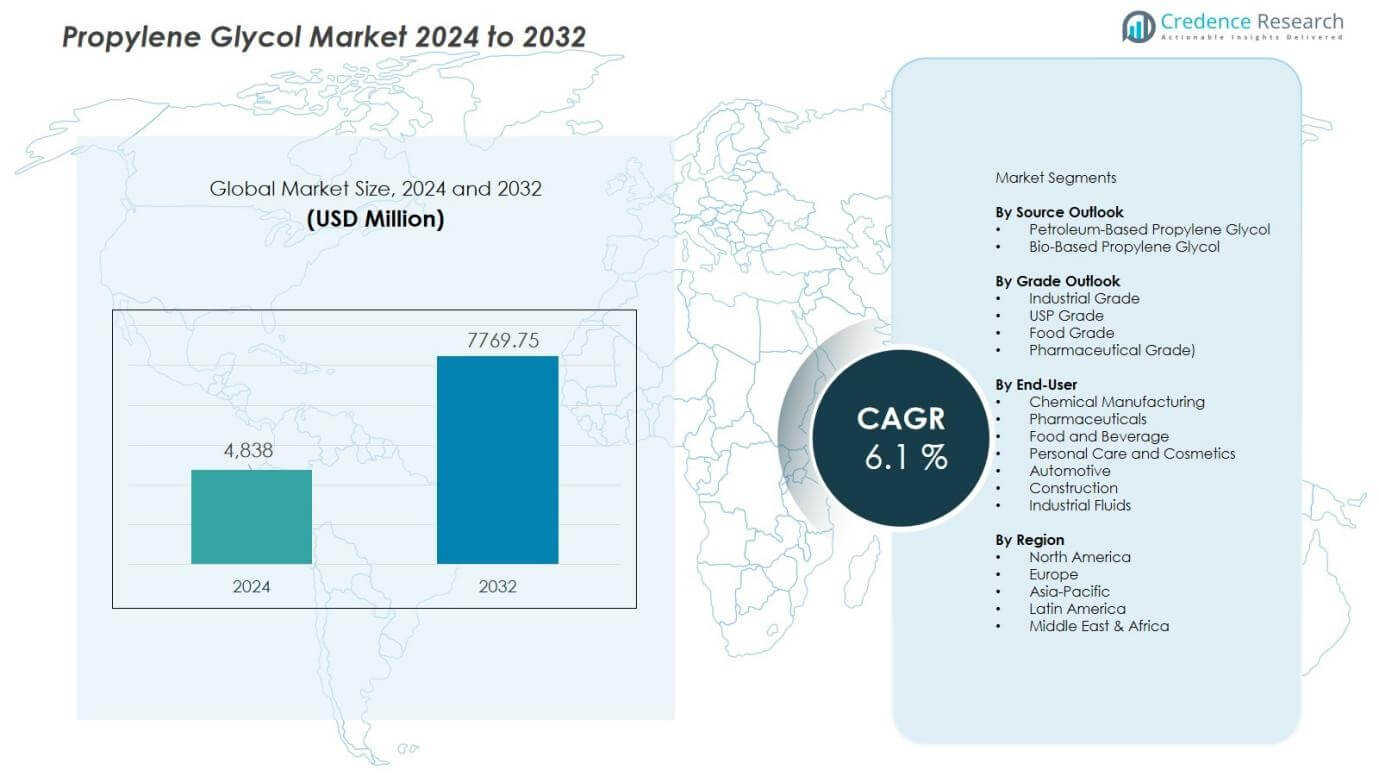
The Propylene Glycol Market size was valued at USD 4,838 million in 2024 and is anticipated to reach USD 7769.75 million by 2032, at a CAGR of 6.1 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Propylene Glycol Market Size 2024 | USD 4,838 million |
| Propylene Glycol Market, CAGR | 6.1 % |
| Propylene Glycol Market Size 2032 | USD 7769.75 million |
Propylene Glycol Market Insights:
- Asia-Pacific holds ~42% share, North America ~27%, and Europe ~21%, driven by large-scale industrial manufacturing in Asia-Pacific, high-purity pharmaceutical and food demand in North America, and sustainability-focused specialty applications in Europe.
- Asia-Pacific also represents the fastest-growing region with ~42% share, supported by rapid industrialization, expanding construction and coatings activity, and rising automotive and personal care production in China, India, and Southeast Asia.
- By end-user, unsaturated polyester resins account for ~38% share, while pharmaceuticals and personal care contribute ~26%, reflecting strong use in composites, coatings, drug formulations, and cosmetic products.
- By source and grade, petroleum-based propylene glycol holds ~68% share, while USP, food, and pharmaceutical grades together represent ~34%, supported by strict regulatory standards and growing preference for high-purity, low-toxicity formulations.
Propylene Glycol Market Drivers:
Expanding Demand from Unsaturated Polyester Resins and Industrial Composites
The Propylene Glycol Market benefits from strong demand in unsaturated polyester resins used across construction, marine, and automotive applications. Manufacturers rely on this chemical for consistent performance, durability, and formulation control in composite materials. Infrastructure investment and lightweight material adoption sustain procurement volumes. It supports resin producers that seek stable supply and predictable quality parameters.
- For instance, SABIC developed LNP™ ELCRES™ resin, a polycarbonate-based copolymer that outperforms glass reinforced nylon in PV connector bodies for 1.5 kV solar systems, earning the 2023 R&D 100 Award in Mechanical/Materials.
Rising Utilization Across Pharmaceutical, Food, and Personal Care Sectors
The Propylene Glycol Market gains momentum from wide acceptance in pharmaceuticals, food, and personal care due to favorable toxicity and solvent profiles. Drug formulations, oral liquids, and topical products depend on it for stability and uniformity. Food processors value it for moisture control and texture preservation. It aligns with regulatory frameworks that prioritize consumer safety and formulation transparency.
Growth in Automotive Fluids, Antifreeze, and De-icing Applications
The Propylene Glycol Market advances through steady demand from automotive coolants, heat transfer fluids, and de-icing solutions. Automotive production and maintenance cycles support recurring consumption across regions with temperature variability. Industrial facilities favor it for low volatility and controlled thermal behavior. It enables safer alternatives where ethylene glycol restrictions apply.
- For instance, Dow Chemical developed a propylene glycol-based coolant formulation that achieves a freezing point of -34°C in a 50/50 water mix, outperforming ethylene glycol alternatives in toxicity reduction while maintaining equivalent thermal stability.
Shift Toward Bio-Based and Low-Toxicity Chemical Solutions
The Propylene Glycol Market receives support from sustainability strategies and interest in bio-based chemical pathways. Producers invest in renewable feedstocks to meet corporate and regulatory objectives. End users prefer formulations with reduced environmental impact and clear compliance credentials. It strengthens supplier differentiation and long-term contract stability across regulated industries.
Propylene Glycol Market Trends:
Acceleration of Bio-Based Production Routes and Sustainability-Oriented Supply Chains
The Propylene Glycol Market shows a clear trend toward bio-based production routes that rely on renewable feedstocks such as glycerin. Manufacturers invest in fermentation and catalytic processes to reduce carbon intensity and improve lifecycle metrics. Regulatory pressure and corporate sustainability goals encourage procurement teams to favor low-toxicity and renewable alternatives. It supports compliance with food, pharmaceutical, and personal care standards that emphasize safety and traceability. Long-term supply contracts increasingly include sustainability clauses and emissions disclosures. Producers also strengthen backward integration to secure feedstock stability and cost control.
- For instance, BASF employs a proprietary copper catalyst in its G2PG process for hydrogenolysis of glycerin at 175-195°C, achieving very high conversion rates in two serial fixed bed reactors.
Premiumization Through High-Purity Grades and Application-Specific Customization
The Propylene Glycol Market continues to shift toward higher-purity grades tailored for pharmaceuticals, cosmetics, and food applications. End users demand tighter specifications, consistent performance, and validated quality systems. Suppliers respond with dedicated production lines and enhanced quality assurance protocols. It enables differentiation through value-added grades rather than volume expansion alone. Digital quality monitoring and batch traceability gain traction across regulated industries. Pricing strategies reflect purity, compliance, and reliability rather than commodity benchmarks.
- For instance, LyondellBasell offers pharmaceutical-grade propylene glycol achieving less than 1 ppm heavy metal content through GMP-compliant processes. It enables differentiation through value-added grades rather than volume expansion alone.
Propylene Glycol Market Challenges Analysis:
Volatility in Feedstock Pricing and Supply Chain Exposure Across Petrochemical Inputs
The Propylene Glycol Market faces pressure from volatility in propylene and glycerin feedstock pricing. Crude oil fluctuations influence cost structures and reduce margin visibility for producers. Supply chain disruptions affect procurement planning and inventory management. It complicates long-term pricing agreements with downstream customers. Regional dependency on imports raises exposure to logistics risk. Producers must balance cost control with consistent product availability.
Regulatory Compliance Complexity and Competition from Alternative Chemical Substitutes
The Propylene Glycol Market encounters challenges from complex regulatory frameworks across food, pharmaceutical, and industrial segments. Compliance demands raise operational costs and extend approval timelines. It requires continuous investment in testing, documentation, and quality systems. Competition from ethylene glycol substitutes and emerging bio-solvents intensifies price pressure. End users evaluate alternatives based on performance and cost parity. Producers must defend value through purity, safety, and reliability.
Propylene Glycol Market Opportunities:
Expansion of Bio-Based Production Capacity and Renewable Feedstock Adoption
The Propylene Glycol Market presents strong opportunities through expansion of bio-based production capacity. Manufacturers invest in renewable glycerin routes to meet sustainability targets. Regulatory support favors low-toxicity and environmentally aligned chemicals. It enables differentiation in food, pharmaceutical, and personal care applications. Buyers value traceable supply chains and reduced carbon profiles. Premium pricing becomes feasible for certified renewable grades.
Rising Demand from High-Growth End-Use Industries and Specialty Applications
The Propylene Glycol Market benefits from rising demand across pharmaceuticals, cosmetics, and advanced industrial fluids. Urbanization and healthcare expansion support steady volume growth. It fits well in formulations that require safety, stability, and performance consistency. Specialty grades open access to niche, high-margin applications. Emerging economies increase consumption across construction and automotive sectors. Producers can strengthen market presence through localized production and tailored product portfolios.
Propylene Glycol Market Segmentation Analysis:
By Source Outlook
The Propylene Glycol Market shows clear differentiation between petroleum-based and bio-based sources. Petroleum-derived propylene glycol holds a dominant share due to established infrastructure, cost efficiency, and large-scale availability. Bio-based variants gain traction as sustainability targets influence procurement decisions across regulated industries. It benefits from renewable glycerin feedstocks and favorable environmental profiles. Producers focus on balancing cost competitiveness with sustainability credentials. Long-term growth supports gradual share expansion for bio-based sources.
- For instance, Archer Daniels Midland (ADM) utilizes PNNL-developed catalysts to convert glycerol to propylene glycol, boosting conversion rates from 40-60% to over 90% in scaled operations.
By Grade Outlook
The Propylene Glycol Market segments strongly by grade, with industrial grade and USP/food/pharma grade as key categories. Industrial grade supports antifreeze, de-icing fluids, and unsaturated polyester resin applications. USP and food-grade material serves pharmaceuticals, cosmetics, and food processing due to strict purity requirements. It demands validated quality systems and regulatory compliance. Higher-grade products command premium pricing through consistency and safety assurance. Demand growth favors high-purity grades across regulated end uses.
- For Instance, Archer Daniels Midland (ADM) produces bio-based USP-grade propylene glycol, marketed as EVO-100™, which meets FCC, EP, and USP standards with a specified purity of greater than 99.5%.
By End-User Outlook
The Propylene Glycol Market serves diverse end users across chemicals, pharmaceuticals, food and beverage, personal care, automotive, and construction sectors. Chemical manufacturing and resins account for substantial volume consumption. Pharmaceuticals and personal care drive value growth through higher margins and stable demand cycles. It supports formulation stability and safety in sensitive applications. Automotive and industrial fluids maintain steady baseline demand. End-user diversification reduces exposure to single-sector volatility.
Segmentations:
By Source Outlook
- Petroleum-Based Propylene Glycol
- Bio-Based Propylene Glycol
By Grade Outlook
- Industrial Grade
- USP Grade
- Food Grade
- Pharmaceutical Grade
By End-User
- Chemical Manufacturing
- Pharmaceuticals
- Food and Beverage
- Personal Care and Cosmetics
- Automotive
- Construction
- Industrial Fluids
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Leadership Driven by Industrial Expansion and Manufacturing Scale
The Propylene Glycol Market in Asia-Pacific holds the largest share due to strong industrial expansion. China, India, and Southeast Asia support high consumption across resins, automotive fluids, and construction materials. Large manufacturing bases ensure steady demand and competitive production economics. It benefits from expanding pharmaceutical and personal care industries in urban centers. Government support for chemicals manufacturing improves capacity utilization. Rising infrastructure investment sustains long-term regional consumption.
North America Strength Supported by High-Purity Demand and Regulatory Compliance
The Propylene Glycol Market in North America reflects stable growth supported by pharmaceuticals and food processing. The United States drives demand through strict quality standards and premium-grade usage. Producers focus on USP and food-grade material for regulated applications. It aligns with safety-focused formulations and traceable supply chains. Automotive and industrial fluids provide consistent baseline demand. Innovation and contract manufacturing reinforce regional stability.
Europe Growth Anchored by Sustainability Focus and Specialty Applications
The Propylene Glycol Market in Europe benefits from strong emphasis on sustainability and chemical safety. Regulatory frameworks favor low-toxicity and renewable chemical inputs. Manufacturers increase adoption across cosmetics, pharmaceuticals, and specialty industrial uses. It supports demand for bio-based and high-purity grades. Germany, France, and the Nordic countries lead regional consumption. Mature end-user industries ensure predictable demand patterns.
Key Player Analysis:
- Dow
- BASF SE
- ADM
- INEOS
- Shell Plc
- Adeka Corporation
- Huntsman International LLC.
- LyondellBasell Industries Holdings B.V.
Competitive Analysis:
The Propylene Glycol Market features moderate concentration with a mix of global chemical majors and regional producers competing on scale, purity, and supply reliability. Leading players leverage integrated feedstock access and large production capacities to secure cost efficiency. It favors suppliers that maintain consistent quality across industrial and regulated grades. Competitive positioning depends on portfolio breadth, regulatory compliance, and long-term supply agreements with end users. Producers invest in process optimization and capacity upgrades to protect margins. Strategic focus also includes expansion of bio-based offerings to meet sustainability targets. Regional players compete through proximity to customers and flexible logistics. Price competition remains strong in industrial grades, while high-purity segments rely on differentiation through certification and traceability. Competitive strength increasingly reflects resilience, compliance discipline, and customer-specific solutions.
Recent Developments:
- In September 2025, BASF SE and Louis Dreyfus Company completed the sale of BASF's Food and Health Performance Ingredients business.
- In July 2025, Dow announced cuts to European operations, including job reductions, to improve profitability.
Report Coverage:
The research report offers an in-depth analysis based on Source Outlook, Grade Outlook, End-User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Propylene Glycol Market will benefit from sustained demand across pharmaceuticals, food processing, personal care, and industrial fluids, supported by its safety profile and functional versatility.
- Producers will continue to prioritize high-purity and application-specific grades to meet stricter regulatory and quality expectations in regulated industries.
- Bio-based production routes will gain wider acceptance as sustainability targets influence procurement strategies and supplier selection.
- End users will favor suppliers that offer traceable supply chains, consistent quality, and long-term contract stability.
- Growth in automotive, construction, and infrastructure activity will support steady consumption in antifreeze, heat transfer, and resin applications.
- Manufacturers will invest in process efficiency and capacity optimization to manage feedstock volatility and protect operating margins.
- Regional production expansion in Asia-Pacific will strengthen global supply availability and improve cost competitiveness.
- North America and Europe will emphasize compliance, certification, and premium formulations rather than volume expansion.
- Digital quality control and advanced monitoring systems will enhance batch consistency and customer confidence.
- Competitive advantage will increasingly depend on sustainability alignment, operational resilience, and the ability to serve diverse end-use requirements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Demand from Unsaturated Polyester Resins and Industrial Composites
Propylene glycol is a key input for unsaturated polyester resins used in construction, marine, and automotive composites, with infrastructure investment and lightweight material adoption driving sustained procurement and market growth.
Rising Utilization in Pharmaceuticals, Food, and Personal Care
Its favorable toxicity profile and solvent properties make propylene glycol essential in drug formulations, food processing, and cosmetics, supporting stable demand as regulatory standards and consumer safety expectations rise.
Growth in Automotive Fluids, Antifreeze, and De-icing Applications
Automotive and industrial sectors rely on propylene glycol for coolants, heat transfer fluids, and de-icing solutions, with recurring consumption supported by vehicle production, maintenance cycles, and the need for safer alternatives to ethylene glycol.
Shift Toward Bio-Based and Low-Toxicity Chemical Solutions
Sustainability initiatives and regulatory pressure are accelerating investment in bio-based propylene glycol production, enabling suppliers to differentiate through renewable feedstocks and appeal to environmentally conscious buyers in regulated industries.
Premiumization Through High-Purity Grades and Application-Specific Customization
Increasing demand for USP, food, and pharmaceutical grades is driven by stricter quality and safety requirements in sensitive applications, prompting suppliers to invest in dedicated production lines and quality assurance for higher-margin, value-added products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Propylene Glycol Market, and what value is expected by 2032?
What growth rate is expected for the Propylene Glycol Market during the forecast period?
Which segment accounted for the largest share of the Propylene Glycol Market in 2024?
What are the key factors driving growth in the Propylene Glycol Market?
Who are the major companies operating in the Propylene Glycol Market?
Which region dominated the Propylene Glycol Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Grade
- 1.2.1 Industrial Grade
- 1.2.2 USP Grade
- 1.2.3 Food Grade
- 1.2.4 Pharmaceutical Grade
- 1.3 By Source
- 1.3.1 Petroleum-Based Propylene Glycol
- 1.3.2 Bio-Based Propylene Glycol
- 1.4 By End-User
- 1.4.1 Chemical Manufacturing
- 1.4.2 Pharmaceuticals
- 1.4.3 Food and Beverage
- 1.4.4 Personal Care and Cosmetics
- 1.4.5 Automotive
- 1.4.6 Construction
- 1.4.7 Industrial Fluids
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,838 million → 2032: USD 7,769.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Propylene Glycol Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Propylene Glycol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Propylene Glycol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Propylene Glycol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Propylene Glycol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Propylene Glycol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Propylene Glycol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Propylene Glycol Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,838 million → 2032: USD 7,769.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Propylene Glycol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Grade - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Industrial Grade
- 12.3.7.2 USP Grade
- 12.3.7.3 Food Grade
- 12.3.7.4 Pharmaceutical Grade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Petroleum-Based Propylene Glycol
- 12.4.7.2 Bio-Based Propylene Glycol
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Chemical Manufacturing
- 12.5.7.2 Pharmaceuticals
- 12.5.7.3 Food and Beverage
- 12.5.7.4 Personal Care and Cosmetics
- 12.5.7.5 Automotive
- 12.5.7.6 Construction
- 12.5.7.7 Industrial Fluids
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Propylene Glycol End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Propylene Glycol Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Propylene Glycol Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Propylene Glycol Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dow
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 Archer Daniels Midland (ADM)
- 18.5 INEOS
- 18.6 Shell Plc
- 18.7 Adeka Corporation
- 18.8 Huntsman International LLC.
- 18.9 LyondellBasell Industries Holdings B.V.
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

