
Market Overview
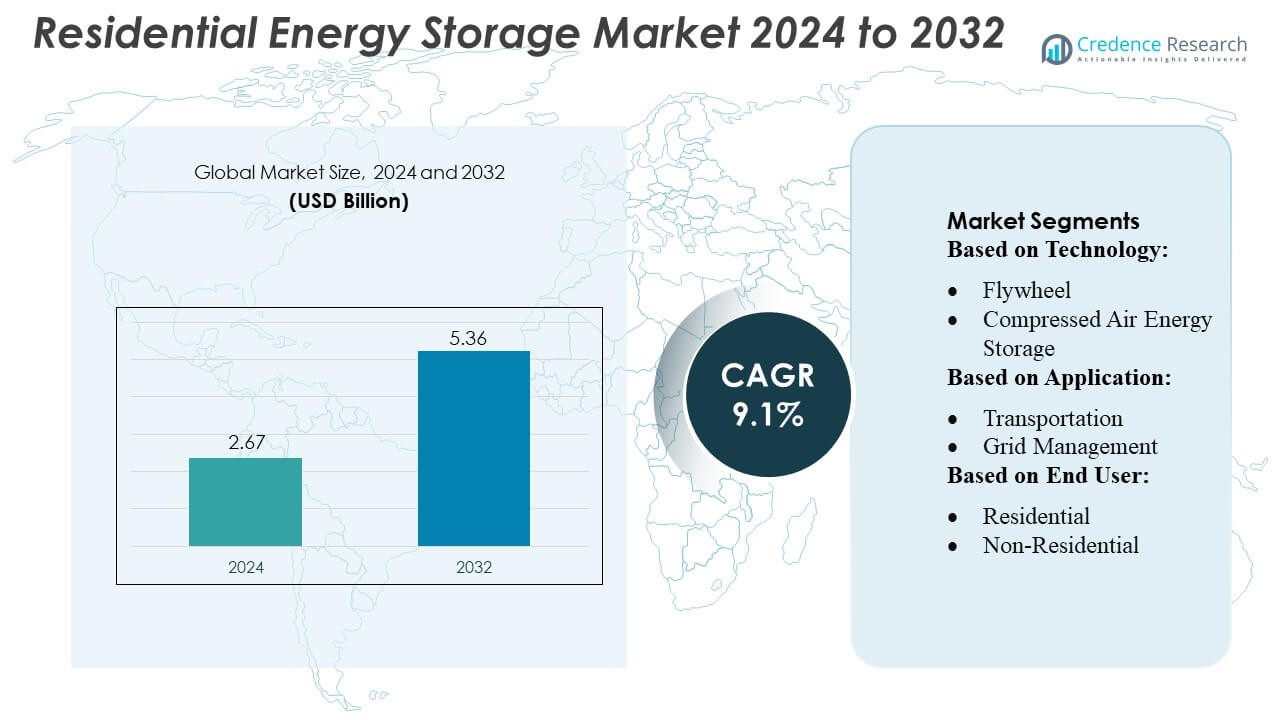
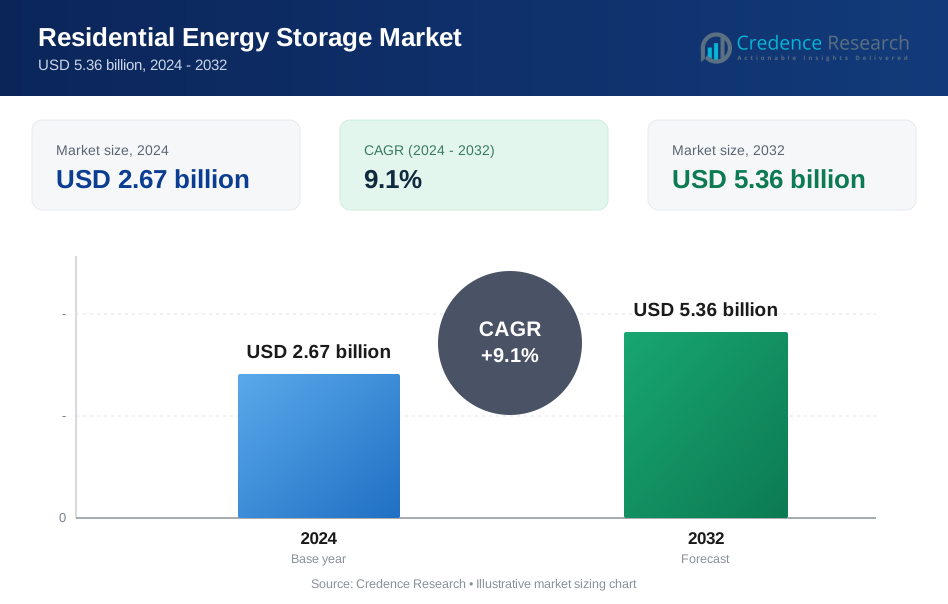
Residential Energy Storage Market size was valued USD 2.67 billion in 2024 and is anticipated to reach USD 5.36 billion by 2032, at a CAGR of 9.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Residential Energy Storage Market Size 2024 | USD 2.67 Billion |
| Residential Energy Storage Market, CAGR | 9.1% |
| Residential Energy Storage Market Size 2032 | USD 5.36 Billion |
The Residential Energy Storage Market is highly competitive, with key players including Showa Denko Materials Co., Ltd., Maxwell Technologies, Inc., The Furukawa Battery Co., Ltd., LG Chem, Langley Holdings plc, Electrovaya, GENERAL ELECTRIC, Ecoult, Saft, and Altairnano driving innovation and market growth. These companies focus on enhancing battery efficiency, lifecycle, and integration with solar PV and smart home systems, while expanding their regional presence through strategic partnerships and product diversification. North America leads the market, holding approximately 35% of the global share, driven by high solar PV adoption, supportive government incentives, and rising demand for energy resilience and backup power. Technological advancements, declining costs, and growing consumer awareness continue to strengthen North America’s leadership, while competitive strategies among global manufacturers shape the evolving landscape and accelerate adoption across Europe, Asia-Pacific, and other emerging regions.
Market Insights
- The Residential Energy Storage Market was valued at USD 2.67 billion in 2024 and is projected to reach USD 5.36 billion by 2032, growing at a CAGR of 9.1% during the forecast period.
- North America leads the market with approximately 35% share, supported by high solar PV adoption, government incentives, and growing demand for energy resilience and backup power. Europe and Asia-Pacific follow, with rising renewable energy integration and urbanization driving growth.
- Lithium-ion batteries dominate the technology segment, accounting for the largest share due to high efficiency, long lifecycle, and compatibility with residential solar systems. Electro-chemical and electro-mechanical technologies are gradually expanding in niche applications.
- Market growth is driven by declining battery costs, increasing residential solar installations, smart home integration, and incentives for peak shaving and energy cost optimization.
- High initial investment costs, safety concerns, and regulatory variations remain key restraints, while competitive strategies and innovation among leading players accelerate adoption across regions.
Market Segmentation Analysis:
By Technology
The Electro-Chemical segment, particularly Lithium-Ion batteries, dominates the residential energy storage market, capturing over 60% of the technology share. Lithium-ion’s high energy density, long lifecycle, and declining costs drive widespread adoption in residential setups. Other technologies like Lead Acid and Flow Batteries serve niche applications due to lower efficiency or higher maintenance needs. Emerging technologies such as Molten Salt and Phase Change Materials are gaining attention for long-duration storage, but the market preference remains with Lithium-Ion due to proven reliability, scalability, and compatibility with solar PV systems.
- For instance, The Furukawa Battery Co., Ltd. Under recommended conditions (25 °C, Depth-of-Discharge 70 %), the UB‑1000 model is rated for approximately 4,500 cycles, and the UB‑50‑12 model about 4,000 cycles.
By Application
Grid Management leads the application segment, accounting for approximately 55% of market share, as residential energy storage increasingly supports peak shaving, load balancing, and demand response programs. While Transportation applications, such as electric vehicle integration, are expanding, their penetration in residential systems remains limited. The growing adoption of smart grids and distributed energy resources further strengthens grid management’s prominence. Consumers are investing in storage solutions to enhance energy security, optimize electricity costs, and participate in utility-driven incentive programs, reinforcing grid management as the primary residential application.
- For instance, LG ESS Home 5 system (another variant) shows a nominal battery capacity of 15.8 kWh, with a usable capacity of 14.4 kWh under standard conditions.
By End User
The Residential end-user segment holds a dominant position, representing nearly 70% of the market. Increasing electricity costs, rising solar PV adoption, and government incentives for home energy storage drive residential deployment. Non-residential segments, including commercial and industrial users, are growing but still lag due to higher system complexity and cost. Utilities also deploy residential storage for distributed grid support, yet residential customers remain the core growth driver, leveraging energy autonomy, backup power, and cost savings. Technological advancements in compact, modular storage solutions further accelerate market penetration among homeowners.
Key Growth Drivers
Rising Adoption of Solar PV Systems
The rapid increase in residential solar photovoltaic (PV) installations is a major driver for energy storage adoption. Homeowners are increasingly investing in storage solutions to store excess solar energy, reduce reliance on the grid, and optimize electricity costs. Technological advancements in lithium-ion and other battery systems, coupled with government incentives and rebates, make storage systems more accessible. Integration with smart home energy management systems further enhances usability, driving market growth across both developed and emerging regions.
- For instance, GKN Hydrogen’s storage system has reportedly demonstrated over 7,000 charge/discharge cycles with 99% efficiency, and can preserve hydrogen stored in metal hydride “without degradation for up to 30 years.
Energy Cost Savings and Peak Shaving
Residential energy storage enables homeowners to reduce electricity bills through peak shaving and load shifting. Consumers can store energy during off-peak hours when electricity rates are lower and utilize it during peak periods, optimizing energy costs. Rising electricity tariffs and time-of-use pricing policies encourage adoption. Energy storage also allows homeowners to participate in demand response programs, creating additional economic benefits. These financial incentives and cost-optimization opportunities continue to accelerate the deployment of residential storage systems globally.
- For instance, Electrovaya achieved UL2580 certification for 448 distinct battery‑system models, covering 24 V, 36 V, and 48 V lithium‑ion systems.
Grid Resiliency and Backup Power
Increasing frequency of power outages and grid instability has heightened demand for residential energy storage as a reliable backup solution. Homeowners prioritize uninterrupted power supply during emergencies, natural disasters, or blackouts. Advanced storage systems provide stable electricity for critical household appliances while supporting grid resiliency. This driver is reinforced by growing awareness of climate change impacts and energy security concerns. Utilities are also promoting residential storage to enhance distributed grid reliability, further fueling market expansion.
Key Trends & Opportunities
Integration with Smart Home and IoT Systems
Residential energy storage is increasingly integrated with smart home and Internet of Things (IoT) technologies, enabling real-time energy monitoring and management. Homeowners can optimize consumption, remotely control battery usage, and automate storage operations. This trend enhances system efficiency and user convenience, creating new market opportunities. Partnerships between battery manufacturers, solar providers, and smart home technology companies are expected to expand, driving innovation and adoption.
- For instance, GE’s continuing investment in power conversion and storage integration. The 2025 data sheet shows that the FLEXINVERTER BESS solution supports up to 1,500 Vdc input, with DC‑input current capacity up to 4200 A (at 25 °C) and can output up to 4.4 MVA AC power in a standard 20‑ft ISO‑container format.
Declining Battery Costs and Technological Advancements
Continuous improvements in battery technology, particularly lithium-ion systems, and reductions in production costs are creating opportunities for widespread residential adoption. Enhanced energy density, longer lifecycle, and faster charging capabilities make systems more attractive to homeowners. Emerging technologies such as solid-state batteries and flow batteries are expected to further improve performance. Cost-effective solutions paired with government subsidies and financing options enable more households to adopt residential energy storage, expanding market potential.
- For instance, Ecoult UltraBattery-based systems have operated for over 20,000 cycles without significant loss of capacity under conditions involving frequent charging/discharging.
Emergence of Virtual Power Plants (VPPs)
Residential energy storage systems are increasingly leveraged in virtual power plant networks, aggregating distributed storage to support grid management. This presents opportunities for homeowners to monetize stored energy while contributing to grid stability. Utilities and energy service providers are promoting VPP participation through incentives and dynamic pricing schemes. The development of VPPs enhances the business case for residential storage, encouraging adoption and creating a scalable market ecosystem for both technology providers and consumers.
Key Challenges
High Initial Investment Costs
Despite declining battery prices, residential energy storage systems still require significant upfront investment, limiting adoption in price-sensitive markets. Costs for installation, maintenance, and integration with existing solar or grid infrastructure can be prohibitive for many households. Lack of awareness about financing schemes or incentives further constrains market penetration. Manufacturers and policymakers need to address affordability through cost reduction, leasing options, and targeted subsidies to expand adoption and overcome this barrier.
Technological and Safety Concerns
Battery safety, efficiency, and degradation remain critical challenges for residential energy storage systems. Issues such as thermal runaway, limited lifecycle, and energy losses can affect performance and user confidence. Additionally, integration with grid infrastructure and varying local regulations create technical complexities. Ongoing research, stringent safety standards, and reliable system monitoring are essential to address these concerns, ensuring consumer trust and fostering sustainable market growth.
Regional Analysis
North America
North America holds a dominant position in the residential energy storage market, capturing approximately 35% of global market share in 2024. Growth is fueled by widespread adoption of residential solar PV systems, supportive government incentives, and time-of-use electricity pricing. Homeowners increasingly deploy lithium-ion storage systems for peak shaving, backup power, and integration with smart home technologies. Frequent power outages and the need for energy resilience further boost demand. The U.S. leads the region, followed by Canada, with utilities and private consumers driving large-scale adoption. Technological advancements and declining battery costs continue to strengthen North America’s market leadership.
Europe
Europe accounts for roughly 28% of the global residential energy storage market, driven by renewable energy policies, financial incentives, and high electricity tariffs. Germany, the U.K., France, and the Netherlands lead adoption with extensive solar PV penetration and feed-in tariff programs. Lithium-ion batteries dominate due to energy efficiency and long lifecycle, while emerging technologies like flow and thermal batteries gain niche traction. Residential storage supports grid stability, peak shaving, and energy autonomy. Virtual power plant initiatives and smart energy management systems create additional growth opportunities, positioning Europe as a key regional market with strong regulatory support and technology adoption.
Asia-Pacific
Asia-Pacific represents about 25% of the global residential energy storage market, showing the fastest growth rate globally. Strong adoption in China, Japan, South Korea, and Australia is driven by urbanization, rising electricity demand, and supportive government policies promoting solar-plus-storage systems. Lithium-ion batteries dominate due to cost efficiency, reliability, and integration capabilities with residential solar PV. Storage solutions are increasingly used for energy independence, electric vehicle charging, and grid support. Declining battery costs, technological advancements, and favorable financing schemes further accelerate adoption, making Asia-Pacific a rapidly expanding market with significant long-term growth potential.
Latin America
Latin America contributes approximately 6% of the global residential energy storage market, with Brazil, Mexico, and Chile as key adopters. Market growth is propelled by rising electricity costs, unreliable grid infrastructure in remote areas, and renewable energy incentives. Residential storage systems are primarily used for backup power, load shifting, and energy cost optimization. Lithium-ion batteries are the preferred technology, while thermal and lead-acid solutions serve specific regional needs. Increasing awareness of energy efficiency and expanding solar PV penetration present significant growth opportunities, though adoption remains constrained by affordability and limited financing options in several countries.
Middle East & Africa
The Middle East & Africa region holds nearly 6% of global market share, with adoption concentrated in the UAE, Saudi Arabia, South Africa, and Egypt. Residential energy storage is driven by rising energy costs, intermittent grid supply, and government initiatives promoting renewable energy integration. Lithium-ion systems dominate, providing reliable backup power and supporting solar PV installations. Energy independence, demand for uninterrupted power, and favorable subsidies accelerate adoption. Despite infrastructural and cost challenges, residential storage deployment is expected to grow steadily, fueled by policy support, private investments, and increasing awareness of energy resilience and sustainability in both urban and off-grid areas.
Market Segmentations:
By Technology:
- Flywheel
- Compressed Air Energy Storage
By Application:
- Transportation
- Grid Management
By End User:
- Residential
- Non-Residential
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The residential energy storage market players such as Showa Denko Materials Co., Ltd., Maxwell Technologies, Inc., The Furukawa Battery Co., Ltd., LG Chem, Langley Holdings plc, Electrovaya, GENERAL ELECTRIC, Ecoult, Saft, and Altairnano. The residential energy storage market is highly competitive, characterized by rapid technological innovation, declining battery costs, and growing integration with residential solar PV systems. Companies compete on system efficiency, energy density, lifecycle performance, and compatibility with smart home and grid management solutions. Strategic initiatives such as partnerships, mergers, and product diversification are common to strengthen market presence and regional reach. Innovation in compact, modular, and scalable storage solutions is driving differentiation. Additionally, supportive government policies, subsidies, and energy incentive programs further intensify competition, compelling manufacturers to continuously improve performance, safety, and reliability to capture a larger share of the expanding residential energy storage market.
Key Player Analysis
- Showa Denko Materials Co., Ltd.
- Maxwell Technologies, Inc.
- The Furukawa Battery Co., Ltd.
- LG Chem
- Langley Holdings plc
- Electrovaya
- GENERAL ELECTRIC
- Ecoult
- Saft
- Altairnano
Recent Developments
- In May 2025, NTPC Green Energy (NGEL) launched an engineering, procurement, and construction (EPC) tender for a 250 MW/1,000 MWh battery energy storage system (BESS) at its Kayamkulam thermal plant in Kerala. The project aims to enhance grid stability by integrating a large-scale battery storage system, crucial for balancing intermittent renewable energy sources.
- In May 2025, CATL announced the TENER Stack, a 9MWh energy storage system designed to be more efficient, safer, and easier to transport than previous technologies. Key features include a 45% increase in volume utilization and a 50% boost in energy density compared to traditional systems, along with enhanced safety measures.
- In September 2024, Eaton and Tesla announced a collaboration to improve home energy systems by integrating Tesla's Powerwall with Eaton's AbleEdge™ smart breakers. This partnership aims to make it easier for homeowners and installers to implement intelligent load management, which optimizes energy use and extends backup power during grid outages.
- In June 2024, ABB has introduced the ReliaHome Smart Panel will empower homeowners to take control of their energy use by providing insights needed to save energy and costs. Developed in collaboration with software partner Lumin, this innovative solution streamlines the coordination of home energy assets, offering enhanced energy optimization, circuit scheduling, and real-time control capabilities.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of residential energy storage systems will continue to rise with growing solar PV installations.
- Advanced lithium-ion batteries and emerging technologies will drive efficiency and reliability improvements.
- Integration with smart home and IoT systems will enhance energy management and user convenience.
- Energy cost optimization and peak shaving will remain a major incentive for homeowners.
- Virtual power plants and grid-support programs will expand opportunities for residential storage.
- Declining battery costs will make storage systems more accessible to a wider range of consumers.
- Backup power and energy resilience will increasingly influence purchase decisions.
- Government incentives and renewable energy policies will continue to support market growth.
- Modular and scalable storage solutions will gain preference in diverse household setups.
- Regional adoption in Asia-Pacific, Latin America, and the Middle East will grow rapidly alongside North America and Europe.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Residential Solar PV Systems
The rapid increase in residential solar photovoltaic installations is fueling demand for energy storage, as homeowners seek to store excess solar energy, reduce grid reliance, and optimize electricity costs. Government incentives and technological advancements in battery systems further accelerate this trend.
Energy Cost Savings and Peak Shaving
Residential energy storage enables homeowners to shift energy use to off-peak hours and participate in demand response programs, reducing electricity bills and optimizing energy consumption. Rising electricity tariffs and time-of-use pricing policies make storage solutions increasingly attractive.
Grid Resiliency and Backup Power
Frequent power outages and grid instability are driving homeowners to invest in energy storage for reliable backup power. Advanced storage systems ensure uninterrupted electricity supply during emergencies, supporting both household needs and broader grid stability.
Integration with Smart Home and IoT Systems
The growing integration of energy storage with smart home and IoT technologies allows real-time energy monitoring, remote control, and automation, enhancing system efficiency and user convenience. This trend is expanding market opportunities and driving adoption.
Declining Battery Costs and Technological Advancements
Continuous improvements in battery technology, especially lithium-ion, and reductions in production costs are making residential energy storage more accessible. Enhanced energy density, longer lifecycles, and faster charging capabilities are increasing the appeal and feasibility of home storage systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Residential Energy Storage Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Residential Energy Storage Market projected to grow between 2025 and 2032?
Which Residential Energy Storage Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Residential Energy Storage Market?
Who are the leading companies in the Residential Energy Storage Market?
Which region commanded the largest share of the Residential Energy Storage Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Non-Residential
- 1.2.3 Utilities
- 1.3 By Technology
- 1.3.1 Lithium-Ion Batteries
- 1.3.2 Lead Acid Batteries
- 1.3.3 Flow Batteries
- 1.3.4 Molten Salt
- 1.3.5 Phase Change Materials
- 1.3.6 Flywheel
- 1.3.7 Compressed Air Energy Storage
- 1.4 By Application
- 1.4.1 Grid Management
- 1.4.2 Backup Power
- 1.4.3 Self-Consumption Optimization
- 1.4.4 Transportation
- 1.4.5 Virtual Power Plant Participation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.67 billion → 2032: USD 5.36 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Residential Energy Storage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Residential Energy Storage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Residential Energy Storage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Residential Energy Storage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Residential Energy Storage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Residential Energy Storage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Residential Energy Storage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Residential Energy Storage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.67 billion → 2032: USD 5.36 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Residential Energy Storage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Non-Residential
- 12.3.7.3 Utilities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lithium-Ion Batteries
- 12.4.7.2 Lead Acid Batteries
- 12.4.7.3 Flow Batteries
- 12.4.7.4 Molten Salt
- 12.4.7.5 Phase Change Materials
- 12.4.7.6 Flywheel
- 12.4.7.7 Compressed Air Energy Storage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Grid Management
- 12.5.7.2 Backup Power
- 12.5.7.3 Self-Consumption Optimization
- 12.5.7.4 Transportation
- 12.5.7.5 Virtual Power Plant Participation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Residential Energy Storage End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Residential Energy Storage Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Residential Energy Storage Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Residential Energy Storage Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Showa Denko Materials Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Maxwell Technologies, Inc.
- 18.4 The Furukawa Battery Co., Ltd.
- 18.5 LG Chem
- 18.6 Langley Holdings plc
- 18.7 Electrovaya
- 18.8 GENERAL ELECTRIC
- 18.9 Ecoult
- 18.10 Saft
- 18.11 Altairnano
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

