
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Satellite Communication Equipment Market Size 2024 | USD 31245 million |
| Satellite Communication Equipment Market, CAGR | 9.4% |
| Satellite Communication Equipment Market Size 2032 | USD 64109.01 million |
Market Overview:
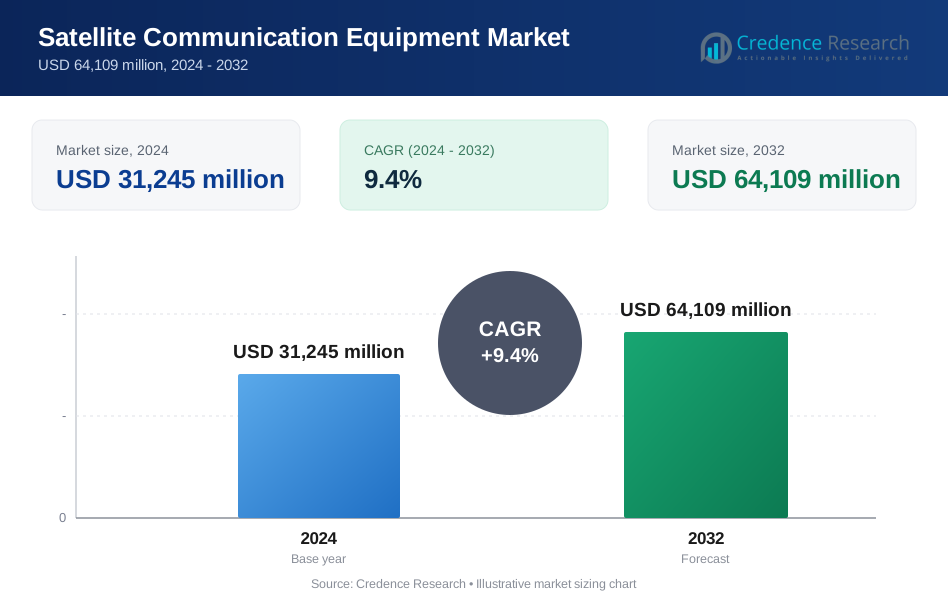
The Satellite Communication Equipment Market is projected to grow from USD 31245 million in 2024 to an estimated USD 64109.01 million by 2032, with a compound annual growth rate (CAGR) of 9.4% from 2024 to 2032.
The Satellite Communication Equipment Market is primarily driven by a growing demand for uninterrupted connectivity and communication capabilities in areas where traditional networks may be unreliable or unavailable. As remote work and digital transformations accelerate across industries, the need for reliable satellite-based communication is escalating. Additionally, governments and military organizations worldwide are increasing their investment in satellite technology to enhance defense communication systems, monitor territories, and boost intelligence-gathering capabilities. Furthermore, the expansion of over-the-top (OTT) streaming services and content providers, combined with the increasing adoption of Internet of Things (IoT) applications, has led to a surge in satellite data demand. These factors, coupled with innovations in satellite miniaturization and cost-effective satellite launches, are expected to drive continued market growth.
Regionally, North America holds a significant share in the Satellite Communication Equipment Market due to strong demand from sectors such as defense, aerospace, and telecommunications. The U.S., in particular, is a leading player, driven by both governmental investments and private sector innovation. Europe follows closely, with investments from prominent space agencies and private players contributing to market development. Meanwhile, the Asia-Pacific region is expected to exhibit the highest CAGR during the forecast period, fueled by increased investments in satellite technology by emerging economies like China, India, and Japan. These countries are enhancing their satellite infrastructure to support digital transformation efforts, IoT expansion, and national security objectives.
Market Drivers:
Increasing Demand for Connectivity in Remote and Underserved Areas:
One of the primary drivers of growth in the Satellite Communication Equipment Market is the escalating demand for connectivity in remote and underserved areas. Traditional communication infrastructures often struggle to reach these areas due to geographical and infrastructural challenges, resulting in a digital divide. Satellite communication technology offers an effective solution, providing reliable connectivity even in the most isolated regions. This has made satellite equipment indispensable for emergency response, disaster management, and remote area development. With the growing adoption of satellite broadband for remote work, e-learning, and telemedicine, the need for satellite communication equipment is expected to continue its upward trajectory.
Advancements in Satellite Technology and Cost Reduction:
Advancements in satellite technology, including the development of high-throughput satellites (HTS), small satellites, and low Earth orbit (LEO) constellations, are significantly driving the Satellite Communication Equipment Market. These innovations have improved the speed, capacity, and cost-effectiveness of satellite networks, making them more accessible and appealing to a wider array of industries. HTS, in particular, has enabled high-capacity data transmission, which is essential for applications in data-intensive sectors like telecommunications and streaming services. LEO satellites offer reduced latency, providing an internet experience comparable to that of traditional fiber networks. As the cost of satellite launches and equipment continues to decrease, the market is set to benefit from broader adoption across commercial and government sectors.
Rising Demand from Defense and Military Sectors:
The defense and military sectors play a critical role in the growth of the Satellite Communication Equipment Market. Governments worldwide are investing heavily in satellite technology to bolster national security, enhance intelligence gathering, and improve military communications. Satellite communication equipment offers secure, reliable, and real-time communication channels, which are crucial for operations in hostile or remote environments. For example, the demand for government and military satellite communication is expected to exceed 1 Tbps of throughput by 2030, up from 52 Gbps in 2020. As geopolitical tensions and security concerns rise, defense agencies increasingly rely on satellite networks for monitoring and surveillance purposes. Additionally, the need for precise navigation, data exchange, and battlefield coordination is driving demand for satellite communication equipment, further accelerating market growth.
Expansion of Internet of Things (IoT) and Machine-to-Machine (M2M) Communication:
The rapid expansion of the Internet of Things (IoT) and machine-to-machine (M2M) communication is another significant driver for the Satellite Communication Equipment Market. Industries such as agriculture, transportation, and logistics are adopting IoT solutions to enhance operational efficiency and monitor assets in real time. In remote areas where traditional cellular or broadband networks are unreliable, satellite communication provides a critical link for IoT applications. For instance, Analysys Mason reports that the number of satellite IoT connections is expected to grow significantly over the next decade. This trend is particularly evident in asset tracking, environmental monitoring, and fleet management, where satellite-enabled IoT solutions can offer continuous data flow from any location. As IoT usage grows globally, the demand for satellite communication equipment capable of supporting seamless M2M connectivity is expected to rise steadily, contributing to the long-term expansion of the market.
Market Trends:
Rising Adoption of Low Earth Orbit (LEO) Satellites:
A prominent trend in the Satellite Communication Equipment Market is the increasing adoption of low Earth orbit (LEO) satellites, driven by their advantages in latency reduction and enhanced data transmission speeds. Traditional geostationary satellites orbiting at higher altitudes have inherent latency issues, limiting their effectiveness for certain applications like real-time gaming, telemedicine, and live-streaming services. LEO satellites, on the other hand, operate at much closer distances, offering significantly lower latency and enabling more efficient data transmission. With major companies like SpaceX, Amazon, and OneWeb investing in LEO satellite constellations, the demand for compatible communication equipment is on the rise, pushing the market toward high-growth opportunities.
Growth in Satellite-Based Internet Services:
The expansion of satellite-based internet services is another key trend shaping the Satellite Communication Equipment Market. Satellite internet services are gaining popularity as they provide high-speed connectivity to remote, rural, and underserved communities. This is particularly important in regions where terrestrial internet infrastructure is limited or non-existent. For instance, notable players like SpaceX’s with its Starlink has already connected over 1.5 million users worldwide, offering speeds up to 150 Mbps. as well as upcoming players, are setting up extensive satellite networks to address the increasing demand for reliable internet access. As these services scale, demand for satellite communication equipment, including user terminals, transceivers, and ground stations, is expected to surge, making satellite internet an influential trend in the market.
Integration of Artificial Intelligence and Advanced Analytics:
The integration of artificial intelligence (AI) and advanced analytics into satellite communication systems is emerging as a transformative trend. AI-driven solutions enhance satellite performance by optimizing data transmission, predictive maintenance, and autonomous operation, thereby improving overall network efficiency and reducing operational costs. With advanced analytics, satellite operators can gain valuable insights into data patterns, network congestion, and user demand, enabling more precise decision-making. Furthermore, AI-powered algorithms support autonomous anomaly detection and fault management, enhancing system reliability and longevity. As AI applications in satellite communications grow, demand for AI-compatible equipment and technology is expected to bolster the Satellite Communication Equipment Market significantly.
Miniaturization and Cost-Effective Launch Solutions:
Miniaturization of satellite technology and the development of cost-effective launch solutions are propelling the market forward by making satellite deployments more feasible and affordable. Advances in small satellite technology, such as CubeSats, are reducing the size and cost of satellite communication equipment, allowing organizations with smaller budgets to access satellite-based solutions. Additionally, reusable launch vehicles developed by companies like SpaceX have lowered the cost of sending satellites into orbit, making satellite networks more accessible to various industries, including agriculture, logistics, and environmental monitoring. For instance, Planet Labs has successfully launched over 450 CubeSats, known as "Doves," which provide daily Earth imaging. This extensive deployment allows Planet Labs to offer high-frequency, high-resolution imagery at a lower cost compared to traditional satellite systems. This trend of miniaturization, coupled with affordable launch options, is expected to continue driving demand for innovative and compact satellite communication equipment, supporting further market growth and expansion.
Market Restraints and Challenges:
High Initial Costs and Capital Investment:
One of the key restraints in the Satellite Communication Equipment Market is the high initial cost and capital investment required for satellite deployment and infrastructure development. Setting up satellite communication networks involves substantial expenses, including costs for manufacturing, launching, and maintaining satellites. These costs can be prohibitive for smaller companies and limit market entry, particularly for firms in emerging economies. Although recent advancements, such as reusable launch vehicles, have reduced some expenses, the overall investment remains high, slowing market growth and adoption rates.
Regulatory Challenges and Spectrum Allocation:
Regulatory challenges and spectrum allocation issues pose significant obstacles to the growth of the Satellite Communication Equipment Market. The allocation of spectrum for satellite communication is highly regulated and often involves lengthy approval processes. This complex regulatory landscape varies significantly across regions, making it challenging for companies to deploy and operate satellite systems globally. Additionally, spectrum scarcity has led to increased competition for bandwidth, creating operational challenges and potential service limitations. These regulatory and spectrum-related constraints can delay deployment timelines and increase operational costs, impacting market expansion.
Vulnerability to Space Debris and Environmental Concerns:
Satellite communication systems face challenges related to space debris, which poses a risk to satellite longevity and operational safety. With an increasing number of satellites being launched, especially in low Earth orbit (LEO), the risk of collisions with space debris has intensified, potentially leading to equipment damage and service interruptions. Environmental concerns regarding satellite launches, such as carbon emissions, have also raised scrutiny and regulatory pressures. These factors contribute to operational risks and added maintenance costs, limiting the market’s potential and necessitating innovations in satellite design and debris management.
Market Segmentation Analysis:
The Satellite Communication Equipment Market is segmented by product, technology, platform, application, and end user, each serving varied demands across industries.
By Product, the market is divided into receivers, transmitters/transponders, transceivers, antennas, modems/routers, and others. Transceivers and antennas account for a significant share due to their critical role in data transmission, while modems/routers see high demand for reliable internet connectivity.
By Technology, the market includes VSAT (Very Small Aperture Terminal), telemetry, AIS (Automatic Identification System), on-the-move, and on-the-pause solutions. VSAT technology is widely used for satellite internet and communications in remote locations, while telemetry and AIS support tracking and data monitoring in maritime and military sectors.
By Platform, the market segments include portable equipment, land mobile equipment, maritime equipment, airborne equipment, and land fixed equipment. Each platform serves specific environments, with maritime and airborne equipment seeing increased demand in defense and commercial sectors for reliable, location-independent communication.
By Application, segments include navigation, scientific research, communication, remote sensing, and others. Communication applications dominate due to the rising need for seamless data transfer, while navigation and remote sensing are pivotal in environmental monitoring and defense.
By End User, the market caters to government, defense, and commercial sectors. Government and defense users require secure, robust communication networks for surveillance and tactical operations, while commercial users, particularly telecom and media companies, drive demand for satellite equipment to extend connectivity across remote and rural areas. Each segment highlights the market’s critical role in supporting diverse, data-intensive applications across industries.
Segmentation:
By Product
- Receiver
- Transmitter/Transponder
- Transceiver
- Antenna
- Modem/Router
- Others
By Technology
- VSAT
- Telemetry
- AIS
- on-the-Move
- on-the-Pause
By Platform
- Portable Equipment
- Land Mobile Equipment
- Maritime Equipment
- Airborne Equipment
- Land Fixed Equipment
By Application
- Navigation
- Scientific Research
- Communication
- Remote Sensing
- Others
By End User
- Government
- Defense
- Commercial
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is the leading region in the Satellite Communication Equipment Market, driven by strong demand from the defense, aerospace, and telecommunications sectors. The United States is at the forefront, supported by substantial government investments and a vibrant private sector with major players like SpaceX, Lockheed Martin, and Boeing. The region’s commitment to innovation, with a focus on advanced satellite technologies such as low Earth orbit (LEO) constellations, has fueled market growth. Additionally, North America’s emphasis on reliable communication networks for rural connectivity and disaster response has further increased the demand for satellite-based solutions.
Europe
Europe is a significant player in the Satellite Communication Equipment Market, supported by government-backed initiatives and investments from space agencies, particularly the European Space Agency (ESA). Leading countries, including the United Kingdom, France, and Germany, are driving advancements in satellite-based telecommunications, environmental monitoring, and navigation systems. The region’s focus on sustainable and secure satellite technologies, such as reusable rockets and efficient satellite launches, has supported growth in both civilian and defense applications. Europe’s rigorous regulatory landscape around spectrum allocation and data security also influences the development of reliable and secure satellite communication networks.
Asia-Pacific
Asia-Pacific is projected to be the fastest-growing region in the Satellite Communication Equipment Market, fueled by substantial investments in satellite infrastructure from countries like China, India, and Japan. China’s ambitious satellite programs and India’s cost-effective satellite launch capabilities have enhanced the region’s standing. The region’s increasing defense budgets and the demand for secure communication networks amid rising geopolitical concerns are also driving market growth. Moreover, the expansion of satellite-based applications in agriculture, disaster management, and IoT is creating additional growth opportunities in Asia-Pacific.
Latin America
Latin America, though a smaller segment of the Satellite Communication Equipment Market, is seeing increasing growth potential. The region’s demand for satellite communication is largely focused on improving digital access in rural and underserved areas, with Brazil and Mexico leading initiatives to expand connectivity. Additionally, satellite-based data is becoming essential in sectors like agriculture and mining. Latin America’s emphasis on economic development and infrastructure expansion is expected to drive further growth in satellite communication equipment in the coming years.
Middle East and Africa
The Middle East and Africa region is experiencing steady growth in the Satellite Communication Equipment Market, primarily driven by government investments in secure communication networks for defense and public services. In the Middle East, the focus on strengthening resilient communication infrastructure is influenced by regional security needs, while Africa is leveraging satellite communication to bridge connectivity gaps in remote areas. With increasing digital transformation initiatives across the continent, demand for reliable and affordable satellite-based solutions is anticipated to grow, supporting gradual market expansion in these regions.
Key Player Analysis:
- Airbus SE
- Antwerp Space
- Ball Aerospace & Technologies Corporation
- General Dynamics Corporation
- Harris Corporation
- Honeywell International Inc. and Other Players.
- Maxar Technologies
- Mitsubishi Electric Corporation
- Oxford Space Systems
- Space B.V.
Competitive Analysis:
The Satellite Communication Equipment Market is highly competitive, with numerous global and regional players striving to enhance their market positions through innovation and strategic collaborations. Key players, including SpaceX, Thales Group, Cobham, Viasat, and L3Harris Technologies, lead the market with comprehensive product portfolios and strong R&D investments. These companies are focused on developing advanced equipment that supports high-speed, low-latency communication, driven by the demand for LEO satellite constellations and cost-effective satellite launches. Competitive strategies in the market include mergers and acquisitions, partnerships, and technological innovations aimed at expanding service capabilities and geographic reach. Additionally, increasing emphasis on compact, lightweight, and energy-efficient equipment has intensified competition, as companies seek to meet diverse industry needs, from defense and government to commercial sectors. As demand for satellite communication continues to grow, competition is expected to increase, spurring further technological advancements and market expansion.
Recent Developments:
- In May 2023, Gilat Satellite Networks Ltd. received a multi-million-dollar order for VSATs to support the expansion of an advanced disaster response network in Asia. The VSATs are designed to enhance national disaster prevention and management efforts, enabling secure, bandwidth-efficient services, including voice, video, emergency alerts, and mobility services, to bolster government and first responder capabilities.
- Also, in May 2023, Viasat Inc. and Inmarsat received approval from the UK's Competition & Markets Authority (CMA) for their acquisition deal. Following an extensive Phase II review, the CMA determined that the merger would not raise competition concerns, allowing the deal to move forward without conditions. This acquisition, which has also received clearance from the UK government, Australia, and the U.S., will enhance Viasat’s competitive position, create high-skilled tech jobs, and advance the UK's National Space Strategy. Viasat’s CEO, Mark Dankberg, expressed gratitude for the CMA’s comprehensive review.
- In April 2023, ASELSAN completed delivery of SATCOM systems for the AKINCI Armed UAV, just six months after contracting with Turkey’s Presidency of Defence Industries. This SATCOM system enables AKINCI to communicate beyond Line of Sight (LOS), enhancing its cross-border operational capabilities.
- In March 2023, Cobham Satcom and SES signed a contract for Communications on the Pause (COTP) terminals supported by O3b mPOWER. This includes Cobham’s TACTICAL TRACKER series, suitable for LEO/MEO/GEO environments, and the EXPLORER 8120 tracking antenna. These terminals will support government and defense applications, as well as service restoration for government agencies and enterprise customers.
- In February 2023, Cobham Satcom was selected by Inmarsat Government to provide SAILOR XTR user terminals for the U.S. Navy Military Sealift Command’s (MSC) Next Generation Wideband service. This upgrade shifts MSC's primary afloat network from Ku-band VSAT to Global Xpress (GX) Ka-band, under a $578 million contract with the Defense Information Systems Agency.
Market Concentration & Characteristics:
The Satellite Communication Equipment Market is moderately concentrated, with a mix of large multinational corporations and specialized regional players. Major firms like SpaceX, Viasat, Thales Group, and Cobham dominate the market due to their extensive resources, advanced technological capabilities, and established distribution networks. These companies hold substantial market share, driven by their ability to invest in R&D and innovation, particularly in areas like low Earth orbit (LEO) satellites, high-throughput satellite systems, and energy-efficient equipment. The market is characterized by rapid technological advancements and a growing emphasis on cost efficiency and operational flexibility. Key features include a focus on miniaturization, reducing latency, and improving bandwidth to meet diverse industry needs, from government and defense applications to remote connectivity and IoT integration in the commercial sector. Although barriers to entry exist due to high initial costs and regulatory requirements, emerging players leveraging new technologies are increasing competition in specific niches.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Technology, By Platform, By Application and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expanding demand for high-speed satellite internet in remote and underserved regions will drive significant market growth.
- Increased deployment of low Earth orbit (LEO) satellites will reduce latency and improve data transmission capabilities.
- Advancements in satellite miniaturization and reusable launch technologies are expected to lower costs and expand market accessibility.
- Rising adoption of satellite-enabled Internet of Things (IoT) applications will boost demand for reliable satellite communication equipment.
- Government and defense sectors will continue to invest in secure satellite networks to support national security and surveillance.
- The commercial sector, including media and telecommunications, will drive market growth through increased demand for global connectivity.
- Enhanced integration of artificial intelligence (AI) will optimize satellite data management, predictive maintenance, and autonomous operations.
- Growing environmental concerns and space debris risks may encourage regulatory advancements and new solutions for sustainable satellite operations.
- Rapid digital transformation in emerging economies will accelerate satellite-based communication infrastructure investments.
- Increasing competition from new players and technological breakthroughs will spur innovation and push the market toward greater efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Satellite Communication Equipment Market by 2032?
What is the expected CAGR for the Satellite Communication Equipment Market from 2024 to 2032?
What factors are driving growth in the Satellite Communication Equipment Market?
Which regions hold the largest share in the Satellite Communication Equipment Market?
What challenges does the Satellite Communication Equipment Market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Satellite Communication Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Satellite Communication Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 31,245 million → 2032: USD 64,109 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Satellite Communication Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Satellite Communication Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Satellite Communication Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Satellite Communication Equipment Market Drivers
- 3.3 Satellite Communication Equipment Market Restraints & Challenges
- 3.4 Satellite Communication Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Satellite Communication Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Satellite Communication Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Satellite Communication Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Satellite Communication Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Satellite Communication Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Satellite Communication Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Satellite Communication Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Satellite Communication Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Satellite Communication Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Satellite Communication Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Satellite Communication Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Satellite Communication Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Satellite Communication Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Satellite Communication Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Satellite Communication Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Satellite Communication Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Satellite Communication Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Satellite Communication Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Satellite Communication Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
