
Market Overview:
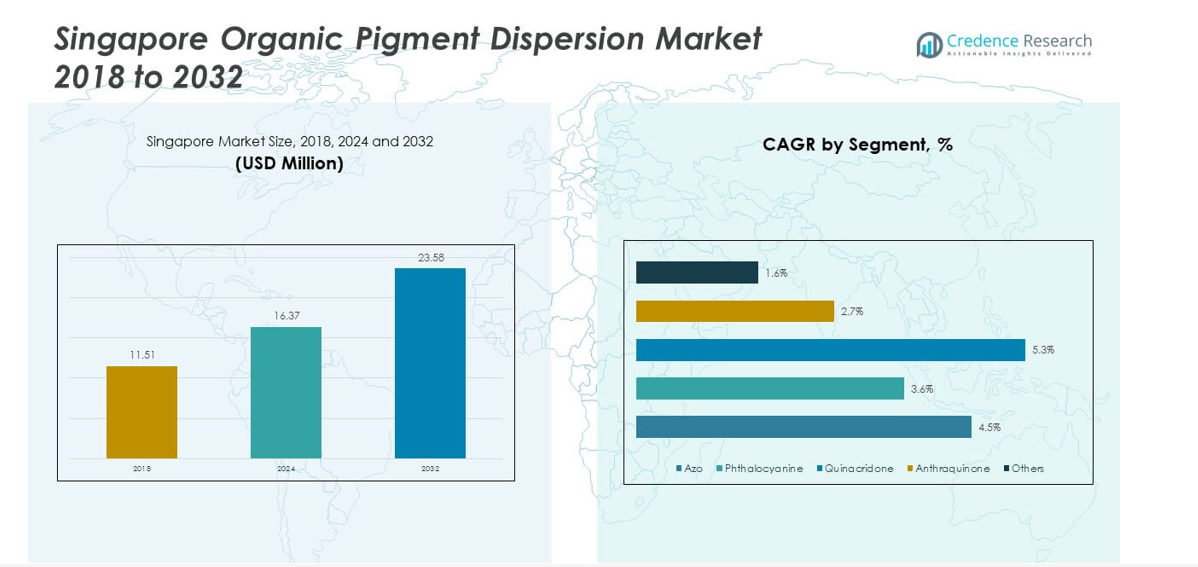
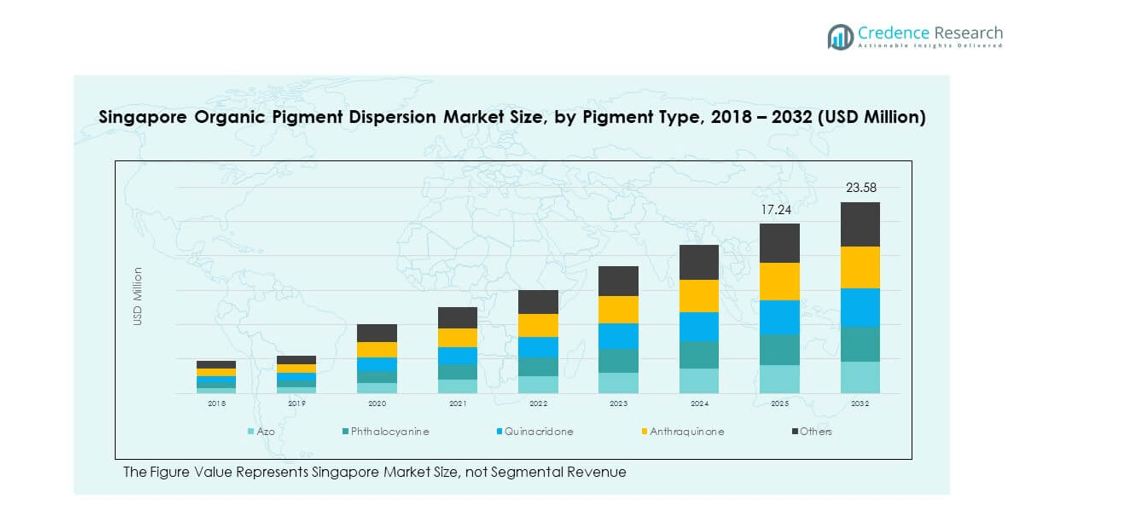
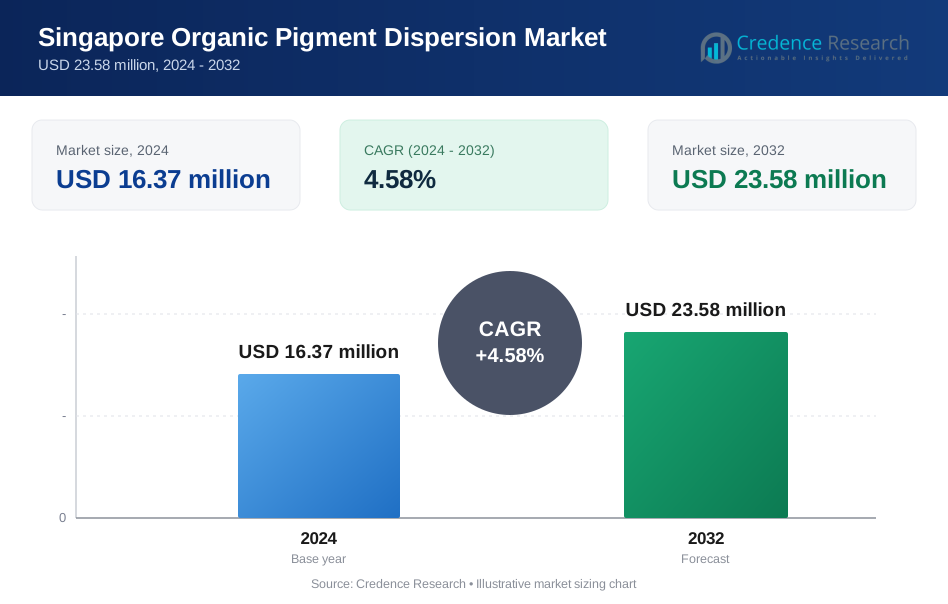
The Singapore Organic Pigment Dispersion Market size was valued at USD 11.51 million in 2018 to USD 16.37 million in 2024 and is anticipated to reach USD 23.58 million by 2032, at a CAGR of 4.58% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Singapore Organic Pigment Dispersion Market Size 2024 | USD 16.37 million |
| Singapore Organic Pigment Dispersion Market, CAGR | 4.58% |
| Singapore Organic Pigment Dispersion Market Size 2032 | USD 23.58 million |
Market drivers include the rising need for eco-friendly and high-performance pigments in printing, coatings, plastics, and textiles. Growing emphasis on sustainability encourages the adoption of dispersions that meet environmental standards and consumer expectations. Technological advancements in pigment formulations improve stability, durability, and color quality, making them suitable for high-end applications. Expanding demand from the packaging and automotive industries further strengthens the market outlook. Regulatory policies in Singapore also support safer and greener chemical use, which encourages investment in innovative dispersion technologies.
Geographically, Central Singapore remains the leading subregion due to its concentration of industrial, commercial, and trade activities. East and West Singapore follow with their strong industrial clusters in Jurong and Changi, driving logistics and production efficiency. North and North-East Singapore show rising importance as the government promotes decentralization of industrial development. These subregions benefit from growing textile, plastics, and specialty applications. Together, the geographic diversity creates a balanced and resilient market structure that strengthens Singapore’s role as a regional supply hub.
Market Insights
- The Singapore Organic Pigment Dispersion Market was valued at USD 11.51 million in 2018, reached USD 16.37 million in 2024, and is projected to attain USD 23.58 million by 2032, growing at a CAGR of 4.58%.
- Central Singapore accounted for 40% share in 2024, driven by its strong industrial base, advanced infrastructure, and concentration of commercial hubs, followed by East and West Singapore with 37% and North/North-East with 23%.
- North and North-East Singapore, with a 23% share, represent the fastest-growing region, supported by government-backed industrial decentralization and expansion in textiles and plastics.
- By pigment type, Azo pigments represented the largest share of over 35% in 2024, supported by their versatility and broad application in printing inks and coatings.
- Phthalocyanine pigments held close to 28% share, reflecting strong demand in paints, plastics, and packaging, while other pigment categories contributed smaller but steady shares across niche applications.
Market Drivers
Rising Demand for Eco-Friendly Pigments in Multiple Applications
The Singapore Organic Pigment Dispersion Market benefits from increasing demand for sustainable and non-toxic colorants across industries. Manufacturers in coatings, plastics, and inks are adopting eco-friendly pigment dispersions to align with environmental standards. Growing awareness among consumers about the harmful impact of synthetic pigments strengthens this adoption. It supports industries aiming to reduce volatile organic compound emissions in formulations. Water-based applications see strong growth as companies prefer safer and cleaner alternatives. This trend creates opportunities for product developers focused on green chemistry. Strict regional environmental regulations also accelerate market adoption. Rising investments in sustainable solutions strengthen long-term growth.
- For example, in June 2022, Clariant launched Dispersogen® Flex 100, a universal dispersing agent for organic and inorganic pigment preparations. It is low-VOC, label-free, and carries Clariant’s EcoTain® label, supporting sustainable water-based coatings and meeting global regulatory requirements.
Expansion of Advanced Coating and Packaging Applications
Growth in advanced coatings and packaging sectors fuels pigment dispersion adoption in Singapore. Packaging producers demand superior color strength, durability, and stability for diverse substrates. Organic pigment dispersions offer compatibility with water-based and solvent-based systems, making them versatile. The Singapore Organic Pigment Dispersion Market grows further with demand for high-quality printing inks used in premium packaging. It also gains momentum from the automotive industry, which requires durable pigments for coatings. Rising e-commerce activity drives packaging innovations and enhances pigment usage. The growing need for high-performance labeling solutions adds momentum. Market participants are investing in tailored products for these industries.
- For example, in October 2024, Heubach introduced Ultrazur® HGIN62-R and Ultrazur® HPRB01 pigment solutions at SEPAWA 2024. These products were presented as sustainable options for packaging and coatings, emphasizing high-quality color performance for industrial applications.
Technological Innovations Driving Product Performance and Efficiency
Research and development activities play a central role in shaping the pigment dispersion industry. Companies invest in advanced processing techniques that improve color uniformity and dispersion stability. Nanotechnology integration enhances pigment properties and broadens end-use applications. It enables higher efficiency and durability, especially in demanding industries such as automotive and electronics. The Singapore Organic Pigment Dispersion Market benefits from local innovation hubs fostering material science advancements. Collaboration between manufacturers and research institutes accelerates commercialization of new products. Custom formulations designed for specific industrial requirements enhance competitiveness. These innovations improve adoption rates and customer satisfaction.
Regulatory Support and Strategic Industrial Policies
The regulatory environment in Singapore favors adoption of environmentally safe pigment dispersions. Government policies encourage sustainable production and responsible chemical management. It creates a supportive landscape for manufacturers committed to compliance. Strong trade connections allow efficient import and export of pigment solutions to regional markets. The Singapore Organic Pigment Dispersion Market strengthens with government-backed sustainability initiatives in packaging and construction. Industrial policies promote innovation, green chemistry, and advanced materials. Local companies benefit from incentives encouraging clean technology integration. These factors make the market more resilient and growth-oriented.
Market Trends
Growing Adoption of Digital Printing and Customized Applications
Digital printing expansion supports organic pigment dispersion usage in specialized applications. Rising demand for personalized packaging and promotional materials enhances growth. It boosts adoption in textile printing, commercial signage, and labels. The Singapore Organic Pigment Dispersion Market aligns with this trend by supplying high-performance inks. Digital printing requires pigments with excellent dispersion stability and vibrant shades. Companies develop formulations to meet high-speed printing needs. This transformation encourages long-term industry engagement. Expanding consumer preference for customization amplifies demand.
Increasing Integration of Smart Manufacturing Practices
Smart manufacturing practices change pigment dispersion production efficiency. Automation and digital monitoring improve process consistency, reducing defects. It enhances supply chain efficiency by ensuring reliable product delivery. The Singapore Organic Pigment Dispersion Market incorporates these practices to optimize resource use. Predictive analytics help producers maintain consistent quality and lower waste. Companies employ real-time monitoring to manage complex formulations. Improved production systems support competitive pricing. This integration positions Singapore as a technologically advanced hub.
- For example, Chevron Oronite installed nearly 1,000 wireless IIoT sensors and devices at its Singapore lubricant additives plant. The system enables remote equipment data extraction, reduces manual fieldwork, improves asset efficiency, and saves significant man-hours annually.
Rising Popularity of Sustainable Textile and Fashion Applications
The textile sector witnesses rising adoption of organic pigment dispersions for eco-friendly fabrics. Fashion brands demand sustainable dyes that maintain durability and color vibrancy. The Singapore Organic Pigment Dispersion Market supports this shift through high-quality solutions. It provides dispersions compatible with water-based textile printing. The global fashion industry’s focus on sustainability drives higher adoption. Innovative pigments offer resistance to fading and enhanced softness. Collaborations with textile manufacturers create tailored solutions. Consumer preference for ethical fashion strengthens this trend further.
- For example, Lubrizol stated that its advanced high-stability dispersions are designed to improve printhead life and overall throughput in direct-to-film (DTF) printing, while supporting industry goals for more sustainable printing solutions.
Development of Specialty Pigments for Niche Applications
Manufacturers introduce specialty pigment dispersions for electronics, construction, and automotive applications. These pigments provide enhanced properties such as heat resistance and UV stability. It broadens the end-use scope beyond traditional industries. The Singapore Organic Pigment Dispersion Market benefits from rising niche demand. Specialty applications require high-performance dispersions tailored to specific technical needs. Producers develop advanced pigments for printed electronics and smart packaging. This trend highlights the versatility of organic pigment dispersions. Expansion into niche markets ensures long-term competitiveness.
Market Challenges Analysis
High Production Costs and Intense Global Competition
The Singapore Organic Pigment Dispersion Market faces rising production costs due to raw material fluctuations. Manufacturers invest heavily in R&D, which increases operational expenses. It challenges smaller players with limited resources to compete effectively. Intense global competition from low-cost producers in Asia creates pricing pressures. Singaporean manufacturers focus on quality and compliance, but high costs affect margins. Demand for low-priced alternatives puts strain on premium pigment suppliers. Companies must balance quality with affordability. Strategic alliances become essential to maintain market position.
Regulatory Compliance and Limited Local Manufacturing Scale
Strict environmental regulations demand continuous adaptation and compliance. The Singapore Organic Pigment Dispersion Market aligns with these rules, but the process adds costs. It requires specialized infrastructure, certifications, and audits to remain competitive. Limited scale of local manufacturing reduces economies of scale compared to larger markets. It creates dependency on imports, which exposes companies to trade fluctuations. Manufacturers face difficulties in scaling up production to meet growing demand. High compliance requirements also restrict new entrants. It limits innovation speed and increases industry consolidation.
Market Opportunities
Expanding Regional Trade and Export Potential Across Asia-Pacific
The Singapore Organic Pigment Dispersion Market holds strong potential for regional trade growth. It benefits from Singapore’s position as a strategic logistics hub. Strong connectivity with Asia-Pacific markets allows access to diverse industries. Demand for organic pigments in textiles, coatings, and packaging across the region supports export expansion. It also creates opportunities for Singaporean firms to develop regional partnerships. Trade agreements further facilitate cross-border market penetration. Rising demand from emerging economies boosts growth prospects. This dynamic enhances Singapore’s role as a supply leader.
Innovation in Sustainable Solutions and Customized Formulations
Ongoing demand for eco-friendly pigment solutions provides innovation opportunities. The Singapore Organic Pigment Dispersion Market benefits from R&D focused on green chemistry. It encourages companies to design dispersions tailored for specific applications. Sustainable formulations for textiles, packaging, and printing drive customer preference. Innovation in water-based dispersions meets regulatory and consumer requirements. Local firms invest in differentiated products to strengthen competitive edge. These advancements expand application scope across industries. Innovation becomes a central opportunity for sustained market growth.
Market Segmentation Analysis
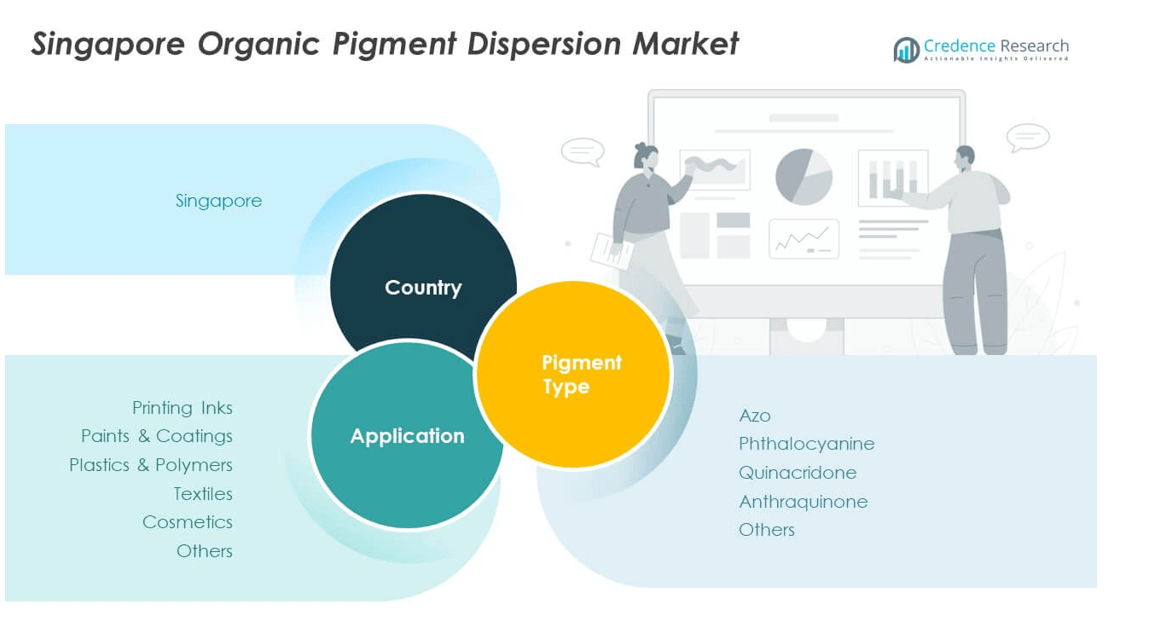
By pigment type, the Singapore Organic Pigment Dispersion Market is led by azo pigments due to their versatility, strong tinting strength, and cost-effectiveness. Phthalocyanine pigments hold a significant share for their stability, brightness, and use in coatings and printing applications. Quinacridone pigments support high-end uses in automotive and packaging where durability and color quality are critical. Anthraquinone pigments provide niche opportunities with their deep shades, while other pigment types serve specialty and emerging applications. It demonstrates balanced adoption across both mass-market and premium product categories.
- For example, DIC Corporation’s Sunbrite® Yellow 74 (Pigment Yellow 74) is a widely used azo pigment recommended for coatings and packaging inks. It offers high opacity along with strong acid and weather resistance and is supplied to the coatings industry in Asia, including Singapore.
By application, the Singapore Organic Pigment Dispersion Market shows printing inks as the leading segment, driven by growth in packaging, labeling, and digital printing. Paints and coatings follow closely with strong demand from construction and automotive industries. Plastics and polymers account for a growing share due to their use in consumer goods, packaging materials, and industrial components. Textiles represent an emerging opportunity as sustainable dyes gain acceptance in fashion and apparel. Cosmetics contribute steadily, supported by demand for safe and vibrant color formulations. Other applications include niche industries requiring specialized pigment dispersions. This application diversity strengthens the market’s overall growth potential.
- For example, Clariant’s Hostaperm® Red E5B is recognized for its high weatherfastness and strong color durability in automotive and industrial coatings.
Segmentation
By Pigment Type
- Azo
- Phthalocyanine
- Quinacridone
- Anthraquinone
- Others
By Application
- Printing Inks
- Paints & Coatings
- Plastics & Polymers
- Textiles
- Cosmetics
- Others
Regional Analysis
Central Singapore holds 40% share of the Singapore Organic Pigment Dispersion Market. This subregion is home to the largest concentration of manufacturing and commercial activities. It benefits from strong infrastructure, access to research hubs, and proximity to port facilities. It also serves as the base for many multinational headquarters driving trade of pigment dispersions. The cluster of advanced printing, packaging, and coatings companies ensures strong demand. Strategic connectivity strengthens export-oriented production. Central Singapore remains the leading hub for innovation and trade.
East and West Singapore together account for 37% of the market share. Industrial estates in Jurong and Changi play a key role in production and logistics. The Singapore Organic Pigment Dispersion Market benefits from their integration with petrochemical, plastics, and specialty chemical clusters. It supports pigment dispersion supply for coatings, automotive, and construction applications. Efficient transport links in these regions ensure timely distribution across domestic and regional markets. Industrial diversity in these subregions creates consistent demand. Local partnerships enhance value-added opportunities.
North and North-East Singapore represent 23% of the market. These subregions are expanding through small-to-medium scale manufacturers and growing research collaborations. It reflects the government’s push to decentralize industries and support innovation beyond the central hub. The Singapore Organic Pigment Dispersion Market in this area gains momentum from emerging textile and plastics applications. Residential and industrial balance fosters sustainable development. Strong logistics infrastructure supports distribution from this base to other subregions. Growing industrial parks continue to attract investment into pigment-related industries.
Key Player Analysis
- BASF SE
- Sudarshan Chemical
- DIC Corporation
- Cabot Corporation
- Heubach GmbH
- Penn Colors
- Pidilite Industries
- Lanxess
Competitive Analysis
The Singapore Organic Pigment Dispersion Market demonstrates a competitive landscape driven by global and regional companies. Key players include BASF SE, Sudarshan Chemical, DIC Corporation, Cabot Corporation, Heubach GmbH, Penn Colors, Pidilite Industries, and Lanxess. These firms focus on sustainability, innovation, and tailored product portfolios to meet diverse industrial needs. It benefits from strategic collaborations, regional expansions, and technology-driven advancements in pigment formulation. Multinationals strengthen their presence in Singapore by leveraging trade networks and local partnerships. Regional players compete by offering cost-effective solutions while ensuring regulatory compliance. Product differentiation, quality standards, and supply chain efficiency remain critical factors shaping competition. The market maintains a balance between global leaders and local innovators, fostering steady growth across industries.
Recent Developments
- In May 2025, BASF South East Asia Pte Ltd signed a Power Purchase Agreement with SP Group in Singapore for the installation of solar rooftop panels at its Jurong Island Performance Chemicals site and the Chemetall site, aligning with BASF’s green transformation strategy and aiming for the panels to be operational by the end of 2025, with Chemetall’s site expected to meet 100% of its electricity demand through this renewable energy initiative.
- In March 2025, Sudarshan Chemical Industries Limited completed the acquisition of Germany-based Heubach Group, creating a global pigment entity with a diversified asset footprint across 19 sites globally and combining Sudarshan’s operations with Heubach’s technological expertise, with the combined company led by Sudarshan’s Managing Director Rajesh Rathi.
- In March 2025, Sun Chemical, a subsidiary of DIC Corporation, announced the launch of new metallic effect pigments for cosmetics, including Chione Electric Scarlet SR90D and Chione Electric Sienna SC90D, showcasing these innovations at in-cosmetics Global 2025, and emphasizing expanded offerings in vegan and multifunctional pigment solutions.
Report Coverage
The research report offers an in-depth analysis based on Pigment Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for eco-friendly pigment dispersions will expand due to sustainability regulations across industries.
- Growth in packaging and printing applications will drive higher adoption of advanced pigment formulations.
- Digital printing expansion will create opportunities for specialized dispersions tailored for high-speed applications.
- Textile and fashion industries will increasingly adopt organic pigment dispersions for sustainable production.
- Technological advancements in dispersion stability and nanotechnology will enhance product performance.
- Singapore’s role as a regional trade hub will strengthen export opportunities across Asia-Pacific and Oceania.
- Rising industrialization in Southeast Asia will increase reliance on Singapore for pigment supply.
- Local innovation and R&D collaborations will support the development of customized pigment solutions.
- Strategic partnerships between global players and local distributors will improve market penetration.
- Focus on premium, durable pigments for automotive and construction industries will sustain long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Singapore Organic Pigment Dispersion Market, and what is its projected size in 2032?
Which Singapore Organic Pigment Dispersion Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Singapore Organic Pigment Dispersion Market?
Who are the leading companies in the Singapore Organic Pigment Dispersion Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Singapore Organic Pigment Dispersion Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Singapore Organic Pigment Dispersion Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 16.37 million → 2032: USD 23.58 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Singapore Organic Pigment Dispersion Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Singapore Organic Pigment Dispersion Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Singapore Organic Pigment Dispersion Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Singapore Organic Pigment Dispersion Market Drivers
- 3.3 Singapore Organic Pigment Dispersion Market Restraints & Challenges
- 3.4 Singapore Organic Pigment Dispersion Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Singapore Organic Pigment Dispersion Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Singapore Organic Pigment Dispersion Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Singapore Organic Pigment Dispersion category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Singapore Organic Pigment Dispersion Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Singapore Organic Pigment Dispersion Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Singapore Organic Pigment Dispersion market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Singapore Organic Pigment Dispersion Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Singapore Organic Pigment Dispersion Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Singapore Organic Pigment Dispersion Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Singapore Organic Pigment Dispersion (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Singapore Organic Pigment Dispersion Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Singapore Organic Pigment Dispersion Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Singapore Organic Pigment Dispersion Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Singapore Organic Pigment Dispersion Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Singapore Organic Pigment Dispersion Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Singapore Organic Pigment Dispersion Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Singapore Organic Pigment Dispersion Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Singapore Organic Pigment Dispersion Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Singapore Organic Pigment Dispersion Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
