
Market Overview
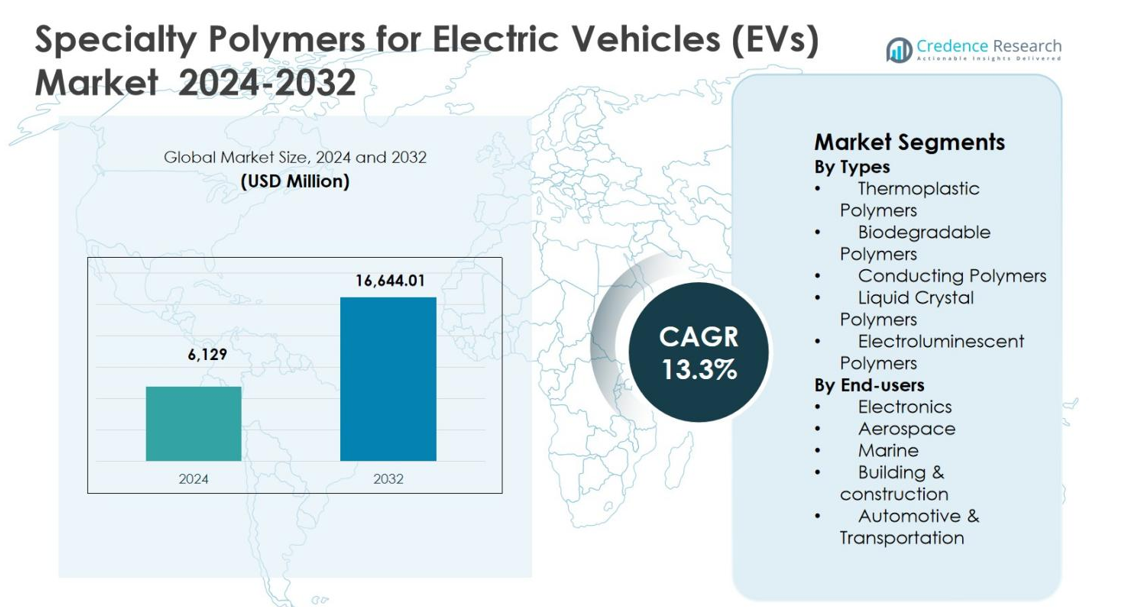
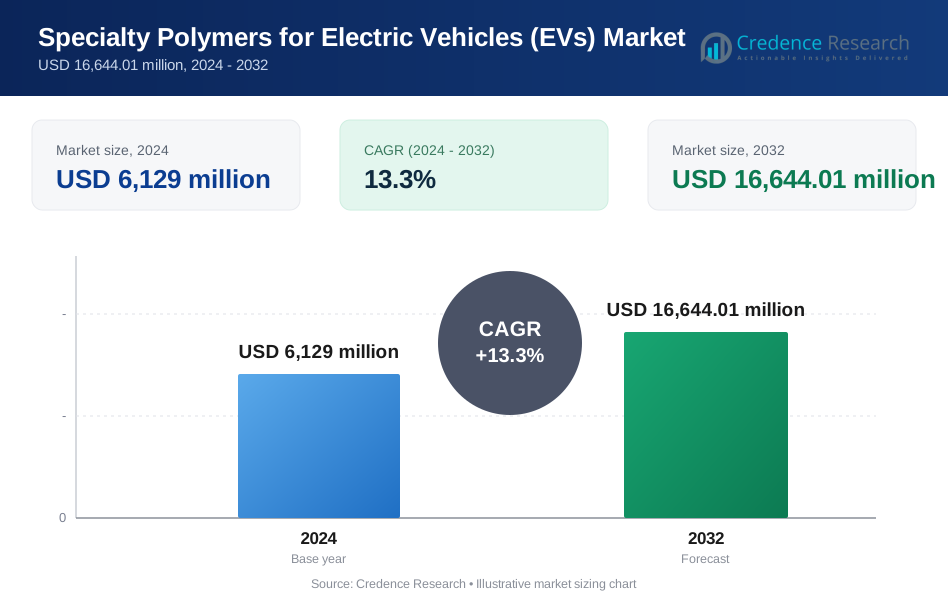
Specialty Polymers for Electric Vehicles (EVs) Market size was valued at USD 6,129 million in 2024 and is anticipated to reach USD 16,644.01 million by 2032, expanding at a CAGR of 13.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Specialty Polymers for Electric Vehicles (EVs) Market Size 2024 | USD 6,129 million |
| Specialty Polymers for Electric Vehicles (EVs) Market, CAGR | 13.3% |
| Specialty Polymers for Electric Vehicles (EVs) Market Size 2032 | USD 16,644.01 million |
Specialty Polymers for Electric Vehicles (EVs) Market is shaped by the strong presence of global chemical and material leaders such as BASF SE, Solvay Group, Arkema Group, The Dow Chemical Company, LyondellBasell Industries N.V., Clariant, 3M, and Celanese Corporation, which focus on advanced polymer solutions for batteries, power electronics, and lightweight vehicle components. These companies emphasize material innovation, thermal stability, electrical insulation, and sustainability to meet evolving EV requirements. Asia Pacific led the market with a 34.8% share in 2024, supported by large-scale EV production and battery manufacturing in China, Japan, and South Korea. Europe followed with a 31.4% share, driven by stringent emission regulations and strong automotive R&D, while North America accounted for 28.6%, supported by advanced EV adoption and material innovation.
Market Insights
- Specialty Polymers for Electric Vehicles (EVs) Market was valued at USD 6,129 million in 2024 and is projected to reach USD 16,644.01 million by 2032, growing at a CAGR of 13.3% during the forecast period.
- Market growth is driven by rapid EV production expansion, rising demand for lightweight and high-performance materials, and increasing adoption of specialty polymers in batteries, power electronics, and thermal management systems.
- Thermoplastic polymers dominated the market with a 6% segment share in 2024, supported by their recyclability, mechanical strength, and suitability for EV structural and electrical components, followed by conducting and liquid crystal polymers.
- Leading companies such as BASF SE, Solvay Group, Arkema Group, Dow Chemical Company, and LyondellBasell focus on innovation, sustainability, and partnerships with EV manufacturers to strengthen market positioning.
- Asia Pacific led with a 8% regional share in 2024, followed by Europe at 31.4% and North America at 28.6%, while Latin America and Middle East & Africa together accounted for the remaining share.
Market Segmentation Analysis:
By Types:
The Specialty Polymers for Electric Vehicles (EVs) Market, by types, is led by Thermoplastic Polymers, which accounted for 42.6% market share in 2024, driven by their lightweight properties, high mechanical strength, recyclability, and excellent thermal resistance for battery housings, connectors, and interior components. Strong demand for polyamide, PEEK, and polypropylene in EV powertrain and structural applications reinforces this dominance. Conducting polymers and liquid crystal polymers follow, supported by rising use in electronic components and thermal management systems, while biodegradable and electroluminescent polymers gain traction in sustainable materials and advanced display technologies.
- For instance, Lanxess's Durethan BKV30FN04, a glass-fiber-reinforced polyamide 6, equips battery module housings from INFAC with halogen-free flame retardancy and high-voltage insulation up to 800 V, enabling complex function integration and lighter weight.
By End-users:
By end-users, Automotive & Transportation dominated the Specialty Polymers for Electric Vehicles (EVs) Market with a 51.8% share in 2024, supported by accelerating EV production, stringent emission regulations, and the need for lightweight and high-performance materials. Specialty polymers are widely used in battery modules, cable insulation, power electronics, and thermal management systems. Electronics held the second-largest share due to growing demand for polymer-based connectors and insulation materials, while aerospace, marine, and building & construction segments contributed steadily through adoption of high-strength and corrosion-resistant polymer solutions.
- For instance, SABIC's NORYL NHP8000VT3 resin, a polyphenylene ether-based material, enables ultra-thin-wall insulation films for high-voltage (600-800 V) EV battery modules, achieving the highest CTI PLC0 rating and UL94 V0 at 0.25 mm thickness for enhanced safety and space savings.
Key Growth Drivers
Rapid Expansion of Electric Vehicle Production
The accelerating global production of electric vehicles is a primary growth driver for the Specialty Polymers for Electric Vehicles (EVs) Market. Automakers increasingly rely on advanced polymers to reduce vehicle weight, improve energy efficiency, and extend driving range. Specialty polymers replace traditional metals in battery enclosures, power electronics, connectors, and interior components due to their superior strength-to-weight ratio and design flexibility. Government incentives, emission regulations, and expanding charging infrastructure further stimulate EV manufacturing, directly increasing demand for high-performance thermoplastic, conducting, and liquid crystal polymers.
- For instance, Covestro supplies Makrolon® polycarbonate and Bayblend® PC/ABS resins for EV battery enclosures, enabling injection-molded, flame-retardant designs with tight tolerances for mass production.
Rising Demand for Lightweight and High-Performance Materials
Light weighting remains a critical focus in EV design, strongly driving the Specialty Polymers for Electric Vehicles (EVs) Market. Specialty polymers enable significant weight reduction while maintaining thermal stability, flame retardancy, and mechanical durability required for high-voltage EV systems. Their use enhances battery efficiency, vehicle safety, and overall performance. Automakers and component manufacturers increasingly adopt polymer composites and advanced thermoplastics to meet efficiency targets, comply with safety standards, and support modular vehicle architectures, reinforcing sustained demand across global EV platforms.
- For instance, SABIC employs NORYL GTX™ resins in hybrid plastic/metal designs for lightweight honeycomb crash protection structures in EV battery systems. These modified PPE resins with polyamide provide low density, dimensional stability, and E-coat capability up to 220°C for 30 minutes, replacing heavier metals while ensuring impact protection.
Advancements in Battery and Power Electronics Technologies
Continuous advancements in battery chemistry and power electronics significantly propel the Specialty Polymers for Electric Vehicles (EVs) Market. Next-generation lithium-ion and solid-state batteries require polymers with superior thermal management, electrical insulation, and chemical resistance. Specialty polymers support improved heat dissipation, reduced risk of thermal runaway, and enhanced durability of battery packs. Growing investments in fast-charging technologies and high-voltage systems further boost the need for conducting and high-temperature polymers, strengthening their role in advanced EV architectures.
Key Trends & Opportunities
Growing Adoption of Sustainable and Recyclable Polymers
Sustainability has emerged as a key trend shaping the Specialty Polymers for Electric Vehicles (EVs) Market. Automakers increasingly prioritize recyclable and bio-based polymers to reduce vehicle lifecycle emissions and comply with environmental regulations. Biodegradable and recyclable thermoplastics present significant opportunities for material innovation in EV interiors and non-structural components. Manufacturers investing in circular polymer solutions and low-carbon production processes can gain competitive advantages while addressing sustainability goals across the EV value chain.
- For instance, Avient developed reSound™ REC thermoplastic elastomers (TPEs) incorporating recycled polyvinyl butyral (PVB) from broken vehicle glass, closing the loop for automotive applications.
Increasing Integration of Smart and Functional Polymers
The integration of smart and functional polymers presents a strong growth opportunity in the Specialty Polymers for Electric Vehicles (EVs) Market. Conducting and electroluminescent polymers enable advanced sensing, lighting, and energy-monitoring applications within EVs. These materials support intelligent battery management systems, enhanced human–machine interfaces, and lightweight display technologies. As EVs evolve toward connected and autonomous platforms, demand for multifunctional polymer materials is expected to increase, opening new avenues for product differentiation and innovation.
- For instance, BASF's OPPANOL® high-molecular-weight polyisobutylene serves as a cathode binder in EV batteries. It exhibits superior elasticity and elongation to accommodate mechanical expansion during battery operation, reducing physical damage risk.
Key Challenges
High Material Costs and Price Volatility
High costs associated with specialty polymers pose a significant challenge for the Specialty Polymers for Electric Vehicles (EVs) Market. Advanced polymers require complex manufacturing processes and specialized raw materials, leading to higher prices compared to conventional plastics and metals. Fluctuations in petrochemical feedstock prices further impact cost structures. These factors can limit adoption, particularly among cost-sensitive EV manufacturers, and create pricing pressure across the supply chain.
Performance Validation and Regulatory Compliance
Ensuring consistent performance and meeting stringent regulatory standards remains a challenge in the Specialty Polymers for Electric Vehicles (EVs) Market. EV applications demand polymers that withstand extreme temperatures, high voltages, and long-term mechanical stress. Extensive testing, certification requirements, and evolving safety regulations increase development timelines and costs. Manufacturers must continuously invest in material validation and compliance processes, which can slow commercialization and restrict rapid adoption of new polymer technologies.
Regional Analysis
North America
North America held 28.6% market share in 2024 in the Specialty Polymers for Electric Vehicles (EVs) Market, supported by strong EV adoption, advanced automotive manufacturing, and sustained investments in battery technology. The United States leads regional demand due to the presence of major EV manufacturers and polymer suppliers, alongside federal incentives promoting electric mobility. Specialty polymers are widely used in battery enclosures, thermal management systems, and power electronics. Growing focus on lightweight materials, recycling initiatives, and high-performance polymers for fast-charging applications continues to strengthen regional market growth.
Europe
Europe accounted for 31.4% market share in 2024 in the Specialty Polymers for Electric Vehicles (EVs) Market, driven by strict emission regulations and aggressive electrification targets. Countries including Germany, France, and the United Kingdom are major contributors, supported by strong automotive OEM presence and advanced polymer R&D capabilities. The region emphasizes sustainable and recyclable polymer materials to meet environmental compliance standards. Rising investments in EV battery gigafactories and lightweight vehicle design further boost demand for thermoplastic and conducting polymers across automotive and transportation applications.
Asia Pacific
Asia Pacific dominated the Specialty Polymers for Electric Vehicles (EVs) Market with a 34.8% market share in 2024, led by rapid EV production growth in China, Japan, and South Korea. Strong government incentives, expanding charging infrastructure, and large-scale battery manufacturing drive high consumption of specialty polymers. The region benefits from cost-effective manufacturing, robust supply chains, and growing domestic demand for electric passenger and commercial vehicles. Increasing adoption of advanced polymers in battery packs, connectors, and electronic components continues to reinforce Asia Pacific’s leadership.
Latin America
Latin America captured 3.1% market share in 2024 in the Specialty Polymers for Electric Vehicles (EVs) Market, supported by gradual EV adoption and emerging automotive manufacturing hubs in Brazil and Mexico. Government initiatives promoting clean transportation and rising investments in electric public transport systems are driving polymer demand. Specialty polymers are increasingly used in lightweight automotive components and electrical insulation materials. Although the market remains in a developing stage, improving regulatory frameworks and growing regional partnerships present steady growth opportunities.
Middle East & Africa
The Middle East & Africa region accounted for 2.1% market share in 2024 in the Specialty Polymers for Electric Vehicles (EVs) Market, driven by early-stage EV adoption and infrastructure development. Countries such as the United Arab Emirates and South Africa are investing in electric mobility and sustainable transportation solutions. Demand for specialty polymers is rising in EV components requiring thermal resistance and durability under harsh climatic conditions. Increasing government focus on diversification and clean energy initiatives supports long-term market expansion across the region.
Market Segmentations:
By Types
- Thermoplastic Polymers
- Biodegradable Polymers
- Conducting Polymers
- Liquid Crystal Polymers
- Electroluminescent Polymers
By End-users
- Electronics
- Aerospace
- Marine
- Building & construction
- Automotive & Transportation
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Specialty Polymers for Electric Vehicles (EVs) Market includes BASF SE, Solvay Group, Arkema Group, The Dow Chemical Company, LyondellBasell Industries N.V., Clariant, 3M, Celanese Corporation, Specialty Polymers, Inc., and AmeriLux International, LLC. The market features a mix of global chemical leaders and specialized material manufacturers focused on high-performance polymer solutions for EV applications. Companies compete through continuous material innovation, emphasizing lightweighting, thermal stability, electrical insulation, and flame-retardant properties tailored for batteries, power electronics, and charging systems. Strategic investments in polymer R&D, capacity expansion, and advanced compounding technologies strengthen product differentiation. Collaborations with automotive OEMs and battery manufacturers support early material integration and long-term supply agreements. Sustainability initiatives, including recyclable and low-carbon polymers, further shape competition, while regional manufacturing footprints and technical service capabilities influence customer preference and market positioning.
Key Player Analysis
- Solvay Group
- LyondellBasell Industries N.V.
- AmeriLux International, LLC
- Arkema Group
- BASF SE
- Specialty Polymers, Inc.
- The Dow Chemical Company
- Clariant
- Celanese Corporation
- 3M
Recent Developments
- In September 2025, BASF SE launched Glysantin Electrified low electrical conductivity coolants for electric vehicles, designed to improve battery safety and comply with the new GB 29743.2-2025 standard in China.
- In August 2025, SABIC introduced LNP™ THERMOCOMP™ non-brominated/non-chlorinated flame-retardant PBT compounds for critical EV components, enhancing safety and performance in high-demand electrical applications.
- In July 2025, Covestro launched Baysafe BEF, an advanced flame-retardant polyurethane encapsulation foam for EV batteries. The material limits thermal propagation between cells, aligning with China's new battery safety regulations to enhance overall vehicle safety.
Report Coverage
The research report offers an in-depth analysis based on Type, End Users and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Specialty Polymers for Electric Vehicles (EVs) Market will experience sustained demand growth driven by increasing global EV production and model diversification.
- Automakers will continue replacing traditional materials with specialty polymers to achieve weight reduction and improved energy efficiency.
- Advancements in battery technology will accelerate the adoption of high-temperature and electrically insulating polymer materials.
- Demand for conducting and functional polymers will increase with the expansion of smart power electronics and battery management systems.
- Sustainability requirements will push manufacturers toward recyclable, bio-based, and low-carbon polymer solutions.
- Continuous innovation in thermal management polymers will support safer and faster-charging EV architectures.
- Strategic partnerships between polymer producers and automotive OEMs will strengthen long-term supply relationships.
- Expansion of EV manufacturing capacity in Asia Pacific will influence global polymer supply chains.
- Regulatory standards for fire safety and electrical performance will drive material certification and innovation.
- Customization of polymer formulations for specific EV platforms will become a key competitive differentiator.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Specialty Polymers for Electric Vehicles (EVs) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Specialty Polymers for Electric Vehicles (EVs) Market projected to grow between 2024 and 2032?
Which regions are leading markets for these specialty polymers?
What is the projected compound annual growth rate for this market?
What are some key applications for specialty polymers in electric vehicles?
Who are the leading companies in the Specialty Polymers for Electric Vehicles (EVs) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Specialty Polymers for Electric Vehicles (EVs) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Specialty Polymers for Electric Vehicles (EVs) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,129 million → 2032: USD 16,644.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Specialty Polymers for Electric Vehicles (EVs) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Specialty Polymers for Electric Vehicles (EVs) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Specialty Polymers for Electric Vehicles (EVs) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Specialty Polymers for Electric Vehicles (EVs) Market Drivers
- 3.3 Specialty Polymers for Electric Vehicles (EVs) Market Restraints & Challenges
- 3.4 Specialty Polymers for Electric Vehicles (EVs) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Specialty Polymers for Electric Vehicles (EVs) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Specialty Polymers for Electric Vehicles (EVs) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Specialty Polymers for Electric Vehicles (EVs) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Specialty Polymers for Electric Vehicles (EVs) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Specialty Polymers for Electric Vehicles (EVs) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Specialty Polymers for Electric Vehicles (EVs) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Specialty Polymers for Electric Vehicles (EVs) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Specialty Polymers for Electric Vehicles (EVs) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Specialty Polymers for Electric Vehicles (EVs) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Specialty Polymers for Electric Vehicles (EVs) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Specialty Polymers for Electric Vehicles (EVs) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Specialty Polymers for Electric Vehicles (EVs) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Specialty Polymers for Electric Vehicles (EVs) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Specialty Polymers for Electric Vehicles (EVs) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Specialty Polymers for Electric Vehicles (EVs) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Specialty Polymers for Electric Vehicles (EVs) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Specialty Polymers for Electric Vehicles (EVs) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Specialty Polymers for Electric Vehicles (EVs) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Specialty Polymers for Electric Vehicles (EVs) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
