
Market Overview
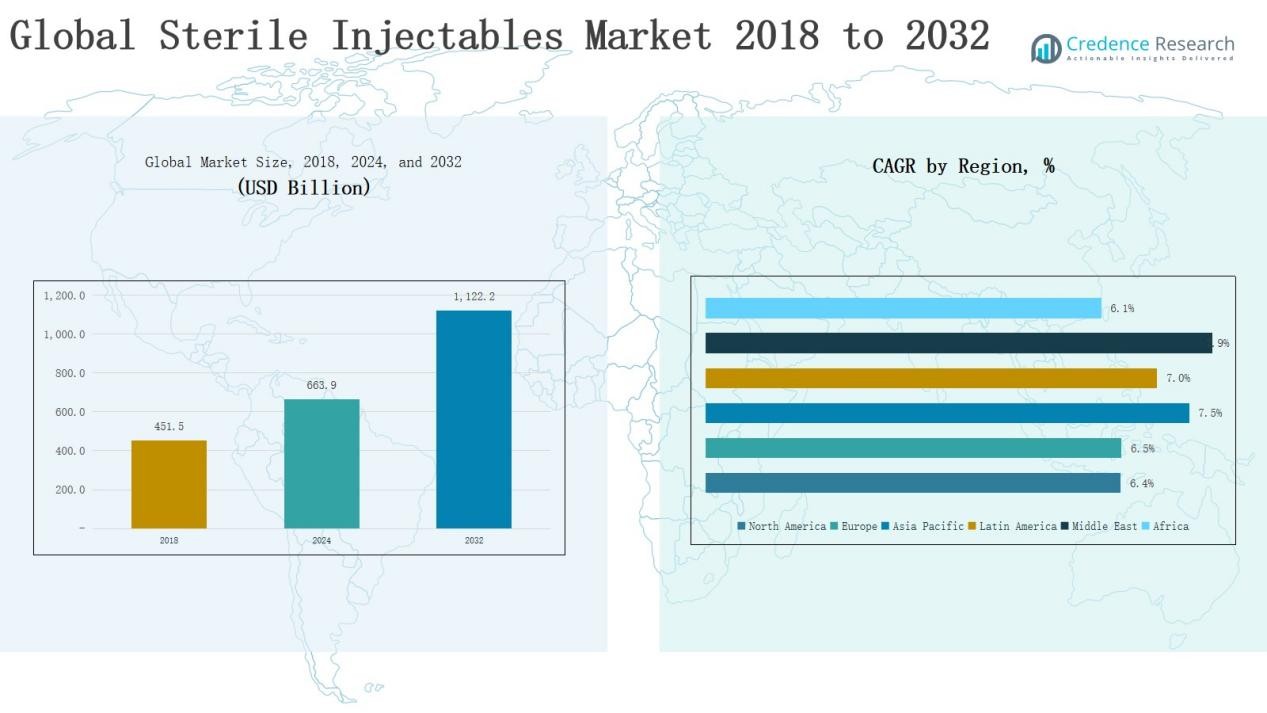
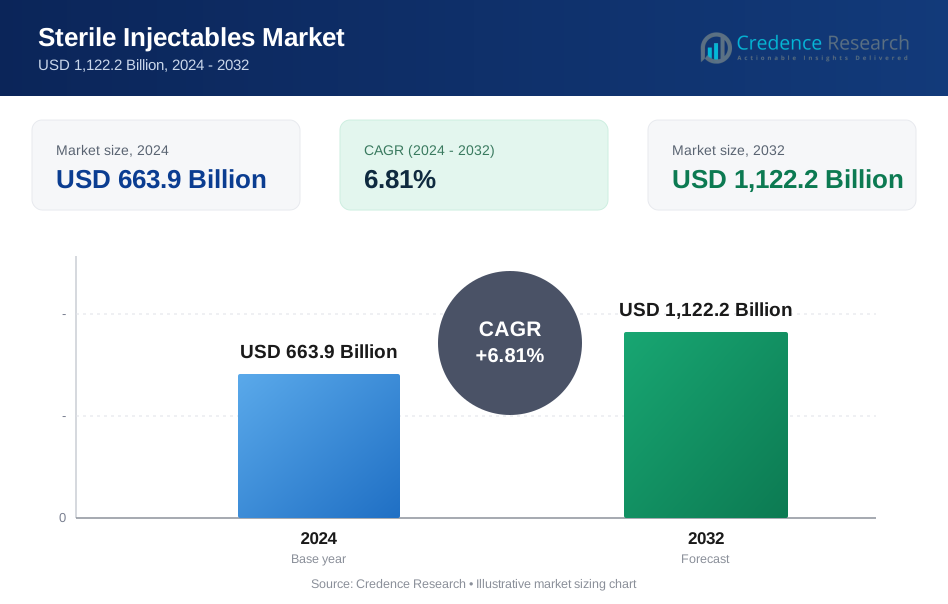
Global Sterile Injectables Market size was valued at USD 451.5 Billion in 2018 to USD 663.9 Billion in 2024 and is anticipated to reach USD 1,122.2 Billion by 2032, at a CAGR of 6.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sterile Injectables Market Size 2024 | USD 663.9 Billion |
| Sterile Injectables Market, CAGR | 6.81% |
| Sterile Injectables Market Size 2032 | USD 1,122.2 Billion |
What is the current market size for Global Sterile Injectables Market, and what is its projected size in 2032? The Global Sterile Injectables Market is shaped by the strong presence of leading players such as Pfizer, Amgen, Sanofi, Johnson & Johnson, AstraZeneca, Eli Lilly, Merck, Baxter, and Mylan, each leveraging extensive biologics pipelines, oncology portfolios, and global distribution networks to strengthen competitiveness. These companies actively invest in R&D, biosimilar development, and strategic partnerships to expand market reach and improve affordability. Among regions, North America led the market in 2024 with a 33% share, supported by advanced healthcare infrastructure, favorable reimbursement systems, and rapid adoption of biologics and biosimilars. This dominance reflects the region’s strong clinical demand and innovation leadership.
 Market Insights
- The Global Sterile Injectables Market grew from USD 451.5 Billion in 2018 to USD 663.9 Billion in 2024, projected to reach USD 1,122.2 Billion by 2032.
- Monoclonal antibodies led with 36% share in 2024, supported by oncology and autoimmune therapies, while vaccines (14%) and cytokines (12%) followed as strong growth drivers.
- By therapeutic area, cancer dominated with 38% share, followed by infectious diseases (21%) and diabetes (12%), highlighting the critical role of biologics and biosimilars.
- North America held 33% share in 2024, followed by Europe (28%) and Asia Pacific (23%), reflecting strong healthcare infrastructure and rising biologics adoption across regions.
- Leading companies including Pfizer, Amgen, Sanofi, Johnson & Johnson, AstraZeneca, Eli Lilly, Merck, Baxter, and Mylan continue to drive innovation, biosimilar development, and competitive expansion.
Market Segment Insights
By Drug Type
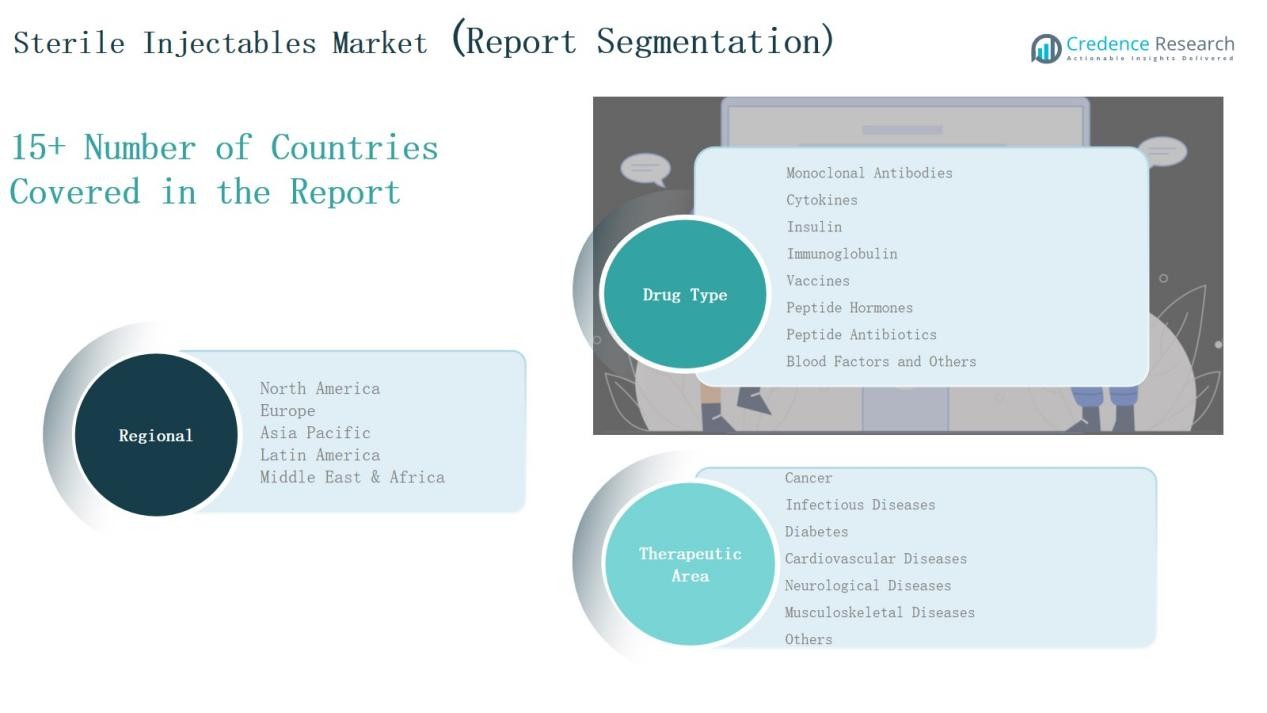
In the Global Sterile Injectables Market, monoclonal antibodies lead with 36% share in 2024, driven by oncology and autoimmune treatments alongside strong biologics pipelines. Vaccines hold 14% share, supported by global immunization efforts and mRNA advancements. Cytokines represent 12%, while insulin accounts for 10% due to the diabetes burden. Immunoglobulin secures 9% share with demand in immunodeficiency therapies. Peptide hormones and peptide antibiotics capture 6% and 5% respectively, addressing endocrine and antimicrobial needs. Blood factors account for 4%, sustained by hemophilia treatments, while other injectables contribute 4% from anesthesia and diagnostic use.
For instance, Pfizer and BioNTech’s Comirnaty, the first mRNA COVID-19 vaccine to gain full FDA approval in 2021, had billions of doses administered globally, underscoring the vital role of sterile injectable vaccines in public health.
By Therapeutic Area
Cancer dominates with 38% share in 2024, fueled by high biologics adoption and targeted oncology therapies. Infectious diseases follow with 21%, benefiting from vaccine uptake and pandemic preparedness. Diabetes holds 12%, driven by insulin and GLP-1 analogs, while cardiovascular diseases capture 10% through anticoagulation and biologics. Neurological diseases account for 7%, musculoskeletal disorders 6%, and other conditions 6%, covering ophthalmology, dermatology, and gastrointestinal applications. Strong prevalence of chronic illnesses and rising biologics approvals reinforce growth across all therapeutic segments.
For instance, Merck’s immunotherapy drug Keytruda generated over $25 billion in revenue in 2023, making it one of the world’s top-selling oncology biologics.
Key Growth Drivers
Rising Prevalence of Chronic Diseases
The growing incidence of chronic conditions such as cancer, diabetes, and cardiovascular disorders fuels strong demand for sterile injectables. These therapies deliver rapid and targeted treatment, making them essential in critical care. Oncology dominates demand, supported by biologics like monoclonal antibodies. Increasing lifestyle-related diseases globally and a rising aging population further boost the need for injectable biologics and biosimilars. This trend positions sterile injectables as a vital treatment option across multiple therapeutic areas, ensuring sustained long-term market expansion.
For instance, Amgen’s Repatha® (evolocumab), an injectable biologic for lowering LDL cholesterol in cardiovascular patients, has been widely adopted, with over 1 Billion patients treated worldwide by 2021, reflecting the rising importance of sterile injectables in cardiovascular care.
Expanding Biologics and Biosimilars Pipeline
The global pipeline of biologics and biosimilars continues to expand, driving adoption of sterile injectables. Biopharmaceutical companies increasingly prioritize injectable formats for new drug launches, particularly in oncology, immunology, and infectious diseases. Patent expirations of blockbuster biologics create opportunities for biosimilars, making therapies more affordable and accessible. Regulatory approvals worldwide encourage rapid commercialization. As research shifts toward personalized medicine, injectable biologics remain the preferred choice for targeted therapies. This expanding portfolio strengthens sterile injectables’ market position across advanced and emerging economies.
For instance, in June 2025, Sandoz launched Wyost® and Jubbonti®, the first interchangeable biosimilars for Amgen’s Xgeva® and Prolia® (denosumab) in the U.S., enhancing access to lower-cost osteoporosis and oncology therapies.
Government and Institutional Support
Government healthcare initiatives and institutional support programs play a critical role in the adoption of sterile injectables. National immunization drives, pandemic preparedness policies, and funding for biologics infrastructure accelerate demand. Public-private collaborations foster innovation and expand access to injectable therapies in low- and middle-income countries. Favorable reimbursement frameworks in developed markets further enhance adoption. Increased investment in cold-chain infrastructure and hospital supply networks also ensures reliable distribution. This strong policy backing reinforces sterile injectables’ position as a frontline treatment modality.
Key Trends & Opportunities
Shift Toward Targeted and Personalized Therapies
Personalized medicine is reshaping the sterile injectables market, with biologics and biosimilars tailored to individual patient needs. Growth in precision oncology, immunotherapies, and advanced neurological treatments underscores this trend. Pharmaceutical companies are focusing on developing injectable therapies with higher efficacy and fewer side effects. The rising use of biomarkers and genetic profiling supports adoption. This shift creates opportunities for drug developers to expand their product portfolios while offering patients improved outcomes, making personalized sterile injectables a major opportunity segment.
For instance, Bristol Myers Squibb’s Opdivo (nivolumab), a sterile injectable immunotherapy, is prescribed based on PD-L1 biomarker testing to treat cancers such as non-small cell lung cancer, enabling greater treatment precision.
Growth of Contract Manufacturing and Outsourcing
Contract manufacturing organizations (CMOs) and outsourcing partnerships are gaining traction as companies seek cost-efficient sterile injectable production. Rising complexity of biologics manufacturing encourages outsourcing to specialized providers with advanced capabilities. CMOs support scalability, compliance, and global distribution, which are critical for meeting surging demand. Emerging markets, especially in Asia-Pacific, present opportunities for low-cost manufacturing hubs. Strategic collaborations also help biopharma firms reduce capital expenditure and speed up product launches. This trend positions outsourcing as a long-term growth enabler for the market.
For instance, Lonza Group, a Swiss-based CMO, has expanded its capabilities in cell and gene therapy production to support biopharma firms in scaling advanced therapies efficiently.
Key Challenges
High Production and Development Costs Sterile injectable manufacturing requires sophisticated infrastructure, strict compliance, and advanced aseptic processes, leading to high production costs. Biopharmaceutical firms face significant upfront investments in facilities, quality systems, and skilled labor. Developing biologics and biosimilars adds additional R&D expenses. These costs increase financial risk, especially for smaller players, and limit affordability in low-income markets. The challenge of balancing safety, efficacy, and cost-efficiency remains critical. Manufacturers must adopt process innovations and partnerships to mitigate expenses while maintaining high quality standards.
Supply Chain and Cold-Chain Constraints
Sterile injectables require stringent handling, with cold-chain infrastructure vital for biologics and vaccines. Disruptions in global supply chains, as seen during the COVID-19 pandemic, exposed vulnerabilities in distribution networks. Many regions still lack adequate storage and logistics capabilities, limiting access to essential injectables. Maintaining temperature integrity during transport is a major challenge, especially in emerging markets. Infrastructure gaps and high logistical costs restrict equitable access. Strengthening global supply networks and investing in advanced cold-chain solutions remain essential to address these hurdles.
Regulatory and Safety Compliance Barriers
The sterile injectables market faces complex and evolving regulatory requirements that demand strict compliance. Manufacturers must adhere to Good Manufacturing Practices (GMP), sterility assurance protocols, and continuous quality monitoring. Meeting these requirements increases operational complexity and costs. Regulatory delays in approvals often slow time-to-market for new drugs. Additionally, product recalls or contamination issues can damage brand reputation and patient safety. Navigating diverse international standards poses further challenges for global players. Ensuring consistent compliance while accelerating innovation remains a pressing concern.
Regional Analysis
North America
North America leads the global sterile injectables market, accounting for 33% share in 2024 with revenues of USD 218.37 billion, rising from USD 135.92 billion in 2018. Strong healthcare infrastructure, high biologics adoption, and advanced research pipelines sustain regional dominance. The U.S. drives most demand, supported by favorable reimbursement systems and rapid uptake of biosimilars. A robust presence of key pharmaceutical companies further strengthens growth. With a 6.4% CAGR, the market is projected to reach USD 359.11 billion by 2032, highlighting North America’s continued leadership in oncology, immunology, and chronic disease treatments.
Europe
Europe captures 28% share in 2024, valued at USD 182.58 billion, up from USD 112.65 billion in 2018. Rising demand for biologics, vaccines, and insulin injectables drives regional growth. Germany, France, and the UK serve as key contributors, supported by strong government healthcare initiatives and widespread adoption of biosimilars. Strategic collaborations with research institutions enhance innovation in sterile injectables. With a projected 6.5% CAGR, the market is set to reach USD 300.53 billion by 2032, positioning Europe as a consistent growth hub with balanced demand across oncology, diabetes, and cardiovascular therapies.
Asia Pacific
Asia Pacific holds 23% share in 2024, worth USD 157.56 billion, growing from USD 94.21 billion in 2018, and is the fastest-growing region with a 7.5% CAGR. Rising chronic disease prevalence, expanding healthcare infrastructure, and increasing biosimilar penetration drive demand. China, India, and Japan lead the market, supported by government programs and rising investments in biologics manufacturing. Affordable production capabilities and a growing patient pool fuel regional expansion. By 2032, the market is forecasted to reach USD 280.55 billion, establishing Asia Pacific as a key driver of global growth in sterile injectables.
Latin America
Latin America accounts for 8% share in 2024, valued at USD 52.98 billion, up from USD 32.86 billion in 2018. Growth is supported by rising diabetes and cardiovascular cases, alongside government initiatives to expand healthcare access. Brazil dominates regional demand, followed by Argentina, due to strong hospital networks and improved biologics availability. Local partnerships and imports support market expansion across smaller economies. With a 7.0% CAGR, the market is expected to reach USD 90.90 billion by 2032, making Latin America a steadily expanding region in sterile injectables.
Middle East
The Middle East contributes 5% share in 2024, valued at USD 30.72 billion, rising from USD 18.04 billion in 2018, and shows strong momentum with the highest regional CAGR of 7.9%. GCC countries and Israel drive demand through advanced healthcare systems and increased biologics adoption. Rising government spending on healthcare modernization and expansion of cold-chain facilities strengthen growth. Oncology and infectious disease treatments remain primary demand drivers. By 2032, the market is expected to reach USD 56.22 billion, positioning the Middle East as a rapidly expanding market within the global sterile injectables landscape.
Africa
Africa represents 3% share in 2024, valued at USD 21.71 billion, up from USD 14.30 billion in 2018, with growth driven by improving healthcare infrastructure and rising prevalence of infectious diseases. South Africa and Egypt serve as leading contributors, while other regions depend heavily on imports of biologics and vaccines. Limited access and high costs challenge broader adoption, yet government and NGO-led health initiatives are expanding reach. The market is projected to grow at a 6.1% CAGR, reaching USD 34.90 billion by 2032, highlighting steady but constrained progress in the region.
Market Segmentations:
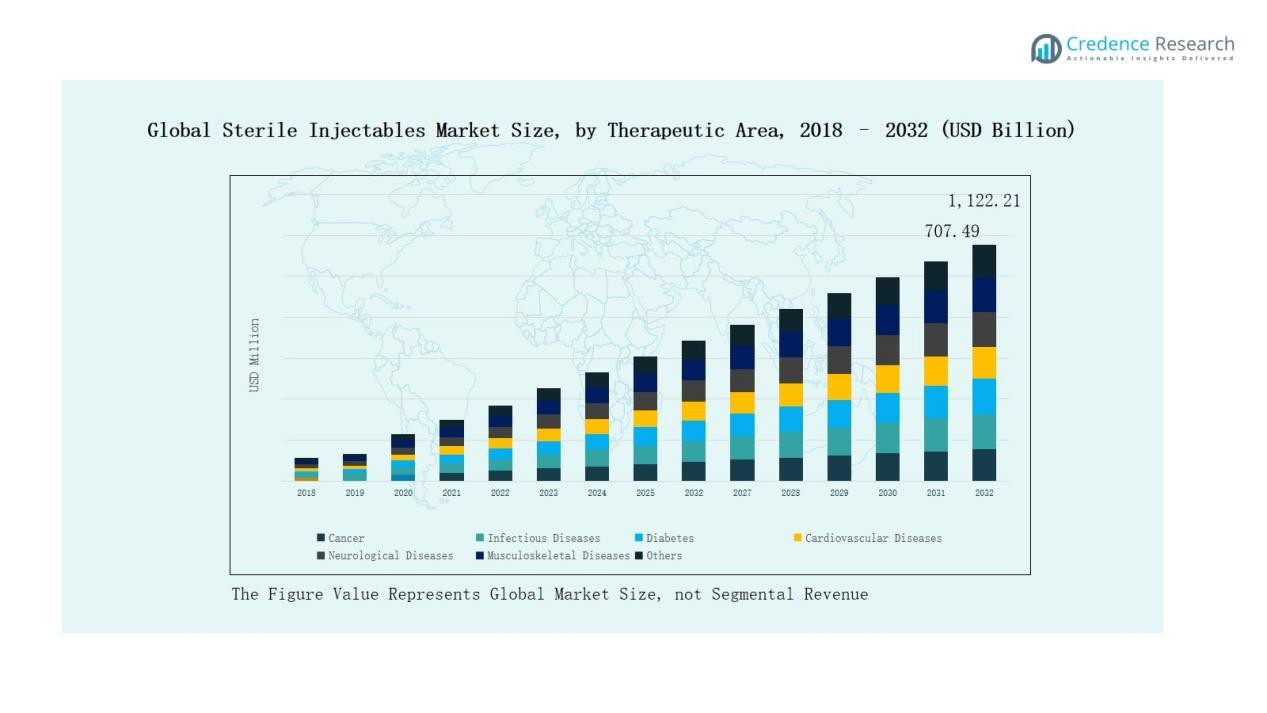
By Drug Type
- Monoclonal Antibodies
- Cytokines
- Insulin
- Immunoglobulin
- Vaccines
- Peptide Hormones
- Peptide Antibiotics
- Blood Factors
- Others
By Therapeutic Area
- Cancer
- Infectious Diseases
- Diabetes
- Cardiovascular Diseases
- Neurological Diseases
- Musculoskeletal Diseases
- Others
By Region
North America
- U.S.
- Canada
- Mexico
Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The Global Sterile Injectables Market is highly competitive, characterized by the presence of leading multinational pharmaceutical companies alongside regional players. Key participants such as Pfizer, Amgen, Sanofi, Johnson & Johnson, AstraZeneca, Eli Lilly, Merck, Baxter, and Mylan dominate with strong portfolios in biologics, vaccines, and oncology therapies. These companies leverage extensive R&D pipelines, strategic acquisitions, and global distribution networks to maintain leadership. Patent expirations of blockbuster biologics are encouraging biosimilar development, intensifying competition and expanding access in cost-sensitive markets. Regional manufacturers, particularly in Asia-Pacific, are gaining momentum by offering affordable biosimilars and contract manufacturing services, further reshaping the competitive dynamics. Strategic collaborations with contract manufacturing organizations and technology partnerships also play a vital role in sustaining supply efficiency and innovation. The market reflects moderate concentration, with top players holding significant revenue share, while smaller firms compete in niche therapeutic areas and emerging regions, creating a dynamic and evolving competitive landscape.
Key Players
- Amgen Limited
- AstraZeneca plc
- Baxter International, Inc.
- Eli Lilly and Company
- Johnson & Johnson Services, Inc.
- Merck & Co., Inc.
- Mylan N.V.
- Pfizer, Inc.
- Sanofi
- Nichi-Iko Pharmaceutical Co.
- Other Key Players
Recent Developments
- In March 2025, Eli Lilly, Merck, and Purdue University launched the Young Institute Pharmaceutical Manufacturing Consortium to advance sterile injectable manufacturing through AI, robotics, and aseptic processing innovation.
- In March 2025, Mallinckrodt and Endo announced the merger of their generics and sterile injectables businesses, forming Par Health, with a planned spin-off in Q4 2025.
- In May 2025, Amneal partnered with Apiject to install dedicated manufacturing lines supporting Apiject’s advanced delivery systems in the U.S., with annual production capacity scalable up to 400 Billion units to aid emergency and commercial readiness.
- In January 2025, Akums Drugs & Pharmaceuticals initiated the development of a new facility dedicated to lyophilized and sterile dosage manufacturing, with a focus on injectables and biologics.
Report Coverage
The research report offers an in-depth analysis based on Drug Type, Therapeutic Area and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biologics and biosimilars will continue to drive sterile injectable adoption.
- Oncology and immunology therapies will remain the largest contributors to injectable growth.
- Vaccines and infectious disease treatments will see consistent demand from global health initiatives.
- Contract manufacturing organizations will gain a stronger role in large-scale production.
- Personalized and targeted therapies will expand the use of advanced injectable formulations.
- Emerging markets will witness rapid growth due to healthcare infrastructure improvements.
- Cold-chain logistics and supply chain investments will enhance global accessibility of injectables.
- Strategic partnerships and acquisitions will remain central to competitive positioning.
- Regulatory harmonization efforts will streamline biosimilar approvals and accelerate market entry.
- Technological advances in delivery systems will improve patient compliance and treatment outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of cancer, diabetes, and cardiovascular disorders is fueling demand for sterile injectables, as these therapies offer rapid and targeted treatment essential for critical care and chronic disease management.
Expanding Biologics and Biosimilars Pipeline
A robust pipeline of biologics and biosimilars, especially in oncology and immunology, is driving adoption of sterile injectables, with patent expirations and regulatory support enabling broader access and affordability.
Government and Institutional Support
National immunization programs, pandemic preparedness initiatives, and investments in healthcare infrastructure are accelerating the uptake of sterile injectables, particularly vaccines and biologics, across both developed and emerging markets.
Shift Toward Targeted and Personalized Therapies
Advancements in precision medicine and biomarker-driven treatments are increasing the use of sterile injectable biologics and immunotherapies, offering higher efficacy and improved patient outcomes in oncology and autoimmune diseases.
Growth of Contract Manufacturing and Outsourcing
Pharmaceutical companies are increasingly partnering with contract manufacturing organizations to scale up sterile injectable production efficiently, leveraging specialized expertise and infrastructure to meet rising global demand.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Sterile Injectables Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Sterile Injectables Market projected to grow between 2025 and 2032?
Which Global Sterile Injectables Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Sterile Injectables Market?
Who are the leading companies in the Global Sterile Injectables Market?
Which region commanded the largest share of the Global Sterile Injectables Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Monoclonal Antibodies
- 1.2.2 Cytokines
- 1.2.3 Insulin
- 1.2.4 Immunoglobulin
- 1.2.5 Vaccines
- 1.2.6 Peptide Hormones
- 1.2.7 Peptide Antibiotics
- 1.2.8 Blood Factors
- 1.2.9 Others
- 1.3 By Therapeutic Area
- 1.3.1 Cancer
- 1.3.2 Infectious Diseases
- 1.3.3 Diabetes
- 1.3.4 Cardiovascular Diseases
- 1.3.5 Neurological Diseases
- 1.3.6 Musculoskeletal Diseases
- 1.3.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 663.9 Billion → 2032: USD 1,122.2 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sterile Injectables Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sterile Injectables Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sterile Injectables Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sterile Injectables Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sterile Injectables Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sterile Injectables Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sterile Injectables Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sterile Injectables Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 663.9 Billion → 2032: USD 1,122.2 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sterile Injectables Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Monoclonal Antibodies
- 12.3.7.2 Cytokines
- 12.3.7.3 Insulin
- 12.3.7.4 Immunoglobulin
- 12.3.7.5 Vaccines
- 12.3.7.6 Peptide Hormones
- 12.3.7.7 Peptide Antibiotics
- 12.3.7.8 Blood Factors
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cancer
- 12.4.7.2 Infectious Diseases
- 12.4.7.3 Diabetes
- 12.4.7.4 Cardiovascular Diseases
- 12.4.7.5 Neurological Diseases
- 12.4.7.6 Musculoskeletal Diseases
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sterile Injectables Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sterile Injectables Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sterile Injectables Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Amgen
- 17.4 Sanofi
- 17.5 Johnson & Johnson
- 17.6 AstraZeneca
- 17.7 Eli Lilly
- 17.8 Merck
- 17.9 Baxter
- 17.10 Mylan
- 17.11 Nichi-Iko Pharmaceutical
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

