
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sterile Injectable Drugs Market Size 2024 | USD 7,989.78 million |
| Sterile Injectable Drugs Market, CAGR | 10.80% |
| Sterile Injectable Drugs Market Size 2032 | USD 19,212.51 millio |
Market Overview
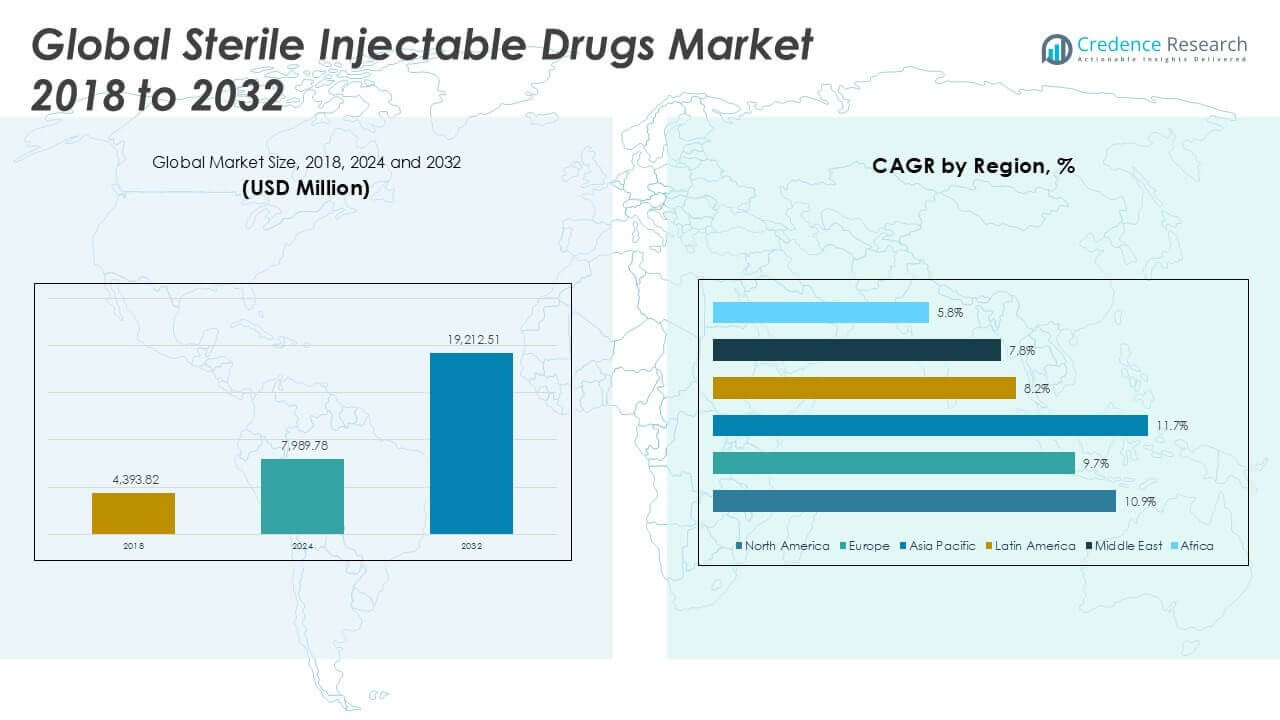
Sterile Injectable Drugs Market size was valued at USD 4,393.82 million in 2018 to USD 7,989.78 million in 2024 and is anticipated to reach USD 19,212.51 million by 2032, at a CAGR of 10.80% during the forecast period.
The Sterile Injectable Drugs Market is advancing rapidly, driven by the rising prevalence of chronic diseases, increased demand for biologics and biosimilars, and the need for rapid and effective treatment options in acute care settings. Pharmaceutical companies are investing in advanced manufacturing technologies and stringent quality controls to meet evolving regulatory standards and ensure patient safety. The market also benefits from the growing adoption of ready-to-administer formulations, prefilled syringes, and injectable drug-device combinations that improve convenience and compliance. Key trends include the expansion of contract manufacturing and outsourcing to streamline production and lower costs, as well as increased R&D activity targeting complex therapies such as oncology, autoimmune, and infectious diseases. The push for innovation, combined with the expanding global geriatric population and healthcare infrastructure improvements, continues to accelerate market growth and diversify product portfolios across established and emerging regions.
The Sterile Injectable Drugs Market demonstrates robust growth across major regions, with North America, Europe, and Asia Pacific leading in demand and innovation. North America benefits from advanced healthcare infrastructure and a strong pharmaceutical industry, while Europe sees significant expansion through regulatory harmonization and rising biosimilar adoption. Asia Pacific emerges as a dynamic growth engine due to increasing healthcare investments, a large patient population, and rapid uptake of generics and biosimilars. Key countries such as the United States, Germany, China, and India drive regional momentum with ongoing investments in manufacturing and research. Prominent players shaping the global competitive landscape include GlaxoSmithKline PLC, Pfizer Inc., and AstraZeneca, each leveraging extensive product portfolios, R&D capabilities, and strategic collaborations to strengthen their market position and support the development of innovative sterile injectable therapies worldwide.
Market Insights
- The Sterile Injectable Drugs Market grew from USD 4,393.82 million in 2018 to USD 7,989.78 million in 2024 and is projected to reach USD 19,212.51 million by 2032, with a CAGR of 10.80%.
- Rising incidence of chronic diseases and expanding demand for biologics and biosimilars drive the need for sterile injectable therapies across healthcare settings.
- Growing adoption of ready-to-use and prefilled injectables improves convenience, reduces risk of contamination, and supports faster treatment in hospitals and outpatient care.
- Leading companies such as GlaxoSmithKline PLC, Pfizer Inc., and AstraZeneca focus on expanding their product portfolios, investing in research and development, and forming strategic partnerships to strengthen their market positions.
- Complex regulatory compliance, high production costs, and quality assurance requirements present significant restraints for new entrants and established manufacturers in the market.
- North America and Europe maintain leadership due to advanced healthcare systems and active pharmaceutical research, while Asia Pacific emerges as a key growth engine driven by large patient populations and rising healthcare investments.
- The market sees a strong shift toward outsourcing sterile injectable manufacturing and the adoption of innovative drug delivery technologies, enabling greater efficiency and faster access to advanced therapies globally.
Market Drivers
Rising Prevalence of Chronic Diseases and Growing Need for Effective Therapies
The Sterile Injectable Drugs Market experiences strong growth due to the rising burden of chronic diseases, such as cancer, diabetes, and autoimmune disorders. These conditions require fast-acting and reliable treatments, prompting healthcare providers to rely on sterile injectables for immediate therapeutic effects. The increasing frequency of hospitalizations and outpatient procedures further drives demand for injectable medications that support rapid patient stabilization. Governments and health organizations are promoting early disease detection and advanced treatment protocols, making sterile injectables a preferred choice in many critical care scenarios. The rising number of elderly patients with multiple comorbidities also leads to higher adoption rates of injectable therapies. This driver remains critical for the market’s sustained expansion, ensuring that patient needs for efficient drug delivery are consistently met.
- For instance, the increasing prevalence of chronic diseases such as cancer, diabetes, and cardiovascular disorders is fueling demand for sterile injectable treatments.
Advancements in Biologics and Biosimilars Accelerate Market Expansion
Biologics and biosimilars contribute significantly to the Sterile Injectable Drugs Market, offering innovative therapies for complex and previously untreatable diseases. Pharmaceutical companies invest in research and development to introduce new injectable biologics and expand biosimilar portfolios. It enables treatment of rare conditions and improves outcomes for patients with limited options. Increasing approvals for biologic drugs and biosimilars across global regulatory agencies encourage market entrants and intensify competition. Healthcare systems favor these advanced products for their efficacy and safety profiles, while patients benefit from improved access to life-saving therapies. The integration of advanced drug formulations and delivery technologies ensures reliable and efficient administration, fueling further growth in this market.
Stringent Regulatory Standards Drive Quality and Compliance
Regulatory agencies enforce rigorous quality standards in the Sterile Injectable Drugs Market to safeguard patient safety and ensure product efficacy. Companies respond by investing in advanced manufacturing facilities and robust quality assurance programs to comply with evolving regulations. It pushes manufacturers to adopt state-of-the-art technologies such as aseptic processing, real-time monitoring, and automated packaging systems. Regulatory scrutiny strengthens trust in injectable therapies among healthcare professionals and patients. The focus on compliance not only minimizes risks associated with contamination and recalls but also differentiates reputable manufacturers. This dynamic continues to shape industry practices and underpins sustainable market growth.
- For instance, regulatory scrutiny strengthens trust in injectable therapies among healthcare professionals and patients, ensuring compliance with evolving international guidelines.
Adoption of Prefilled Syringes and Outsourcing Trends Enhance Efficiency
Shifting preferences toward prefilled syringes and ready-to-administer injectables drive transformation in the Sterile Injectable Drugs Market. Pharmaceutical companies and healthcare providers choose these solutions to improve dosing accuracy, reduce medication errors, and simplify logistics. The outsourcing of sterile injectable production to specialized contract manufacturing organizations accelerates time-to-market and enables cost-effective scaling. It also allows companies to concentrate resources on research, development, and commercialization of innovative therapies. Global supply chain integration and rising demand for high-quality, reliable injectable products continue to stimulate investments in advanced manufacturing partnerships. This trend optimizes efficiency and supports market competitiveness across regions.
Market Trends
Rising Adoption of Ready-to-Use and Prefilled Injectable Solutions
The Sterile Injectable Drugs Market witnesses a clear shift toward ready-to-use formulations and prefilled syringes. Healthcare facilities and professionals prefer these products for their ability to reduce preparation time and minimize risks of contamination or dosing errors. It simplifies logistics in clinical settings, supporting faster administration and improving patient safety. Pharmaceutical manufacturers invest in new packaging and device technologies to meet the growing demand for these convenient formats. Ready-to-use injectables now play a vital role in outpatient care, emergency response, and home healthcare environments. Their rising popularity strengthens product portfolios and helps companies differentiate themselves in a competitive landscape.
- For instance, the adoption of prefilled syringes has grown significantly, improving patient compliance and reducing contamination risks.
Expansion of Biologics and Specialty Injectables Pipeline
Biologics and specialty drugs are reshaping the Sterile Injectable Drugs Market, leading to an expanded product pipeline. Companies prioritize development of targeted therapies for oncology, autoimmune, and rare diseases, where injectable formats offer superior bioavailability. The market benefits from increased regulatory approvals of novel biologics and biosimilars, which address unmet medical needs. It creates opportunities for innovation in drug delivery systems that enhance patient experience and compliance. The trend toward personalized medicine and precision therapies further accelerates pipeline diversification. This ongoing evolution ensures that the market remains dynamic and responsive to advances in science and healthcare needs.
- For instance, monoclonal antibodies have emerged as a dominant segment due to their targeted therapeutic applications across various medical conditions.
Integration of Digital Technologies in Manufacturing and Supply Chain
Digital transformation influences every stage of the Sterile Injectable Drugs Market, from manufacturing to distribution. Automation, artificial intelligence, and IoT enable real-time monitoring, predictive maintenance, and improved quality control in production facilities. It allows for faster response to disruptions and supports greater transparency throughout the supply chain. Pharmaceutical firms adopt advanced analytics to optimize inventory and reduce waste, increasing efficiency in global distribution networks. The integration of digital solutions ensures regulatory compliance and traceability, which is essential for patient safety. These advancements set new industry benchmarks and foster resilience in a rapidly changing environment.
Growth of Outsourcing and Contract Manufacturing Partnerships
Outsourcing continues to play a pivotal role in the Sterile Injectable Drugs Market, with pharmaceutical companies collaborating with contract manufacturing organizations for specialized production capabilities. It enables firms to access advanced technologies and scale up production quickly without significant capital investment. The trend helps address capacity constraints and rising demand for complex injectable therapies, especially in emerging markets. Strategic partnerships focus on quality, speed, and regulatory expertise, which enhances competitiveness and market reach. Outsourcing also allows companies to concentrate resources on core research and commercialization activities. This collaborative approach supports a flexible, efficient, and globally integrated market structure.
Market Challenges Analysis
Complex Regulatory Compliance and Stringent Quality Requirements Create Barriers The Sterile Injectable Drugs Market faces significant challenges from complex regulatory compliance and stringent quality requirements. Manufacturers must adhere to rigorous standards for aseptic processing, packaging, and labeling to ensure patient safety and product efficacy. It demands continuous investments in advanced manufacturing facilities, robust quality control systems, and frequent regulatory inspections. Navigating different global regulatory frameworks further complicates market entry and product approvals, particularly for new entrants and smaller companies. Delays in approvals or non-compliance can lead to costly recalls, reputational damage, and restricted access to key markets. These factors place immense pressure on firms to maintain consistent quality while adapting to evolving standards.
- For instance, the U.S. FDA and European Medicines Agency (EMA) require extensive documentation and validation for sterile injectable drug approvals.
High Production Costs and Supply Chain Vulnerabilities Impact Market Stability
Production costs in the Sterile Injectable Drugs Market remain high due to specialized infrastructure, skilled labor, and advanced technologies needed for sterile manufacturing. It limits profit margins, especially for low-volume or generic injectables, where price competition is intense. Disruptions in raw material supply or shortages of critical components can cause production delays and inventory challenges, affecting product availability in the market. Global events, such as pandemics or geopolitical tensions, expose vulnerabilities in the supply chain and highlight the need for resilient sourcing strategies. Maintaining efficient logistics, ensuring timely distribution, and managing costs remain critical concerns for manufacturers operating in this demanding sector.
Market Opportunities
Expansion into Emerging Markets and Growing Healthcare Investments Drive Growth
The Sterile Injectable Drugs Market presents significant opportunities for expansion into emerging markets, where rising healthcare investments and improving infrastructure support broader access to advanced therapies. Many governments are increasing healthcare budgets and focusing on modernizing hospitals, clinics, and distribution networks. It enables pharmaceutical companies to introduce innovative sterile injectables to new patient populations, driving both volume and value growth. Partnerships with local firms and healthcare providers can accelerate market penetration while addressing region-specific regulatory and logistical needs. The growing prevalence of chronic diseases in developing regions amplifies demand for effective injectable treatments. Companies that adapt strategies for local preferences and compliance can establish a strong competitive presence.
Advances in Drug Delivery Technologies and Personalized Medicine Offer Differentiation
Rapid advances in drug delivery technologies create new opportunities for differentiation within the Sterile Injectable Drugs Market. Pharmaceutical companies are investing in smart injectables, auto-injectors, and long-acting formulations that improve patient compliance and therapeutic outcomes. It enables the development of targeted therapies tailored to individual patient profiles, supporting the rise of personalized medicine. Collaborations with technology providers and research institutions accelerate the introduction of next-generation products. Innovations in formulation and packaging extend shelf life and simplify storage, making these therapies more accessible across varied healthcare environments. These opportunities position companies to lead in both innovation and patient-centric care.
Market Segmentation Analysis:
By Type:
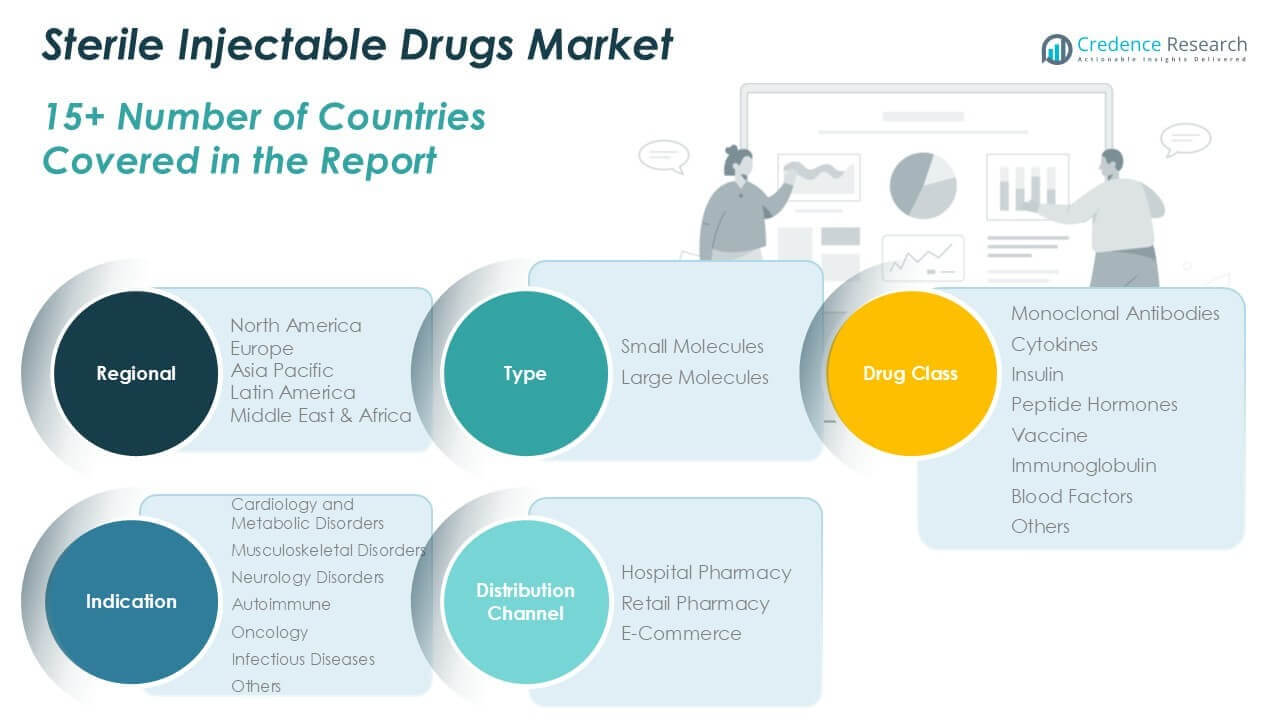
The market divides into small molecules and large molecules. Small molecules continue to dominate due to their established clinical use, faster development timelines, and broad application in chronic and acute conditions. They offer ease of formulation and widespread adoption in generic injectables. Large molecules, including complex biologics, are gaining share through their effectiveness in treating rare and life-threatening diseases. It reflects the growing importance of biotechnology in drug development, leading to increased investment in research and manufacturing capabilities.
By Drug Class:
The market encompasses monoclonal antibodies, cytokines, insulin, peptide hormones, vaccines, immunoglobulins, and blood factors. Monoclonal antibodies lead this segment, driven by rising demand for targeted therapies in oncology, autoimmune, and infectious diseases. Cytokines and peptide hormones support innovative treatments for a range of immune and metabolic disorders, while insulin remains a cornerstone therapy for diabetes. Vaccines have experienced substantial growth due to global immunization initiatives and heightened focus on pandemic preparedness. Immunoglobulins and blood factors address critical care needs in immune deficiencies and hematological conditions, underscoring the market’s role in supporting patient outcomes across complex disease areas.
By Indication:
The Sterile Injectable Drugs Market serves a wide range of therapeutic areas, including cardiology and metabolic disorders, musculoskeletal disorders, neurology disorders, autoimmune diseases, oncology, infectious diseases, and others. Oncology leads the indication segment, fueled by continuous advancements in cancer therapeutics and the introduction of new injectable biologics. Autoimmune and infectious diseases present strong demand for innovative and fast-acting therapies, reflecting changes in global disease patterns and patient needs. Cardiology and metabolic disorders, musculoskeletal and neurology disorders also drive substantial growth, highlighting the versatility of sterile injectables across acute and chronic conditions. This comprehensive segmentation ensures that the market remains responsive to evolving clinical demands, technological advancements, and shifting healthcare priorities worldwide.
Segments:
Based on Type:
- Small Molecules
- Large Molecules
Based on Drug Class:
- Monoclonal Antibodies
- Cytokines
- Insulin
- Peptide Hormones
- Vaccine
- Immunoglobulin
- Blood Factors
Based on Indication:
- Cardiology and Metabolic Disorders
- Musculoskeletal Disorders
- Neurology Disorders
- Autoimmune
- Oncology
- Infectious Diseases
- Others
Based on Distribution Channel:
- Hospital Pharmacy
- Retail Pharmacy
- E-Commerce
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Sterile Injectable Drugs Market
North America Sterile Injectable Drugs Market grew from USD 1,405.82 million in 2018 to USD 2,520.13 million in 2024 and is projected to reach USD 6,083.04 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.9%. North America is holding a 32% market share. The United States leads regional demand due to its advanced healthcare infrastructure, strong presence of global pharmaceutical companies, and significant investment in biologics and specialty injectables. Canada also contributes meaningfully, benefiting from universal healthcare systems and high chronic disease prevalence. The region’s strict regulatory standards and emphasis on quality assurance further bolster market expansion, while increasing outsourcing and contract manufacturing foster supply chain efficiency.
Europe Sterile Injectable Drugs Market
Europe Sterile Injectable Drugs Market grew from USD 995.77 million in 2018 to USD 1,729.00 million in 2024 and is set to reach USD 3,850.21 million by 2032, posting a CAGR of 9.7%. Europe accounts for 20% of the global market share. Germany, France, and the United Kingdom are key markets, driven by a robust pharmaceutical manufacturing base and growing demand for advanced therapies. Regulatory harmonization across the European Union, strong R&D activity, and expanding biosimilars portfolio support regional growth. Aging populations and high healthcare spending ensure sustained demand for sterile injectables across public and private sectors.
Asia Pacific Sterile Injectable Drugs Market
Asia Pacific Sterile Injectable Drugs Market grew from USD 1,711.57 million in 2018 to USD 3,241.26 million in 2024 and will reach USD 8,325.08 million by 2032, with a CAGR of 11.7%. Asia Pacific is holding a 43% market share, the largest globally. China, India, and Japan drive regional momentum with rising healthcare investments, large patient populations, and an increasing focus on generic and biosimilar injectables. Governments are promoting pharmaceutical manufacturing and regulatory improvements, making the region a focal point for industry expansion. Rapid urbanization and rising chronic disease rates further accelerate market demand.
Latin America Sterile Injectable Drugs Market
Latin America Sterile Injectable Drugs Market grew from USD 137.80 million in 2018 to USD 245.89 million in 2024 and will reach USD 488.30 million by 2032, at a CAGR of 8.2%. Latin America holds a 3% market share. Brazil and Mexico represent the largest contributors, supported by public healthcare programs, increased disease awareness, and the adoption of innovative therapies. Regulatory modernization and expansion of local production capacity are improving access to sterile injectables in the region. Market growth remains steady as healthcare infrastructure advances.
Middle East Sterile Injectable Drugs Market
Middle East Sterile Injectable Drugs Market grew from USD 99.58 million in 2018 to USD 161.84 million in 2024 and is anticipated to reach USD 312.32 million by 2032, achieving a CAGR of 7.8%. The Middle East accounts for 2% of the global market share. Saudi Arabia and the United Arab Emirates are key countries investing in healthcare modernization and pharmaceutical imports. Efforts to upgrade hospital infrastructure and adopt international quality standards fuel demand for injectable therapies. Strategic partnerships and government initiatives support steady market penetration.
Africa Sterile Injectable Drugs Market
Africa Sterile Injectable Drugs Market grew from USD 43.28 million in 2018 to USD 91.66 million in 2024 and is projected to reach USD 153.55 million by 2032, with a CAGR of 5.8%. Africa holds a 1% market share. South Africa and Egypt are leading countries, focusing on expanding healthcare access and improving supply chains. Limited local manufacturing capacity and economic constraints present challenges, but international aid and public health programs are boosting demand for essential sterile injectables across the continent.
Key Player Analysis
- GlaxoSmithKline PLC
- Baxter International Inc.
- AstraZeneca
- Johnson & Johnson Services, Inc.
- Sanofi
- Merck & Co., Inc.
- Gilead Sciences Inc.
- Pfizer Inc.
- Novartis AG
- Novo Nordisk A/S
Competitive Analysis
The Sterile Injectable Drugs Market features a highly competitive landscape, led by major global pharmaceutical companies including GlaxoSmithKline PLC, Baxter International Inc., AstraZeneca, Johnson & Johnson Services, Inc., Sanofi, Merck & Co., Inc., Gilead Sciences Inc., Pfizer Inc., Novartis AG, and Novo Nordisk A/S. These companies command strong market positions by leveraging extensive research and development capabilities, large-scale manufacturing infrastructure, and broad product portfolios that cover critical therapeutic areas such as oncology, immunology, metabolic disorders, and infectious diseases. They invest consistently in innovation, focusing on biologics, biosimilars, and novel drug delivery technologies to address evolving patient needs and differentiate their offerings. Strategic collaborations, mergers and acquisitions, and partnerships with contract manufacturing organizations further enhance their agility and expand their reach in both developed and emerging markets. Regulatory expertise and a strong global presence enable these firms to navigate complex compliance landscapes and capitalize on market opportunities efficiently. As demand for sterile injectable drugs continues to increase, leading players sustain their advantage by prioritizing product quality, expanding global distribution channels, and accelerating the introduction of next-generation therapies to meet the diverse requirements of healthcare providers and patients worldwide.
Recent Developments
- In June 2024, PCI Pharma Services company announced the expansion of its packaging operations in Ireland. It invested in a new facility in Dublin, which would focus on secondary packaging, labeling, and serialization services. The expansion is part of PCI's ongoing commitment to providing comprehensive pharmaceutical packaging solutions to its clients across Europe.
- In May 2024, Sharp, a worldwide frontrunner in contract packaging, clinical supply services, and small-scale sterile manufacturing, has unveiled its intentions to expand its Macungie, Pennsylvania, facility in North America. This move aims to bolster the site's production capacity for the secondary packaging of sterile injectables. Macungie's expansion will boost its capacity for secondary packaging activities. These include vial labeling, assembly and labeling of pre-filled syringes (PFS), assembly and labeling of autoinjectors/pens, as well as kitting and cartoning of injectables, catering specifically to pharmaceutical and biotech firms.
- In April 2024, Eli Lilly and Company entered into a definitive agreement with Nexus Pharmaceuticals, LLC, a prominent sterile manufacturer in the pharmaceutical sector, to acquire one of Nexus's manufacturing facilities. By acquiring this FDA-approved facility in Pleasant Prairie, Wisconsin, Lilly is set to bolster its global network for parenteral (injectable) product manufacturing, catering to the rising demand for its medicines. Lilly projects that production at this facility may commence by late 2025.
- In February 2024, Novo Holdings, under the Novo Nordisk Foundation, acquired Catalent for USD 16.5 billion. This acquisition is part of Novo Holdings’ strategy to utilize its Wegovy cash and expand its manufacturing capabilities. The deal includes Novo Nordisk acquiring three of Catalent’s fill-finish sites from Novo Holdings for USD 11 billion upfront. These sites specialize in sterile drug filling and are expected to enhance Novo Nordisk’s manufacturing network for current and future treatments for diabetes and obesity. The acquisition is set to increase Novo Nordisk’s filling capacity starting in 2026 gradually.
- In December 2023, Cipla filed a patent for a stable, ready-to-use, extended-release injectable formulation of aripiprazole aimed at treating schizophrenia and related disorders. The patent outlined a formulation that maintains stability over 6 months in sealed, sterile conditions, with total impurities not exceeding 1.0% when stored at 25°C and 60% relative humidity.
Market Concentration & Characteristics
The Sterile Injectable Drugs Market demonstrates a moderately high level of market concentration, with a handful of global pharmaceutical companies holding significant market shares and setting industry standards. It features strong barriers to entry due to complex regulatory requirements, high capital investment for advanced manufacturing facilities, and stringent quality assurance standards. The market is characterized by rapid innovation, frequent product launches, and a continuous push for novel drug delivery technologies. Leading players leverage their global distribution networks, broad product portfolios, and research expertise to sustain their competitive edge. It also reflects a high degree of collaboration through partnerships with contract manufacturing organizations and strategic alliances aimed at expanding reach and accelerating product development. Demand for sterile injectables spans a wide range of therapeutic areas, underscoring the market’s versatility and critical role in modern healthcare delivery.
Report Coverage
The research report offers an in-depth analysis based on Type, Drug Class, Indication, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Sterile Injectable Drugs Market is projected to experience steady growth, driven by increasing demand for biologics and biosimilars across various therapeutic areas.
- Advancements in drug delivery technologies, such as auto-injectors and prefilled syringes, are enhancing patient compliance and expanding the market reach.
- The rising prevalence of chronic diseases, including cancer and diabetes, is fueling the need for effective and rapid-acting injectable treatments.
- Expansion into emerging markets, particularly in Asia Pacific and Latin America, offers significant growth opportunities due to improving healthcare infrastructure and rising healthcare expenditures.
- Strategic collaborations and partnerships among pharmaceutical companies are fostering innovation and accelerating the development of new sterile injectable drugs.
- Regulatory support and streamlined approval processes are facilitating quicker market entry for novel injectable therapies.
- The shift towards personalized medicine is increasing the demand for targeted injectable treatments tailored to individual patient needs.
- Investments in advanced manufacturing facilities are ensuring high-quality production standards and meeting the growing global demand.
- The integration of digital technologies in manufacturing and supply chain management is improving efficiency and traceability in the production of sterile injectables.
- Ongoing research and development efforts are expected to introduce a new wave of sterile injectable drugs, addressing unmet medical needs and expanding therapeutic options.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic conditions such as cancer, diabetes, and autoimmune disorders is driving demand for sterile injectable drugs, as these therapies offer rapid and effective treatment options for acute and long-term management.
Advancements in Biologics and Biosimilars
Ongoing innovation and approvals in biologics and biosimilars are expanding the range of injectable therapies available, enabling treatment of complex and previously untreatable diseases and fueling market growth.
Adoption of Ready-to-Use and Prefilled Injectables
Healthcare providers are increasingly adopting ready-to-use and prefilled injectable formats, which improve dosing accuracy, reduce contamination risk, and streamline administration in both hospital and outpatient settings.
Expansion of Contract Manufacturing and Outsourcing
Pharmaceutical companies are leveraging contract manufacturing organizations to scale up production, reduce costs, and accelerate time-to-market for sterile injectables, supporting broader access and efficiency.
Stringent Regulatory Standards and Quality Assurance
Tightening regulatory requirements are prompting manufacturers to invest in advanced technologies and quality systems, ensuring product safety and efficacy, which in turn builds trust and supports market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Sterile Injectable Drugs Market?
What factors are driving the growth of the Sterile Injectable Drugs Market?
What are the key segments within the Sterile Injectable Drugs Market?
Who are the major players in the Sterile Injectable Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Small Molecules
- 1.2.2 Large Molecules
- 1.3 By Drug Class
- 1.3.1 Monoclonal Antibodies
- 1.3.2 Cytokines
- 1.3.3 Insulin
- 1.3.4 Peptide Hormones
- 1.3.5 Vaccine
- 1.3.6 Immunoglobulin
- 1.3.7 Blood Factors
- 1.4 By Indication
- 1.4.1 Oncology
- 1.4.2 Autoimmune
- 1.4.3 Infectious Diseases
- 1.4.4 Cardiology and Metabolic Disorders
- 1.4.5 Musculoskeletal Disorders
- 1.4.6 Neurology Disorders
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,989.78 million → 2032: USD 19,212.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sterile Injectable Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sterile Injectable Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sterile Injectable Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sterile Injectable Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sterile Injectable Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sterile Injectable Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sterile Injectable Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sterile Injectable Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,989.78 million → 2032: USD 19,212.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sterile Injectable Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small Molecules
- 12.3.7.2 Large Molecules
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Monoclonal Antibodies
- 12.4.7.2 Cytokines
- 12.4.7.3 Insulin
- 12.4.7.4 Peptide Hormones
- 12.4.7.5 Vaccine
- 12.4.7.6 Immunoglobulin
- 12.4.7.7 Blood Factors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Autoimmune
- 12.5.7.3 Infectious Diseases
- 12.5.7.4 Cardiology and Metabolic Disorders
- 12.5.7.5 Musculoskeletal Disorders
- 12.5.7.6 Neurology Disorders
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sterile Injectable Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sterile Injectable Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sterile Injectable Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 GlaxoSmithKline PLC
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Baxter International Inc.
- 17.4 AstraZeneca
- 17.5 Johnson & Johnson Services, Inc.
- 17.6 Sanofi
- 17.7 Merck & Co., Inc.
- 17.8 Gilead Sciences Inc.
- 17.9 Pfizer Inc.
- 17.10 Novartis AG
- 17.11 Novo Nordisk A/S
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

