
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Antibiotics market Size 2024 | USD 50,915 million |
| Antibiotics market, CAGR | 3.67% |
| Antibiotics market Size 2032 | USD 67,931.3 million |
Market Overview:
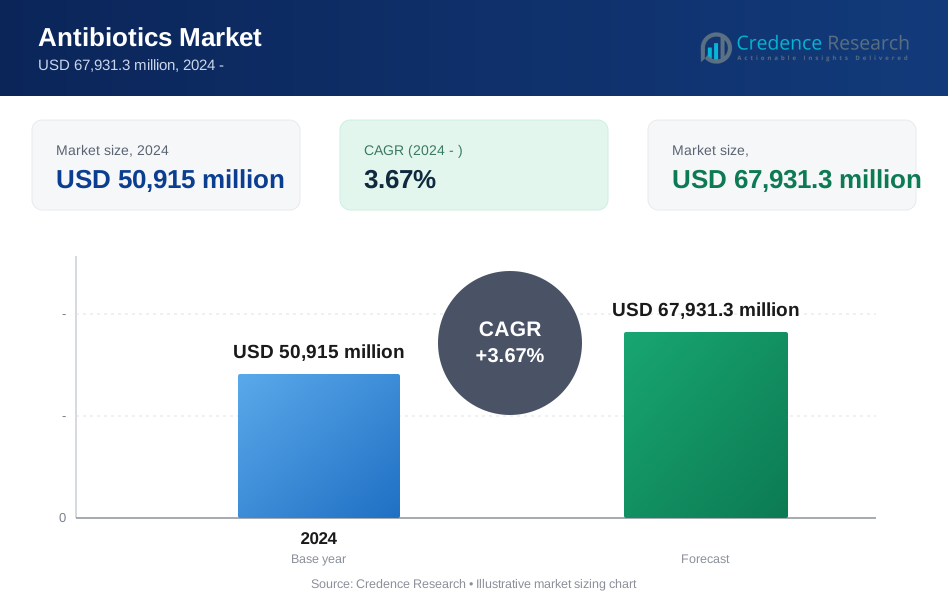
The global antibiotics market is projected to grow from USD 50,915 million in 2024 to approximately USD 67,931.3 million by 2032, at a compound annual growth rate (CAGR) of 3.67%. This market expansion is primarily driven by the rising prevalence of bacterial infections and the increasing use of antibiotics in treating a wide range of infectious diseases, particularly respiratory, urinary, and skin infections. With the growing emergence of antibiotic-resistant bacteria, there is a rising demand for new and effective antibiotics, which further fuels investment in research and development for novel antibiotics and combination therapies. Market growth is also supported by advancements in diagnostic technologies that enable faster, more accurate detection of infections, facilitating timely and targeted antibiotic treatments.
Several factors drive the antibiotics market, including the high incidence of infectious diseases globally and the expansion of healthcare infrastructure in emerging economies, leading to increased access to antibiotics. The global threat posed by antibiotic resistance has spurred governments and health organizations to promote the prudent use of antibiotics and incentivize R&D in developing effective antibiotics. Additionally, the ongoing burden of hospital-acquired infections (HAIs) and increased hospitalizations due to complex diseases contribute significantly to the demand for antibiotics. Market dynamics are also influenced by technological advancements that enhance the efficacy and formulation of antibiotics, as well as growing awareness and accessibility to healthcare in low- and middle-income countries.
Regionally, North America holds the largest share of the antibiotics market, supported by advanced healthcare infrastructure, high awareness levels, and strong regulatory frameworks that promote antibiotic R&D. Europe follows closely, with significant market contributions from countries like Germany, the U.K., and France, driven by a strong focus on combatting antimicrobial resistance. The Asia-Pacific region is anticipated to witness the fastest growth due to a high incidence of infectious diseases, increased healthcare spending, and expanding access to healthcare services in countries such as China and India. These factors collectively contribute to the antibiotics market's sustained growth and evolving demand patterns across regions.
Market Drivers:
Rising Prevalence of Infectious Diseases:
The increasing incidence of infectious diseases is a significant driver of growth in the antibiotics market. According to the Centers for Disease Control and Prevention (CDC), there were over 31 million cases of influenza reported in the U.S. during the 2022-2023 flu season, highlighting the ongoing public health challenge posed by infectious diseases. This surge in infections necessitates effective treatment options, thereby driving demand for antibiotics. For instance, the World Health Organization (WHO) estimates that bacterial infections are responsible for approximately 1.5 million deaths annually, underscoring the urgent need for effective antimicrobial therapies.
Advancements in Research and Development:
Ongoing advancements in research and development are pivotal to the growth of the antibiotics market. Pharmaceutical companies are increasingly focusing on developing novel antibiotics and combination therapies to combat antibiotic resistance, a growing global concern. For instance, A recent report from Pfizer indicated that they are actively engaged in clinical trials for a new antibiotic combination targeting multi-drug resistant bacteria, demonstrating a commitment to innovation in this field. The industry's dedication to R&D not only enhances treatment options but also addresses the pressing issue of antimicrobial resistance, which is critical for sustaining market growth.
Government Support and Regulatory Frameworks:
Supportive government initiatives and regulatory frameworks play a crucial role in driving the antibiotics market. Many governments are increasing their investment in healthcare infrastructure and antibiotic stewardship programs aimed at promoting responsible use of antibiotics. For instance, the U.S. government has allocated substantial funds to combat antibiotic resistance through programs like the National Action Plan for Combating Antibiotic-Resistant Bacteria (CARB). These initiatives not only facilitate research and development but also ensure that effective antibiotics remain accessible to healthcare providers and patients.
Growing Demand for Generic Antibiotics:
The demand for generic antibiotics is another key factor propelling market growth. The affordability of generic formulations makes them an attractive option for healthcare providers and patients alike. According to a report by the American Society of Health-System Pharmacists, generic antibiotics accounted for nearly 80% of all antibiotic prescriptions filled in 2023. This trend is further supported by favorable regulatory policies that encourage the production and distribution of generic drugs, thereby enhancing access to essential medications and driving overall market expansion.
Market Trends:
Focus on Antibiotic Stewardship Programs:
Antibiotic stewardship programs are gaining traction as healthcare providers and institutions prioritize responsible antibiotic use to combat resistance. These programs aim to optimize antibiotic prescribing practices, ensuring that patients receive the most appropriate treatment while minimizing the risk of developing resistant strains. For instance, the CDC reported that hospitals implementing stewardship initiatives saw a 20-50% reduction in unnecessary antibiotic prescriptions. This trend not only enhances patient safety but also supports the long-term efficacy of existing antibiotics, thereby influencing market dynamics positively.
Emergence of Combination Therapies:
The development of combination therapies is becoming a prominent trend in the antibiotics market. Pharmaceutical companies are increasingly focusing on creating formulations that combine multiple antibiotics or synergistic agents to enhance efficacy against resistant bacteria. For example, in 2023, Merck & Co. announced the launch of a new combination therapy designed to target multi-drug resistant infections effectively. This approach addresses the growing concern of antibiotic resistance and provides healthcare providers with more effective treatment options, reflecting a shift towards innovative solutions in infectious disease management.
Advancements in Research and Development:
Research and development continue to play a critical role in shaping the antibiotics market. Companies are investing significantly in discovering new antibiotics and alternative therapies to address the challenges posed by resistant bacteria. A report from GlaxoSmithKline highlighted their commitment to developing novel antibiotics, with several candidates currently in clinical trials aimed at treating infections caused by resistant pathogens. This focus on R&D not only drives innovation but also ensures that the market remains responsive to evolving bacterial threats.
Increased Demand for Generic Antibiotics:
The demand for generic antibiotics is on the rise, driven by their affordability and accessibility. According to a report by the American Society of Health-System Pharmacists, generic antibiotics accounted for approximately 80% of all antibiotic prescriptions filled in 2023. This trend is particularly significant in regions where healthcare costs are a concern, as generic options provide effective treatment without the high price tag associated with branded medications. The growing acceptance of generics among healthcare providers and patients alike is expected to continue influencing market dynamics positively as they seek cost-effective solutions for managing bacterial infections.
Market Challenges Analysis:
Regulatory Hurdles:
The antibiotics market faces significant regulatory challenges that can impede the timely development and approval of new drugs. Regulatory authorities, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), impose stringent guidelines for antibiotic approval, which can lead to lengthy and costly processes. For instance, the FDA's complex requirements for clinical trials often result in delays that can extend up to several years, discouraging pharmaceutical companies from investing in antibiotic research. This bureaucratic environment hampers innovation and limits the availability of new antibiotics needed to combat emerging resistant strains.
Antibiotic Resistance:
The growing issue of antibiotic resistance poses a formidable challenge for the market. According to the Centers for Disease Control and Prevention (CDC), more than 2.8 million antibiotic-resistant infections occur in the United States each year, leading to over 35,000 deaths. This alarming trend not only complicates treatment options but also increases healthcare costs significantly. The emergence of resistant bacteria diminishes the effectiveness of existing antibiotics, creating a pressing need for new solutions while simultaneously constraining market growth due to heightened scrutiny over antibiotic prescriptions.
Economic Viability:
The economic viability of developing new antibiotics is another critical restraint. The high costs associated with research and development, coupled with the relatively low return on investment, discourage pharmaceutical companies from pursuing antibiotic innovation. A report highlighted that many newly developed antibiotics enter a market dominated by generics, resulting in limited profitability. As a result, companies may prioritize more lucrative therapeutic areas over antibiotics, further exacerbating the existing shortage of effective treatments.
Public Awareness and Misuse:
Public awareness regarding the appropriate use of antibiotics remains insufficient, contributing to their misuse and over-prescription. The CDC has noted that nearly 30% of antibiotics prescribed in outpatient settings are unnecessary. This misuse not only leads to increased resistance but also complicates treatment protocols for healthcare providers. Efforts to educate both patients and healthcare professionals about responsible antibiotic use are essential but often face challenges in implementation, limiting their effectiveness in curbing inappropriate usage patterns.
Market Segmentation Analysis:
By Type:
The antibiotics market is primarily divided into broad-spectrum and narrow-spectrum antibiotics. Broad-spectrum antibiotics, capable of targeting a wide range of bacterial infections, hold a significant market share due to their applicability in treating multiple infection types. Narrow-spectrum antibiotics, however, are becoming increasingly important as healthcare systems prioritize targeted therapies to combat antibiotic resistance and improve patient outcomes.
By Technology:
Key technological segments in the antibiotics market include synthetic, semisynthetic, and natural antibiotics. Synthetic and semisynthetic antibiotics dominate the market, as these formulations allow for enhanced stability, efficacy, and scalability in production. Advances in biotechnology are also driving interest in natural antibiotics, derived from bacteria and fungi, which are particularly useful as novel alternatives to combat antibiotic-resistant strains.
By End User:
The primary end users of antibiotics include hospitals, clinics, and outpatient facilities. Hospitals represent the largest segment due to high demand for antibiotic treatments in critical care settings, particularly for patients with hospital-acquired infections. Clinics and outpatient settings also contribute significantly, as they cater to infections that do not require hospitalization, supporting substantial use of oral and injectable antibiotics for minor infections and follow-up treatments. This segmentation reflects the multifaceted needs within healthcare, emphasizing both innovation and accessibility across antibiotic types, technological developments, and diverse end users in the market.
Segmentations:
By Drug Class
- Penicillin
- Cephalosporin
- Aminoglycosides
- Tetracycline
- Macrolides
- Fluoroquinolones
- Sulfonamides
- Others
By Application
- Skin Infections
- Respiratory Infections
- Urinary Tract Infections
- Septicemia
- Ear Infection
- Gastrointestinal Infections
- Others
By Route of Administration
- Oral
- Parenteral
- Others
By Distribution Channel
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the antibiotics market, capturing approximately 30% of the global market. This region’s dominance is driven by a robust healthcare infrastructure, high awareness of antibiotic usage, and significant investment in research and development. The United States is a key contributor within this region, owing to its advanced pharmaceutical industry, extensive government support for antibiotic R&D, and established regulatory frameworks that prioritize combatting antibiotic resistance. High rates of healthcare access and the prevalence of hospital-acquired infections (HAIs) further increase the demand for antibiotics. Efforts by public health organizations, such as the Centers for Disease Control and Prevention (CDC), promote the prudent use of antibiotics, adding to market growth.
Europe
Europe accounts for around 25% of the global antibiotics market, supported by strong healthcare systems and a focus on reducing antimicrobial resistance (AMR). Countries like Germany, the U.K., and France are leading contributors, driven by high healthcare spending and proactive regulatory policies promoting antibiotic stewardship. The European Union’s One Health Action Plan against AMR plays a critical role in addressing AMR, encouraging investments in antibiotic alternatives and fostering innovations within the antibiotics sector. As a result, Europe remains a significant region within the antibiotics market, with demand concentrated around both broad-spectrum and specialized, narrow-spectrum antibiotics.
Asia-Pacific
The Asia-Pacific region is anticipated to experience the fastest growth in the antibiotics market, projected to capture approximately 28% of the global share by 2032. This growth is driven by high incidences of infectious diseases, rapid population growth, and increasing healthcare investments in countries like China, India, and Japan. Rising disposable incomes, improving healthcare access, and the prevalence of antibiotic-resistant infections further fuel demand. Government initiatives in these countries, including subsidies for antibiotic production and distribution, support market expansion. Moreover, growing awareness and improvements in healthcare infrastructure, especially in rural areas, enable broader antibiotic access, making Asia-Pacific a critical market.
Latin America
Latin America holds a moderate share of the antibiotics market, accounting for around 10% of the global market. The region’s demand is fueled by rising cases of bacterial infections and increasing healthcare expenditure in countries like Brazil, Argentina, and Mexico. Expanding healthcare infrastructure and increased access to healthcare services in urban and semi-urban areas contribute to the market’s growth. However, challenges like regulatory variations across countries can impact the market’s overall expansion in this region.
Middle East & Africa
The Middle East & Africa represent approximately 7% of the global antibiotics market. Growth in this region is supported by an increasing prevalence of infectious diseases, expanding healthcare infrastructure, and government efforts to improve healthcare accessibility. Countries such as Saudi Arabia, the UAE, and South Africa are leading the market, driven by rising healthcare awareness and infrastructure improvements. Despite growth potential, the market remains smaller compared to other regions due to limited resources and varying regulatory frameworks.
Key Player Analysis:
- Johnson & Johnson
- GlaxoSmithKline plc (GSK)
- Pfizer Inc.
- Merck & Co., Inc.
- Bayer AG
- Novartis AG
- Sanofi SA
- Abbott Laboratories
- Hoffmann-La Roche AG
- Eli Lilly and Company
Competitive Analysis:
The antibiotics market is highly competitive, led by pharmaceutical giants such as Johnson & Johnson, Pfizer, Merck & Co., and GlaxoSmithKline (GSK), who dominate through extensive R&D, global distribution networks, and robust antibiotic portfolios. These key players continuously invest in developing new antibiotics to combat rising antibiotic resistance, a significant healthcare concern worldwide. Companies focus on both broad-spectrum and targeted therapies, aiming to enhance treatment efficacy and reduce resistance risks. The competitive landscape is also shaped by mid-sized firms and generic manufacturers, particularly in emerging regions, where affordability and accessibility are crucial. Strategic partnerships, acquisitions, and licensing agreements are common as companies seek to expand their antibiotic offerings and geographical reach. This competitive environment emphasizes innovation, regulatory expertise, and adaptation to global antibiotic stewardship initiatives, which promote responsible antibiotic use to sustain long-term effectiveness.
Recent Developments:
- In 2023, Pfizer announced promising Phase III results for its antibiotic combination aztreonam-avibactam (ATM-AVI), designed to target Gram-negative bacterial infections resistant to other treatments. Positive outcomes from the ASSEMBLE and REVISIT trials demonstrated this drug’s efficacy, providing hope for patients with limited treatment options and supporting Pfizer’s planned regulatory submissions in major markets, including the U.S. and EU.
- GSK’s gepotidacin, an investigational oral antibiotic for uncomplicated urinary tract infections (uUTIs), reached key milestones in 2023. The drug, with a novel mechanism, showed success in Phase III EAGLE-2 and EAGLE-3 trials, potentially positioning it as the first new UTI antibiotic in over two decades. GSK plans to seek FDA approval based on these promising results.
- Pfizer has been actively engaging in global antimicrobial stewardship initiatives. In 2022, the company collaborated with BD and Wellcome Trust to enhance antimicrobial stewardship practices worldwide, focusing on diagnostics to improve targeted antibiotic use and reduce resistance. This initiative supports Pfizer’s commitment to responsible antibiotic use and addresses the rising challenge of antimicrobial resistance.
- In 2022, Pfizer partnered with NHS England and NICE on a subscription-based reimbursement model for antibiotics. This innovative approach prioritizes the public health value of antibiotics over prescription volume, incentivizing the discovery and appropriate use of new antibiotics. The model aims to promote investment in antibiotic R&D to combat resistance, potentially inspiring global adoption of similar frameworks.
Market Concentration & Characteristics:
The antibiotics market is moderately concentrated, with a few major players, including Pfizer, GSK, Merck & Co., and Johnson & Johnson, holding significant market shares due to their advanced R&D capabilities, extensive distribution networks, and broad antibiotic portfolios. These industry leaders maintain competitive advantages by focusing on innovative antibiotic formulations to combat rising antibiotic resistance, a global health concern. Mid-sized and generic pharmaceutical companies also play a crucial role, particularly in emerging markets where cost-effective access to antibiotics is essential. Market dynamics are further shaped by government initiatives promoting antimicrobial stewardship and R&D incentives for novel treatments. This competitive landscape emphasizes a dual focus on innovation for new antibiotic classes and affordability, making partnerships and regulatory collaborations essential for expanding access to effective antibiotics across diverse regions.
Report Coverage:
The research report offers an in-depth analysis based on Drug Class, Application, Route of Administration, and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for antibiotics is projected to increase due to the high prevalence of bacterial infections and the rising threat of antibiotic-resistant pathogens worldwide.
- Major pharmaceutical companies are expected to prioritize R&D for new antibiotic classes to address emerging resistance, especially targeting multidrug-resistant Gram-negative bacteria.
- Strategic partnerships with governments and healthcare organizations to promote antimicrobial stewardship are likely to expand, supporting responsible antibiotic use.
- Increasing investments in diagnostics and rapid testing technologies are anticipated, enabling faster detection and targeted antibiotic treatments.
- The Asia-Pacific region is expected to experience rapid market growth due to rising healthcare expenditures and high infection rates, particularly in countries such as China and India.
- Subscription-based reimbursement models, like Pfizer’s partnership with NHS England, may gain traction globally, incentivizing new antibiotic development by valuing public health impact over prescription volume.
- Growing demand for broad-spectrum antibiotics will persist, although a shift towards narrow-spectrum, targeted therapies is expected to mitigate resistance.
- Generic antibiotic manufacturers will play a vital role in expanding access in emerging markets, where affordability is crucial.
- Advances in synthetic biology and biotechnology are expected to facilitate more efficient antibiotic production, reducing dependency on traditional sources.
- Expansion of online pharmacy channels will enhance antibiotic accessibility, particularly in regions with limited healthcare infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Infectious Diseases
The increasing incidence of bacterial infections, including respiratory, urinary, and skin infections, is driving demand for antibiotics as effective treatment options remain essential for public health.
Advancements in Research and Development
Pharmaceutical companies are investing in novel antibiotics and combination therapies to address the growing threat of antibiotic resistance, leading to a pipeline of innovative products and market expansion.
Government Support and Regulatory Frameworks
Government initiatives and funding, such as antibiotic stewardship programs and incentives for R&D, are fostering the development and responsible use of antibiotics, ensuring continued market growth.
Growing Demand for Generic Antibiotics
The affordability and accessibility of generic antibiotics are increasing their adoption, especially in emerging markets, supporting overall market expansion and improving access to essential medicines.
Expansion of Healthcare Infrastructure in Emerging Economies
Improved healthcare infrastructure and increased healthcare spending in regions like Asia-Pacific and Latin America are enabling broader access to antibiotics, fueling market growth in these high-need areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Antibiotics Market?
What factors are driving the growth of the Global Antibiotics Market?
What are the key segments within the Global Antibiotics Market?
What are some challenges faced by the Global Antibiotics Market?
Who are the major players in the Global Antibiotics Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Penicillin
- 1.2.2 Cephalosporin
- 1.2.3 Aminoglycosides
- 1.2.4 Tetracycline
- 1.2.5 Macrolides
- 1.2.6 Fluoroquinolones
- 1.2.7 Sulfonamides
- 1.2.8 Others
- 1.3 By Application
- 1.3.1 Skin Infections
- 1.3.2 Respiratory Infections
- 1.3.3 Urinary Tract Infections
- 1.3.4 Septicemia
- 1.3.5 Ear Infection
- 1.3.6 Gastrointestinal Infections
- 1.3.7 Others
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Parenteral
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 50,915 million → 2032: USD 67,931.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Antibiotics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Antibiotics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Antibiotics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Antibiotics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Antibiotics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Antibiotics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Antibiotics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Antibiotics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 50,915 million → 2032: USD 67,931.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Antibiotics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Penicillin
- 12.3.7.2 Cephalosporin
- 12.3.7.3 Aminoglycosides
- 12.3.7.4 Tetracycline
- 12.3.7.5 Macrolides
- 12.3.7.6 Fluoroquinolones
- 12.3.7.7 Sulfonamides
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Skin Infections
- 12.4.7.2 Respiratory Infections
- 12.4.7.3 Urinary Tract Infections
- 12.4.7.4 Septicemia
- 12.4.7.5 Ear Infection
- 12.4.7.6 Gastrointestinal Infections
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Parenteral
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Antibiotics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Antibiotics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Antibiotics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Antibiotics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Johnson & Johnson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GlaxoSmithKline plc (GSK)
- 18.4 Pfizer Inc.
- 18.5 Merck & Co., Inc.
- 18.6 Bayer AG
- 18.7 Novartis AG
- 18.8 Sanofi SA
- 18.9 Abbott Laboratories
- 18.10 Hoffmann-La Roche AG
- 18.11 Eli Lilly and Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

