
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Switzerland Geospatial Analytics Market Size 2023 | USD 440.27 million |
| Switzerland Geospatial Analytics Market , CAGR | 7.6% |
| Switzerland Geospatial Analytics Market Size 2032 | USD 849.79 million |
Market Overview:
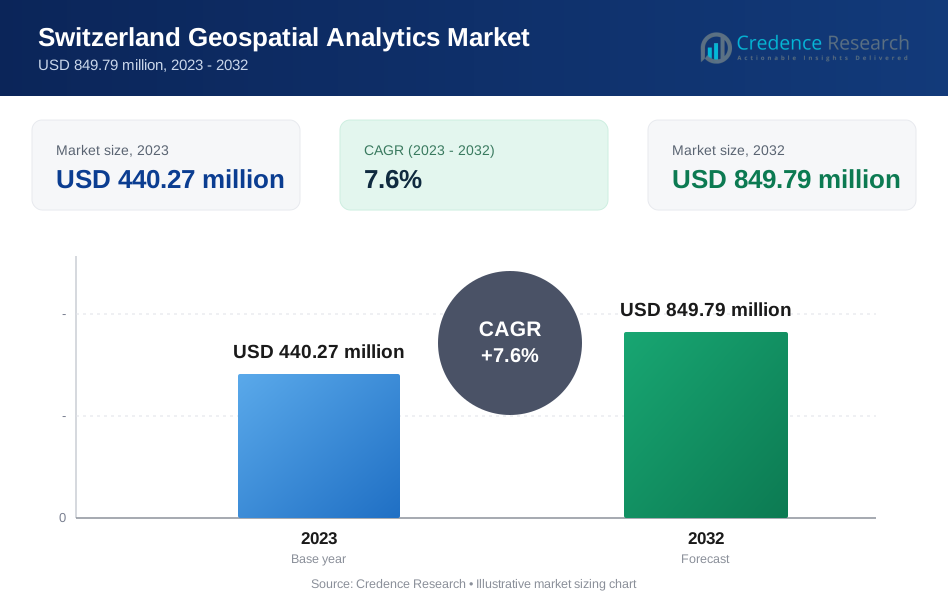
Switzerland Geospatial Analytics Market size was valued at USD 440.27 million in 2023 and is anticipated to reach USD 849.79 million by 2032, at a CAGR of 7.6% during the forecast period (2023-2032).
Several factors are propelling the growth of geospatial analytics in Switzerland. The country's strong focus on environmental sustainability has led to increased adoption of geospatial technologies for climate change assessment and natural resource management. Additionally, Switzerland's strategic investments in smart city initiatives and infrastructure development are leveraging geospatial analytics for urban planning and efficient resource allocation. The integration of geospatial data with emerging technologies like artificial intelligence (AI) and machine learning (ML) is enhancing predictive analytics capabilities, thereby improving decision-making processes across various sectors. Furthermore, the presence of leading geospatial companies, such as Hexagon AB, underscores Switzerland's pivotal role in advancing geospatial analytics solutions. The private sector's growing interest in real-time spatial data is fueling the demand for advanced analytics platforms. Moreover, government agencies are increasingly deploying GIS tools for public service optimization and environmental resilience.
Switzerland's geospatial analytics market is characterized by a concentration of high-tech companies and research institutions that contribute to the development and application of geospatial technologies. The country's central location in Europe facilitates collaboration and data sharing with neighboring countries, enhancing regional geospatial initiatives. Switzerland's diverse topography, including the Alps, necessitates sophisticated geospatial solutions for environmental monitoring, disaster management, and infrastructure development. The government's support for innovation and data-driven policies further accelerates the adoption of geospatial analytics across various sectors, including transportation, agriculture, and public safety. Urban hubs like Zurich and Geneva are emerging as innovation centers for geospatial startups and solution providers. Additionally, Switzerland’s multilingual and multicultural environment supports international projects and cross-border geospatial collaboration.
Market Insights:
- Switzerland’s geospatial analytics market was valued at USD 440.27 million in 2023 and is projected to reach USD 849.79 million by 2032, growing at a CAGR of 7.6% during the forecast period.
- Environmental sustainability initiatives are driving the adoption of geospatial technologies for climate change assessment, biodiversity monitoring, and natural resource management.
- Smart city projects in Zurich, Geneva, and Basel are leveraging geospatial analytics for infrastructure planning, traffic management, and optimization of public services.
- The integration of geospatial data with AI, machine learning, and big data analytics is enhancing predictive capabilities and operational efficiency across various sectors.
- Zurich and Geneva are emerging as leading innovation hubs, supported by top research institutions like ETH Zurich and a growing number of geospatial startups and tech firms.
- Challenges include high implementation costs, technical integration barriers, and compliance with strict data privacy regulations such as FADP and GDPR.
- Regionally, Zurich leads the market with a 28.5% share, followed by Geneva (22.3%), Bern (18.1%), Basel (15.4%), and the Rest of Switzerland (15.7%), reflecting diverse regional adoption levels.
Report Scope
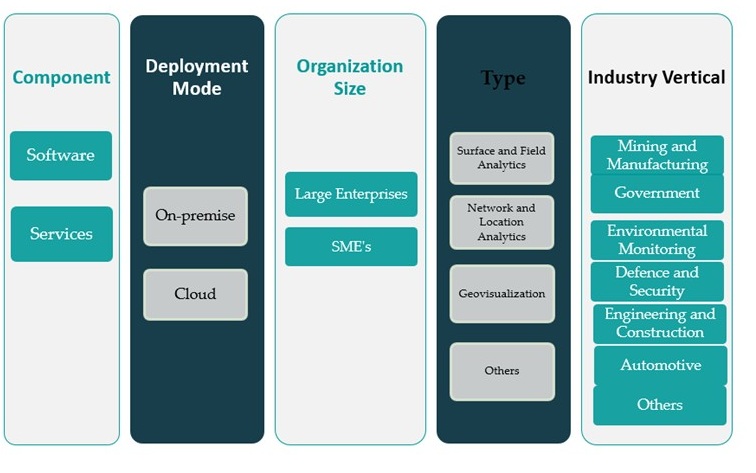
This report segments the Switzerland Geospatial Analytics Market as follows:
Market Drivers:
Environmental Sustainability and Climate Resilience Initiatives
Switzerland's unwavering commitment to environmental sustainability is a foundational driver of its geospatial analytics market. The country consistently invests in technologies that support environmental monitoring, biodiversity conservation, and climate change adaptation. Geospatial analytics plays a pivotal role in these efforts by enabling authorities to collect, analyze, and visualize spatial data related to natural resource usage, carbon emissions, and ecological disturbances. For instance, companies like GEOTEST AG, with nearly 200 experts, provide comprehensive environmental and geotechnical solutions, including hydrogeology, geothermal energy, and natural hazard management, using advanced geospatial modeling to mitigate risks such as rockslides and landslides. As climate variability intensifies, geospatial tools offer precise insights that aid in risk assessments, habitat preservation, and disaster preparedness. Government initiatives and environmental agencies increasingly rely on satellite imagery, remote sensing, and GIS platforms to manage land use and support sustainable development goals.
Smart Cities and Infrastructure Modernization
The ongoing transformation of urban centers into smart cities has significantly contributed to the growing demand for geospatial analytics in Switzerland. As cities like Zurich, Geneva, and Basel continue to modernize, geospatial tools are being adopted for efficient infrastructure planning, traffic management, and public service optimization. These solutions enable authorities to visualize spatial patterns, monitor utility networks, and enhance city-wide connectivity. The integration of geospatial systems with Internet of Things (IoT) devices further facilitates real-time monitoring and predictive maintenance of urban infrastructure. For instance, Hexagon’s HxGN Content Program offers the largest library of high-resolution aerial imagery, elevation data, and 3D models across Europe, providing Swiss cities with accurate, cloud-based geospatial content for urban planning, asset management, and infrastructure monitoring. These capabilities not only improve urban planning but also help reduce operational costs and environmental impact, making them essential to sustainable urban development.
Technological Integration and Innovation
Switzerland's robust innovation ecosystem is accelerating the adoption of advanced geospatial technologies through integration with emerging digital tools. The fusion of geospatial data with artificial intelligence (AI), machine learning (ML), and big data analytics is enabling organizations to derive deeper insights from complex datasets. These integrated technologies enhance decision-making capabilities in sectors such as agriculture, logistics, telecommunications, and public safety. The country’s strong emphasis on research and development, supported by institutions like ETH Zurich and EPFL, fosters a dynamic environment where novel geospatial applications are tested and scaled. Additionally, the availability of high-precision satellite data and cloud-based GIS platforms allows businesses and governments to access, process, and share spatial information with unprecedented efficiency.
Supportive Regulatory Environment and Public-Private Collaboration
Switzerland's regulatory landscape is conducive to the growth of geospatial analytics, with policies that encourage digital innovation, data transparency, and interoperability. Governmental bodies have implemented frameworks that facilitate the ethical use of geospatial data, ensuring privacy while promoting accessibility. This regulatory clarity fosters confidence among stakeholders and accelerates adoption across sectors. Furthermore, Switzerland benefits from strong public-private partnerships, where tech companies, research institutions, and public agencies collaborate on pilot projects and national geospatial programs. Companies such as Hexagon AB and Swiss-based startups actively contribute to the development of cutting-edge solutions, reinforcing the country’s leadership in the European geospatial analytics space. These collaborations ensure that geospatial innovations are not only technologically advanced but also aligned with national priorities and societal needs.
Market Trends:
Rising Demand for Real-Time Geospatial Intelligence
One of the most prominent trends in the Switzerland geospatial analytics market is the increasing demand for real-time data processing and location intelligence. Businesses and public sector organizations are prioritizing rapid decision-making capabilities, especially in areas such as disaster response, logistics, and mobility management. For example, Picterra has developed a GeoAI platform that enables the rapid interpretation of satellite, drone, and aerial imagery, transforming what was traditionally a months-long process into actionable insights within hours. The availability of advanced sensors, drones, and connected devices has enabled continuous data collection from diverse sources, which, when combined with geospatial platforms, allows for near-instant insights. Applications such as real-time traffic monitoring, emergency alert systems, and location-aware mobile services are gaining traction, particularly in urban centers with high connectivity and infrastructure density.
Adoption of Digital Twin Technology
The emergence of digital twin technology has significantly influenced the Swiss geospatial analytics landscape. Government bodies and private enterprises are increasingly adopting digital replicas of physical environments to simulate infrastructure systems, evaluate environmental conditions, and optimize asset performance. These digital twins, supported by 3D GIS and remote sensing technologies, enable stakeholders to conduct scenario analysis and predictive modeling in real-time. Cities like Zurich have launched pilot programs that use digital twins for construction planning, flood risk management, and urban sustainability assessments. For instance, companies like AVEVA provide digital twin solutions that consolidate real-time and historical data from IoT devices, engineering systems, and environmental sources, enabling organizations to simulate scenarios, predict outcomes, and reduce maintenance costs through proactive decision-making. The trend reflects Switzerland’s growing reliance on data-driven planning tools to enhance operational efficiency and reduce infrastructure lifecycle costs.
Expansion of Geospatial Use in Finance and Insurance
Beyond traditional domains like urban planning and agriculture, geospatial analytics in Switzerland is gaining momentum in finance and insurance sectors. Financial institutions are utilizing location-based risk assessments to evaluate property portfolios, identify climate-related hazards, and enhance fraud detection systems. Similarly, insurance companies are leveraging geospatial data to improve underwriting accuracy, assess natural disaster exposure, and streamline claims processing. With Switzerland being a global hub for finance and reinsurance, the application of geospatial intelligence in these areas is becoming a key differentiator. This trend highlights the broadening of geospatial analytics beyond core industries into high-value, data-intensive sectors.
Cloud-Based Platforms and SaaS Integration
The shift toward cloud-native geospatial analytics platforms is reshaping how Swiss organizations manage and deploy spatial data solutions. Software-as-a-Service (SaaS) models are making geospatial tools more accessible to small and medium-sized enterprises by reducing infrastructure costs and enabling scalable usage. These platforms support seamless integration with enterprise resource planning (ERP) and customer relationship management (CRM) systems, offering added value through location-based insights. Swiss companies are also adopting open-source geospatial tools in conjunction with proprietary platforms, promoting interoperability and customization. This trend aligns with the country’s digital transformation agenda, where agility, data mobility, and collaboration are key priorities across sectors.
Market Challenges Analysis:
Data Privacy Regulations and Ethical Concerns
A significant challenge facing the Switzerland geospatial analytics market is navigating the complexities of data privacy regulations. For instance, geospatial analytics involves the collection and processing of location-based data, ensuring compliance with stringent Swiss and EU data protection laws, such as the Federal Act on Data Protection (FADP) and GDPR, becomes critical. Organizations must maintain transparency and obtain proper consent for data usage, especially when dealing with personal or sensitive geospatial information. These regulatory requirements can delay implementation timelines and increase operational costs, particularly for smaller firms lacking legal expertise or compliance infrastructure. Ethical concerns around surveillance and individual privacy also pose reputational risks for organizations employing location-based solutions.
High Implementation Costs and Technical Barriers
The adoption of advanced geospatial analytics solutions often involves substantial upfront investments in hardware, software, skilled personnel, and system integration. This creates an entry barrier for small and mid-sized enterprises, limiting widespread adoption across industries. High-resolution satellite imagery, LiDAR systems, and real-time analytics platforms come with associated maintenance and licensing costs, making it challenging for budget-constrained institutions to scale their capabilities. Additionally, the complexity of integrating geospatial analytics with legacy IT systems poses technical challenges. Organizations may lack in-house expertise in spatial data science, which further impedes the seamless deployment of advanced geospatial tools.
Limited Standardization and Interoperability
Another restraint is the lack of standardization and interoperability among geospatial data sources and platforms. Disparities in data formats, coordinate systems, and processing methods hinder effective data exchange between agencies, organizations, and cross-border partners. This fragmentation can result in duplicated efforts, data silos, and reduced analytical accuracy. Although Switzerland promotes digital collaboration, the absence of universal standards across geospatial tools can slow progress, especially in multi-stakeholder or public-private projects. Addressing this challenge requires sustained coordination between policymakers, software providers, and end-users to ensure consistent and accessible geospatial data infrastructure.
Market Opportunities:
The Switzerland geospatial analytics market presents substantial growth opportunities driven by the nation’s strong focus on innovation and digital transformation. As the Swiss government continues to prioritize sustainable urban development and smart infrastructure, demand for advanced geospatial solutions is expected to increase across sectors such as transportation, energy, and public safety. Emerging applications like autonomous mobility, precision agriculture, and environmental modeling offer fertile ground for the expansion of geospatial technologies. The country’s emphasis on climate change mitigation and disaster risk reduction further strengthens the need for location-based insights, enabling proactive decision-making and efficient resource management. Additionally, Switzerland’s stable regulatory environment and strong intellectual property protections make it an attractive destination for geospatial startups and multinational tech firms seeking to develop and deploy cutting-edge spatial analytics tools.
There is also a growing opportunity in enhancing public services and citizen engagement through the integration of geospatial platforms with digital governance initiatives. Municipalities can leverage GIS-based solutions to streamline service delivery, improve infrastructure planning, and foster transparent urban management. Furthermore, the proliferation of cloud computing and the rise of SaaS-based geospatial solutions offer scalable models that are accessible to small and medium-sized enterprises. As industries increasingly embrace Industry 4.0 technologies, geospatial analytics can play a pivotal role in driving operational efficiency, competitive differentiation, and data-driven innovation. Switzerland’s highly skilled workforce, advanced research institutions, and strong cross-border connectivity position the country to capitalize on these emerging opportunities and lead geospatial analytics development in the European region.
Market Segmentation Analysis:
The Switzerland geospatial analytics market is segmented by component, deployment mode, organization size, type, and industry vertical, each offering distinct growth dynamics and application scopes.
By component, the software segment dominates the market, driven by increasing adoption of GIS platforms, 3D mapping, and AI-powered spatial modeling tools. The services segment is also witnessing steady growth, as organizations increasingly rely on consulting, integration, and maintenance services to maximize the value of geospatial systems.
By deployment mode, cloud-based solutions are rapidly gaining traction due to their scalability, cost-effectiveness, and ease of integration with existing digital infrastructures, while on-premise deployments remain relevant for government and defense applications requiring high data security.
By organization size, large enterprises currently lead the market owing to their higher investment capacity and expansive operational needs. However, the small and medium-sized enterprises (SMEs) segment is expanding steadily, fueled by the availability of cost-efficient SaaS-based geospatial solutions.
By type, network and location analytics hold a substantial market share due to widespread use in urban mobility, logistics, and smart city initiatives. Surface and field analytics are particularly important in environmental and agricultural applications, while geovisualization tools support enhanced data interpretation and decision-making across sectors.
By industry verticals, the government sector remains the primary adopter, leveraging geospatial analytics for urban planning, land administration, and public safety. Environmental monitoring, defense, and construction sectors are also key contributors, with mining, automotive, and manufacturing industries exploring spatial insights for process optimization, risk assessment, and supply chain management.
Segmentation:
By Component:
- Software
- Services
By Deployment Mode:
- On-premise
- Cloud
By Organization size:
- Large Enterprises
- SME’s
By Type:
- Surface and Field Analytics
- Network and Location Analytics
- Geovisualization
- Others
By Industry Vertical:
- Mining and Manufacturing
- Government
- Environmental Monitoring
- Defence and Security
- Engineering and Construction
- Automotive
- Others
Regional Analysis:
The Switzerland geospatial analytics market demonstrates regional variation in adoption and application, primarily driven by the economic development, urbanization levels, and digital infrastructure maturity of each canton. The market is segmented into five key regions: Zurich, Geneva, Bern, Basel, and the Rest of Switzerland. In 2023, Zurich held the largest market share at 28.5%, followed by Geneva with 22.3%, Bern with 18.1%, Basel with 15.4%, and the remaining 15.7% attributed to the Rest of Switzerland. These disparities reflect both the concentration of industrial and government investments in technology and the differing levels of smart infrastructure initiatives across regions.
Zurich, as the economic and technological hub of the country, dominates the geospatial analytics landscape. The presence of leading tech firms, financial institutions, and academic research centers fosters significant demand for advanced geospatial applications in urban planning, environmental monitoring, and location-based services. Additionally, Zurich’s robust support for smart city initiatives and sustainable infrastructure planning accelerates the integration of geospatial technologies across public and private sectors.
Geneva follows closely, leveraging its role as an international center for diplomacy and global institutions. The city’s use of geospatial analytics is prominent in urban resilience planning, environmental risk assessments, and humanitarian logistics, particularly by international organizations and NGOs headquartered in the area. The demand is further supported by cross-border projects and collaborations with French geospatial agencies.
Bern, the political capital, actively integrates geospatial analytics into governance frameworks and public service delivery. Applications include land-use planning, infrastructure management, and natural disaster risk reduction. The federal administration’s investment in digital transformation ensures steady growth in the adoption of GIS platforms and spatial data solutions.
Basel represents a key region due to its strong life sciences and pharmaceutical sector. Companies in the area utilize geospatial analytics for supply chain optimization, site selection, and market mapping. Additionally, Basel’s cross-border trade with Germany and France increases the importance of location intelligence for logistics and transportation planning.
The Rest of Switzerland, including cantons such as Vaud, Ticino, and St. Gallen, is witnessing growing adoption of geospatial analytics in agriculture, tourism, and regional development. Although these areas account for a smaller share, rising investment in rural digitization and environmental sustainability is expected to boost market participation.
Key Player Analysis:
- SwissGeo
- SAP SE
- Google, Inc.
- Bentley Systems, Incorporated
- FlyPix AI
- Oracle Corporation
- Geomap
- Hexagon AB
- Geosys
- Trimble, Inc.
- Esri
- Pix4D
- SwissTopo
- Terralytics
- Meteomatics
- Others
Competitive Analysis:
The Switzerland geospatial analytics market is moderately competitive, with a mix of global players, regional providers, and innovative startups contributing to its growth. Companies such as Hexagon AB, Esri, and Trimble Inc. hold a significant presence through their advanced GIS platforms and analytics tools. These firms maintain a competitive edge by investing in R&D, offering integrated solutions, and forming strategic partnerships with Swiss government agencies and infrastructure developers. Local firms and research institutions also play a vital role in niche applications, particularly in environmental monitoring and precision mapping. The market dynamics are shaped by innovation, data accuracy, and interoperability, with players focusing on cloud-based services and AI integration to meet evolving user demands. As demand for real-time spatial insights and cross-sector applications increases, companies that offer scalable, secure, and customizable geospatial solutions are expected to strengthen their market position within Switzerland’s technology-driven ecosystem.
Recent Developments:
- In April 2025, Bentley Systems, Incorporated and Google announced a strategic partnership that integrates Google Maps Platform’s Imagery Insights with Bentley’s Blyncsy product. This collaboration leverages AI and crowdsourced imagery for automated roadway asset detection and inspection, enhancing infrastructure maintenance and disaster recovery capabilities.
- In December 2024, Hexagon AB made a significant move in the geospatial analytics sector by launching its HxGN Content Program, which expanded its satellite imagery and aerial mapping portfolio with new, high-resolution geospatial data products. This initiative is designed to provide more accurate data for environmental monitoring, agriculture, and urban planning, thereby enhancing decision-making for industries that rely heavily on geospatial information for planning and monitoring.
Market Concentration & Characteristics:
The Switzerland geospatial analytics market exhibits a moderately concentrated structure, dominated by a combination of global leaders and innovative domestic firms. International companies such as Esri, Hexagon AB, and Trimble Inc. maintain a significant presence, offering advanced GIS platforms and analytics tools. These firms leverage strategic partnerships with Swiss governmental agencies and infrastructure developers to solidify their market positions. Concurrently, local enterprises and research institutions contribute to the market by focusing on niche applications, particularly in environmental monitoring and precision mapping. The market is characterized by a strong emphasis on innovation, data accuracy, and interoperability. Organizations prioritize the integration of cloud-based services and artificial intelligence to meet evolving user demands. The adoption of scalable, secure, and customizable geospatial solutions is a key trend, driven by the need for real-time spatial insights across various sectors. Switzerland's commitment to technological advancement and its robust digital infrastructure further support the growth and sophistication of the geospatial analytics market.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment Mode, Organization size, Type and Industry Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Switzerland geospatial analytics market is expected to experience steady growth due to increasing adoption across urban planning, environmental monitoring, and infrastructure development.
- Advancements in AI, machine learning, and cloud computing will enhance the functionality and accessibility of geospatial platforms.
- Integration of digital twin technology in construction and smart city projects will drive demand for high-precision spatial data.
- Government investments in sustainable development and climate resilience will expand the use of geospatial analytics in public policy and resource management.
- Rising need for real-time geospatial insights will boost the deployment of IoT-enabled and edge-computing solutions.
- Growing interest from the financial and insurance sectors will diversify the application of geospatial analytics beyond traditional industries.
- Increased availability of open-source geospatial data will support innovation and reduce entry barriers for startups and SMEs.
- Regional collaboration with EU partners on cross-border data initiatives will strengthen Switzerland’s role in the European geospatial ecosystem.
- Market players will focus on offering customizable SaaS-based solutions tailored to specific enterprise needs.
- Continued emphasis on data privacy and regulatory compliance will shape product development and market expansion strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Switzerland Geospatial Analytics Market?
What factors are driving the growth of the Switzerland Geospatial Analytics Market?
What are some challenges faced by the Switzerland Geospatial Analytics Market?
Who are the major players in the Switzerland Geospatial Analytics Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Switzerland Geospatial Analytics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Switzerland Geospatial Analytics Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 440.27 million → 2032: USD 849.79 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Switzerland Geospatial Analytics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Switzerland Geospatial Analytics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Switzerland Geospatial Analytics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Switzerland Geospatial Analytics Market Drivers
- 3.3 Switzerland Geospatial Analytics Market Restraints & Challenges
- 3.4 Switzerland Geospatial Analytics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Switzerland Geospatial Analytics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Switzerland Geospatial Analytics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Switzerland Geospatial Analytics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Switzerland Geospatial Analytics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Switzerland Geospatial Analytics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Switzerland Geospatial Analytics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Switzerland Geospatial Analytics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Switzerland Geospatial Analytics Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Switzerland Geospatial Analytics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Switzerland Geospatial Analytics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Switzerland Geospatial Analytics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Switzerland Geospatial Analytics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Switzerland Geospatial Analytics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Switzerland Geospatial Analytics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Switzerland Geospatial Analytics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Switzerland Geospatial Analytics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Switzerland Geospatial Analytics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Switzerland Geospatial Analytics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Switzerland Geospatial Analytics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
