
Market Overview:
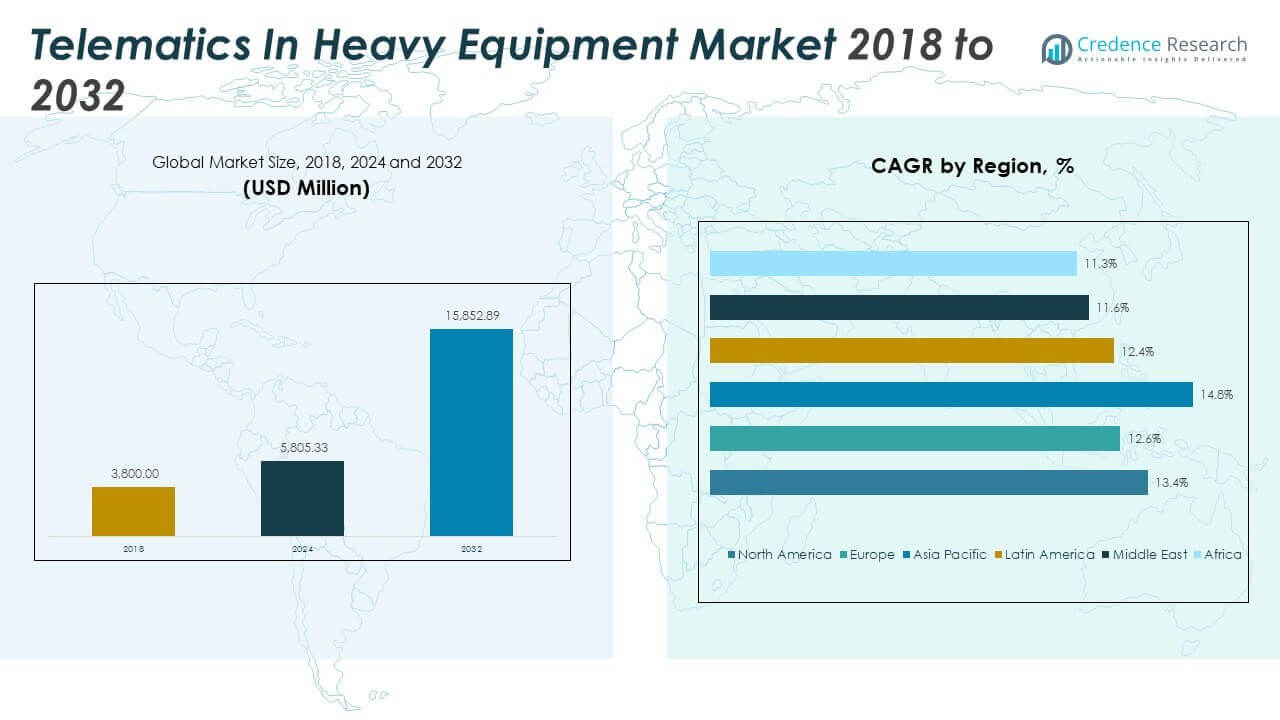
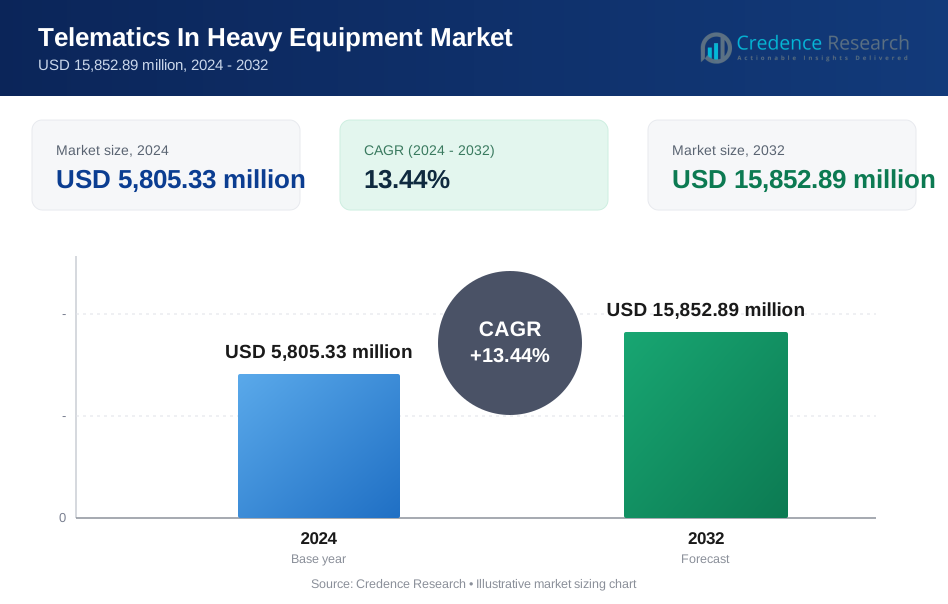
The Global Telematics In Heavy Equipment Market size was valued at USD 3,800.00 million in 2018 to USD 5,805.33 million in 2024 and is anticipated to reach USD 15,852.89 million by 2032, at a CAGR of 13.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Telematics in Heavy Equipment Market Size 2024 | USD 5,805.33 million |
| Telematics in Heavy Equipment Market, CAGR | 13.44% |
| Telematics in Heavy Equipment Market Size 2032 | USD 15,852.89 million |
The market grows due to rising demand for connected and efficient equipment operations. Fleet owners adopt telematics to track usage, fuel, and maintenance in real time. Construction and mining firms focus on uptime, safety, and cost control. OEMs embed sensors and software to support predictive maintenance and remote diagnostics. Regulations on emissions and worker safety support digital monitoring. Cloud platforms and mobile apps improve data access. Rental companies use telematics to manage assets and billing accuracy. These factors raise adoption across job sites and fleets.
North America leads due to strong construction activity and early technology use. The United States shows wide adoption across mining and large infrastructure projects. Europe follows with strict safety rules and focus on equipment efficiency. Germany and the Nordics drive innovation through OEM-led solutions. Asia Pacific emerges fast as urbanization and infrastructure spending rise. China and India expand connected fleets to improve productivity. Latin America and the Middle East gain traction through mining and energy projects.
Market Insights:
- The market was valued at USD 3,800.00 million in 2018, reached USD 5,805.33 million in 2024, and is projected to hit USD 15,852.89 million by 2032, growing at a CAGR of 13.44%, driven by rapid digital adoption across heavy equipment fleets.
- North America leads with about 38.0% share, followed by Asia Pacific at 28.1% and Europe at 22.7%, supported by large equipment fleets, strong OEM presence, and early use of connected technologies.
- Asia Pacific is the fastest-growing region with a 28.1% share, driven by large-scale infrastructure projects, urbanization, and rising adoption of telematics across construction and mining sectors.
- By component, software holds the largest share at around 45%, followed by hardware at nearly 35%, reflecting higher demand for analytics, dashboards, and remote monitoring capabilities.
- By deployment type, cloud accounts for about 60% share, while on-premises holds close to 40%, as fleets favor scalable access, faster updates, and multi-site visibility.
Market Drivers:
Rising Need For Operational Visibility And Asset Performance Optimization
Fleet owners demand real time visibility across dispersed heavy equipment assets. Telematics enables monitoring of fuel use, idle time, and machine health. Construction firms seek higher utilization rates to protect margins. Mining operators rely on data to prevent costly unplanned downtime. Equipment owners value predictive maintenance over reactive repair models. OEMs promote embedded systems to strengthen aftersales service revenue. Safety compliance needs also push monitoring adoption. The Global Telematics In Heavy Equipment Market gains traction from these efficiency goals.
- For instance, Caterpillar reports its VisionLink platform tracks over 1.5 million connected assets globally, helping customers cut unplanned downtime through condition alerts.
Cost Control Pressure Across Construction And Mining Operations
Heavy equipment operations face high fuel and maintenance expenses. Telematics supports cost reduction through behavior tracking and route optimization. Fleet managers use alerts to limit misuse and excessive idling. Data driven insights improve service scheduling accuracy. Rental companies depend on usage data for fair billing models. Contractors aim to reduce total ownership cost per asset. Insurers support monitored fleets due to lower risk exposure. These pressures sustain steady telematics demand.
- For instance, Komatsu states its KOMTRAX system monitors machine utilization and fuel metrics across 600,000+ machines worldwide.
OEM Integration Of Smart Systems Within New Equipment Platforms
OEMs integrate telematics during equipment manufacturing stages. Embedded systems improve equipment value and buyer appeal. Dealers use data for remote diagnostics and service planning. Manufacturers benefit from lifecycle data across installed bases. Software driven differentiation strengthens competitive positioning. Customers prefer factory fitted solutions over aftermarket add ons. This shift accelerates standardized adoption across fleets. Digital readiness becomes a purchase decision factor.
Regulatory Focus On Safety, Emissions, And Equipment Accountability
Authorities enforce stricter safety and emission norms globally. Telematics helps track compliance and operator behavior. Monitoring reduces accident risk on large job sites. Emission tracking supports sustainability reporting goals. Public infrastructure projects demand transparent equipment use records. Contractors align with digital compliance tools. These mandates support long term system deployment. Regulatory alignment drives consistent market demand.
Market Trends:
Shift Toward Data Driven Decision Making Across Job Sites
Fleet decisions rely more on analytics than experience alone. Telematics platforms deliver dashboards for quick operational insights. Managers compare asset performance across projects and regions. Data transparency improves planning accuracy and accountability. Enterprises integrate reports into ERP and project systems. This trend strengthens reliance on connected equipment ecosystems. Decision cycles shorten with continuous data flow. The Global Telematics In Heavy Equipment Market reflects this analytical shift.
- For instance, Trimble integrates machine data into project controls used on thousands of infrastructure sites globally.
Growth Of Subscription Based And Software Centric Revenue Models
Vendors expand recurring revenue through subscription platforms. Customers prefer predictable operating expense models. Software updates enhance features without hardware changes. Cloud access improves scalability across fleet sizes. OEMs bundle services with equipment sales. Dealers upsell analytics and support packages. This trend reshapes vendor revenue structures. Software value gains prominence over hardware margins.
- For instance, John Deere confirmed over 500,000 machines connect through its Operations Center, with software services bundled into equipment sales.
Increasing Use Of Mobile Interfaces For Field Level Management
Supervisors access telematics data through mobile applications. Real time alerts reach managers directly on sites. Mobile tools support faster response to faults. Operators receive performance feedback instantly. Simpler interfaces improve adoption among non-technical users. This trend supports decentralized fleet management. Mobility enhances operational responsiveness. Digital field tools become standard practice.
Integration Of Telematics With Broader Digital Construction Platforms
Telematics data links with BIM and project management tools. Integration supports end to end project visibility. Equipment data aligns with scheduling and costing systems. Stakeholders gain unified operational views. This trend supports smart construction ecosystems. Interoperability becomes a buying criterion. Vendors focus on open platform compatibility. Digital convergence shapes market evolution.
Market Challenges Analysis:
High Initial Deployment Cost And Unclear Short Term ROI
Telematics systems require hardware, software, and training investment. Small contractors hesitate due to budget constraints. ROI clarity remains limited in early adoption stages. Integration with legacy equipment raises costs. Customization needs vary by fleet type. Decision delays occur without proven benchmarks. Financing options remain uneven across regions. Cost sensitivity slows adoption among smaller operators.
Data Security Concerns And Skill Gaps In Fleet Management Teams
Connected equipment increases cybersecurity exposure risks. Fleet data requires secure storage and access control. Many operators lack skilled analytics personnel. Misinterpretation of data limits value realization. Resistance to digital change persists among operators. Training demands add operational burden. Vendor support quality varies widely. These factors restrict full system utilization.
Market Opportunities:
Expansion Potential Across Emerging Infrastructure And Mining Markets
Emerging economies expand infrastructure and resource projects. New fleets adopt telematics from early stages. Governments promote digital oversight of public projects. Contractors seek productivity gains under tight timelines. OEMs target greenfield deployments in these regions. Service penetration remains low but rising. This creates strong long term growth potential. The Global Telematics In Heavy Equipment Market benefits from regional expansion.
Advancement In AI Based Predictive And Autonomous Equipment Systems
AI enhances fault prediction and maintenance accuracy. Advanced analytics reduce downtime and service costs. Telematics supports semi-autonomous equipment operations. Data driven insights improve asset lifecycle planning. Vendors invest in intelligent feature development. Customers seek higher value beyond basic tracking. Innovation opens premium service opportunities. Technology evolution expands market scope.
Market Segmentation Analysis:
By Component
Hardware forms the foundation through sensors, GPS units, and control modules. Software drives analytics, dashboards, and alerts for fleet decisions. Services support installation, integration, and lifecycle management. Software value grows due to analytics depth and remote access. Services gain relevance with complex fleets and compliance needs. Hardware demand stays stable with OEM fitment. Integrated offerings improve customer retention. The Global Telematics In Heavy Equipment Market reflects this balanced component mix.
- For instance, Bosch Rexroth offers telematics hardware paired with cloud analytics used across multiple OEM platforms.
By Application
Construction leads adoption due to large fleets and tight schedules. Mining relies on monitoring for uptime and safety in remote sites. Agriculture adopts telematics for precision use and seasonal planning. Oil and gas uses tracking for harsh environments and compliance. Other sectors include forestry and ports. Each application values reliability and visibility. Data supports cost control and productivity. Use cases differ by asset intensity.
- For instance, Volvo Construction Equipment reports its CareTrack system connects hundreds of thousands of machines across construction and mining.
By Deployment Type
On-premises suits firms with strict data control needs. Cloud enables scalability and faster updates. Cloud access supports multi-site fleets. Subscription models favor cloud adoption. On-premises remains relevant for legacy systems. Hybrid approaches appear across large enterprises. Security standards shape choices. Flexibility drives preference.
By Equipment Type
Excavators and loaders dominate due to high utilization. Dozers and dump trucks need route and load tracking. Other equipment includes cranes and graders. Utilization data guides maintenance cycles. Mixed fleets benefit from unified platforms. OEM integration simplifies deployment. Asset diversity increases platform value. Performance insights support planning.
By Technology
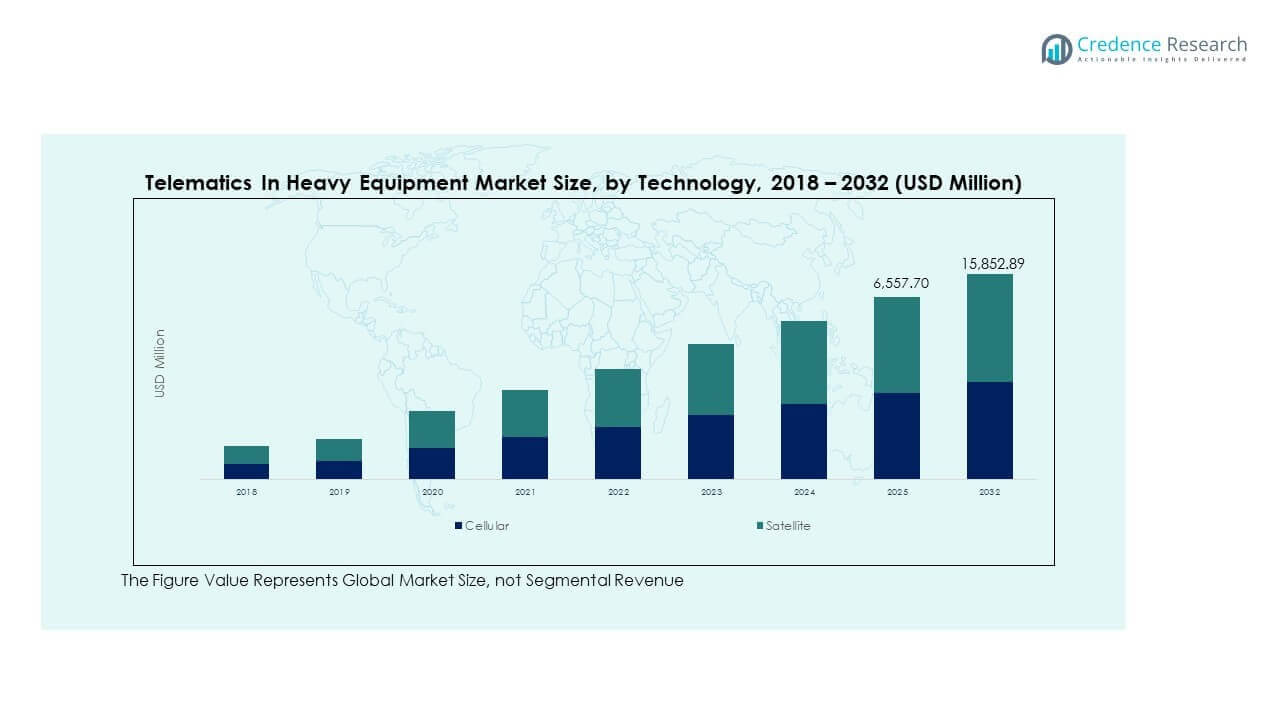
Cellular leads with wide coverage and lower cost. Satellite serves remote and off-grid locations. Dual-mode solutions ensure continuity. Technology choice depends on terrain. Reliability remains critical. Latency affects use cases. Connectivity underpins analytics. Coverage drives adoption.
Segmentation:
By Component
- Hardware
- Software
- Services
- Construction
- Mining
- Agriculture
- Oil & Gas
- Others
- On-Premises
- Cloud
- Excavators
- Loaders
- Dozers
- Dump Trucks
- Others
- Cellular
- Satellite
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Telematics In Heavy Equipment Market size was valued at USD 1,462.24 million in 2018 to USD 2,208.31 million in 2024 and is anticipated to reach USD 6,022.54 million by 2032, at a CAGR of 13.4 during the forecast period. North America holds nearly 38.0% share in 2032. The region leads due to advanced construction practices and early technology adoption. Large fleets demand real time monitoring and cost control. OEM embedded systems gain strong acceptance. Mining and infrastructure projects sustain demand. Safety and emission rules support telematics use. Rental fleets rely on data for utilization tracking. Strong dealer networks enhance service penetration.
Europe
The Europe Global Telematics In Heavy Equipment Market size was valued at USD 954.56 million in 2018 to USD 1,398.93 million in 2024 and is anticipated to reach USD 3,597.86 million by 2032, at a CAGR of 12.6 during the forecast period. Europe accounts for about 22.7% share. The region focuses on efficiency and sustainability. Strict safety norms drive monitoring adoption. OEM led innovation supports system integration. Construction modernization sustains growth. Mining activity in select countries adds demand. Digital fleet management gains traction. Cross border projects increase connected equipment use.
Asia Pacific
The Asia Pacific Global Telematics In Heavy Equipment Market size was valued at USD 925.68 million in 2018 to USD 1,477.14 million in 2024 and is anticipated to reach USD 4,453.09 million by 2032, at a CAGR of 14.8 during the forecast period. Asia Pacific holds around 28.1% share. Rapid urbanization drives infrastructure expansion. Governments invest heavily in transport and energy projects. Contractors adopt telematics to manage large fleets. OEM localization supports cost effective deployment. Mining and agriculture add volume demand. Digital adoption accelerates across emerging economies.
Latin America
The Latin America Global Telematics In Heavy Equipment Market size was valued at USD 239.40 million in 2018 to USD 362.19 million in 2024 and is anticipated to reach USD 917.41 million by 2032, at a CAGR of 12.4 during the forecast period. Latin America captures about 5.8% share. Mining activity drives primary demand. Construction growth supports gradual adoption. Fleet operators focus on asset security. Telematics aids fuel and maintenance control. OEM partnerships improve access. Infrastructure gaps slow deployment. Growth remains steady across key countries.
Middle East
The Middle East Global Telematics In Heavy Equipment Market size was valued at USD 117.80 million in 2018 to USD 165.99 million in 2024 and is anticipated to reach USD 397.99 million by 2032, at a CAGR of 11.6 during the forecast period. The region represents nearly 2.5% share. Large infrastructure and energy projects support demand. Harsh operating conditions favor remote monitoring. Fleet visibility improves project execution. Government backed projects drive adoption. Cloud platforms support multi site operations. Market growth remains gradual but stable.
Africa
The Africa Global Telematics In Heavy Equipment Market size was valued at USD 100.32 million in 2018 to USD 192.76 million in 2024 and is anticipated to reach USD 464.00 million by 2032, at a CAGR of 11.3 during the forecast period. Africa holds close to 2.9% share. Mining activity forms the core demand base. Telematics improves asset security and uptime. Infrastructure projects support gradual uptake. Connectivity challenges affect deployment scale. OEM initiatives expand regional presence. Long term potential remains strong.
Key Player Analysis:
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment
- Hitachi Construction Machinery Co., Ltd.
- John Deere
- Trimble Inc.
- Teletrac Navman
- Topcon Corporation
- JCB
- Doosan Infracore
- Hyundai Construction Equipment
- Liebherr Group
- Terex Corporation
- Kobelco Construction Machinery Co., Ltd.
- Atlas Copco
- Wacker Neuson SE
Competitive Analysis:
The Global Telematics In Heavy Equipment Market shows strong competition among OEMs and telematics specialists. Leading players focus on embedded systems, analytics depth, and service coverage. Companies differentiate through predictive maintenance, remote diagnostics, and platform integration. OEM-backed solutions gain trust due to factory fitment and warranty alignment. Independent providers compete through flexible software and multi-brand support. Partnerships with dealers strengthen aftermarket reach. Scale, data security, and interoperability shape buyer choice. It remains moderately consolidated with room for niche innovators.
Recent Developments:
- Hitachi Construction Machinery pursued innovation through collaborative partnerships focused on autonomous operations and electrification. In October 2025, the company signed a charter agreement with Rio Tinto's subsidiary Technological Resources to develop remote operation technologies for ultra-large hydraulic excavators over the next five years. This collaboration aims to advance operator assist, remote operation, and partial autonomy capabilities for mining operations, with a goal to establish an interoperable platform by 2030 capable of operating multiple ultra-large excavators with partial autonomy across mine sites. Earlier, in October 2024, Hitachi partnered with Dimaag-AI Inc., a U.S.-based provider of electric solutions, to develop an electrified compact hydraulic excavator in the 1.7-ton class. The ENCORE electric technology includes high-power swappable battery modules and thermal management systems, with an official unveiling planned for Bauma 2025 in Munich and commercial launch targeted for Europe by 2027. Additionally, Hitachi acquired approximately 12% equity holding in Australian software company Envirosuite Ltd for $10 million AUD in September 2024, positioning the company to strengthen operational management and environmental responsibility in mining operations.
- JCB pursued market expansion in India through strategic partnerships and product innovation. In January 2025, JCB India announced a partnership with SAMIL to transform the pre-owned construction equipment market by combining JCB's pre-owned machinery offerings with SAMIL's extensive platform networks. This alliance addresses growing demand for well-maintained certified pre-owned equipment among contractors seeking cost efficiency. At EXCON 2025 in December 2025, JCB India launched over 10 new products, including a 52-tonne excavator, marking one of the company's most substantial product showcases and demonstrating its commitment to expanding its product portfolio for India's infrastructure development boom.
- Doosan Infracore shifted its strategic focus beyond traditional construction equipment toward emerging energy solutions. In August 2025, Doosan Enerbility secured two landmark partnerships: a collaboration with Amazon, X-energy, and KHNP to deploy small modular reactors (SMRs) providing 960 MW of carbon-free power for Amazon data centers, and a partnership with Texas-based Fermi America to supply equipment for an 11 GW "AI Campus Project". In response to these significant contracts, Doosan announced in December 2025 the construction of South Korea's first dedicated SMR manufacturing plant, signaling a strategic shift from component manufacturing for individual demonstration projects to mass production for the global commercial market. Additionally, Doosan expanded its construction equipment partnerships with HD Hyundai Infracore through product cross-supply cooperation agreements in the North American market.
- Volvo Construction Equipment demonstrated substantial commitment to geographic expansion and electrification. In June 2025, the company announced a strategic investment of approximately 2,500 MSEK in crawler excavator production at three key locations: Changwon in South Korea (the largest investment), a facility in Sweden, and Shippensburg in the United States. This investment aims to strengthen Volvo's global crawler excavator footprint, improve operational efficiency through localized production, reduce carbon emissions by minimizing transportation distances, and enhance supply chain resilience. Complementing this infrastructure investment, Volvo CE launched its New Generation Excavator series in Southeast Asia beginning January 2025, with models including the EC210, EC220, EC230, EC300, and EC360. The company further demonstrated its India-focused innovation strategy at EXCON 2025, unveiling the new EC215 excavator engineered for India's diverse working conditions, the SD110 Compactor for long-term durability in road construction, the L120 Electric Wheel Loader representing India's most advanced commercial electric loader, and the EC650 mining excavator. Volvo also announced progress on an upcoming Technology Centre in Bengaluru to drive research and development, localization, and product innovation for both Indian and global markets.
Report Coverage:
The research report offers an in-depth analysis based on component and application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- OEM embedded telematics will gain wider acceptance across new equipment sales.
- Software platforms will lead value creation through analytics and insights.
- Cloud deployment will expand across multi-site fleets.
- Predictive maintenance use will deepen across construction and mining.
- Rental fleets will rely more on utilization and billing data.
- Integration with project and asset systems will increase.
- Mobile access will drive faster on-site decision making.
- Cybersecurity features will gain buyer focus.
- Emerging regions will see faster first-time adoption.
- Service-led revenue models will strengthen vendor positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Operational Visibility and Asset Performance Optimization
Fleet owners and operators increasingly require real-time monitoring of heavy equipment to maximize utilization, reduce idle time, and prevent unplanned downtime. Telematics solutions provide actionable insights into machine health, fuel consumption, and usage patterns, enabling predictive maintenance and higher operational efficiency.
Cost Control Pressure in Construction and Mining
Heavy equipment operations face significant fuel and maintenance costs. Telematics enables data-driven management of operator behavior, route optimization, and maintenance scheduling, helping companies reduce total cost of ownership and improve billing accuracy, especially for rental and large fleet operators.
OEM Integration of Smart Systems
Leading equipment manufacturers are embedding telematics hardware and software directly into new machines, making connected features a standard offering. This integration enhances equipment value, supports remote diagnostics, and strengthens aftersales service revenue, accelerating adoption across fleets.
Regulatory Focus on Safety and Emissions
Stricter global regulations on worker safety, emissions, and equipment accountability are driving adoption of telematics for compliance monitoring. Digital tracking helps contractors and fleet owners meet regulatory requirements, reduce accident risks, and support sustainability reporting.
Growth of Cloud and Mobile Platforms
The shift toward cloud-based telematics platforms and mobile applications enables scalable, multi-site fleet management and real-time field-level decision making. This trend supports faster updates, easier integration with project management tools, and broader adoption among both large and small operators.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Telematics In Heavy Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Telematics In Heavy Equipment Market projected to grow between 2025 and 2032?
Which Global Telematics In Heavy Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Telematics In Heavy Equipment Market?
Who are the leading companies in the Global Telematics In Heavy Equipment Market?
Which region commanded the largest share of the Global Telematics In Heavy Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Application
- 1.3.1 Construction
- 1.3.2 Mining
- 1.3.3 Agriculture
- 1.3.4 Oil & Gas
- 1.3.5 Others
- 1.4 By Equipment Type
- 1.4.1 Excavators
- 1.4.2 Loaders
- 1.4.3 Dozers
- 1.4.4 Dump Trucks
- 1.4.5 Others
- 1.5 By Deployment Type
- 1.5.1 On-Premises
- 1.5.2 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,805.33 million → 2032: USD 15,852.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Telematics In Heavy Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Telematics In Heavy Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Telematics In Heavy Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Telematics In Heavy Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Telematics In Heavy Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Telematics In Heavy Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Telematics In Heavy Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Telematics In Heavy Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,805.33 million → 2032: USD 15,852.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Telematics In Heavy Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Construction
- 12.4.7.2 Mining
- 12.4.7.3 Agriculture
- 12.4.7.4 Oil & Gas
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Equipment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Excavators
- 12.5.7.2 Loaders
- 12.5.7.3 Dozers
- 12.5.7.4 Dump Trucks
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premises
- 12.6.7.2 Cloud
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Telematics In Heavy Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Telematics In Heavy Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Telematics In Heavy Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Telematics In Heavy Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Komatsu Ltd.
- 18.4 Volvo Construction Equipment
- 18.5 Hitachi Construction Machinery Co., Ltd.
- 18.6 John Deere
- 18.7 Trimble Inc.
- 18.8 Teletrac Navman
- 18.9 Topcon Corporation
- 18.10 JCB
- 18.11 Doosan Infracore
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

