
Market Overview
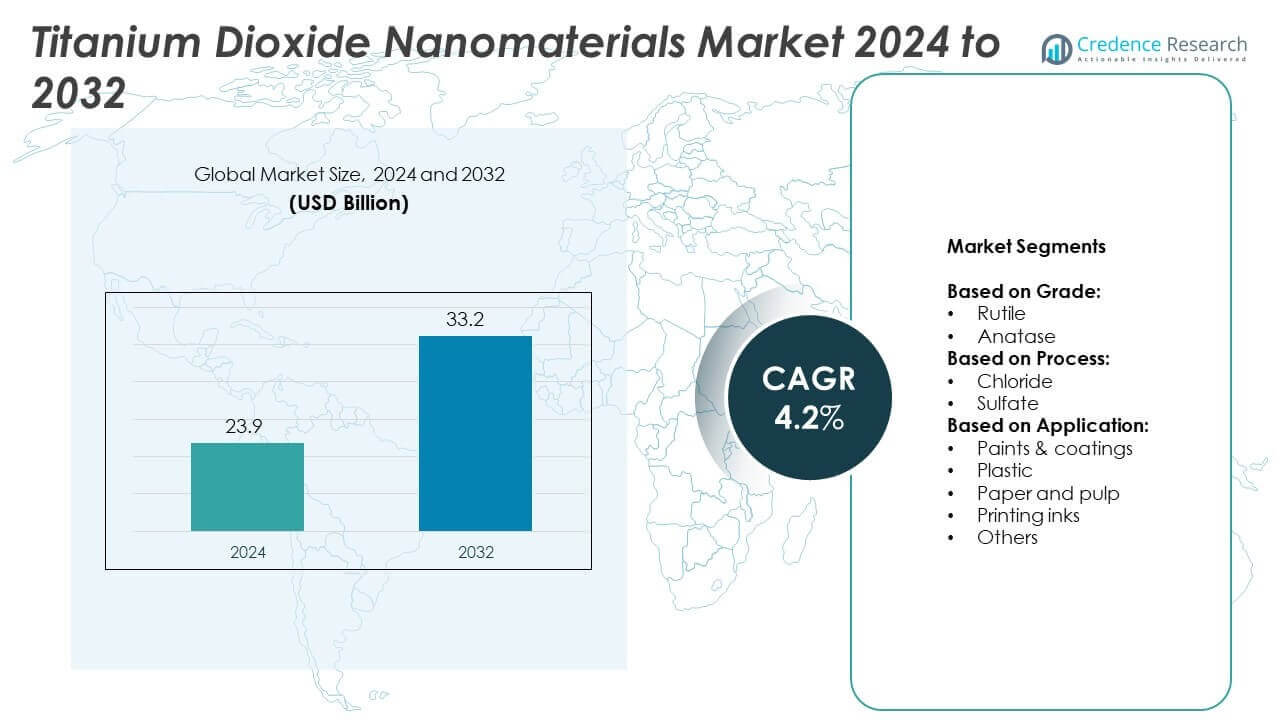
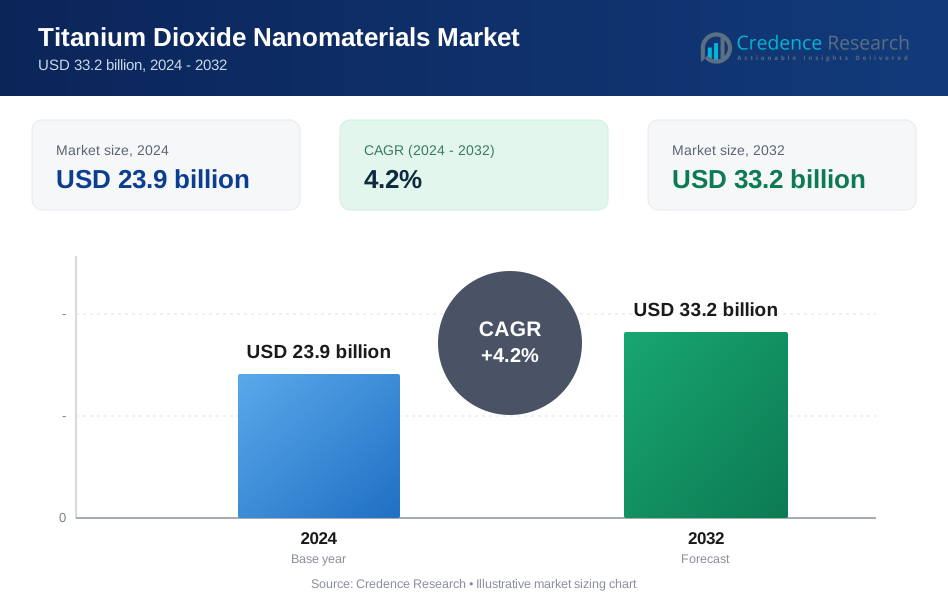
The Titanium Dioxide Nanomaterials Market size was valued at USD 23.9 billion in 2024 and is anticipated to reach USD 33.2 billion by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Titanium Dioxide Nanomaterials Market Size 2024 | USD 23.9 Billion |
| Titanium Dioxide Nanomaterials Market, CAGR | 4.2% |
| Titanium Dioxide Nanomaterials Market Size 2032 | USD 33.2 Billion |
The Titanium Dioxide Nanomaterials market grows with rising demand from paints, coatings, plastics, and cosmetics, supported by superior UV resistance, durability, and photocatalytic properties. Increasing use in renewable energy, water purification, and self-cleaning surfaces strengthens adoption. Healthcare applications such as implants and drug delivery also drive expansion. Trends highlight a shift toward sustainable production methods, eco-friendly formulations, and advanced nanotechnology innovations. Rising investments in R&D and regulatory focus on safe, high-performance materials position the market for steady long-term growth.
North America and Europe demonstrate strong demand for titanium dioxide nanomaterials, driven by advanced infrastructure, strict environmental regulations, and innovation in coatings and cosmetics. Asia Pacific leads in production and consumption with rapid industrialization, construction growth, and expanding electronics applications. Latin America and the Middle East & Africa show steady adoption through infrastructure and healthcare investments. Key players such as Tronox Holdings, Evonik Industries, Kronos Worldwide, and Showa Denko strengthen global presence with innovation, sustainable production methods, and expanding product portfolios.
Market Insights
- The Titanium Dioxide Nanomaterials market was valued at USD 23.9 billion in 2024 and is projected to reach USD 33.2 billion by 2032, expanding at a CAGR of 4.2%.
- Rising demand from paints, coatings, plastics, and cosmetics industries drives market growth due to superior UV resistance, durability, and opacity.
- Strong trends include adoption in renewable energy, water purification, and self-cleaning surfaces, supported by advanced nanotechnology innovations.
- Competition remains intense with key players focusing on R&D, sustainable production, and global distribution networks to expand presence.
- Market restraints include health and environmental concerns related to nanoparticle exposure and high production costs limiting mass-scale adoption.
- North America and Europe show strong growth through advanced infrastructure and strict regulatory standards, while Asia Pacific leads consumption through large-scale manufacturing and industrial expansion.
- Latin America and the Middle East & Africa show steady growth with applications in construction, packaging, and healthcare, supported by rising investments and gradual adoption of sustainable solutions.
Market Drivers
Rising Demand from Paints and Coatings Industry
The paints and coatings industry drives strong demand for titanium dioxide nanomaterials. It enhances opacity, brightness, and UV resistance in architectural and industrial coatings. Construction and infrastructure projects worldwide increase the need for high-performance coatings. Growing urbanization fuels the consumption of decorative paints in residential and commercial buildings. The product’s ability to provide long-lasting protection supports its preference over alternatives. Environmental regulations also encourage the use of advanced materials with lower toxicity. The Titanium Dioxide Nanomaterials market benefits significantly from this widespread industrial reliance.
- For instance, Chemours is one of the world's largest producers of titanium dioxide (TiO₂), with an annual capacity of over 1.25 million tonnes. Its Ti-Pure™ TS-6300 grade was specifically developed for high-hiding flat (matte) architectural coatings.
Expanding Applications in Cosmetics and Personal Care
Cosmetics and personal care products represent a major growth driver for titanium dioxide nanomaterials. It is widely used in sunscreens due to excellent UV-blocking properties. Skincare formulations adopt it to protect against photoaging and skin cancer risks. Rising consumer awareness about harmful UV radiation strengthens market demand. The preference for non-toxic, transparent formulations further accelerates adoption. Growing middle-class populations in emerging markets increase product consumption in personal care. The Titanium Dioxide Nanomaterials market gains traction from these expanding applications.
- For instance, Evonik supplies ultrafine titanium dioxide under its TEGO® Sun range for use as a UV filter in sunscreen formulations. The particles are typically below 100 nanometers, which is the standard size for producing transparent mineral-based sunscreens.
Increasing Use in Environmental and Energy Applications
Environmental applications significantly influence titanium dioxide nanomaterials adoption. It serves as a photocatalyst in air and water purification systems. Governments focus on pollution control solutions to ensure cleaner environments. The product also supports self-cleaning surfaces in construction and automotive industries. Renewable energy sectors adopt it in solar cells for improved efficiency. Rising awareness of sustainability enhances its role in green technologies. The Titanium Dioxide Nanomaterials market sees steady expansion from these environmental benefits.
Growing Utilization in Electronics and Healthcare
Electronics and healthcare sectors offer diverse opportunities for titanium dioxide nanomaterials. It improves performance of sensors, batteries, and other electronic components. Demand for miniaturized, efficient devices accelerates material adoption. In healthcare, the product is used in drug delivery, implants, and antibacterial coatings. Rising investments in nanomedicine strengthen its role in medical applications. Expanding R&D supports innovation across both industries. The Titanium Dioxide Nanomaterials market secures long-term growth through this multi-sector adoption.
Market Trends
Advancements in Nanotechnology and Product Innovation
Nanotechnology innovation is reshaping demand for titanium dioxide nanomaterials. It enables manufacturers to design products with enhanced photocatalytic efficiency and improved particle stability. Research focuses on tailoring particle size for targeted applications in coatings, energy, and healthcare. Advanced production techniques reduce environmental impact while ensuring high purity levels. Companies invest in surface modification technologies to enhance compatibility with polymers and cosmetics. Continuous innovation strengthens adoption across industries. The Titanium Dioxide Nanomaterials market evolves with these advancements.
- For instance, Kronos Worldwide is a major producer of titanium dioxide (TiO₂) and operates production plants across five countries: Germany, Norway, Belgium, Canada, and the United States. The company's annual production capacity is approximately 550,000 metric tonnes. Kronos offers a wide variety of TiO₂ pigment grades, including those used in plastics and cosmetic formulations, which can be surface-modified for specific performance enhancements
Growing Focus on Sustainable and Eco-Friendly Solutions
Sustainability trends strongly influence the development of titanium dioxide nanomaterials. It is increasingly used in green building materials and water treatment systems. Eco-friendly formulations align with global regulations promoting safer industrial practices. Demand rises for recyclable coatings and low-VOC products supported by titanium dioxide nanostructures. Solar energy applications highlight its role in renewable power generation. Industry players prioritize sustainable sourcing and cleaner manufacturing processes. The Titanium Dioxide Nanomaterials market adapts to these evolving sustainability goals.
- For instance, Pilkington (a part of NSG Group) has integrated a titanium dioxide nanocoating into its Activ™ self-cleaning glass product line. This glass is widely installed in residential and commercial buildings globally. The company publicly announced a sales milestone of 10 million square meters of Activ™ self-cleaning glass in February 2018.
Rising Adoption in High-Performance Consumer Goods
Consumer goods industries increasingly integrate titanium dioxide nanomaterials into product design. It enhances durability, brightness, and UV resistance in packaging, textiles, and plastics. Cosmetic companies adopt transparent grades for advanced sun protection. Consumer electronics also benefit from improved functional properties offered by nanoscale coatings. Urban lifestyles and rising disposable incomes drive demand for premium products. The trend supports broader use of titanium dioxide nanostructures in daily-use goods. The Titanium Dioxide Nanomaterials market expands with this consumer-driven adoption.
Integration into Healthcare and Biomedical Applications
Healthcare innovations highlight emerging uses of titanium dioxide nanomaterials. It demonstrates antibacterial, photocatalytic, and biocompatible properties suited for medical implants. Nanostructured coatings improve sterilization and reduce infection risks in healthcare environments. Drug delivery systems adopt it for controlled release and targeted therapies. Medical device manufacturers explore advanced composites for enhanced safety. Growing investment in nanomedicine accelerates its biomedical integration. The Titanium Dioxide Nanomaterials market strengthens through this healthcare-focused trend.
Market Challenges Analysis
Health and Environmental Concerns Associated with Nanoparticles
Health and environmental risks remain a key challenge for titanium dioxide nanomaterials. Inhalation of nanoparticles may cause respiratory issues, leading to strict workplace regulations. It also raises concerns about long-term effects on human health. Environmental impact from disposal of nanomaterials in soil and water further complicates adoption. Governments enforce stricter safety assessments before approving large-scale applications. Compliance with these regulatory standards increases production costs and slows commercialization. The Titanium Dioxide Nanomaterials market faces significant hurdles in balancing growth with safety concerns.
High Production Costs and Technical Limitations
Production complexity poses another barrier to titanium dioxide nanomaterials expansion. It requires advanced synthesis methods that are costly and energy-intensive. Limited scalability restricts affordable supply for mass-market applications. Small particle sizes also demand specialized handling to avoid agglomeration and maintain stability. Manufacturers face challenges in ensuring consistent quality across industries such as healthcare and electronics. Limited awareness among end-users about technical benefits reduces wider adoption. The Titanium Dioxide Nanomaterials market must overcome these cost and technology limitations to sustain growth.
Market Opportunities
Expansion in Renewable Energy and Environmental Applications
Renewable energy and environmental sectors create strong opportunities for titanium dioxide nanomaterials. It is widely used in solar cells to enhance energy conversion efficiency. Photocatalytic properties also enable applications in water and air purification systems. Governments support clean energy and pollution control initiatives, driving demand for advanced nanomaterials. Adoption of self-cleaning surfaces in construction and transportation expands its utility. Growing focus on sustainability ensures consistent funding for R&D projects. The Titanium Dioxide Nanomaterials market gains momentum from these environmentally driven opportunities.
Emerging Potential in Healthcare and Advanced Electronics
Healthcare and electronics sectors offer promising growth avenues for titanium dioxide nanomaterials. It is increasingly applied in antibacterial coatings, medical implants, and drug delivery systems. Rising investment in nanomedicine supports further innovation in healthcare solutions. Electronics benefit from improved performance of batteries, sensors, and semiconductors enhanced by nanostructures. Demand for lightweight and efficient devices continues to grow across global markets. Collaborations between research institutions and manufacturers strengthen product development pipelines. The Titanium Dioxide Nanomaterials market secures long-term potential through these advanced applications.
Market Segmentation Analysis:
By Grade:
The Titanium Dioxide Nanomaterials market is segmented into rutile and anatase grades. Rutile dominates due to its higher stability, UV resistance, and strong optical properties. It is widely used in paints, coatings, and plastics where durability is critical. Anatase, on the other hand, offers superior photocatalytic activity, making it suitable for environmental and energy applications. Demand for anatase rises in solar cells, water purification, and self-cleaning surfaces. Both grades maintain strong growth trajectories, driven by industry-specific performance needs. The Titanium Dioxide Nanomaterials market benefits from the complementary advantages of these two grades.
- For instance, Tronox Holdings operates eight titanium dioxide (TiO₂) production facilities globally, following the announcement in March 2025 that it would be idling its Botlek plant in the Netherlands. The company reported a total nameplate capacity of 1.1 million metric tonnes of TiO₂ pigment in its 2023 annual report.
By Process:
Production processes are divided into chloride and sulfate methods. The chloride process is preferred in developed markets due to its ability to produce high-purity titanium dioxide nanomaterials with lower environmental impact. It ensures consistency in particle size, which is essential for advanced coatings and electronics. The sulfate process remains important in price-sensitive regions, offering cost advantages despite higher waste generation. Emerging economies continue to rely on the sulfate route due to infrastructure limitations. Investments in cleaner technologies strengthen the adoption of chloride-based production worldwide. The Titanium Dioxide Nanomaterials market adapts its processes to balance cost efficiency and sustainability.
- For instance, Lomon Billions (now known as LB Group) is a major global titanium dioxide (TiO₂) producer, ranked among the top three worldwide. The company has invested significantly in expanding its chloride-process capacity. As of a January 2024 announcement, LB Group's total chloride-process capacity across all sites was 660,000 tonnes per year. The company continues to operate sulfate-based production, with a total capacity of 850,000 tonnes per year, to serve various applications and meet market demand. Its total TiO₂ production capacity as of January 2024 was approximately 1.51 million tonnes per year.
By Application:
Applications span paints and coatings, plastic, paper and pulp, printing inks, and others. Paints and coatings account for the largest share, supported by construction, automotive, and industrial growth. It enhances opacity, brightness, and weather resistance, making it indispensable in architectural coatings. Plastics represent another significant segment where nanomaterials improve strength, UV resistance, and durability. The paper and pulp industry leverages titanium dioxide nanostructures for brightness and smooth finish. Printing inks adopt it for high-quality printing and improved adhesion on multiple substrates. Other applications include cosmetics, textiles, and electronics, where specialized uses continue to expand. The Titanium Dioxide Nanomaterials market secures broad relevance through these diverse end-use sectors.
Segments:
Based on Grade:
- Rutile
- Anatase
Based on Process:
- Chloride
- Sulfate
Based on Application:
- Paints & coatings
- Plastic
- Paper and pulp
- Printing inks
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a market share of 32% in the Titanium Dioxide Nanomaterials market, supported by strong demand from construction, automotive, and industrial coatings industries. The United States leads the region with advanced infrastructure and significant investments in high-performance paints and coatings. It also demonstrates high adoption in cosmetics and personal care due to rising awareness of UV protection. The presence of leading nanotechnology research centers accelerates product innovation and commercialization. Canada and Mexico contribute through expanding manufacturing sectors and rising consumer demand for sustainable solutions. Stringent environmental regulations in the region further drive the adoption of chloride-based production methods, ensuring high-quality output. The market in North America benefits from a mix of technological leadership, consumer awareness, and strong industrial bases.
Europe
Europe accounts for 27% of the Titanium Dioxide Nanomaterials market, driven by stringent environmental policies and advanced research facilities. Germany, France, and the United Kingdom dominate regional demand with strong emphasis on sustainable construction materials and eco-friendly coatings. It is also widely adopted in cosmetics, where regulatory standards promote safer and non-toxic formulations. Growth in automotive coatings and printing inks further strengthens demand across the region. European companies prioritize sustainable sourcing and invest heavily in nanotechnology R&D. The sulfate process has lower preference here, with a shift toward chloride-based production for efficiency and reduced environmental impact. Europe maintains strong momentum through innovation, regulatory support, and high-value end-user industries.
Asia Pacific
Asia Pacific captures the largest share at 30% of the Titanium Dioxide Nanomaterials market, supported by rapid industrialization and urbanization. China leads with significant consumption across paints, coatings, plastics, and printing inks. It also emerges as a global hub for low-cost production supported by large-scale manufacturing infrastructure. Japan and South Korea drive innovation with strong investments in electronics and healthcare applications. India contributes through rising construction and packaging industries that heavily depend on advanced nanomaterials. Growing middle-class populations across Southeast Asia further boost demand for personal care and household products. Asia Pacific secures its leadership position through a combination of manufacturing strength, expanding end-use sectors, and increasing research initiatives.
Latin America
Latin America represents 6% of the Titanium Dioxide Nanomaterials market, reflecting moderate growth supported by specific industries. Brazil dominates the region with expanding demand from paints, coatings, and packaging sectors. It also invests in water treatment and environmental applications where photocatalytic properties are essential. Mexico contributes with growing adoption in automotive coatings and industrial applications. Rising consumer awareness in cosmetics and personal care supports gradual expansion across the region. Limited infrastructure for advanced production processes remains a challenge, but international collaborations help bridge technology gaps. Latin America maintains steady demand while moving toward adoption of more sustainable and high-value applications.
Middle East & Africa
The Middle East & Africa account for 5% of the Titanium Dioxide Nanomaterials market, supported by growing construction and industrial sectors. The United Arab Emirates and Saudi Arabia drive demand through large-scale infrastructure projects that rely on durable coatings. It is also applied in packaging and plastics, reflecting rising consumer product demand. South Africa contributes with steady adoption in healthcare and environmental applications. Limited production capabilities in the region create reliance on imports from Asia Pacific and Europe. Governments are investing in nanotechnology R&D to diversify industrial capabilities beyond oil and gas. The region shows long-term potential as infrastructure expansion and healthcare investments accelerate adoption of titanium dioxide nanomaterials.
Key Player Analysis
- Tronox Holdings
- Kronos Worldwide
- Evonik Industries
- Showa Denko
- American Elements
- Sakai Chemical Industry
- Huntsman International
- Cristal
- Nanoptek
- CINKARNA Celje
- Reinste Nano Ventures
- Altairnano
- Catalysis
- DuPont
- Ishihara Sangyo Kaisha
Competitive Analysis
The leading players in the Titanium Dioxide Nanomaterials market include Tronox Holdings, Kronos Worldwide, Evonik Industries, Showa Denko, DuPont, Huntsman International, Cristal, Sakai Chemical Industry, American Elements, CINKARNA Celje, Altairnano, Catalysis, Reinste Nano Ventures, Nanoptek, and Ishihara Sangyo Kaisha. These companies compete through advanced product innovation, capacity expansion, and sustainability-driven strategies. The focus remains on producing high-purity nanomaterials with tailored properties for paints, coatings, plastics, and healthcare applications. Investment in R&D plays a crucial role, with firms prioritizing surface modification technologies and enhanced photocatalytic activity to meet diverse industrial needs. Strong distribution networks and strategic partnerships enable global players to secure a competitive edge in both developed and emerging markets. Regional diversification also strengthens market reach, as companies adapt to regulatory environments and consumer preferences across North America, Europe, and Asia Pacific. Price competitiveness continues to matter, but innovation and quality consistency drive long-term positioning. With growing demand in renewable energy, environmental purification, and advanced electronics, these companies are investing in next-generation applications. The Titanium Dioxide Nanomaterials market is therefore shaped by a balance of technological leadership, regulatory compliance, and sustained industry collaboration, ensuring steady growth and increasing opportunities across end-use industries.
Recent Developments
- In 2025, Tronox Holdings published its 2024 sustainability report, highlighting progress in responsible operations and environmental performance
- In August 2025, Kronos Worldwide was listed in industry reports for experiencing decreased production volumes due to weak market demand and general global uncertainty. The company is a producer of titanium dioxide (TiO₂) pigments, a key ingredient for the coatings and plastics industries, and does not sell end-product coatings.
- In 2024, ISK's "Vision 2030 Stage II" plan, which began in fiscal year 2024, the company is focused on "accelerating development of new products". Its official research and development (R&D) strategy leverages its proprietary titanium dioxide technology to create new value in functional materials that address social issues like sustainable development.
Report Coverage
The research report offers an in-depth analysis based on Grade, Process, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand from construction and automotive coatings.
- Sustainable and eco-friendly production methods will gain wider adoption.
- Advanced photocatalytic applications in water and air purification will strengthen usage.
- Growth in solar energy will drive higher demand for nanostructured materials.
- Healthcare innovations will create opportunities in implants and drug delivery.
- Cosmetics and personal care industries will continue to adopt transparent grades.
- Electronics and sensor technologies will integrate nanomaterials for better efficiency.
- Emerging economies will increase consumption through infrastructure and industrial growth.
- Strategic collaborations in R&D will accelerate product innovation.
- Regulatory compliance and safety standards will shape market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Titanium Dioxide Nanomaterials market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Titanium Dioxide Nanomaterials Market projected to grow between 2025 and 2032?
Which Titanium Dioxide Nanomaterials market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Titanium Dioxide Nanomaterials market?
Who are the leading companies in the Titanium Dioxide Nanomaterials Market?
Which region commanded the largest share of the Titanium Dioxide Nanomaterials market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Titanium Dioxide Nanomaterials Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Titanium Dioxide Nanomaterials Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 23.9 billion → 2032: USD 33.2 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Titanium Dioxide Nanomaterials Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Titanium Dioxide Nanomaterials Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Titanium Dioxide Nanomaterials Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Titanium Dioxide Nanomaterials Market Drivers
- 3.3 Titanium Dioxide Nanomaterials Market Restraints & Challenges
- 3.4 Titanium Dioxide Nanomaterials Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Titanium Dioxide Nanomaterials Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Titanium Dioxide Nanomaterials Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Titanium Dioxide Nanomaterials category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Titanium Dioxide Nanomaterials Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Titanium Dioxide Nanomaterials Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Titanium Dioxide Nanomaterials market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Titanium Dioxide Nanomaterials Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Titanium Dioxide Nanomaterials Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Titanium Dioxide Nanomaterials Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Titanium Dioxide Nanomaterials (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Titanium Dioxide Nanomaterials Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Titanium Dioxide Nanomaterials Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Titanium Dioxide Nanomaterials Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Titanium Dioxide Nanomaterials Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Titanium Dioxide Nanomaterials Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Titanium Dioxide Nanomaterials Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Titanium Dioxide Nanomaterials Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Titanium Dioxide Nanomaterials Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Titanium Dioxide Nanomaterials Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
