
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Feminine Hygiene Products Market Size 2024 | USD 6,849.11 million |
| U.S. Feminine Hygiene Products Market, CGR | 7.3% |
| U.S. Feminine Hygiene Products Market Size 2032 | USD 12,916.13 million |
Market Overview
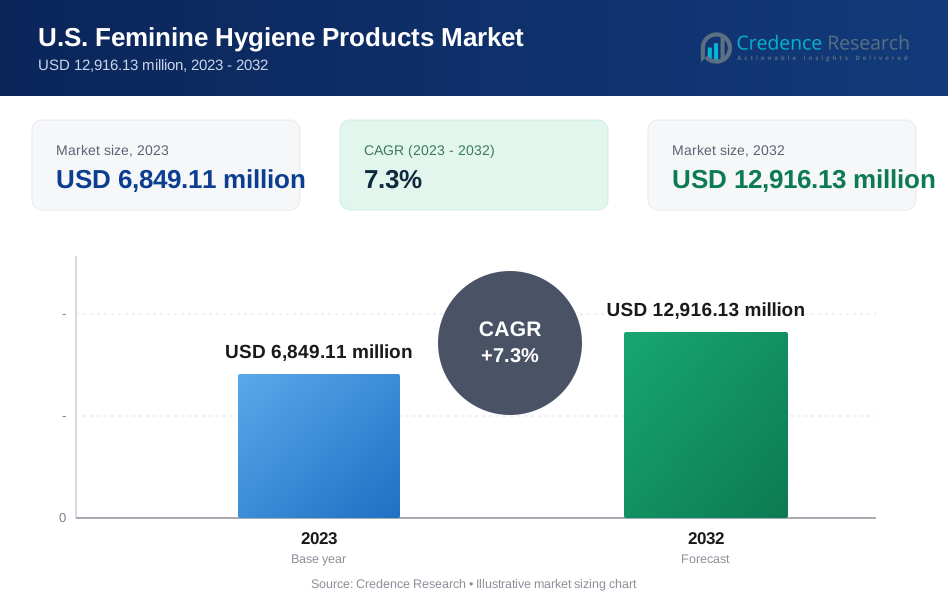
U.S. Feminine Hygiene Products size was valued at USD 6,849.11 million in 2023 and is anticipated to reach USD 12,916.13 million by 2032, at a CAGR of 7.3% during the forecast period (2023-2032).
The U.S. feminine hygiene products market is being driven by several factors that are shaping consumer behavior and industry growth. One of the primary drivers is the increasing awareness around health and hygiene, which has led to a surge in demand for high-quality feminine hygiene products. Consumers are becoming more health-conscious, seeking products that offer both comfort and safety. Additionally, innovation in product formulations, such as organic cotton and eco-friendly alternatives, is gaining traction, especially among environmentally aware consumers. The expansion of e-commerce platforms has further accelerated market growth, offering consumers easier access to a broad range of products and creating a more personalized shopping experience. Furthermore, legislative support, such as eliminating sales taxes on menstrual products and providing free access to these products in schools and public institutions, has reduced economic barriers, making these essential products more accessible to a wider demographic.
Regionally, the U.S. feminine hygiene market displays distinct trends influenced by demographic and cultural factors. The Northeast, with its urban centers and higher disposable incomes, exhibits a strong preference for premium and organic products, reflecting the region’s focus on health and sustainability. In the Midwest, the market is characterized by a diverse mix of urban and rural areas, which creates a steady demand for a variety of products across different price points. The South is experiencing a growing awareness of menstrual health, leading to an increased demand for feminine hygiene products. The expansion of retail networks, particularly in supermarkets and pharmacies, has made these products more accessible to consumers in the region. Lastly, the West is known for its progressive approach to health and environmental issues, with a significant shift towards sustainable and innovative menstrual solutions.
Market Insights:
- The U.S. feminine hygiene products market was valued at USD 6,849.11 million in 2023 and is projected to reach USD 12,916.13 million by 2032, growing at a CAGR of 7.3%.
- The global feminine hygiene products market, valued at USD 23,490.00 million in 2023, is projected to reach USD 43,917.35 million by 2032, growing at a CAGR of 7.2% from 2023 to 2032.
- Increasing awareness around menstrual health is driving demand for high-quality, reliable, and comfortable feminine hygiene products, leading to higher market growth.
- Innovations in product formulations, such as organic cotton and eco-friendly alternatives, are gaining traction, catering to environmentally conscious consumers.
- The expansion of e-commerce platforms and direct-to-consumer sales has made feminine hygiene products more accessible, offering consumers greater convenience and product variety.
- Legislative support, such as the removal of sales taxes and free access in public institutions, is making feminine hygiene products more affordable and widely available.
- High price sensitivity remains a key restraint, especially in economically disadvantaged areas, limiting the widespread adoption of premium and organic products.
- Regional variations show a preference for premium and organic products in the Northeast, while the South and West are shifting towards sustainable and innovative menstrual solutions.
Report Scope
This report segments the U.S. Feminine Hygiene Products Market as follow

Market Drivers:
Increasing Awareness of Menstrual Health
One of the primary drivers of growth in the U.S. feminine hygiene products market is the rising awareness surrounding menstrual health. Over the past few years, there has been a significant shift in consumer attitudes towards menstrual hygiene, with many women increasingly prioritizing their health and well-being. This shift is a result of heightened education on the importance of maintaining proper hygiene during menstruation, particularly with the proliferation of awareness campaigns and educational programs. Public health initiatives and social media campaigns have played a crucial role in dismantling the stigma associated with menstruation, encouraging open conversations about menstrual health. As a result, more women are opting for high-quality and reliable feminine hygiene products that ensure comfort and hygiene, driving increased demand for these products in the market.
Product Innovation and Consumer Preferences
Product innovation is another significant factor propelling the U.S. feminine hygiene products market. As consumer preferences continue to evolve, manufacturers are developing new and improved products to meet the demand for better performance, comfort, and sustainability. For example, in December 2022, Trace Femcare introduced tampons made from Climate Beneficial Cotton and regenerative hemp fiber, directly addressing consumer demand for environmentally responsible products. Moreover, advancements in product designs, such as ultra-thin pads, tampons with leak-proof protection, and menstrual cups, have increased the appeal of feminine hygiene products. This innovation not only enhances comfort but also caters to the growing demand for sustainable and eco-friendly alternatives. Consumers are increasingly drawn to products that offer better functionality, reliability, and sustainability, which has prompted manufacturers to focus on product development and innovation to stay competitive in the market.
Growth of E-commerce and Direct-to-Consumer Sales
The rapid growth of e-commerce and direct-to-consumer sales channels is reshaping the way feminine hygiene products are marketed and distributed in the U.S. As more consumers turn to online shopping for convenience, e-commerce platforms have become a vital avenue for purchasing feminine hygiene products. Online retailers offer a wide selection of products, from well-known brands to niche, organic, or eco-friendly options, giving consumers a broader range of choices. This shift towards online shopping has been further accelerated by the COVID-19 pandemic, which has led to a surge in online shopping habits. Direct-to-consumer brands, such as Thinx and Cora, have also leveraged e-commerce to build strong brand loyalty by offering subscription models that deliver products directly to consumers’ doors, providing convenience and cost savings. This transition towards digital platforms is expanding the reach of feminine hygiene products and increasing their availability to a larger audience.
Legislative Support and Public Initiatives
Legislative support and public initiatives aimed at making feminine hygiene products more accessible are also driving market growth in the U.S. Several states and local governments have passed laws that eliminate sales taxes on menstrual products, reducing the financial burden on consumers. For example, in 2020, Congresswoman Grace Meng introduced the Good Samaritan Menstrual Products Act, which would allow for more menstrual products to be donated and distributed by nonprofit organizations by providing liability protection to donors and distributors. Additionally, public initiatives like providing free access to menstrual products in schools, prisons, and public buildings are helping to ensure that menstruation is treated as a basic health need rather than a luxury. These efforts are contributing to the normalization of menstruation and increasing product availability, which is expected to boost the overall market. The growing recognition of menstrual products as essential goods has created a more favorable environment for market expansion, with more consumers able to access these products without facing economic barriers. This legislative support further reinforces the market’s growth potential, ensuring that feminine hygiene products are both affordable and widely available.
Market Trends:
Rising Demand for Organic and Sustainable Products
A notable trend in the U.S. feminine hygiene products market is the growing demand for organic and sustainable alternatives. As consumers become more conscious of environmental issues and their health, there has been a significant shift towards products made from organic materials, such as organic cotton. This trend is driven by increasing concerns about the chemicals and pesticides used in conventional cotton farming, which can affect both the environment and human health. For example, Cora offers a range of organic tampons, pads, liners, and menstrual cups, emphasizing both skin sensitivity and environmental responsibility. Additionally, sustainable packaging, such as biodegradable and recyclable materials, is increasingly being prioritized by consumers. This growing preference for organic and sustainable feminine hygiene products aligns with the broader movement towards environmental sustainability and healthier, chemical-free lifestyles.
Technological Advancements in Product Design
Technological advancements in product design are also shaping the U.S. feminine hygiene products market. Manufacturers are investing in research and development to create products that offer enhanced comfort, performance, and ease of use. For example, the development of ultra-thin pads and tampons with superior absorbency has become a key trend. These products cater to women seeking discreet, comfortable options that do not compromise on effectiveness. Another innovation is the rise of menstrual cups, which are becoming more popular due to their long-lasting and eco-friendly properties. The ability to wear these cups for extended periods without the need for frequent changes appeals to many consumers looking for convenience and cost savings. As these innovations continue to improve, the market is expected to see even more advanced and efficient product designs.
Shift Toward Subscription Services
Subscription-based models are rapidly gaining popularity in the U.S. feminine hygiene products market. Consumers are increasingly turning to subscription services that deliver feminine hygiene products directly to their doors on a regular basis. This trend is particularly appealing to busy individuals who value convenience and consistency in purchasing essential items. Direct-to-consumer brands such as Cora and Lola have capitalized on this trend by offering customizable subscription boxes that allow customers to choose their preferred products and receive regular shipments. Subscription services not only ensure product availability but also help reduce the inconvenience of last-minute shopping trips, particularly for sensitive products like sanitary pads and tampons. The trend toward subscription services is expected to grow as consumers seek more convenient and personalized shopping experiences.
Growing Focus on Menstrual Health Education
The increasing focus on menstrual health education is another key trend influencing the U.S. feminine hygiene products market. With a greater emphasis on health and wellness, both consumers and healthcare organizations are dedicating more resources to menstrual health education. Schools, social media platforms, and healthcare professionals are increasingly educating individuals about the importance of menstrual hygiene and the various products available. This has led to a greater understanding of the options available for menstrual care, encouraging more women to explore and invest in products that best suit their needs. For instance, Bayer’s Midol, in partnership with the nonprofit Period., launched the “PeriodTalk” campaign to address knowledge gaps: a survey found that only about 40% of U.S. menstruating adults could name all four phases of the menstrual cycle, and over 85% reported that period symptoms had impacted their daily lives in the previous three months. This growing awareness has contributed to the normalization of menstruation and a broader acceptance of feminine hygiene products, further driving their adoption across diverse demographic groups. As educational efforts continue to expand, the market for feminine hygiene products is poised for sustained growth.
Market Challenges Analysis:
High Price Sensitivity
One of the key market restraints for the U.S. feminine hygiene products market is the high price sensitivity among consumers. Despite the increasing availability of premium and organic products, many consumers remain hesitant to pay higher prices for these products, especially given the ongoing economic pressures. While a significant portion of the market is driven by a willingness to invest in high-quality, eco-friendly products, the overall price sensitivity limits the adoption of these products, particularly among budget-conscious individuals. This constraint is especially noticeable in economically disadvantaged communities, where the affordability of feminine hygiene products remains a significant barrier. As a result, there is a growing demand for more affordable options, which can challenge manufacturers focused on high-end, premium products.
Lack of Awareness in Rural Areas
Another challenge faced by the U.S. feminine hygiene products market is the lack of awareness and access to menstrual health education and products in rural areas. While urban centers benefit from widespread educational campaigns and product availability, rural regions still face challenges in terms of both awareness and accessibility. For instance, nonprofit organizations report that period supplies are significantly more expensive and less available in rural and Indigenous communities, forcing many to rely on donated products from schools, food pantries, or churches, which may not always meet their needs. Moreover, there can be a lack of menstrual health education, which may contribute to stigma and misinformation surrounding menstruation. Overcoming these barriers will require targeted outreach efforts and increased product distribution in underserved areas to ensure more inclusive access to feminine hygiene solutions.
Regulatory Challenges
The feminine hygiene products market also faces regulatory challenges, particularly in terms of labeling and ingredient transparency. While several states have made progress in eliminating sales tax on menstrual products, others still impose taxes or restrictions on these goods. Additionally, there is an increasing demand for transparency regarding the ingredients used in these products. Manufacturers must navigate a complex regulatory environment as they work to meet consumer expectations for safer, more natural products, which could lead to higher compliance costs.
Market Opportunities:
The U.S. feminine hygiene products market presents significant opportunities driven by the increasing consumer shift toward sustainable and organic solutions. As more women seek products that align with their environmental and health-conscious values, the demand for organic cotton-based pads, tampons, and menstrual cups continues to rise. Consumers are increasingly prioritizing products that are free from chemicals, fragrances, and synthetic materials, creating a lucrative market for eco-friendly alternatives. Manufacturers have the opportunity to expand their product offerings by incorporating organic and biodegradable materials, as well as adopting environmentally friendly packaging, to cater to this growing demand. This trend is particularly prominent among younger consumers who are more attuned to environmental and health-related concerns, offering companies a chance to tap into a dedicated market segment focused on wellness and sustainability.
Another significant opportunity in the U.S. feminine hygiene products market lies in the continued growth of e-commerce and subscription-based services. As more consumers shift towards online shopping for convenience and privacy, the potential for direct-to-consumer brands to expand is considerable. Subscription models, which offer personalized product deliveries, are gaining popularity due to their convenience and reliability. This trend is particularly appealing in the U.S., where consumers seek ease and consistency in purchasing everyday items. Brands that can successfully leverage e-commerce platforms and subscription services to deliver tailored solutions are well-positioned to capture a larger share of the market. The expansion of digital channels also enables brands to reach underserved areas, offering a scalable opportunity to grow market presence across diverse demographic segments.
Market Segmentation Analysis:
The U.S. feminine hygiene products market is segmented into several categories based on type, nature, age group, and distribution channel, each influencing consumer preferences and market dynamics.
By Type: The market is primarily divided into sanitary napkins, tampons, panty liners, menstrual cups, and other products. Sanitary napkins hold the largest market share due to their widespread usage and familiarity. Tampons and panty liners are also popular, particularly among women seeking discreet and comfortable options. Menstrual cups are gaining traction for their sustainability and long-lasting nature, although they still represent a smaller portion of the market compared to traditional products.
By Nature: Feminine hygiene products are further classified as reusable and disposable. Disposable products dominate the market, offering convenience and ease of use, while reusable options, such as menstrual cups and cloth pads, are growing in popularity due to their eco-friendly nature and cost savings over time. This segment is expanding, particularly among environmentally conscious consumers.
By Age-Group: The market is segmented by age group into pre-teens, teens, adults, and senior citizens. The largest share is held by adults, who represent the most consistent users of feminine hygiene products. However, there is increasing awareness and adoption of products among teens and pre-teens, as education and product availability improve. Senior citizens are a niche segment, with products tailored to meet specific needs, such as incontinence products.
By Distribution Channel: Distribution is largely dominated by supermarkets and drug stores, which provide wide accessibility to consumers. Online retail stores are experiencing rapid growth, driven by the increasing preference for convenience and home delivery, offering an expanding platform for sales. Other channels include pharmacies and specialty stores.
Segmentation:
By Type
- Sanitary Napkins
- Tampons
- Panty Liners
- Menstrual Cups
- Others
By Nature
- Reusable
- Disposable
By Age-Group
- Pre-teens
- Teens
- Adults
- Senior Citizens
By Distribution Channel
- Supermarkets
- Drug Stores
- Online Retail Stores
- Others
Regional Analysis:
The U.S. feminine hygiene products market exhibits regional variations influenced by demographic, economic, and cultural factors. While comprehensive regional market share data is limited, insights into regional dynamics can be gleaned from available information.
Northeast Region
The Northeast, encompassing states like New York, Massachusetts, and Pennsylvania, is characterized by a high level of urbanization and a strong emphasis on health and wellness. This region has seen increased awareness and accessibility of feminine hygiene products, driven by educational initiatives and supportive policies. However, specific market share figures for this region are not readily available.
Midwest Region
The Midwest, including states such as Illinois, Ohio, and Michigan, presents a diverse demographic with varying needs. While detailed market share data is scarce, the region's emphasis on healthcare access and affordability influences consumer behavior in the feminine hygiene market.
South Region
The South, comprising states like Texas, Florida, and Georgia, has a significant population and diverse economic conditions. While exact market share statistics are not specified, the region's large consumer base contributes notably to the overall market dynamics. Initiatives aimed at increasing product accessibility and affordability are particularly impactful in this region.
West Region
The West, including states such as California, Washington, and Colorado, is known for its progressive approach to health and sustainability. While precise market share data is not available, the region's focus on eco-friendly products and innovation drives consumer preferences in the feminine hygiene sector.
Key Player Analysis:
- Johnson & Johnson
- Procter & Gamble
- Kimberly-Clark
- Essity Aktiebolag
- Kao Corporation
- Daio Paper Corporation
- Unicharm Corporation
- Premier FMCG
- Ontex
- Hengan International Group Company Ltd
- Drylock Technologies
- Natracare LLC
- First Quality Enterprises, Inc
- Yoni
Competitive Analysis:
The U.S. feminine hygiene products market is highly competitive, with key players focusing on innovation, sustainability, and consumer convenience. Leading brands such as Procter & Gamble (Always), Kimberly-Clark (Kotex), and Edgewell Personal Care (Playtex) dominate the market with a wide range of sanitary napkins, tampons, and panty liners. These companies continue to invest in research and development to improve product quality and functionality, such as introducing organic and eco-friendly product lines. In addition to established players, direct-to-consumer brands like Cora, Thinx, and Lola are gaining traction by offering subscription services and personalized product options. These brands often emphasize sustainability and natural materials, appealing to environmentally conscious consumers. The growing preference for organic and reusable products is prompting traditional brands to expand their offerings, creating an increasingly competitive market landscape. Consumer demand for innovative and eco-friendly products is likely to drive further market evolution.
Recent Developments:
- In March 2025, Procter & Gamble launched Always Pocket Flexfoam, a new addition to its feminine care line, designed for portability and on-the-go protection. The launch was celebrated with a high-profile partnership at Coachella 2025, where Always and Tampax became the festival’s first-ever period care partners, providing products and on-site activations for attendees. This campaign highlights P&G’s commitment to both product innovation and experiential marketing in the feminine hygiene space.
- In March 2024, Flex introduced new odor-fighting bamboo pads and liners to the U.S. feminine hygiene market. These products are designed to deliver superior odor control while prioritizing environmental sustainability by using bamboo fibers. This launch reflects Flex’s ongoing commitment to eco-friendly innovation and aims to satisfy growing consumer demand for both effective and sustainable feminine hygiene solutions.
- In July 2023, Unicharm’s subsidiary in Indonesia launched Charm Daun Sirih + Herbal Bio sanitary napkins, featuring eco-friendly materials. The company continues to innovate with products using bio-materials and is expanding its range of disposable period underwear to meet growing demand, particularly among younger consumers.
- In February 2022, Kimberly-Clark Corporation made a significant move in the U.S. feminine hygiene sector by acquiring a majority stake in Thinx Inc. This strategic acquisition strengthens Kimberly-Clark’s position in the market and supports Thinx’s direct-to-consumer business model, while also expanding category growth through retail partnerships. Thinx, known for its innovative feminine hygiene products, benefits from Kimberly-Clark’s resources and market reach, underscoring a shared commitment to innovation and market expansion.
Market Concentration & Characteristics:
The U.S. feminine hygiene products market is characterized by a moderate to high concentration, with leading multinational corporations holding substantial market shares. Procter & Gamble (Always), Kimberly-Clark (Kotex), and Edgewell Personal Care (Playtex) are among the dominant players, leveraging extensive distribution networks and brand recognition to maintain their positions. These companies have a significant presence in both offline and online retail channels, catering to a broad consumer base. However, the market also accommodates a growing number of direct-to-consumer brands such as Thinx, Cora, and Lola, which focus on niche segments like organic and eco-friendly products, often utilizing subscription models to build customer loyalty. The market's characteristics reflect evolving consumer preferences, including a shift towards sustainable and organic products, increased demand for convenience through online shopping and subscription services, and a heightened focus on menstrual health education. These trends are prompting both established and emerging companies to innovate and adapt their product offerings to meet the diverse needs of consumers. Additionally, legislative initiatives aimed at improving access to feminine hygiene products are influencing market dynamics, potentially expanding the consumer base and altering competitive strategies.
Report Coverage:
The research report offers an in-depth analysis based on Type, Nature, Age-Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for organic and eco-friendly feminine hygiene products will continue to rise as consumers prioritize sustainability and health-conscious choices.
- Subscription-based services will gain more traction, offering consumers personalized and convenient purchasing options.
- E-commerce will increasingly dominate sales channels, providing wider accessibility and tailored customer experiences.
- Product innovation will focus on comfort, with advancements in ultra-thin, leak-proof, and odor-controlling products.
- The growth of reusable products, such as menstrual cups and cloth pads, will cater to environmentally conscious and cost-savvy consumers.
- Enhanced menstrual health education will drive awareness, leading to higher adoption of feminine hygiene products across diverse demographics.
- Government initiatives, including tax exemptions and free distribution programs, will boost product accessibility for underserved populations.
- Consumer preferences will shift towards products with transparent ingredient labeling, promoting safety and trust.
- Regulatory changes around labeling, ingredient transparency, and product safety will influence product development and market competition.
- The U.S. market will see a rise in niche brands targeting specific needs, including organic, hypoallergenic, and vegan product lines.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Awareness of Menstrual Health
Educational campaigns and public health initiatives are reducing stigma and encouraging open conversations about menstrual hygiene, leading more women to seek high-quality, reliable feminine hygiene products.
Product Innovation and Eco-Friendly Alternatives
Manufacturers are introducing organic, biodegradable, and sustainable products, such as organic cotton pads and menstrual cups, to meet the growing demand from environmentally conscious consumers, driving market expansion.
Growth of E-commerce and Subscription Services
The rise of online retail and direct-to-consumer subscription models has made feminine hygiene products more accessible and convenient, expanding reach to a broader demographic and supporting recurring purchases.
Legislative Support and Public Initiatives
Government actions such as eliminating sales taxes on menstrual products and providing free access in schools and public institutions are reducing economic barriers and increasing product accessibility, fueling market growth.
Technological Advancements in Product Design
Innovations such as ultra-thin, leak-proof, and odor-controlling products are enhancing comfort and performance, attracting consumers seeking improved functionality and convenience in feminine hygiene solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Feminine Hygiene Products Market?
What factors are driving the growth of the U.S. Feminine Hygiene Products market?
What are some challenges faced by the U.S. Feminine Hygiene Products market?
Who are the major players in the U.S. Feminine Hygiene Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sanitary Napkins
- 1.2.2 Tampons
- 1.2.3 Panty Liners
- 1.2.4 Menstrual Cups
- 1.2.5 Others
- 1.3 By Nature
- 1.3.1 Reusable
- 1.3.2 Disposable
- 1.4 By Age-Group
- 1.4.1 Pre-teens
- 1.4.2 Teens
- 1.4.3 Adults
- 1.4.4 Senior Citizens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 6,849.11 million → 2032: USD 12,916.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Feminine Hygiene Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Feminine Hygiene Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Feminine Hygiene Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Feminine Hygiene Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Feminine Hygiene Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Feminine Hygiene Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Feminine Hygiene Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Feminine Hygiene Products Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 6,849.11 million → 2032: USD 12,916.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Feminine Hygiene Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sanitary Napkins
- 12.3.7.2 Tampons
- 12.3.7.3 Panty Liners
- 12.3.7.4 Menstrual Cups
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Nature - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Reusable
- 12.4.7.2 Disposable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Age-Group - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pre-teens
- 12.5.7.2 Teens
- 12.5.7.3 Adults
- 12.5.7.4 Senior Citizens
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Feminine Hygiene Products Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Feminine Hygiene Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Feminine Hygiene Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Procter & Gamble
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Kimberly-Clark
- 17.4 Johnson & Johnson
- 17.5 Essity Aktiebolag
- 17.6 Kao Corporation
- 17.7 Unicharm Corporation
- 17.8 Daio Paper Corporation
- 17.9 Ontex
- 17.10 Natracare LLC
- 17.11 First Quality Enterprises, Inc
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

