
Assisted Living Market Overview:
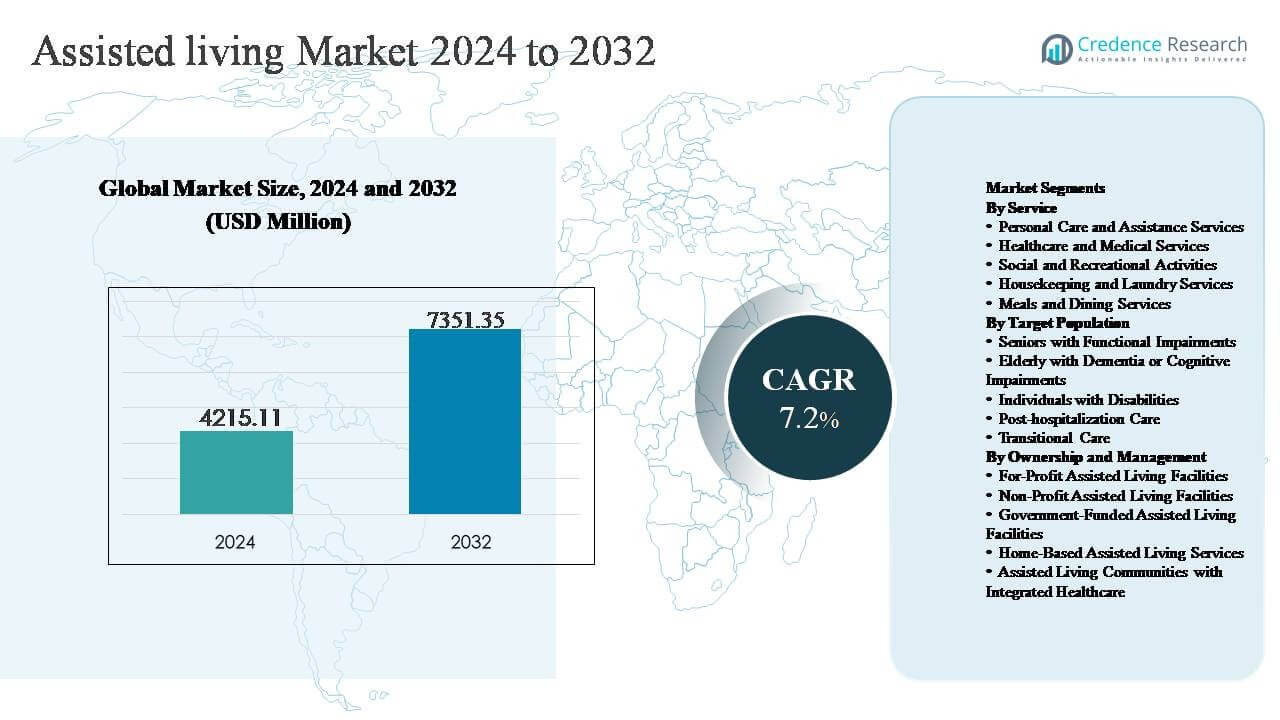
The assisted living market was valued at USD 4,215.11 million in 2024 and is projected to reach USD 7,351.35 million by 2032, expanding at a CAGR of 7.2% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Assisted Living Market Size 2024 | USD 4,215.11 million |
| Assisted Living Market , CAGR | 7.2% |
| Assisted Living Market Size 2032 | USD 7,351.35 million |
Assisted Living Market Insights
- Market growth is driven by the rapidly aging population, increasing life expectancy, and rising prevalence of chronic and functional impairments, which continue to shift demand toward assisted living as a preferred alternative to institutional nursing care.
- Key market trends include the integration of healthcare services, digital health monitoring, and lifestyle-focused amenities, with personal care and assistance services remaining the dominant service segment due to consistent daily care requirements.
- The competitive landscape is moderately fragmented, led by large for-profit operators that benefit from scalable models, private investments, and integrated care offerings, while regional players compete through localized and cost-effective service delivery.
- Regionally, North America holds about 42% market share, followed by Europe at 28% and Asia-Pacific at 20%, with Asia-Pacific emerging as the fastest-growing region due to demographic aging and expanding private senior housing.
Assisted Living Market Segmentation Analysis:
By Service:
Within the assisted living market, personal care and assistance services represent the dominant service sub-segment, accounting for the largest market share due to their central role in daily resident support. These services include assistance with bathing, dressing, mobility, and medication reminders, making them essential for aging residents seeking independence with supervision. Growth is driven by the rising senior population with activities-of-daily-living (ADL) limitations and the preference for non-institutional care settings. While healthcare and medical services are expanding through on-site nursing and chronic disease monitoring, personal care remains the primary driver of occupancy and revenue stability.
- For instance, Brookdale Senior Living operates 589 senior living communities across 41 states following a strategic reduction from 645 earlier in the year and has implemented the PointClickCare electronic health record (EHR) platform.
By Target Population:
By target population, seniors with functional impairments constitute the leading sub-segment, holding the highest market share as assisted living facilities primarily cater to age-related mobility, sensory, and self-care limitations. Demand is driven by increasing life expectancy, higher prevalence of arthritis, cardiovascular conditions, and fall risks among older adults. This group favors assisted living over skilled nursing due to lower medical intensity and greater autonomy. Although dementia and cognitive impairment care is growing rapidly through memory-care units, functionally impaired seniors remain the core resident base sustaining long-term market demand.
- For instance, Atria Senior Living manages over 250 senior living communities and deploys electronic care planning systems that track individualized functional-support needs across thousands of residents, enabling structured assistance for ambulation, transfers, and personal hygiene.
By Ownership and Management:
In terms of ownership and management, for-profit assisted living facilities dominate the market, supported by strong private investment, scalable operating models, and rapid facility expansion across urban and suburban regions. These providers benefit from flexible pricing structures, premium service offerings, and the ability to integrate technology-enabled care and hospitality features. Market growth is driven by rising investor interest in senior housing as a stable, long-term asset class. While non-profit and government-funded facilities play a critical role in affordability, for-profit operators lead in capacity additions and service diversification.
Key Growth Driver
Rapidly Aging Population and Increasing Longevity
The assisted living market is strongly driven by the global rise in the elderly population and increasing life expectancy. Advancements in healthcare and improved living standards have extended average lifespans, resulting in a larger population aged 65 and above requiring long-term support. Many seniors experience age-related functional limitations that do not necessitate full-scale nursing care but require daily assistance with mobility, medication adherence, and personal care. Assisted living facilities effectively address this gap by offering structured support while preserving resident independence. Additionally, smaller family sizes, geographic mobility of younger generations, and reduced availability of informal caregivers have intensified reliance on professional senior care solutions. These demographic shifts continue to expand the core consumer base for assisted living services across both developed and emerging markets.
- For instance,Sunrise Senior Living operates more than 240 senior living communities across the United States and Canada. Its communities integrate age-friendly architectural features, such as lean rails in hallways, custom-height furniture with armrests for easy mobility, and walk-in showers.
Rising Prevalence of Chronic and Cognitive Conditions
The growing incidence of chronic diseases such as diabetes, cardiovascular disorders, arthritis, and neurodegenerative conditions is a major driver for assisted living demand. Many older adults require ongoing supervision, medication management, and assistance with daily routines, which assisted living facilities provide in a cost-effective and less clinical environment compared to nursing homes. The increasing diagnosis of mild cognitive impairment and early-stage dementia further accelerates demand for structured residential care with trained staff and safety monitoring. Facilities offering specialized memory care units and personalized health management programs are particularly well positioned. This medical and functional complexity among seniors reinforces assisted living as a preferred intermediate care model between independent living and skilled nursing facilities.
- For instance, Ensign Group operates more than 290 senior care facilities across the U.S., integrating electronic clinical documentation platforms that support daily medication administration records for tens of thousands of residents with chronic conditions.
Preference for Community-Based and Supportive Living Models
Changing consumer preferences toward community-oriented living environments are significantly boosting the assisted living market. Seniors increasingly seek housing options that combine privacy, social engagement, and access to support services. Assisted living communities address emotional well-being by offering social activities, wellness programs, and communal dining, reducing isolation and improving quality of life. Families also favor these settings due to enhanced safety, professional oversight, and predictable care costs. The shift away from institutional care models toward residential-style communities has encouraged operators to invest in modern infrastructure, hospitality-driven designs, and lifestyle-focused amenities, further strengthening market adoption.
Key Trend & Opportunity
Integration of Digital Health and Smart Care Technologies
The adoption of digital health technologies presents a major growth opportunity within the assisted living sector. Facilities increasingly deploy remote health monitoring systems, electronic health records, fall-detection sensors, and wearable devices to improve resident safety and care efficiency. These technologies enable early detection of health issues, reduce emergency incidents, and support data-driven care planning. Smart room systems and telehealth services also enhance resident comfort while reducing staffing strain. Operators leveraging technology gain operational advantages through improved compliance, reduced care costs, and enhanced family transparency. As technology acceptance among seniors improves, digital integration is expected to become a key differentiator for assisted living providers.
- For instance, Kindred Hospitals, now a division of ScionHealth, utilizes telehealth-enabled clinical oversight across its network of more than 50 specialty hospitals in 16 states. This platform allows physician-led care teams to conduct virtual consultations and monitor medically complex patients remotely, facilitating specialized care without requiring on-site presence for every specialist interaction.
Expansion of Integrated Healthcare and Specialized Care Models
Assisted living communities are increasingly integrating healthcare services through partnerships with hospitals, home health agencies, and specialty care providers. This trend creates opportunities to offer on-site primary care, rehabilitation, memory care, and post-acute services. Facilities that combine housing with coordinated healthcare reduce hospital readmissions and improve continuity of care. Demand for transitional and post-hospitalization care within assisted living settings is also rising, driven by shorter hospital stays and value-based care initiatives. Providers that expand service depth and clinical capabilities can capture higher-acuity residents while maintaining cost advantages over skilled nursing facilities.
- For instance, Diversicare Healthcare Services operates 49 senior living and skilled nursing communities. These facilities utilize integrated clinical service models that feature 24-hour on-site nursing teams and formalized transitional care pathways designed to coordinate a patient's move from post-hospital recovery back to the community.
Key Challenge
High Operating Costs and Workforce Shortages
One of the primary challenges facing the assisted living market is the rising cost of operations, particularly labor expenses. Facilities require trained caregivers, nurses, and support staff to maintain service quality and regulatory compliance. However, workforce shortages, high employee turnover, and wage inflation increase financial pressure on operators. Recruitment and retention challenges are compounded by physically demanding work conditions and limited availability of skilled personnel. These factors can constrain facility capacity, reduce service consistency, and impact profitability, especially for smaller and non-profit providers.
Affordability Constraints and Regulatory Complexity
Affordability remains a significant barrier to assisted living adoption, particularly for middle-income seniors. Monthly fees often exceed household retirement income, limiting access without family support or long-term care insurance. Additionally, the sector operates under complex regulatory frameworks that vary by region, covering staffing ratios, safety standards, and care protocols. Compliance requirements increase administrative burdens and capital investment needs. Operators must balance regulatory adherence with cost control while maintaining service quality, which poses ongoing challenges to sustainable expansion.
Regional Analysis
North America:
North America dominates the assisted living market, accounting for approximately 42% of global market share, driven by a well-established senior care infrastructure and a high proportion of elderly residents. The United States leads the region due to widespread adoption of assisted living communities, strong private-sector investment, and favorable reimbursement and insurance penetration. Demand is supported by rising life expectancy, increasing prevalence of chronic conditions, and strong consumer awareness of organized senior living options. The region also benefits from early adoption of digital health tools, integrated care models, and premium lifestyle-oriented assisted living facilities.
Europe:
Europe represents around 28% of the global assisted living market, supported by rapidly aging populations across Western and Northern Europe. Countries such as Germany, the United Kingdom, France, and the Nordic nations drive demand through structured eldercare systems and growing acceptance of residential care alternatives. Government-supported social care frameworks and non-profit providers play a significant role alongside private operators. The market emphasizes quality standards, resident safety, and community-based care models. Increasing dementia prevalence and policy initiatives aimed at reducing hospital burden continue to support steady assisted living adoption across the region.
Asia-Pacific:
Asia-Pacific holds approximately 20% of the global assisted living market share and represents the fastest-growing regional segment. Rapid demographic aging in countries such as Japan, China, South Korea, and Australia is a primary growth driver. Urbanization, smaller family structures, and increasing female workforce participation are reducing traditional family caregiving, accelerating demand for assisted living facilities. While penetration remains lower than in Western regions, rising disposable incomes and expanding private-sector senior housing developments are improving accessibility. Governments in several countries are also promoting organized eldercare to address long-term aging challenges.
Latin America:
Latin America accounts for nearly 6% of the global assisted living market, with growth driven by demographic transition and gradual modernization of senior care services. Countries such as Brazil, Mexico, and Chile are witnessing increasing demand for assisted living as life expectancy rises and urban lifestyles limit family-based caregiving. The market remains relatively fragmented, with a mix of small private facilities and community-based care models. Limited affordability and lower awareness compared to developed regions restrain faster adoption, though private investment and healthcare partnerships are gradually strengthening regional capacity.
Middle East & Africa:
The Middle East & Africa region holds approximately 4% of the global assisted living market, reflecting an early-stage but gradually developing landscape. Demand is emerging in countries such as the UAE, Saudi Arabia, and South Africa, driven by improving healthcare infrastructure, rising elderly populations, and expatriate demographics. Cultural preferences for family care have historically limited adoption; however, changing social dynamics and urbanization are increasing acceptance of assisted living services. Growth is supported by private healthcare investments, medical tourism expansion, and government initiatives aimed at strengthening long-term care systems.
Assisted Living Market Segmentations:
By Service
- Personal Care and Assistance Services
- Healthcare and Medical Services
- Social and Recreational Activities
- Housekeeping and Laundry Services
- Meals and Dining Services
By Target Population
- Seniors with Functional Impairments
- Elderly with Dementia or Cognitive Impairments
- Individuals with Disabilities
- Post-hospitalization Care
- Transitional Care
By Ownership and Management
- For-Profit Assisted Living Facilities
- Non-Profit Assisted Living Facilities
- Government-Funded Assisted Living Facilities
- Home-Based Assisted Living Services
- Assisted Living Communities with Integrated Healthcare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the assisted living market is moderately fragmented, characterized by the presence of large multinational operators alongside regional and local service providers. Leading companies compete on service quality, facility scale, geographic reach, and the breadth of care offerings, with an increasing focus on integrated healthcare and lifestyle-oriented amenities. Major players continue to expand through acquisitions, new community developments, and partnerships with healthcare providers to strengthen care coordination and occupancy rates. Differentiation is increasingly driven by investments in digital health monitoring, memory care specialization, and personalized resident services. At the same time, regional operators maintain competitiveness through localized care models, cost-effective service delivery, and strong community engagement. Regulatory compliance, workforce management, and the ability to scale operations efficiently remain key competitive factors shaping long-term market positioning.
Key Player Analysis
- Brookdale Senior Living
- Atria Senior Living
- Holiday Retirement
- Merrill Gardens
- Five Star Senior Living
- Ensign Group
- Kindred Healthcare
- SavaSeniorCare
- Diversicare Healthcare Services
- LeadingAge
Recent Developments
- In November 2025, Brookdale Senior Living announced that eight of its skilled nursing communities were honored as “Best Nursing Homes of 2026” by U.S. News & World Report, signifying quality recognition across a portion of its care continuum that overlaps with assisted living and related care services.
- In October 2025, Brookdale reported consolidated occupancy results for September 2025, noting that its 623 communities across 41 states were actively serving approximately 57,000 residents, reflecting ongoing operational scale and engagement amid the senior living landscape.
- In August 2025, Atria at Foster Square a 155-unit senior living community in Foster City, California that includes assisted living offerings was sold by JLL Capital Markets to a new investor group, with Atria continuing as the operating manager under its Signature Collection brand.
Report Coverage
The research report offers an in-depth analysis based on Service, Target Population, Ownership and Management and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for assisted living, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the assisted living market projected to grow between 2024 and 2032?
Which assisted living segment held the largest share in 2024?
What are the primary factors fueling the growth of the assisted living market?
Who are the leading companies in the assisted living market?
Which region commanded the largest share of the assisted living market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,215.11 million → 2032: USD 7,351.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Assisted Living Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Assisted Living Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Assisted Living Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Assisted Living Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Assisted Living Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Assisted Living Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Assisted Living Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Assisted Living Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,215.11 million → 2032: USD 7,351.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Assisted Living Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Assisted Living Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Assisted Living Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Assisted Living Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

