
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wealth Management Software Market Size 20244 | USD 1,508.92 million |
| Wealth Management Software Market, CAGR | 14.07% |
| Wealth Management Software Market Size 2032 | USD 4,318.07 million |
Market Overview
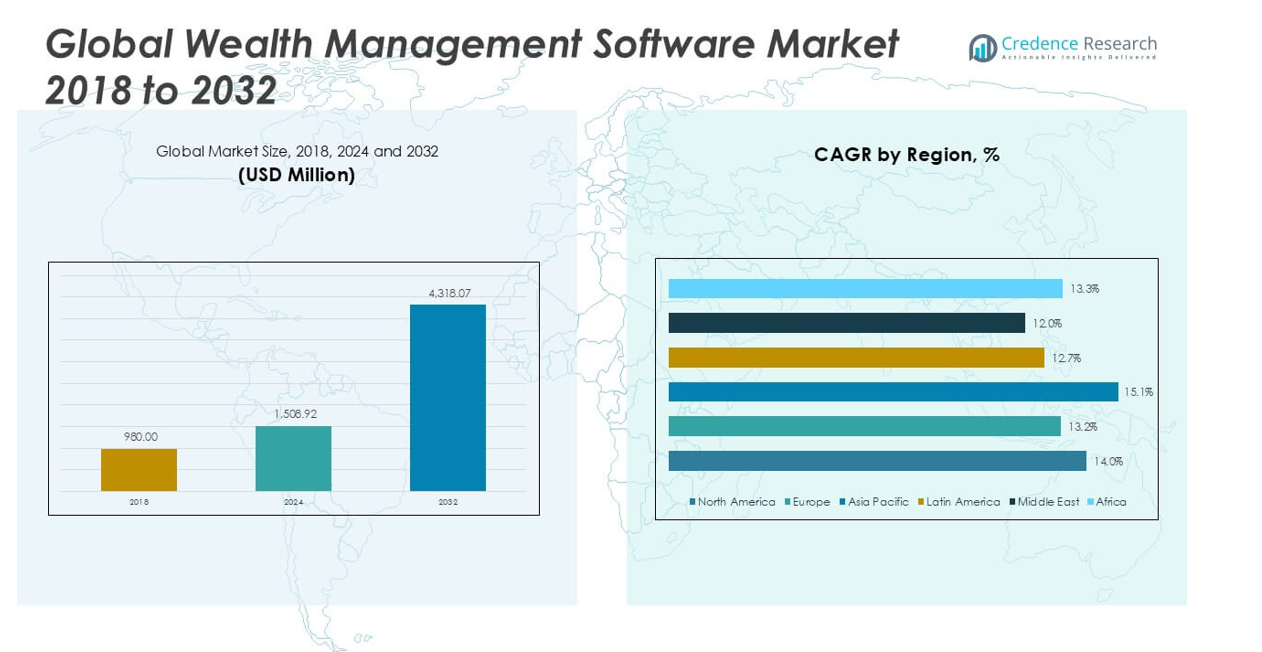
The Wealth Management Software Market was valued at USD 980.00 million in 2018, reached USD 1,508.92 million in 2024, and is anticipated to reach USD 4,318.07 million by 2032, reflecting a compound annual growth rate (CAGR) of 14.07% during the forecast period.
The Wealth Management Software Market is experiencing robust growth driven by rising demand for digital solutions that streamline portfolio management, enhance client engagement, and ensure regulatory compliance. Increasing adoption of advanced analytics, artificial intelligence, and automation enables wealth managers to deliver personalized investment advice and optimize operational efficiency. The proliferation of high-net-worth individuals and the shift toward hybrid advisory models further fuel software adoption among financial institutions. Cloud-based platforms and mobile applications are gaining popularity for their scalability and accessibility, while stringent data security and privacy regulations encourage the integration of secure and compliant solutions. The market is also witnessing a trend toward open architecture platforms that support seamless integration with third-party applications, allowing wealth managers to offer holistic financial planning services. As competition intensifies, vendors continue to innovate with user-centric features, driving further digital transformation across the wealth management landscape.
Geographical analysis of the Wealth Management Software Market reveals strong growth across North America, Europe, and Asia Pacific, with each region driven by unique factors such as advanced financial infrastructure, regulatory modernization, and rising digital adoption. North America leads with high digital innovation and integration of advanced analytics, while Europe sees momentum from hybrid advisory models and sustainable investment trends. Asia Pacific stands out for its rapid expansion, supported by a growing high-net-worth population and robust fintech ecosystems in countries like China, Japan, and Singapore. Latin America, the Middle East, and Africa show increasing adoption rates as financial institutions modernize their IT infrastructure and embrace digital transformation. Key players shaping the global landscape include SS&C Technologies Holdings, Inc., Temenos Headquarters SA, and Fidelity National Information Services, Inc., all of which drive continuous innovation and deliver comprehensive solutions to meet evolving industry needs.
Market Insights
- The Wealth Management Software Market reached USD 1,508.92 million in 2024 and is projected to hit USD 4,318.07 million by 2032, recording a CAGR of 14.07%.
- Growing demand for digital and automated financial advisory solutions fuels the market, as institutions seek to enhance operational efficiency and offer personalized services to diverse client segments.
- Digital transformation, adoption of artificial intelligence, and integration of cloud-based platforms define the latest trends, enabling wealth managers to deliver seamless and highly customized experiences.
- Competitive dynamics are shaped by leading companies such as SS&C Technologies Holdings, Inc., Temenos Headquarters SA, and Fidelity National Information Services, Inc., which continue to innovate through advanced analytics, robust security features, and open architecture solutions.
- The market faces restraints from complex regulatory requirements, high implementation costs, and integration challenges with legacy systems, which can slow the pace of technology adoption.
- North America leads in technology integration and digital innovation, while Europe follows with strong compliance-driven growth, and Asia Pacific shows the fastest expansion due to increasing digital adoption in key markets like China and Singapore.
- Regional markets in Latin America, the Middle East, and Africa are witnessing rising software adoption as financial institutions invest in IT modernization and digital client engagement to keep pace with evolving market demands.
Market Drivers
Digital Transformation Accelerates Adoption Across Financial Institutions
The Wealth Management Software Market is propelled by the rapid digital transformation of the financial services sector. Institutions seek comprehensive software solutions to streamline portfolio management, automate routine processes, and facilitate more efficient advisory services. It allows wealth managers to deliver personalized investment strategies by leveraging data analytics and real-time insights. Demand for seamless integration with existing IT infrastructure encourages vendors to offer open architecture solutions that support a range of third-party applications. It enhances operational efficiency, reduces manual errors, and enables faster decision-making. Financial institutions increasingly prioritize software that enables better client communication and more transparent reporting. The shift toward digital platforms drives long-term growth in the market.
- For instance, Temenos reports that more than 3,000 financial institutions globally use its digital banking platform, helping clients reduce onboarding times by up to 75%.
Regulatory Compliance Drives Investment in Advanced Software Solutions
Strict regulatory frameworks and evolving compliance requirements play a significant role in shaping the Wealth Management Software Market. Financial institutions face mounting pressure to adhere to data protection, anti-money laundering, and know-your-customer regulations. It compels wealth managers to adopt advanced software solutions that automate compliance checks and maintain robust audit trails. Enhanced regulatory scrutiny drives the development of solutions with strong reporting capabilities and comprehensive risk management tools. It helps firms reduce compliance-related risks and potential financial penalties. Regulatory changes across regions require adaptive software that can meet global standards and local nuances. This need for reliable compliance tools stimulates steady investment in wealth management technologies.
- For instance, SS&C Technologies Holdings, Inc. supports more than 18,000 financial services organizations, providing compliance solutions that process over 1 billion transactions annually.
Increasing Demand for Personalization and Client-Centric Services
Client expectations for personalized services are redefining the Wealth Management Software Market. Investors seek tailored portfolio management, dynamic financial planning, and real-time performance updates. It enables wealth managers to offer differentiated services by integrating artificial intelligence, predictive analytics, and customizable dashboards. Modern clients expect digital access to their portfolios and responsive communication channels, prompting firms to invest in user-friendly interfaces and mobile applications. It allows wealth managers to enhance engagement and foster stronger client relationships. Competitive pressures make personalization a key differentiator. Firms that offer advanced digital experiences can attract and retain high-value clients.
Growth of High-Net-Worth Individuals Expands Market Opportunities
The rising population of high-net-worth individuals (HNWIs) worldwide continues to drive the Wealth Management Software Market. Wealth managers seek scalable and flexible software platforms to serve a diverse and expanding client base. It supports sophisticated portfolio management, multi-asset allocation, and complex reporting requirements for affluent clients. Growing intergenerational wealth transfers require solutions that facilitate holistic family wealth planning and estate management. It enables firms to offer comprehensive advisory services across investment, tax, and legacy planning. Market players focus on developing robust solutions to address the evolving needs of HNWIs. The expanding affluent segment fuels ongoing market growth and innovation.
Market Trends
Rising Integration of Artificial Intelligence and Machine Learning
Artificial intelligence (AI) and machine learning are transforming the Wealth Management Software Market by enabling deeper client insights and automating complex investment processes. It leverages predictive analytics to assess risk profiles, forecast market trends, and generate tailored recommendations. Firms deploy AI-powered chatbots and virtual assistants to provide real-time support and enhance client interaction. It helps wealth managers improve efficiency by automating data aggregation and reporting functions. Enhanced AI capabilities empower firms to deliver a highly personalized advisory experience. Adoption of intelligent technologies marks a shift toward data-driven decision-making in the sector. Firms that embrace AI tools set new benchmarks for operational excellence and client satisfaction.
- For instance, Fidelity National Information Services, Inc. (FIS) has deployed AI-driven solutions that serve over 20,000 clients worldwide, with its AI-powered chatbot alone handling over 10 million customer queries annually.
Expansion of Cloud-Based Platforms and Mobile Accessibility
Cloud computing is a defining trend in the Wealth Management Software Market, offering scalability, flexibility, and cost efficiency. It enables wealth managers to access client portfolios, reports, and analytics from any location, facilitating remote advisory services. Cloud-based solutions simplify software upgrades, ensure secure data storage, and reduce IT infrastructure burdens. It supports real-time collaboration between advisors and clients, regardless of geographical boundaries. The proliferation of mobile applications extends these capabilities, allowing clients to monitor investments and receive timely alerts on their devices. Firms adopting cloud and mobile platforms deliver a superior user experience. The demand for anytime, anywhere access continues to shape technology investments.
- For instance, SEI Investments Company provides cloud-based solutions to over 7,500 clients, enabling daily processing of more than 450,000 portfolios and real-time access through mobile apps.
Increasing Focus on Open Architecture and Ecosystem Partnerships
Open architecture is redefining the Wealth Management Software Market, giving firms the flexibility to integrate multiple third-party solutions. It supports seamless connectivity with financial planning tools, custodians, and market data providers, enabling holistic client servicing. Firms prioritize platforms that offer robust application programming interfaces (APIs) to facilitate smooth data exchange and system interoperability. The trend encourages ecosystem partnerships, where wealth managers collaborate with fintechs and specialized service providers. It promotes innovation and allows for rapid deployment of new features and services. Open architecture models foster competitive differentiation and future-proof technology strategies. The market witnesses rising demand for agile and customizable platforms.
Heightened Emphasis on Cybersecurity and Data Privacy
Security concerns remain at the forefront of the Wealth Management Software Market as digital transformation accelerates. It prompts firms to invest in advanced cybersecurity measures, including encryption, multi-factor authentication, and continuous threat monitoring. Regulatory pressure around data privacy intensifies the need for secure software platforms. Firms develop dedicated protocols to prevent unauthorized access and mitigate cyber risks. It builds client trust and protects sensitive financial information. The trend drives software providers to integrate security features into every layer of their solutions. Ongoing vigilance in cybersecurity strengthens the market’s foundation and resilience.
Market Challenges Analysis
Complex Regulatory Environment and Compliance Burdens
The Wealth Management Software Market faces significant challenges from evolving regulatory frameworks and stringent compliance requirements. Financial institutions must navigate diverse regulations across jurisdictions, leading to increased operational complexity and rising costs. It demands constant updates to software systems to align with new rules on data privacy, anti-money laundering, and client reporting. Adapting to frequent changes can strain internal resources and delay digital transformation initiatives. Many firms struggle to ensure seamless integration between compliance tools and core wealth management platforms. Maintaining robust audit trails and real-time reporting remains a persistent challenge for the industry.
Integration Issues and Legacy Infrastructure Constraints
Integration with existing legacy systems presents another major obstacle in the Wealth Management Software Market. Financial institutions often rely on outdated IT infrastructure, making it difficult to adopt modern, cloud-based solutions. It can result in data silos, operational inefficiencies, and limited scalability. Migrating to new platforms requires significant investment and careful change management to avoid business disruption. Customizing software to meet unique institutional needs complicates implementation further. Many firms find it difficult to synchronize disparate systems while ensuring data consistency and security throughout the transition process. These integration hurdles slow the pace of technology adoption across the sector.
Market Opportunities
Complex Regulatory Environment and Compliance Burdens
The Wealth Management Software Market faces significant challenges from evolving regulatory frameworks and stringent compliance requirements. Financial institutions must navigate diverse regulations across jurisdictions, leading to increased operational complexity and rising costs. It demands constant updates to software systems to align with new rules on data privacy, anti-money laundering, and client reporting. Adapting to frequent changes can strain internal resources and delay digital transformation initiatives. Many firms struggle to ensure seamless integration between compliance tools and core wealth management platforms. Maintaining robust audit trails and real-time reporting remains a persistent challenge for the industry.
Integration Issues and Legacy Infrastructure Constraints
Integration with existing legacy systems presents another major obstacle in the Wealth Management Software Market. Financial institutions often rely on outdated IT infrastructure, making it difficult to adopt modern, cloud-based solutions. It can result in data silos, operational inefficiencies, and limited scalability. Migrating to new platforms requires significant investment and careful change management to avoid business disruption. Customizing software to meet unique institutional needs complicates implementation further. Many firms find it difficult to synchronize disparate systems while ensuring data consistency and security throughout the transition process. These integration hurdles slow the pace of technology adoption across the sector.
Market Segmentation Analysis:
By Advisory Mode:
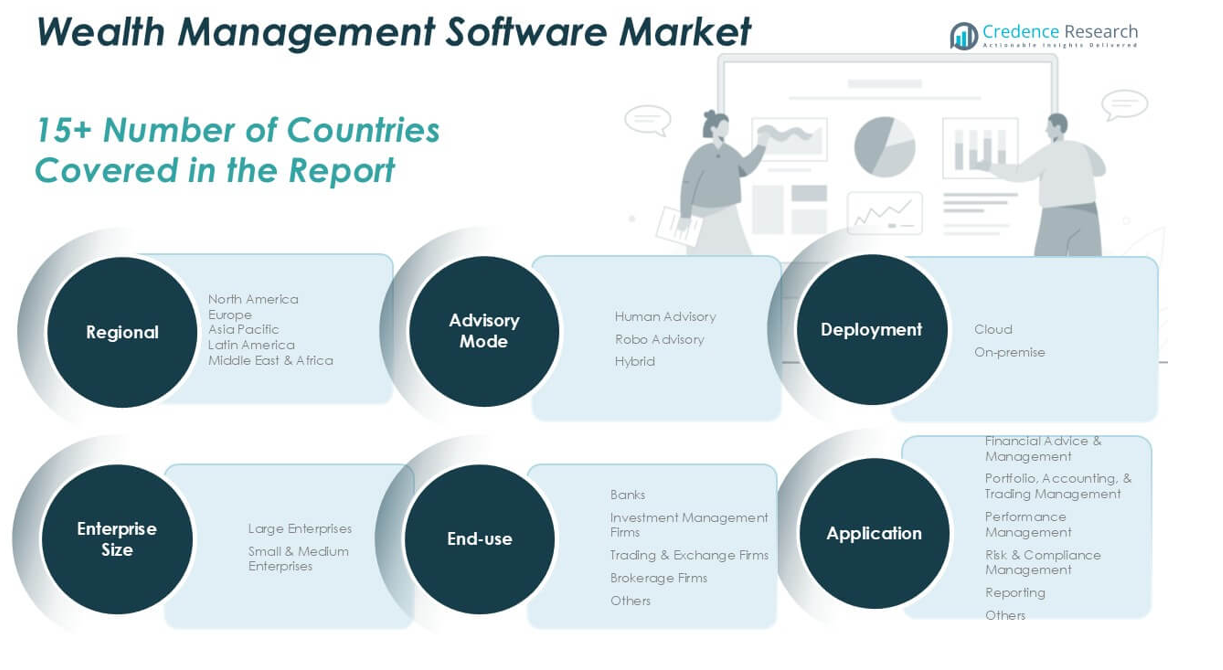
The market is divided into Human Advisory, Robo Advisory, and Hybrid models. Human Advisory remains relevant for clients who value personalized, relationship-driven guidance, particularly for complex financial planning and estate management. It enables wealth managers to offer high-touch, tailored advice to affluent and high-net-worth clients. Robo Advisory has gained substantial traction among tech-savvy investors and cost-conscious segments, leveraging algorithm-based platforms to automate portfolio management and financial planning. This approach provides scalable solutions with lower fees, appealing to younger and mass-market investors. The Hybrid segment blends digital convenience with human expertise, allowing firms to deliver both personalized advice and efficient, automated investment solutions. It meets the needs of clients seeking flexibility and a balanced approach between technology and personal interaction.
- For instance, Betterment, a leading robo-advisor, manages assets for more than 775,000 clients and has over $45 billion in assets under management.
By Deployment:
The market divides into Cloud and On-premise solutions. Cloud deployment leads the segment, favored for its scalability, lower infrastructure costs, and ease of remote access. It allows wealth management firms to update and maintain systems with minimal IT overhead, facilitating quick adaptation to changing client and regulatory requirements. On-premise deployment, while offering greater control over data and security, often requires higher upfront investment and ongoing maintenance. Institutions with strict regulatory or data sovereignty needs continue to prefer on-premise options, but the market trend leans toward cloud adoption due to the agility it offers.
- For instance, Temenos’ cloud platform is used by more than 700 banks worldwide, enabling fast implementation and access to continuous software updates.
By Enterprise Size:
The market segments into Large Enterprises and Small & Medium Enterprises (SMEs). Large Enterprises dominate demand, driven by their complex portfolios, global client bases, and extensive regulatory obligations. It necessitates comprehensive software capable of integrating multiple functions and supporting large-scale advisory operations. SMEs also represent a growing segment, attracted by flexible, affordable solutions that enable them to compete with larger players. Cloud-based offerings help SMEs reduce IT expenses and access advanced tools previously available only to major institutions. The Wealth Management Software Market addresses the unique requirements of each segment, supporting digital transformation and growth across the financial services sector.
Segments:
Based on Advisory Mode:
- Human Advisory
- Robo Advisory
- Hybrid
Based on Deployment:
- Cloud
- On-premise
Based on Enterprise Size:
- Large Enterprises
- Small & Medium Enterprises
Based on Application:
- Financial Advice & Management
- Portfolio, Accounting, & Trading Management
- Performance Management
- Risk & Compliance Management
- Reporting
- Others
Based on End Use:
- Banks
- Investment Management Firms
- Trading & Exchange Firms
- Brokerage Firms
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Wealth Management Software Market
North America Wealth Management Software Market grew from USD 364.76 million in 2018 to USD 554.97 million in 2024 and is projected to reach USD 1,582.96 million by 2032, reflecting a compound annual growth rate (CAGR) of 14.0%. North America is holding a 37% market share. The United States leads regional demand, driven by a mature financial sector and rapid adoption of digital platforms across wealth management firms. Canada also contributes significantly, supported by regulatory modernization and investment in fintech solutions. The region benefits from strong presence of global technology providers and advanced IT infrastructure. Wealth management firms prioritize innovation, with a clear focus on client-centric advisory platforms and enhanced security protocols. Cloud adoption and integration with analytics tools are prominent trends shaping the market’s trajectory.
Europe Wealth Management Software Market
Europe Wealth Management Software Market grew from USD 232.06 million in 2018 to USD 341.88 million in 2024 and is forecasted to reach USD 917.82 million by 2032, with a CAGR of 13.2%. Europe accounts for 21% of the market share. The United Kingdom, Germany, and France anchor regional growth, supported by stringent regulatory standards and strong demand for hybrid advisory models. Financial institutions across the region embrace open architecture platforms and advanced compliance tools to meet evolving client and legal requirements. The push toward sustainable investing and ESG integration creates opportunities for software providers to develop new modules. It reflects an ongoing shift toward digital transformation in wealth management across Europe.
Asia Pacific Wealth Management Software Market
Asia Pacific Wealth Management Software Market grew from USD 292.73 million in 2018 to USD 467.08 million in 2024 and is set to reach USD 1,441.56 million by 2032, at a CAGR of 15.1%. Asia Pacific holds a 33% market share, making it the fastest-growing region. China, Japan, and India are the key contributors, supported by rising numbers of high-net-worth individuals and a growing appetite for digital wealth solutions. It benefits from increasing smartphone penetration and rapid adoption of cloud-based platforms. Regional financial hubs such as Singapore and Hong Kong accelerate market expansion through investments in fintech innovation. Localized platforms and language-specific features drive strong client engagement in this diverse region.
Latin America Wealth Management Software Market
Latin America Wealth Management Software Market grew from USD 50.18 million in 2018 to USD 76.34 million in 2024 and is expected to reach USD 197.47 million by 2032, posting a CAGR of 12.7%. Latin America comprises a 5% market share. Brazil and Mexico lead adoption, leveraging investments in digital transformation to expand wealth management services. Economic growth and financial inclusion initiatives stimulate demand for scalable software platforms. Regional firms seek solutions that facilitate regulatory compliance and enable cross-border advisory services. It supports the development of robust digital ecosystems tailored to Latin American markets. Growth potential remains strong, especially with rising middle-class affluence.
Middle East Wealth Management Software Market
Middle East Wealth Management Software Market grew from USD 27.24 million in 2018 to USD 38.32 million in 2024 and is projected to reach USD 94.49 million by 2032, with a CAGR of 12.0%. The Middle East accounts for a 2% market share. The United Arab Emirates and Saudi Arabia drive market growth, fueled by economic diversification and strategic investments in financial technology. Institutions in the region focus on modernizing legacy IT systems and offering digital-first client services. It addresses demand for Sharia-compliant wealth management and family office solutions. The region’s commitment to innovation and smart city initiatives accelerates software adoption across major financial centers.
Africa Wealth Management Software Market
Africa Wealth Management Software Market grew from USD 13.03 million in 2018 to USD 30.34 million in 2024 and is forecasted to reach USD 83.78 million by 2032, registering a CAGR of 13.3%. Africa holds a 2% market share. South Africa leads regional activity, with Nigeria and Kenya emerging as growth markets driven by rising digitalization and increasing adoption of financial services. The market faces challenges from infrastructural gaps, but it finds opportunities in serving the growing affluent class and promoting financial inclusion. Software providers customize offerings to address local regulatory requirements and multi-currency environments. Strategic partnerships and fintech expansion drive market penetration in the African region.
Key Player Analysis
- Comarch SA
- Dorsum Ltd.
- Fidelity National Information Services, Inc.
- Finantix
- Fiserv, Inc.
- Objectway S.p.A.
- Profile Software
- SEI Investments Company
- SS&C Technologies Holdings, Inc.
- Temenos Headquarters SA
Competitive Analysis
The competitive landscape of the Wealth Management Software Market features strong participation from global technology leaders and specialized fintech firms. Key players include SS&C Technologies Holdings, Inc., Temenos Headquarters SA, Fidelity National Information Services, Inc., Fiserv, Inc., SEI Investments Company, Objectway S.p.A., and Comarch SA. These companies drive market innovation through comprehensive, end-to-end wealth management solutions that address portfolio management, regulatory compliance, risk assessment, and client reporting. Their platforms often integrate advanced technologies such as artificial intelligence, big data analytics, and cloud computing to provide real-time insights and personalized advisory capabilities. Leading firms invest heavily in product development and strategic acquisitions to expand their technological edge and geographic reach. They focus on enhancing user experience with customizable dashboards, mobile interfaces, and open architecture that allows seamless integration with third-party applications. Robust security features and data privacy safeguards remain core differentiators in their product offerings. Many players maintain close partnerships with financial institutions to co-develop tailored solutions for diverse markets. Continuous upgrades and scalable deployment models help them address the evolving needs of both large enterprises and small to medium-sized firms, reinforcing their leadership in a rapidly transforming industry.
Recent Developments
- In February 2025, TIFIN AMP partnered with Ares Wealth Management Solutions (AWMS) to enhance the productivity of AWMS' distribution teams using AI-powered solutions. The collaboration aims to streamline marketing efforts, improve client-advisor interactions, and drive growth. The platform will help deliver personalized, data-driven insights for more effective wealth management distribution.
- In January 2025, Finhaat launched its tech-driven wealth management platform, Finhaat Wealth, aimed at empowering micro-entrepreneurs as Wealth Distributors. The platform offers seamless digital onboarding, training, and 24/7 support to help emerging investors in rural and semi-urban India access wealth solutions.
- In October 2024, Communify Fincentric announced a next-generation suite designed to enhance client and advisor experiences in wealth management. Developed in the age of AI and built on Communify Fincentric’s deep expertise, this flexible platform delivers innovative solutions that offer exceptional access to information, personalization, and automation for advisors.
- In September 2024, KFin Technologies launched mPower Wealth, a comprehensive wealth management platform. It combines front, mid, and back-office functions, accommodates multi-asset and multi-currency portfolios, and utilizes AI for sophisticated analytics. The platform aims to enhance client experiences and meet the needs of wealth managers in a growing market.
- In June 2023, Avaloq (NEC Corporation) partnered with BlackRock to provide integrated technology solutions for meeting the needs of wealth managers.
- In June 2023, Backbase acquired digital wealth platform Nucoro to add end-to-end investing capabilities to its investment banking platform.
- In January 2023, Broadridge Financial Solutions Inc. partnered with IG Wealth Management to optimize advisory team productivity and enrich client experience.
Market Concentration & Characteristics
The Wealth Management Software Market demonstrates moderate to high concentration, with a small group of global technology leaders and established fintech firms accounting for a significant share of total revenue. It is characterized by intense competition, constant innovation, and rapid adoption of advanced digital technologies such as artificial intelligence, big data analytics, and cloud computing. Leading players differentiate their offerings through robust security features, scalable deployment options, and flexible open-architecture platforms that integrate seamlessly with third-party applications. The market supports both large multinational financial institutions and smaller, niche advisory firms, reflecting a diverse client landscape and a wide range of functional requirements. It maintains high barriers to entry due to the complexity of regulatory compliance, the need for continuous product updates, and the capital required for large-scale product development. Partnerships, strategic acquisitions, and client-focused innovations define the evolving characteristics of this dynamic market.
Report Coverage
The research report offers an in-depth analysis based on Advisory Mode, Deployment, Enterprise Size, End Use, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Wealth managers will increase investment in AI-driven advisory tools to improve personalization.
- Cloud-native solutions will expand to support remote and hybrid workforce demands.
- Robo-advisory platforms will become more sophisticated, bridging the gap between automation and human expertise.
- Integration of ESG analytics will become standard to meet rising demand for sustainable investing.
- APIs and open-architecture frameworks will facilitate integration with fintech partners and third-party services.
- Real-time risk monitoring tools will gain prominence to address volatile market conditions.
- Firms will enhance cybersecurity features to protect sensitive client data and comply with new regulations.
- Mobile-first platforms will become essential to meet client expectations for on-the-go access and notifications.
- Wealth software providers will tailor modular solutions for small and mid-sized advisors to drive wider adoption.
- Collaboration between wealth software vendors and traditional banks will increase to develop bundled digital advisory offerings.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation Across Financial Institutions
Financial institutions are rapidly adopting digital solutions to streamline portfolio management, automate advisory processes, and enhance client engagement, driving demand for advanced wealth management software.
Regulatory Compliance and Risk Management
Increasingly complex and evolving regulatory requirements compel wealth managers to invest in software that automates compliance checks, maintains audit trails, and reduces the risk of penalties, fueling market growth.
Personalization and Client-Centric Services
Rising client expectations for tailored investment advice and real-time portfolio access are pushing firms to adopt software with AI, predictive analytics, and customizable dashboards, differentiating their offerings and attracting high-value clients.
Growth of High-Net-Worth Individuals
The expanding population of high-net-worth individuals globally requires scalable, flexible software platforms to manage complex portfolios, multi-asset allocations, and intergenerational wealth transfers, expanding the market opportunity.
Cloud Adoption and Mobile Accessibility
The shift toward cloud-based and mobile-accessible platforms enables wealth managers and clients to access services anytime, anywhere, supporting remote advisory models and driving broader adoption of wealth management software.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Wealth Management Software Market?
What factors are driving the growth of the Wealth Management Software Market?
What are the key segments within the Wealth Management Software Market?
Who are the major players in the Wealth Management Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Deployment
- 1.2.1 Cloud
- 1.2.2 On-premise
- 1.3 By Application
- 1.3.1 Financial Advice & Management
- 1.3.2 Portfolio, Accounting, & Trading Management
- 1.3.3 Performance Management
- 1.3.4 Risk & Compliance Management
- 1.3.5 Reporting
- 1.3.6 Others
- 1.4 By Advisory Mode
- 1.4.1 Human Advisory
- 1.4.2 Robo Advisory
- 1.4.3 Hybrid
- 1.5 By Enterprise Size
- 1.5.1 Large Enterprises
- 1.5.2 Small & Medium Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,508.92 million → 2032: USD 4,318.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wealth Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wealth Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Wealth Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Wealth Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wealth Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wealth Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wealth Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wealth Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,508.92 million → 2032: USD 4,318.07 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wealth Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Deployment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Cloud
- 12.3.6.2 On-premise
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Financial Advice & Management
- 12.4.6.2 Portfolio, Accounting, & Trading Management
- 12.4.6.3 Performance Management
- 12.4.6.4 Risk & Compliance Management
- 12.4.6.5 Reporting
- 12.4.6.6 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Advisory Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Human Advisory
- 12.5.6.2 Robo Advisory
- 12.5.6.3 Hybrid
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Large Enterprises
- 12.6.6.2 Small & Medium Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wealth Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wealth Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wealth Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wealth Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SS&C Technologies Holdings, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Temenos Headquarters SA
- 18.4 Fidelity National Information Services, Inc.
- 18.5 Fiserv, Inc.
- 18.6 SEI Investments Company
- 18.7 Objectway S.p.A.
- 18.8 Comarch SA
- 18.9 Dorsum Ltd.
- 18.10 Finantix
- 18.11 Profile Software
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

