
Market Overview
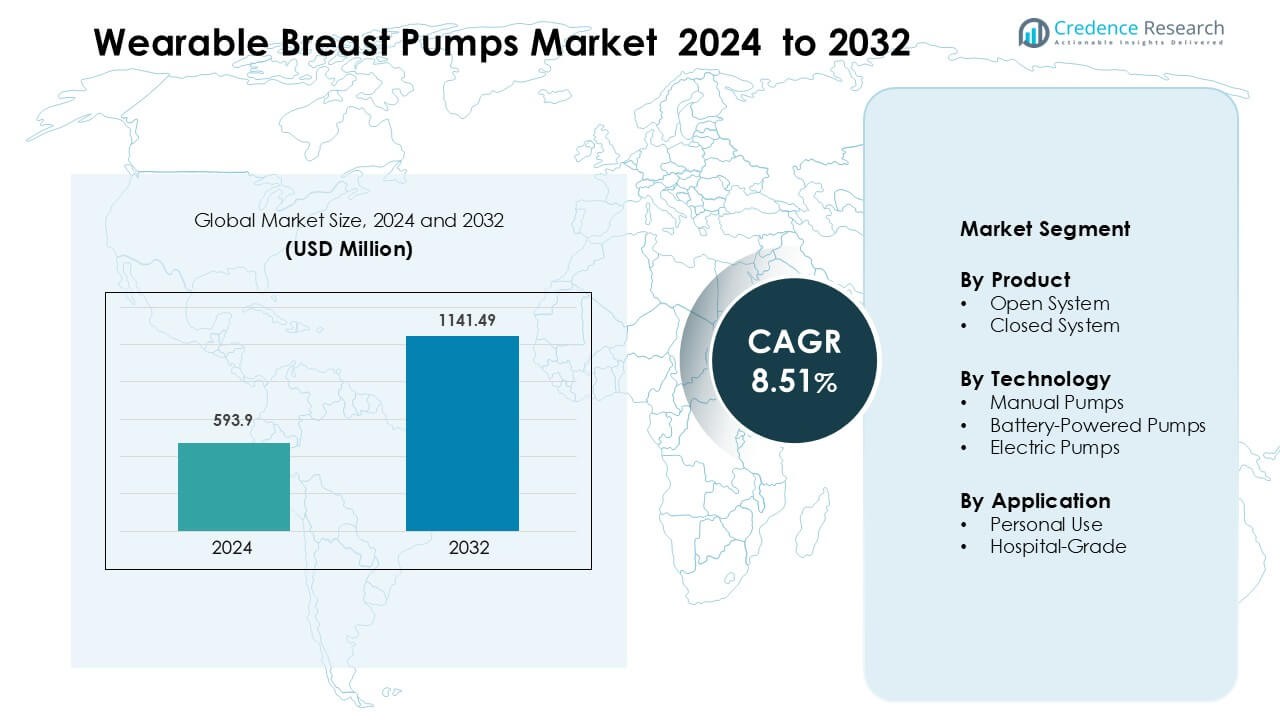
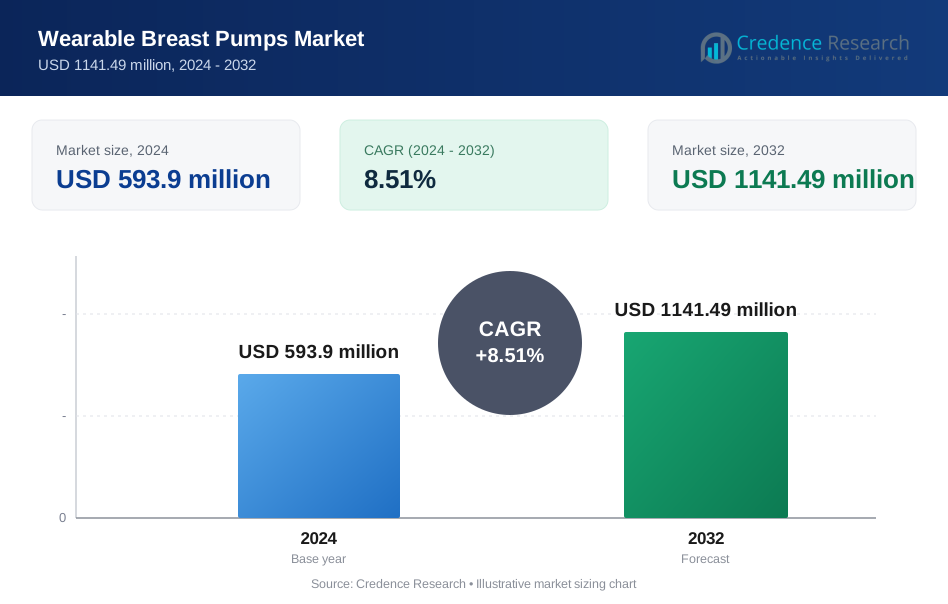
Wearable Breast Pumps Market was valued at USD 593.9 million in 2024 and is anticipated to reach USD 1141.49 million by 2032, growing at a CAGR of 8.51 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wearable Breast Pumps Market Size 2024 | USD 593.9 Million |
| Wearable Breast Pumps Market, CAGR | 8.51 % |
| Wearable Breast Pumps Market Size 2032 | USD 1141.49 Million |
The Wearable Breast Pumps Market is shaped by strong competition among Momcozy, Ameda, Inc., Motif Medical, Chemco Group, Medela, Ardo Medical AG, Luvlap Store, Elvie, Lansinoh Laboratories Inc., and Accelleron Medical Products. These companies focus on quiet operation, mobility, smart tracking, and improved comfort to meet rising demand from working mothers. North America leads the market with about 41% share, supported by high adoption of app-enabled pumps, strong retail availability, and workplace breastfeeding support programs. Continuous product innovation and wide digital distribution strengthen the leadership of major brands and expand global market penetration.
Market Insights
- The Wearable Breast Pumps Market was valued at USD 593.9 million in 2024 and is projected to reach USD 1141.49 million by 2032, growing at a CAGR of 8.51 %.
- Demand rises as working mothers prefer hands-free, portable, and quiet pumps supported by improving breastfeeding awareness and better workplace lactation policies.
- Smart, app-connected features and lightweight battery-powered designs shape major trends, while closed-system pumps lead product share due to higher hygiene and ease of use.
- Competition intensifies as brands enhance comfort, suction control, and pricing strategies, though high device cost remains a key restraint in emerging markets.
- North America holds about 41% share, while battery-powered pumps dominate technology share at around 58%, supported by strong digital retail presence and early adoption of advanced designs.
Market Segmentation Analysis:
By Product
Closed system pumps hold the dominant share at about 72% in 2024 due to their sealed design, which prevents milk contamination and supports safer long-term use. Parents choose closed systems because they reduce cleaning time and lower hygiene risks in daily feeding. Demand rises as working mothers favor compact, reliable pumps that maintain milk purity during frequent sessions. Open system pumps keep a niche presence but face slower growth because many caregivers now prioritize sterile pathways and safer storage.
- For instance, Philips Avent’s Comfort Single Electric Pump weighs just 393 g, has a closed-system design that ensures milk never enters the tubing or motor, and all milk-contact parts (except the motor) are fully sterilizable.
By Technology
Battery-powered pumps lead this segment with nearly 58% share in 2024, driven by strong adoption among working mothers who need portable and hands-free devices. Users select battery models for flexible use in offices, travel, and commutes. Growing demand for discreet wearable designs also supports wider acceptance. Electric pumps hold steady use for higher suction strength, while manual pumps remain common for occasional needs. The shift toward mobility and quiet operation keeps battery-powered pumps ahead.
- For instance, Medela Freestyle Flex features a built‑in rechargeable lithium‑ion battery that delivers up to eight double-pumping sessions per full USB‑C charge.
By Application
Personal-use pumps dominate with around 81% share in 2024, supported by rising breastfeeding awareness and higher adoption of convenient wearable models at home and work. Many parents choose personal-use pumps because they offer privacy, comfort, and continuous availability without hospital constraints. Hospital-grade pumps remain essential in maternity wards and NICUs for mothers needing stronger suction or clinical support. However, personal-use designs grow faster as lightweight, cordless, and silent features meet daily feeding demands.
Key Growth Drivers
Rising Demand for Mobility and Hands-Free Pumping
Mothers seek greater freedom during daily routines, which pushes strong demand for hands-free wearable pumps. Working women value compact devices that fit inside clothing and allow discreet pumping while commuting, attending meetings, or moving around at home. This shift reflects lifestyle changes where rigid pumping schedules are less practical. Many parents now choose cordless pumps that offer comfort, quiet use, and constant mobility without tubes or external units. As more workplaces support breastfeeding policies, the need for portable pumping solutions grows. This demand encourages companies to release lighter, more ergonomic models that align with active routines.
- For instance, Elvie’s wearable breast pump weighs just 225 g, fits entirely into a nursing bra, and operates at 32 dB letting women pump quietly during meetings, commuting, or while moving around.
Growing Breastfeeding Awareness and Health Benefits
Awareness programs highlight the health value of exclusive breastfeeding, which boosts adoption of efficient wearable pumps. Many caregivers need support to maintain milk supply after returning to work or while managing busy schedules, and wearable systems provide a simple way to continue breastfeeding goals. Hospitals and lactation consultants now recommend device-assisted pumping for mothers facing supply issues or latch challenges. This increased guidance encourages early device purchases. As more families learn about immune support and nutritional benefits linked to breast milk, demand for user-friendly pumping devices rises. Market growth accelerates as parents prioritize infant health and convenience.
- For instance, the Lansinoh Wearable Breast Pump offers 8 adjustable suction levels up to 280 mmHg, which lactation experts say helps stimulate milk expression for mothers facing supply challenges.
Advances in Quiet, Smart, and Comfortable Pumping Technologies
Manufacturers invest in improved suction control, noise reduction, and soft silicone shields to enhance comfort and reduce stress during pumping. These upgrades help mothers maintain consistent use without discomfort or disruptions. Smart features such as app-based tracking, customizable suction cycles, and automatic shutoff improve performance and reduce guesswork for new parents. Many users now expect pumps that integrate with digital health tools, monitor milk volume, and store usage data. The shift toward seamless and intuitive technology pushes brands to release advanced models that meet modern expectations and drive repeat purchases.
Key Trends and Opportunities
Rise of Smart Features and App-Connected Devices
Wearable pumps now include Bluetooth connectivity and mobile apps that track milk output, suction levels, and pumping patterns. These features help mothers personalize sessions, monitor supply changes, and manage schedules with greater accuracy. The data supports better lactation planning, especially for working women balancing pumping routines with office hours. Companies use this trend to differentiate products and raise convenience. Continuous improvements in sensors and automation provide more reliable results, making smart pumping a key opportunity for new product launches and premium pricing in the market.
- For instance, Elvie Pump offers seven intensity settings for both Stimulation and Expression modes and, via its app, provides access to different SmartRhythms™ modes to tailor the pumping experience. The app also lets users view real-time volume estimates and track their pumping history on their phone.
Expanding Opportunities in Workplace-Supportive Breastfeeding Policies
More companies now create lactation rooms and flexible pumping breaks, which increases acceptance of wearable pumps. Supportive laws in many regions push employers to maintain breastfeeding-friendly environments. This shift encourages demand for discreet and silent pumping devices that help mothers combine career and infant care. As remote and hybrid work models grow, many mothers invest in portable pumps suited for varied work locations. Brands gain opportunities to partner with employers, insurers, and wellness programs to promote pump adoption and broaden market reach.
- For instance, under the U.S. PUMP Act, employers must provide nursing parents with adequate break time and a private non‑bathroom space to pump for up to one year after childbirth.
Key Challenges
High Device Cost Limits Adoption in Lower-Income Groups
Wearable pumps often cost more than traditional electric or manual pumps, making them less accessible to families with limited budgets. The premium pricing reflects advanced technology, compact design, and battery components, but it also slows adoption in emerging markets. Many caregivers still choose cheaper alternatives despite reduced convenience. Lack of widespread reimbursement programs in many regions further challenges affordability. This cost barrier limits penetration among first-time mothers and reduces replacement purchases, forcing companies to explore cost-effective materials and flexible pricing models.
Inconsistent Suction Performance and Reliability Concerns
Some wearable pumps struggle to match the suction power of hospital-grade models, which raises concerns for mothers who need strong, consistent output. Variability in fit, shield size, and motor strength can reduce milk flow and cause discomfort. These issues create hesitation among new users who depend on predictable results to maintain supply. Reports of battery degradation, leakage, or connectivity problems in earlier models also affect trust. Manufacturers must refine design quality and ensure reliable performance to overcome these barriers and support broader market acceptance.
Regional Analysis
North America
North America holds the leading position with about 41% share in 2024, driven by high adoption of hands-free pumping devices among working mothers and strong insurance support for breastfeeding products. The region benefits from advanced designs, smart app-linked features, and early launches by major brands. Wider workplace lactation programs and rising awareness of breastfeeding benefits also increase usage. Hospitals and lactation consultants recommend wearable pumps for convenience, which boosts repeat purchases. Strong retail channels, including online platforms offering flexible payment options, help maintain the region’s dominant presence.
Europe
Europe accounts for around 27% share in 2024, supported by strong maternal healthcare standards and wide acceptance of breastfeeding-friendly initiatives. Mothers value quiet, comfortable, and compact devices for daily mobility. Countries such as Germany, France, and the U.K. show high adoption due to supportive parental leave policies that encourage sustained breastfeeding. The market grows further as hospitals promote hygienic closed-system pumps and app-enabled designs. Demand also rises through expanding e-commerce platforms and increasing awareness of lactation support programs across major European nations.
Asia Pacific
Asia Pacific captures about 22% share in 2024, with rapid growth driven by rising female workforce participation, urban lifestyles, and expanding retail access to premium pumps. Countries like China, Japan, South Korea, and India show strong interest in lightweight, battery-powered wearable devices suited for long commutes and busy routines. Growing awareness of infant nutrition and government-led breastfeeding campaigns accelerate demand. Expanding middle-income populations choose smart, portable designs for flexible use. Local manufacturers also introduce affordable options, increasing market penetration.
Latin America
Latin America holds nearly 6% share in 2024, supported by gradual improvements in maternal health awareness and expanding online retail channels that offer modern wearable pumps. Brazil, Mexico, and Argentina lead adoption as working mothers look for discreet and comfortable pumping options. Economic constraints limit high-end pump purchases, but mid-range products grow steadily. Breastfeeding education campaigns by public health agencies encourage device use to maintain milk supply. Urban families increasingly choose compact, hands-free designs suited for flexible routines.
Middle East & Africa
The Middle East & Africa region accounts for around 4% share in 2024, with rising traction in urban areas where mothers seek convenient and hygienic wearable pumping solutions. Wealthier Gulf countries lead adoption due to strong healthcare infrastructure and preference for premium products. Breastfeeding initiatives in hospitals and maternity centers support wider acceptance. However, limited affordability and lower awareness in several African nations slow expansion. Gradual improvements in retail access and digital health education are expected to support steady future growth.
Market Segmentations:
By Product
- Open System
- Closed System
By Technology
- Manual Pumps
- Battery-Powered Pumps
- Electric Pumps
By Application
- Personal Use
- Hospital-Grade
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Wearable Breast Pumps Market features strong competition among global and emerging brands that focus on comfort, mobility, and smart functionality. Companies such as Momcozy, Ameda, Inc., Motif Medical, Chemco Group, Medela, Ardo Medical AG, Luvlap Store, Elvie, Lansinoh Laboratories Inc., and Accelleron Medical Products invest heavily in design improvements that offer quieter operation, better suction control, and enhanced fit for daily use. Many players expand product lines with app-connected features that track milk volume and support personalized pumping settings. Direct-to-consumer models strengthen brand visibility through online platforms, while partnerships with hospitals and lactation consultants increase trust and adoption. Firms also differentiate by offering multiple shield sizes, lightweight materials, and long-lasting batteries. Competitive intensity grows as companies release affordable mid-range models to reach wider income groups, pushing continuous innovation in comfort, portability, and smart usability.
Key Player Analysis
- Momcozy
- Ameda, Inc.
- Motif Medical
- Chemco Group
- Medela
- Ardo Medical AG
- Luvlap Store
- Elvie
- Lansinoh Laboratories Inc.
- Accelleron Medical Products
Recent Developments
- In October 2025, Medela launched the Motion In Bra™, a new wearable, in-bra breast pump that combines Medela 2-Phase Expression™ technology with a plug-and-play, discreet design aimed at everyday, hands-free use.
- In June 2025, Ameda launched the GLO Wearable Breast Pump, a hospital-strength, fully hands-free in-bra device now available through Ameda, Amazon, and other retail partners.
- In 2024, LuvLap Store actively marketed and sold its Glory hands-free/wearable electric breast pump across Indian retail channels (official site, Amazon/Flipkart listings and social promotions), showing broad marketplace availability and consumer promotion through social reels and product demo videos.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as more working mothers choose hands-free pumping for daily mobility.
- Smart tracking features will expand, with pumps offering better data insights and automated settings.
- Battery life and motor efficiency will improve, supporting longer and quieter pumping sessions.
- Comfort-focused designs will grow, with softer shields and customizable fit options.
- More companies will enter the mid-range segment, increasing affordability and wider adoption.
- Hospitals will recommend wearable designs more often, boosting trust and clinical acceptance.
- Insurers may broaden coverage for advanced pumps, increasing access for first-time mothers.
- Hybrid work models will support continued uptake of discreet portable pumping solutions.
- Manufacturers will invest in eco-friendly materials and more sustainable production practices.
- Regional growth will accelerate in Asia Pacific as urbanization and female workforce participation increase.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Preference for Mobility and Hands-Free Pumping
Working mothers increasingly seek hands-free, wearable breast pumps that allow discreet and mobile use during daily routines, commutes, and at work. This shift in lifestyle and workplace lactation support policies is driving demand for compact, cordless, and comfortable devices.
Advancements in Smart and App-Connected Features
Manufacturers are integrating Bluetooth connectivity, mobile apps, and smart tracking into wearable pumps, enabling users to monitor milk output, customize suction, and manage schedules. These innovations enhance user experience and differentiate products, supporting premium pricing and repeat purchases.
Rising Breastfeeding Awareness and Health Initiatives
Public health campaigns and hospital recommendations emphasize the benefits of exclusive breastfeeding, encouraging mothers to maintain milk supply after returning to work. Wearable pumps provide a practical solution for continued breastfeeding, boosting adoption rates.
Product Innovation in Comfort and Quiet Operation
Continuous improvements in suction control, noise reduction, and ergonomic design make wearable pumps more comfortable and less disruptive, encouraging consistent use. Enhanced comfort and quieter operation address key user concerns and support broader market acceptance.
Expanding Retail and Digital Distribution Channels
The growth of online retail platforms and flexible payment options increases accessibility to wearable breast pumps, especially in emerging markets. Direct-to-consumer sales and digital marketing expand reach and support rapid market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wearable Breast Pumps Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Wearable Breast Pumps Market projected to grow between 2025 and 2032?
Which Wearable Breast Pumps Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Wearable Breast Pumps Market?
Who are the leading companies in Wearable Breast Pumps Market?
Which region commanded the largest share of Wearable Breast Pumps Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Closed System
- 1.2.2 Open System
- 1.3 By Technology
- 1.3.1 Battery-Powered Pumps
- 1.3.2 Electric Pumps
- 1.3.3 Manual Pumps
- 1.4 By Application
- 1.4.1 Personal Use
- 1.4.2 Hospital-Grade
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 593.9 million → 2032: USD 1141.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wearable Breast Pumps Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wearable Breast Pumps Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wearable Breast Pumps Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wearable Breast Pumps Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wearable Breast Pumps Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wearable Breast Pumps Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wearable Breast Pumps Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wearable Breast Pumps Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 593.9 million → 2032: USD 1141.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wearable Breast Pumps Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Closed System
- 12.3.7.2 Open System
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Battery-Powered Pumps
- 12.4.7.2 Electric Pumps
- 12.4.7.3 Manual Pumps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Personal Use
- 12.5.7.2 Hospital-Grade
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wearable Breast Pumps End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wearable Breast Pumps Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wearable Breast Pumps Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wearable Breast Pumps Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Momcozy
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ameda, Inc.
- 18.4 Motif Medical
- 18.5 Chemco Group
- 18.6 Medela
- 18.7 Ardo Medical AG
- 18.8 Luvlap Store
- 18.9 Elvie
- 18.10 Lansinoh Laboratories Inc.
- 18.11 Accelleron Medical Products
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

