
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Nosocomial Infection Treatment Market Size 2023 | USD 30154.56 Million |
| Nosocomial Infection Treatment Market, CAGR | 1.90% |
| Nosocomial Infection Treatment Market Size 2032 | USD 35720.76 Million |
Market Insights
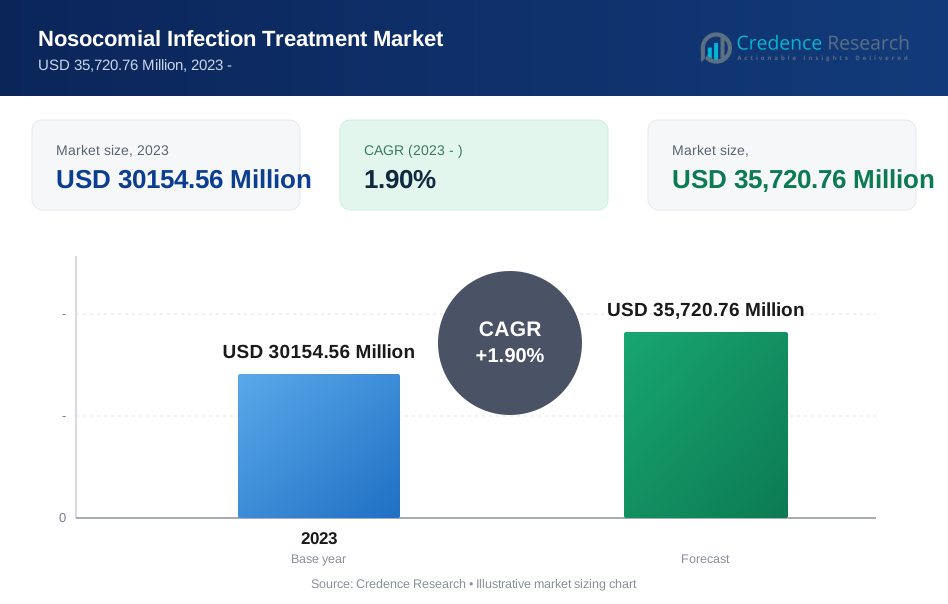
- The global demand for nosocomial infection treatment was valued at USD 30154.56 Million in 2023 and is expected to reach USD 35720.76 Million in 2032, growing at a CAGR of 1.90% between 2024 and 2032.
- Urinary Tract Infections (UTIs) are the market leader by type of infection, accounting for a significant portion of total value in 2023, while the bloodstream infections segment is expected to grow rapidly throughout the forecast period.
- Antibiotics segment dominates the global market by treatment type, accounting for a significant portion in 2023. The antifungal agent segment is predicted to expand at a high CAGR.
- Over the projection period, long-term care facilities are expected to expand at the highest rate, while hospitals dominate the market in 2023 with a substantial share.
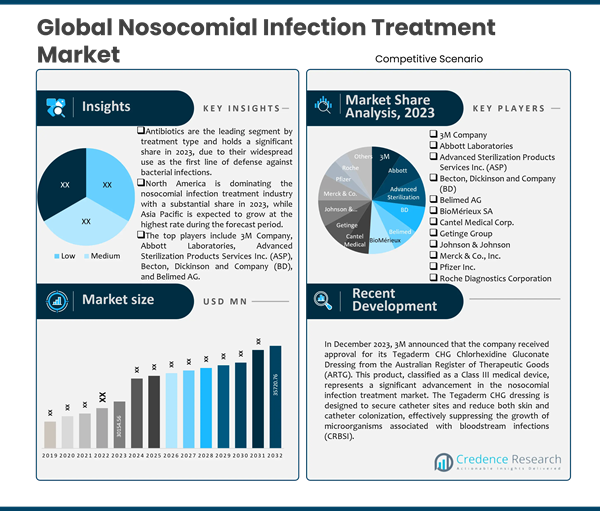
- North America is dominating the Nosocomial Infection Treatment industry with a substantial share in 2023, while Asia Pacific is expected to grow at the highest rate during the forecast period.
- The market's primary possibilities include advancements in medical technology, increased awareness of infection prevention measures, and innovative therapeutic approaches.
Executive Summary
Market Definition
Nosocomial infections, also known as hospital-acquired infections (HAIs), are infections that patients acquire during their stay in healthcare facilities, such as hospitals or nursing homes. These infections can arise from various factors, including surgical procedures, catheter use, and exposure to contaminated equipment or environments.
Treatments for nosocomial infections involve targeted antibiotic or antifungal therapies, chosen based on the specific pathogen responsible for the infection. In addition, supportive care measures such as wound care, intravenous fluids, and oxygen can be adopted. Implementing strict infection control measures, including adherence to hygiene protocols, proper sterilization of medical instruments, and isolating infected patients, is essential in both the prevention and management of these infections.
The goal of nosocomial infection treatment is to reduce the incidence and impact of healthcare-associated infections, thereby improving patient outcomes and ensuring the safety of both patients and healthcare workers.
Market Overview
The global nosocomial infection treatment market has witnessed steady growth in recent years and is expected to grow at a CAGR of 1.90% between 2024 and 2032. The market was valued at USD 30154.56 million in 2023 and is expected to reach USD 35720.76 million in 2032.
The global Nosocomial Infection Treatment market is experiencing robust growth, driven primarily by the rising incidence of hospital-acquired infections. As healthcare systems globally advance, the use of invasive procedures and medical devices such as catheters, surgical implants, and ventilators has become more prevalent. These devices, while indispensable for modern medical care, increase the risk of infections, particularly in settings where maintaining stringent hygiene protocols is challenging.
Moreover, the rising aging population is substantially driving the demand for nosocomial infection treatment. Older adults are more vulnerable to infections due to a natural decline in immune function and the higher likelihood of chronic conditions necessitating frequent and prolonged hospital stays. This demographic shift has led to an increase in elderly patients requiring medical interventions, thereby escalating the occurrence of nosocomial infections.
Additionally, the growing prevalence of chronic diseases such as diabetes, cancer, and respiratory illnesses, which often require continuous medical care, further heightens the risk of hospital-acquired infections. Furthermore, technological advancements in diagnostics and therapeutic interventions are also fueling the market. Innovations in rapid diagnostic tools allow for the swift identification of pathogens, enabling timely and targeted treatment essential for managing nosocomial infections effectively.
In addition, the development of advanced antimicrobial therapies, including novel antibiotics, antifungals, and antiviral medications, is enhancing treatment outcomes. The introduction of infection control products such as antimicrobial-coated medical devices and advanced disinfectants further supports the effective management and prevention of these infections.
The increasing emphasis on stringent infection control protocols and the expansion of healthcare infrastructure in emerging economies contribute to market growth. Governments and healthcare organizations worldwide are prioritizing the implementation of robust infection prevention and control measures. Regulatory initiatives aimed at reducing hospital-acquired infections are leading to higher investments in infection control products and treatment solutions. These factors collectively highlight the urgent need for effective infection control and treatment strategies, driving the ongoing expansion of this market.
Segmentation by Type of Infection
- Urinary Tract Infections (UTIs) are the leading segment by type of infection and hold a substantial share in 2023. This dominance is due to their high incidence rates in hospital settings, particularly among catheterized patients. UTIs are the most common type of hospital-acquired infections, significantly impacting patient morbidity and healthcare costs. Hospitals implement rigorous protocols for prevention and management, but the high prevalence still drives substantial demand for treatment options.
- Bloodstream infections are expected to grow at the highest CAGR during the projected period. This growth is driven by the increasing occurrence of sepsis and central line-associated bloodstream infections (CLABSIs) in intensive care units. Advances in diagnostic technologies and the development of novel antimicrobial therapies are further propelling the growth in this segment. The critical nature of bloodstream infections, requiring immediate and effective treatment, underscores the rapid expansion of this market segment.
- Other segments, such as surgical site infections (SSIS), pneumonia, gastrointestinal infections, and skin & soft tissue infections, also contribute substantially to the market share.
Segmentation by Treatment Type
- The antibiotics segment boasts the dominating position in the nosocomial infection treatment industry, holding a massive share in 2023. This dominance is primarily due to their widespread use as the first line of defense against bacterial infections, which are the most common type of nosocomial infections. Antibiotics are essential for treating a variety of infections, such as urinary tract infections (UTIs), bloodstream infections, and pneumonia, which are prevalent in hospital settings. The broad-spectrum efficacy and critical role of antibiotics in immediate and effective infection management contribute to their significant market share.
- The Antifungal Agents segment is expected to grow at the highest CAGR during the projected period. The rapid growth of this segment can be attributed to the increasing incidence of fungal infections in hospital settings, especially among immunocompromised patients, including those undergoing chemotherapy, organ transplants, or those with HIV/AIDS. Antifungal treatments are becoming more critical as the rise in invasive fungal infections requires effective and specialized treatment options. Additionally, the development of new antifungal drugs and the rising awareness of fungal infections are propelling the growth of this segment.
- Other treatment types, including antiviral drugs, surgical interventions, and supportive care, further contribute significantly to the market's growth.
Segmentation by End-User
- Hospitals boast the dominating position in the nosocomial infection treatment industry, holding a massive share in 2023. This is due to the high incidence of nosocomial infections within hospital settings, where patients are at a higher risk of contracting infections due to prolonged stays, surgeries, and invasive procedures. Hospitals require extensive treatment protocols and a variety of medications and interventions to manage these infections effectively, leading to a larger demand for nosocomial infection treatments in these facilities.
- Long-term care facilities are expected to grow at the highest rate during the forecasted period. The growth in this segment can be attributed to the increasing elderly population, who are more susceptible to infections and often require extended stays in such facilities. Due to the close living quarters and the compromised health status of the residents, long-term care facilities are witnessing a rise in nosocomial infections. This has driven the demand for effective infection control measures and treatments, thereby propelling the growth of this market segment.
- Ambulatory Surgical Centers, Clinics and Outpatient Settings, and Home Healthcare segments contribute significantly to the growth of the market.
Segmentation by Region
- North America dominates the Nosocomial Infection Treatment industry with a massive share in 2023 due to the increase in hospital stays due to chronic diseases and surgeries, coupled with innovative technologies implemented in devices that control infections.
- The Asia Pacific market is expected to grow at the highest rate during the forecasted period.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for the Nosocomial Infection Treatment industry.
North America holds a significant market share in the nosocomial infections treatment market owing to the increase in hospital stays due to chronic diseases and surgeries, coupled with innovative technologies implemented in devices that control infections. In American hospitals alone, the Centers for Disease Control (CDC) estimates that healthcare-associated infections (HAIs) account for approximately 1.7 million infections and 99,000 associated deaths each year. This high incidence highlights the critical need for effective infection control measures and treatments, propelling market growth.
Additionally, the rise in chronic diseases such as cardiovascular diseases and cancer requires extended hospital stays and frequent surgical interventions. According to 2022 data from the American Health Association, there were approximately 33 million hospital admissions in the U.S., highlighting the substantial demand for infection control solutions. The increased number of hospital admissions and longer patient stays elevate the risk of nosocomial infections, further driving the need for advanced treatment options.
Moreover, Innovative technological advancements also play a crucial role in market growth. For example, in February 2021, Penn Medicine opened its new Interventional Support Center (ISC) in Southwest Philadelphia, one of the largest instrument processing and surgical supply preparation facilities in the region. The ISC is among the first facilities of its kind in Pennsylvania, where staff sterilize and package thousands of instruments daily in preparation for surgeries and procedures, from basic scissors and clamps to advanced robotic instruments. The establishment of such state-of-the-art facilities is expected to enhance infection control practices and drive the growth of the nosocomial infection treatment market in North America.
On the other hand, the Asia-Pacific region is poised for significant growth in the nosocomial infections treatment market due to the region's rapidly aging population. With the Asia-Pacific population aging at a faster rate than any other region globally, according to projections from the United Nations Economic and Social Commission for Asia and the Pacific (ESCAP), the prevalence of nosocomial infections is expected to rise significantly. This demographic shift results in a higher susceptibility to infections among the elderly, who often require prolonged hospital stays and have weakened immune systems, necessitating specialized treatment and prevention measures.
Moreover, governments in the Asia Pacific are making substantial investments in healthcare infrastructure to meet the evolving healthcare needs of their populations. For instance, initiatives such as India's establishment of infectious disease (ID) blocks in district hospitals (DHs) and the implementation of the National Action Plan (NAP) to combat antimicrobial resistance (AMR) underscore a concerted effort to enhance healthcare facilities and services. These investments are crucial for improving access to quality healthcare and necessitate advanced infection treatment methods to maintain hygiene standards and mitigate the risk of nosocomial infections.
Additionally, international collaborations and support play a vital role in addressing nosocomial infections in the Asia Pacific region. Partnerships between local healthcare authorities and international organizations, such as the collaboration between the Indian Council of Medical Research (ICMR), All India Institute of Medical Sciences (AIIMS), and the Centers for Disease Control and Prevention (CDC) of the USA, bring in technical expertise and financial support to strengthen infection prevention and control measures. These collaborations are particularly crucial in intensive care units (ICUs) of tertiary care hospitals, where the risk of nosocomial infections is high. The involvement of global health entities such as the World Health Organization (WHO) underscores the importance of addressing nosocomial infections in low- and middle-income countries, highlighting the market growth prospects in the Asia-Pacific region.
Key Highlights of the Report
The global Nosocomial Infection Treatment Market is segmented by type of infection, treatment type, end-user, and region. Antibiotics are the most popular segment, while urinary tract infections (UTIs) are the primary type of infection. In addition, Hospitals are the most demanding end-users, with the North American region leading the market share.
The nosocomial infections treatment market is growing due to the rising incidence of hospital-acquired infections, driven by the increased use of invasive procedures and medical devices. The growing geriatric population is more susceptible to infections due to weakened immune systems and chronic illnesses, leading to the growth of the market. Additionally, heightened awareness and stringent infection control regulations are leading to greater investments in infection prevention. Expanding healthcare infrastructure in emerging economies further boosts the demand for effective nosocomial infection treatments.
Nonetheless, North America is anticipated to have the greatest share of the worldwide nosocomial infection treatment market owing to the increase in hospital stays due to chronic diseases and surgeries, coupled with innovative technologies implemented in devices that control infections. Furthermore, the market is anticipated to expand at the highest rate in the Asia-Pacific region due to the region's rapidly aging population, substantial investments in healthcare infrastructure to meet evolving healthcare needs, and partnerships between local healthcare authorities and international organizations.
What Are the Main Drivers of the Global Nosocomial Infection Treatment Market?
The nosocomial infection treatment market is expanding due to the increasing incidence of hospital-acquired infections fueled by the greater use of invasive procedures and medical devices. The aging population, more prone to infections because of weakened immune systems and chronic diseases, also drives the market growth. Additionally, heightened awareness and stringent infection control regulations are prompting more investments in infection prevention. The expanding healthcare infrastructure in emerging economies further amplifies the demand for effective nosocomial infection treatments.
What Are the Major Challenges Faced by the Global Nosocomial Infection Treatment Market?
The nosocomial infection treatment market is expanding due to the increasing incidence of hospital-acquired infections fueled by the greater use of invasive procedures and medical devices. The aging population, more prone to infections because of weakened immune systems and chronic diseases, also drives the market growth. Additionally, heightened awareness and stringent infection control regulations are prompting more investments in infection prevention. The expanding healthcare infrastructure in emerging economies further amplifies the demand for effective nosocomial infection treatments.
What Are the Growth Opportunities in the Global Nosocomial Infection Treatment Market?
Technological advancements in healthcare are creating substantial opportunities for the growth of the nosocomial infection treatment market. Innovations in diagnostic tools and therapeutic interventions are revolutionizing infection control and treatment, leading to more efficient and effective healthcare solutions. Rapid diagnostic technologies, such as PCR and next-generation sequencing, enable quicker and more accurate pathogen identification. This allows for timely and targeted treatments, reducing infection spread and improving patient outcomes. These advancements are transforming healthcare systems, leading to better patient care and robust healthcare infrastructures in the future.
Market Drivers
Growing incidence of various types of hospital-acquired infections (HAIs).
A significant factor driving the growth of the nosocomial infections treatment market is the rising incidence of various types of hospital-acquired infections (HAIs). According to the Centers for Disease Control and Prevention (CDC), catheter-associated urinary tract infections (CAUTIs) are among the most common types of healthcare-associated infections. Approximately 75% of urinary tract infections (UTIs) developed in hospitals are linked to the use of urinary catheters, with 15-25% of hospitalized patients requiring these devices. CAUTIs contribute to increased morbidity, mortality, healthcare costs, and extended hospital stays, underscoring the need for effective treatment and prevention strategies.
Additionally, a 2022 report from the World Health Organization (WHO) highlights the global burden of HAIs. It reveals that out of every 100 patients in acute-care hospitals, seven patients in high-income countries and 15 patients in low- and middle-income countries acquire at least one healthcare-associated infection during their hospital stay. Alarmingly, on average, one in every ten affected patients will die from their HAI. The impact of HAIs and antimicrobial resistance on patient outcomes is profound, with over 24% of patients affected by healthcare-associated sepsis and 52.3% of those treated in intensive care units succumbing to these infections annually. The mortality rate increases two to threefold when infections are resistant to antimicrobials, emphasizing the urgent need for advanced treatment options and robust infection control measures.
The escalating prevalence of HAIs, such as CAUTIs, and their severe consequences drive the demand for effective nosocomial infection treatments. The increasing recognition of these infections' impact on patient health, hospital resources, and healthcare costs is spurring investments in the development and deployment of innovative diagnostic and therapeutic solutions. Enhanced infection control protocols and regulatory frameworks further support this growth as healthcare systems worldwide strive to mitigate the risks and outcomes associated with HAIs. As a result, the nosocomial infections treatment market continues to expand, addressing a critical need in modern healthcare.
Market Restraints
Impact of Antimicrobial Resistance
The growing problem of antimicrobial resistance (AMR) poses a critical challenge, as pathogens responsible for hospital-acquired infections are increasingly resistant to standard treatments. This resistance makes infections harder to treat, leading to longer hospital stays, higher medical costs, and increased mortality. The diminishing efficacy of existing antibiotics necessitates the development of new, more effective drugs, which is a lengthy and costly process.
Additionally, the financial burden associated with developing and implementing advanced diagnostic tools and therapeutic interventions is substantial. While innovative treatments and technologies are effective, they often come with significant price tags, making them less accessible, especially in low- and middle-income countries. The high costs limit the widespread adoption of new treatments and technologies, thereby restraining market growth.
Opportunities
Advancements in Healthcare Technologies
Technological advancements represent a pivotal factor in creating substantial opportunities for the future growth of the nosocomial infection treatment market. Innovations in diagnostic tools and therapeutic interventions are revolutionizing the landscape of infection control and treatment, paving the way for more efficient, accurate, and effective healthcare solutions. Rapid diagnostic technologies are at the forefront of this transformation.
Traditional diagnostic methods, often time-consuming and less precise, are being replaced by advanced techniques that enable the quicker and more accurate identification of pathogens. These modern diagnostics include molecular methods such as polymerase chain reaction (PCR), next-generation sequencing (NGS), and mass spectrometry, which provide high sensitivity and specificity. The ability to rapidly detect and identify specific pathogens allows healthcare providers to initiate timely and targeted treatments, significantly reducing the spread of infections and improving patient outcomes.
Researchers and pharmaceutical companies are exploring innovative alternatives such as bacteriophage therapy, antimicrobial peptides, and nanotechnology-based solutions. Additionally, nanotechnology is being harnessed to develop advanced drug delivery systems and novel antimicrobial agents. Nanoparticles can be engineered to deliver drugs directly to the site of infection, enhancing drug efficacy and reducing side effects.
Furthermore, nanomaterials with intrinsic antimicrobial properties are being explored for use in coatings, wound dressings, and medical devices to prevent infection. The adoption of these advanced technologies is transforming healthcare systems worldwide. Improved diagnostics and novel treatments enhance the ability to manage and control infections, reducing healthcare-associated costs and improving overall patient care, ultimately leading to better patient outcomes and more robust healthcare systems.
Competitive Landscape
Key Players
The global nosocomial infection treatment market is highly competitive, with several key players. Some of the major players in the market are as follows:
- 3M Company
- Abbott Laboratories
- Advanced Sterilization Products Services Inc. (ASP)
- Becton, Dickinson and Company (BD)
- Belimed AG
- BioMérieux SA
- Cantel Medical Corp.
- Getinge Group
- Johnson & Johnson
- Merck & Co., Inc.
- Pfizer Inc.
- Roche Diagnostics Corporation
- Stryker Corporation
- Thermo Fisher Scientific Inc.
- Steris Corporation
- Zimmer Biomet Holdings, Inc.
- Ansell Limited
- Molnlycke Health Care AB
- Cantel Medical Corp.
These organizations prioritize product launches and business expansion to stay competitive.
The key players in the global nosocomial infection treatment market continually seek to stay ahead by offering new products and developments.
In May 2024, Sanofi announced a significant investment of over €1 billion to enhance its biomanufacturing capabilities in France. This investment aims to bolster the production of essential medicines and vaccines, reinforcing France's health sovereignty. Part of this investment includes the creation of new bioproduction capacity at Sanofi’s sites in Vitry-sur-Seine, Le Trait, and Lyon Gerland. These efforts are crucial for advancing the production of biologics and vaccines, which are essential in the treatment of nosocomial infections and other critical health conditions.
In December 2023, 3M announced that the company received approval for its Tegaderm CHG Chlorhexidine Gluconate Dressing from the Australian Register of Therapeutic Goods (ARTG). This product, classified as a Class III medical device, represents a significant advancement in the nosocomial infection treatment market. The Tegaderm CHG dressing is designed to secure catheter sites and reduce both skin and catheter colonization, effectively suppressing the growth of microorganisms associated with bloodstream infections (CRBSI). The dressing, featuring an antimicrobial synthetic polymer semi-permeable film and its functional design, allows for the securement of various vascular access devices, contributing to improved patient outcomes and reduced infection rates in clinical settings.
How are Companies Performing in the Nosocomial Infection Treatment Market?
The global nosocomial infection treatment market is highly competitive, with several key players.
Startups are playing a pivotal role in revolutionizing the nosocomial infection treatment industry by introducing innovative solutions to combat hospital-acquired infections. These entrepreneurial ventures are leveraging cutting-edge technology, novel approaches, and interdisciplinary collaborations to address the challenges associated with nosocomial infections. Startups are significantly contributing to the industry through the development of advanced infection prevention and control systems.
These systems utilize artificial intelligence (AI) and machine learning algorithms to analyze data and identify patterns that could indicate potential outbreaks or areas of infection risk within healthcare facilities. For instance, Day Zero Diagnostics is revolutionizing the diagnosis and treatment of hospital-acquired infections by utilizing whole-genome sequencing and machine-learning algorithms to identify pathogens and antibiotic resistance patterns rapidly. Their approach allows for more precise and targeted antibiotic therapy, reducing the risk of treatment failure and the spread of multidrug-resistant bacteria.
Additionally, some startups are focusing on improving hand hygiene practices among healthcare workers, which is critical for preventing the transmission of infections in hospitals. For instance, SwipeSense has developed a wearable device that monitors hand hygiene compliance in real time and provides feedback to healthcare workers, encouraging adherence to hand hygiene protocols.
Moreover, startups are innovating in the field of antimicrobial coatings and materials designed to inhibit the growth of pathogens on surfaces commonly found in healthcare settings. Companies such as Parx Materials are developing antimicrobial additives that can be integrated into various materials, such as plastics and textiles, to create self-sanitizing surfaces. These innovative materials have the potential to reduce the transmission of pathogens and prevent the spread of nosocomial infections. With their agility, creativity, and focus on addressing unmet needs, startups are poised to make significant contributions to improving patient outcomes and reducing the burden of nosocomial infections worldwide.
Summary of Key Findings
- The nosocomial infections treatment market is expanding due to the increasing incidence of hospital-acquired infections, fueled by the greater use of invasive procedures and medical devices. The aging population, more prone to infections because of weakened immune systems and chronic diseases, also drives the market growth. Additionally, heightened awareness and stringent infection control regulations are prompting more investments in infection prevention. The expanding healthcare infrastructure in emerging economies further amplifies the demand for effective nosocomial infection treatments.
- Market segmented by type of infection, treatment type, end-user, and region.
- Urinary Tract Infections (UTIs) are the leading segment by type of infection and hold a substantial share due to the high prevalence of catheter use in hospitals, which can introduce bacteria into the urinary tract.
- Antibiotics boast the dominating position in the nosocomial infection treatment industry, holding a massive share in 2023 due to their widespread use as the first line of defense against bacterial infections, which are the most common type of nosocomial infections.
- North America is leading market growth; the market is highly competitive with key players including 3M Company, Abbott Laboratories, Advanced Sterilization Products Services Inc. (ASP), Becton, Dickinson and Company (BD), Belimed AG, BioMérieux SA, Cantel Medical Corp., Getinge Group, Johnson & Johnson, Merck & Co., Inc., Pfizer Inc., Roche Diagnostics Corporation, Stryker Corporation, Thermo Fisher Scientific Inc., Steris Corporation, Zimmer Biomet Holdings, Inc., Ansell Limited, Molnlycke Health Care AB, and Cantel Medical Corp.
Future Outlook
- Positive outlook for the global nosocomial infection treatment market with significant growth potential in the Asia Pacific region.
- One of the main factors promoting the market's expansion is the increasing incidence of hospital-acquired infections, fueled by the greater use of invasive procedures and medical devices. Additionally, heightened awareness and stringent infection control regulations are prompting more investments in infection prevention.
- During the forecast period, the impact of antimicrobial resistance and high treatment costs is expected to act as significant factors restraining the growth of the nosocomial infection treatment market
- To stay competitive, key firms in the nosocomial infection treatment market should prioritize investing in R&D for broad-spectrum and targeted therapies and enhancing their product portfolios with preventative and diagnostic tools.
How CXOs Can Benefit from the Credence Research Nosocomial Infection Treatment Market Report
The Credence Research nosocomial infection treatment market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast:The report provides detailed estimates of the global nosocomial infection treatment market size, segmented by type of infection, treatment type, end-user, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation:The report segments the nosocomial infection treatment market by type of infection, treatment type, end-user, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape:The report profiles the key players in the nosocomial infection treatment market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers:The report identifies and analyses the key trends and drivers shaping the nosocomial infection treatment market. This information can help CXOs make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Nosocomial Infection Treatment Market Report to:
- Identify growth opportunities: The report can help CXOs identify new growth opportunities in the nosocomial infection treatment market. For example, the report identifies the rising demand for effective treatments in emerging economies with growing healthcare infrastructure.
- Make informed investment decisions:The report can help CXOs make informed investment decisions about the nosocomial infection treatment industry. For example, it provides insights into the key factors to consider when evaluating and selecting nosocomial infection treatment providers.
- Develop competitive strategies:The report can help CXOs develop competitive strategies for their Nosocomial Infection Treatment businesses. For example, the report identifies the key strategies that nosocomial infection treatment providers are using to differentiate themselves from their competitors.
- Track market developments:The report can help CXOs monitor market developments and stay ahead of the curve. For example, it provides insights into the latest trends and innovations in the nosocomial infection treatment market.
Overall, the Credence Research Nosocomial Infection Treatment Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
-
By Type of infection
- Urinary Tract Infections (UTIs)
- Surgical Site Infections (SSIs)
- Pneumonia
- Bloodstream Infections
- Gastrointestinal Infections
- Skin and Soft Tissue Infections
-
By Treatment Type
- Antibiotics
- Antifungal Agents
- Antiviral Drugs
- Surgical Interventions
- Supportive Care
-
By End User
- Hospitals
- Long-Term Care Facilities
- Ambulatory Surgical Centers
- Clinics and Outpatient Settings
- Home Healthcare
-
By Region
- North Americas
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North Americas
Adjacent Markets
In the nosocomial infection treatment market, several adjacent markets have high revenue growth opportunities. The key adjacent markets for nosocomial infection treatment market -
Adjacent Markets |
||
| Hospital-acquired infection (HAI) prevention market | Surgical instruments market | Disinfectants market |
| Surgical Site Infection Control Market | Clostridium difficile infection (CDI) treatment market | Healthcare-associated infection (HAI) market |
| Wound care management market | Ventilator-associated pneumonia (VAP) treatment market | Healthcare cleaning services market |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global nosocomial infection treatment market?
What is the expected growth rate of the nosocomial infection treatment market between 2024 and 2032?
Which segment is leading the market share in terms of type of infection?
Which segment is leading the market share in terms of Treatment Type?
Which segment is expected to post the highest CAGR during the forecast period in terms of End Users?
Which region is dominating the nosocomial infection treatment market share?
Who are the major players in the global nosocomial infection treatment market?
What are the major market drivers of the global nosocomial infection treatment market?
What is the major market restraint of the nosocomial infection treatment market?
What are the major market opportunities of the global nosocomial infection treatment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Nosocomial Infection Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Nosocomial Infection Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 30154.56 Million → forecast year: USD 35,720.76 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Nosocomial Infection Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Nosocomial Infection Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Nosocomial Infection Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Nosocomial Infection Treatment Market Drivers
- 3.3 Nosocomial Infection Treatment Market Restraints & Challenges
- 3.4 Nosocomial Infection Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Nosocomial Infection Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Nosocomial Infection Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Nosocomial Infection Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Nosocomial Infection Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Nosocomial Infection Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Nosocomial Infection Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Nosocomial Infection Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Nosocomial Infection Treatment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Nosocomial Infection Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Nosocomial Infection Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Nosocomial Infection Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Nosocomial Infection Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Nosocomial Infection Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Nosocomial Infection Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Nosocomial Infection Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Nosocomial Infection Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Nosocomial Infection Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Nosocomial Infection Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Nosocomial Infection Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
