
Market Overview
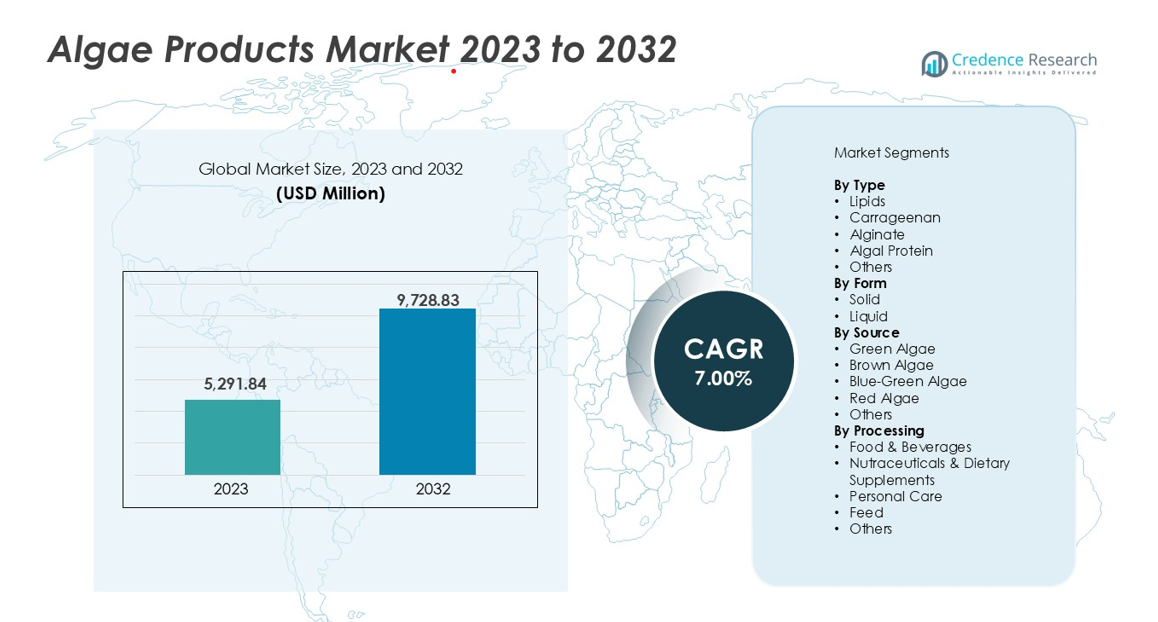
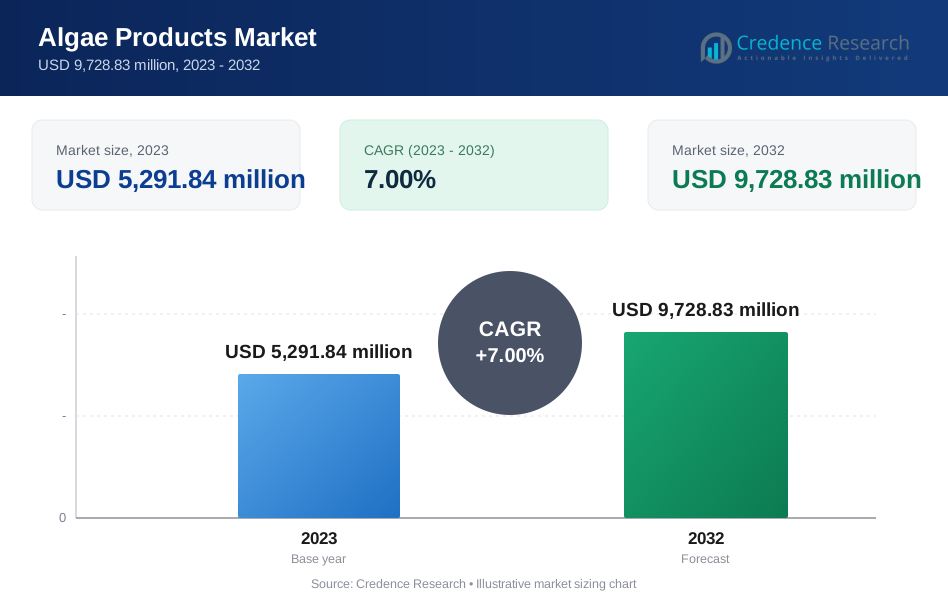
The Algae Products Market size was valued at USD 5,291.84 million in 2024 and is anticipated to reach USD 9,728.83 million by 2032, at a CAGR of 7.00% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Algae Products Market Size 2024 | USD 5,291.84 million |
| Algae Products Market, CAGR | 7.00% |
| Algae Products Market Size 2032 | USD 9,728.83 million |
The algae products market is led by major players such as DSM, BASF, Cargill, Corbion, Euglena Co., Cyanotech Corporation, Kerry, Algae Systems LLC, and BIOPROCESS ALGAE, LLC. These companies focus on expanding algae-based applications across food, nutraceutical, cosmetic, and biofuel sectors through advanced cultivation and extraction technologies. DSM and BASF lead in high-value algae-derived ingredients for nutrition and personal care, while Cargill and Corbion emphasize large-scale sustainable production. Regionally, North America holds the largest market share at 33%, supported by strong R&D investments and consumer demand for plant-based products. Asia-Pacific follows with a 30% share, driven by industrial-scale algae cultivation and expanding applications in food and pharmaceuticals.
Market Insights
- The algae products market was valued at USD 5,291.84 million in 2024 and is projected to reach USD 9,728.83 million by 2032, growing at a CAGR of 7.00%.
- Rising demand for plant-based ingredients, biofuels, and functional food additives is fueling market expansion across global industries.
- Emerging trends include the use of algae in nutraceuticals, cosmetics, and sustainable bioplastics, supported by innovations in cultivation and extraction technologies.
- The market is moderately consolidated, with DSM, BASF, Cargill, Corbion, and Euglena Co. leading through strategic collaborations and product diversification.
- North America dominates with a 33% share, followed by Asia-Pacific at 30% and Europe at 28%; by type, lipids hold the largest segment share at 36%, driven by their application in nutritional and bioenergy sectors.
Market Segmentation Analysis:
By Type
The lipids segment dominated the algae products market in 2024, capturing around 36% of the total share. Lipids derived from microalgae are widely used in nutraceuticals, cosmetics, and biofuel applications due to their high omega-3 fatty acid content. The growing demand for sustainable DHA and EPA sources in dietary supplements and infant nutrition is driving segment growth. Companies are investing in large-scale algae cultivation and extraction technologies to improve lipid yields, reinforcing this segment’s leadership across both food and energy industries.
- For instance, Corbion's AlgaPrime DHA facility in Brazil has been expanding its production of algae-based omega-3 oil for aquafeed. In 2023, sales from the plant exceeded €100 million, and a 2024 expansion project is expected to increase sales to €200 million by 2028.
By Form
The solid form segment held the largest market share of nearly 58% in 2024, driven by its extended shelf life, ease of handling, and suitability for food, pharmaceutical, and cosmetic applications. Dried and powdered algae are widely used as ingredients in protein supplements and animal feed. This format supports convenient packaging and transportation, making it cost-effective for bulk supply. Increasing industrial-scale demand for powdered spirulina and chlorella further strengthens the solid form’s dominance over liquid-based algae extracts.
- For instance, Cyanotech Corporation's Kona facility in Hawaii produces significant quantities of spirulina powder, supplying global nutraceutical and feed markets. In Spain, AlgaEnergy operates a large-scale industrial plant for manufacturing dried microalgae, though its capacity is closer to 100 tons per year.
By Source
Brown algae led the market in 2024, accounting for approximately 40% of total revenue. Its dominance stems from its high content of alginate, fucoidan, and laminarin, which are key components in food additives, pharmaceuticals, and cosmetics. The rising demand for natural hydrocolloids and antioxidants in health products supports steady growth. Leading producers are expanding brown algae harvesting operations in coastal regions of Asia-Pacific and Europe to meet increasing global demand for sustainable, marine-derived bioactive compounds.
Key Growth Drivers
Rising Demand for Natural and Plant-Based Ingredients
The global shift toward sustainable and plant-derived ingredients is a major driver of the algae products market. Consumers increasingly prefer algae-based proteins, lipids, and polysaccharides as alternatives to animal-derived and synthetic ingredients. Algae offer rich nutritional content, including omega-3 fatty acids, antioxidants, and vitamins, making them ideal for food, cosmetics, and nutraceutical applications. Food manufacturers and supplement brands are expanding algae inclusion in their formulations to meet clean-label and vegan demands. Companies like Corbion and DSM are investing in large-scale microalgae fermentation facilities, further boosting supply and market adoption across the food and wellness sectors.
- For instance, Corbion's AlgaPrime DHA plant in Brazil delivers a significantly higher volume of algae-derived omega-3 oil than the "400 metric tons" stated. One source notes that in 2021, the company passed the production milestone of 1 million metric tons of fish feed based on AlgaPrime DHA. In 2024, an update from Corbion's partner, BioMar, indicated that approximately 600,000 metric tons of feed containing the microalgae had been produced and sold.
Expanding Application in Biofuel and Bioplastics Production
Algae’s role as a renewable raw material for biofuels and bioplastics is rapidly strengthening its market potential. Governments worldwide are funding algae-based energy projects to reduce carbon emissions and dependence on fossil fuels. Microalgae can produce lipids for biodiesel and carbohydrates for bioethanol, offering a sustainable energy source. Additionally, algae-derived biopolymers are gaining traction in packaging and industrial materials, addressing global plastic pollution concerns. Collaborations between bioenergy startups and large chemical companies are accelerating technological innovations, improving yield efficiency and scalability. These developments position algae as a vital resource for circular economy solutions.
- For instance, Algenol Biotech’s pilot facility in Florida achieved production rates of over 8,000 gallons of ethanol per acre annually using cyanobacteria-based systems, while Solazyme (now part of Corbion) developed algae oils with a 60% lipid yield for renewable diesel and jet fuel manufacturing.
Technological Advancements in Algae Cultivation and Extraction
Ongoing technological improvements in algae farming, harvesting, and extraction are enhancing production efficiency and cost-effectiveness. Advanced photobioreactors, closed-loop systems, and genetic engineering techniques are improving biomass productivity and nutrient content. Automation and AI-based monitoring systems enable precise control of growth parameters, reducing energy consumption and operational costs. Extraction technologies such as supercritical CO₂ and ultrasound-assisted methods are helping obtain high-purity bioactive compounds. These innovations are supporting wider industrial use in pharmaceuticals, cosmetics, and food processing, making algae production more scalable and commercially viable across multiple industries.
Key Trends & Opportunities
Rising Investment in Nutraceutical and Functional Food Applications
Algae-based products are witnessing growing demand in the nutraceutical and functional food industries due to their dense nutrient profile and health benefits. Chlorella and spirulina are gaining popularity as protein supplements and immunity-boosting ingredients. Major brands are introducing fortified beverages, snacks, and capsules incorporating microalgae extracts. The expanding market for personalized nutrition and preventive healthcare further amplifies growth opportunities. Partnerships between biotech firms and food manufacturers are driving the development of novel formulations, while increasing retail availability through e-commerce channels enhances consumer accessibility and awareness.
- For instance, DIC Corporation's Earthrise facility in California produces 550 metric tons of spirulina powder annually for dietary supplements. As for Roquette, while its Algility range included microalgae ingredients, more recent company information highlights that its chlorella-based flours and powders typically contain 45 grams of protein per 100 grams.
Expansion of Algae Cultivation for Carbon Capture and Sustainability
The increasing focus on carbon-neutral production is opening new opportunities for algae-based carbon capture systems. Algae efficiently absorb CO₂ during photosynthesis, offering an eco-friendly method to mitigate emissions from industrial sources. Several companies are integrating algae cultivation with wastewater treatment and carbon recycling facilities to create sustainable production cycles. Governments and environmental agencies are supporting algae biofixation projects as part of climate change mitigation strategies. These initiatives not only reduce greenhouse gas emissions but also generate valuable by-products like biofertilizers and animal feed, strengthening the market’s sustainability profile.
Key Challenges
High Production and Processing Costs
Despite strong market potential, high production costs remain a major barrier to large-scale algae commercialization. Cultivation requires controlled environmental conditions, advanced photobioreactors, and costly nutrient inputs, which increase capital expenditure. Energy-intensive drying and extraction processes further raise operational costs, limiting competitiveness with conventional plant or synthetic sources. Limited automation and economies of scale restrict affordability for smaller manufacturers. To overcome these challenges, companies are investing in low-cost feedstocks, wastewater-based cultivation, and integrated biorefinery models aimed at maximizing value recovery from every biomass fraction.
Regulatory and Standardization Barriers
The lack of uniform global regulations and product standards for algae-derived materials poses significant challenges. Varying approval timelines for food, pharmaceutical, and cosmetic applications across regions delay product launches and market expansion. Inconsistent labeling requirements and quality certification criteria hinder international trade. Moreover, the absence of standardized testing for purity, safety, and bioactivity affects consumer confidence and investor interest. Industry stakeholders are collaborating with regulatory bodies such as EFSA and FDA to establish clear frameworks for algae products. Streamlined approvals and harmonized standards will be crucial for ensuring long-term market growth.
Regional Analysis
North America
North America dominated the algae products market in 2024, accounting for around 33% of the total share. The region’s growth is driven by strong demand for algae-based nutraceuticals, cosmetics, and biofuels. The U.S. leads due to high consumer awareness regarding plant-based nutrition and active R&D investments in algae cultivation. Companies such as Corbion and Cyanotech are expanding production capacities and developing advanced extraction technologies. Government support for sustainable bioenergy and dietary supplements continues to boost market adoption, strengthening North America’s leadership in the global algae products industry.
Europe
Europe captured nearly 28% of the algae products market in 2024, supported by stringent sustainability regulations and the rising adoption of natural ingredients in food and pharmaceuticals. France, Germany, and the Netherlands are major contributors, driven by innovation in algae-based bioplastics and cosmetics. The European Union’s funding for renewable raw materials and carbon-neutral production enhances regional competitiveness. Growing consumer preference for vegan protein and bioactive compounds derived from algae further supports expansion, positioning Europe as a key hub for environmentally sustainable algae production and value-added applications.
Asia-Pacific
Asia-Pacific held a market share of about 30% in 2024 and is projected to grow rapidly through 2032. China, Japan, South Korea, and India are leading producers and consumers of algae-based food, feed, and industrial materials. Abundant coastal resources and favorable government initiatives toward marine biotechnology support regional supply growth. Expanding demand for spirulina and chlorella in dietary supplements and aquaculture feed drives strong commercial uptake. The increasing focus on sustainable food ingredients and renewable biomass solutions reinforces Asia-Pacific’s emerging dominance in global algae product manufacturing.
Latin America
Latin America accounted for nearly 6% of the algae products market in 2024, supported by the growing use of algae in animal feed and fertilizers. Countries such as Brazil and Chile are leveraging their extensive coastlines to develop commercial-scale algae farms. Local governments are promoting biotechnology projects focused on algae-based energy and food applications. Rising awareness of sustainable agriculture and alternative protein sources contributes to steady market growth. Partnerships between regional producers and global nutraceutical companies are enhancing production capabilities and expanding export potential.
Middle East & Africa
The Middle East & Africa region captured around 3% of the global algae products market in 2024, with gradual growth expected through 2032. Regional development is driven by increasing applications in aquaculture, food supplements, and wastewater treatment. Countries like South Africa and the United Arab Emirates are investing in pilot-scale algae cultivation projects to support biofuel and feed production. Limited freshwater resources are encouraging the use of algae-based biomass in arid zones. Growing awareness of sustainable production and regional investment initiatives are gradually expanding the market footprint.Top of FormBottom of Form
Market Segmentations:
By Type
- Lipids
- Carrageenan
- Alginate
- Algal Protein
- Others
By Form
- Solid
- Liquid
By Source
- Green Algae
- Brown Algae
- Blue-Green Algae
- Red Algae
- Others
By Processing
- Food & Beverages
- Nutraceuticals & Dietary Supplements
- Personal Care
- Feed
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the algae products market is moderately consolidated, with key players focusing on technological innovation, capacity expansion, and strategic collaborations to strengthen market presence. Leading companies such as DSM, BASF, Corbion, and Cargill dominate through extensive product portfolios spanning food ingredients, biofuels, and nutraceuticals. Firms like Euglena Co. and Cyanotech Corporation emphasize product differentiation through high-quality microalgae cultivation and value-added dietary supplements. Algae Systems LLC and BIOPROCESS ALGAE, LLC. are advancing large-scale cultivation technologies for bioenergy and bioplastics. Strategic mergers and joint ventures are expanding global production networks, particularly across Asia-Pacific and North America. Continuous R&D investment in strain improvement, sustainable extraction, and carbon-neutral production remains a core competitive factor shaping the industry’s long-term growth trajectory.
Key Player Analysis
- Algae Systems LLC
- Euglena Co.
- Cyanotech Corporation
- Cargill
- DSM
- Kerry
- Corbion
- BIOPROCESS ALGAE, LLC.
- BASF
Recent Developments
- In October 2024, dsm-firmenich launched Life’sDHA B54-0100, their most potent algal DHA oil to date. This new product delivers 545 mg of DHA and 80 mg of EPA per gram, enabling the development of smaller, more cost-effective capsules with higher DHA concentrations. The company also announced plans to launch two new EPA-rich products in 2025 under the “life’s” portfolio.
- In July 2024, Euglena Co., Ltd. collaborated with ORYZAE Co., Ltd. to launch “ORYZAE GRANOLA Euglena,” a sugar-free granola incorporating Euglena’s nutrient-rich superfood “Ishigaki Island Euglena”. This product combines ORYZAE’s rice koji-based sweetener with Euglena’s microalgae, offering a nutritious and sustainable food option.
- In May 2024, Cyanotech launched Hawaiian Spirulina gummies, expanding their product line to complement their existing Astaxanthin gummy product. This launch was part of their strategy to diversify their microalgae-based dietary supplement offerings.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Source, Processing and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The algae products market is projected to maintain steady growth supported by rising global sustainability goals.
- Increasing use of algae-derived lipids, proteins, and pigments in food and pharma will drive adoption.
- Expanding biofuel production using algae feedstock will strengthen industrial demand worldwide.
- Technological innovations in photobioreactors and strain optimization will enhance production efficiency.
- Strategic alliances among DSM, BASF, and Corbion will shape the competitive landscape.
- Growing consumer preference for vegan and natural ingredients will sustain market momentum.
- High production costs and scalability challenges may limit smaller manufacturers.
- Asia-Pacific will emerge as the fastest-growing region, while North America remains dominant.
- Supportive policies for carbon capture and renewable energy will boost algae cultivation projects.
- Diversification into new applications such as bioplastics and animal nutrition will expand long-term market opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Algae-Based Nutraceuticals and Functional Foods
The increasing incorporation of algae-derived ingredients such as omega-3-rich lipids, proteins, and antioxidants into dietary supplements and functional foods is fueling market growth. Major brands are leveraging the dense nutrient profile of microalgae like spirulina and chlorella to meet consumer demand for clean-label, plant-based, and immunity-boosting products, driving both product innovation and wider adoption.
Technological Advancements in Cultivation and Extraction
Innovations in photobioreactor design, closed-loop cultivation systems, and advanced extraction methods such as supercritical CO₂ are improving the efficiency, yield, and purity of algae products. These advancements are reducing production costs and enabling the scalable manufacture of high-value compounds for food, nutraceutical, and cosmetic applications, thereby expanding the market’s commercial viability.
Rising Demand for Sustainable Biofuels and Bioplastics
Algae’s potential as a renewable feedstock for biofuels and bioplastics is attracting significant investment and government support. The ability of microalgae to produce high lipid yields for biodiesel and biopolymers addresses both energy security and environmental concerns, positioning algae as a key solution for reducing carbon emissions and supporting the circular economy.
Growth in Algae-Derived Ingredients for Personal Care and Cosmetics
The cosmetic industry is increasingly utilizing algae extracts for their bioactive properties, such as antioxidants, moisturizers, and anti-aging compounds. Leading companies are developing new formulations with algae-derived ingredients to cater to consumer preferences for natural and sustainable personal care products, boosting demand in this segment.
Supportive Regulatory and Sustainability Initiatives
Government policies promoting renewable resources, carbon capture, and sustainable agriculture are encouraging investment in algae cultivation and processing. Regulatory support for algae-based food ingredients and bioenergy projects, particularly in North America, Europe, and Asia-Pacific, is accelerating market expansion and adoption across multiple industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the algae products market in 2023 and 2032, and what is the projected CAGR?
What are the primary drivers of growth in the algae products market?
Which regions lead the algae products market, and why?
Why are algae products considered environmentally beneficial?
What are the key applications of algae products?
Who are some major players in the algae products market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Solid
- 1.2.2 Liquid
- 1.3 By Type
- 1.3.1 Lipids
- 1.3.2 Carrageenan
- 1.3.3 Alginate
- 1.3.4 Algal Protein
- 1.3.5 Others
- 1.4 By Source
- 1.4.1 Green Algae
- 1.4.2 Brown Algae
- 1.4.3 Blue-Green Algae
- 1.4.4 Red Algae
- 1.4.5 Others
- 1.5 By Processing
- 1.5.1 Food & Beverages
- 1.5.2 Nutraceuticals & Dietary Supplements
- 1.5.3 Personal Care
- 1.5.4 Feed
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 5,291.84 million → 2032: USD 9,728.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Algae Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Algae Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Algae Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Algae Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Algae Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Algae Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Algae Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Algae Products Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 5,291.84 million → 2032: USD 9,728.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Algae Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solid
- 12.3.7.2 Liquid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lipids
- 12.4.7.2 Carrageenan
- 12.4.7.3 Alginate
- 12.4.7.4 Algal Protein
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Source - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Green Algae
- 12.5.7.2 Brown Algae
- 12.5.7.3 Blue-Green Algae
- 12.5.7.4 Red Algae
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Processing - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food & Beverages
- 12.6.7.2 Nutraceuticals & Dietary Supplements
- 12.6.7.3 Personal Care
- 12.6.7.4 Feed
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Algae Products Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Algae Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Algae Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 DSM
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 BASF
- 17.4 Cargill
- 17.5 Corbion
- 17.6 Euglena Co.
- 17.7 Cyanotech Corporation
- 17.8 Kerry
- 17.9 Algae Systems LLC
- 17.10 BIOPROCESS ALGAE, LLC.
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

