
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Angina Pectoris Drugs Market Size 2024 | USD 12,275.00 million |
| Angina Pectoris Drugs Market, CAGR | 3.7% |
| Angina Pectoris Drugs Market Size 2032 | USD 16,415.4 million |
Market Overview
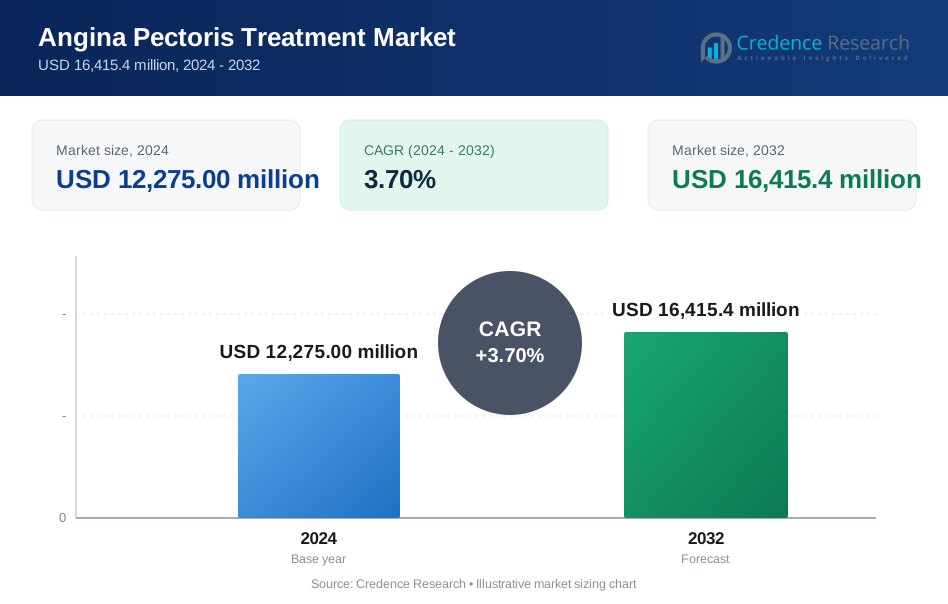
The Angina Pectoris Drugs Market is projected to grow from USD 12,275.00 million in 2024 to USD 16,415.4 million by 2032, registering a compound annual growth rate (CAGR) of 3.7% during the forecast period.
The Angina Pectoris Drugs Market is driven by the increasing global prevalence of cardiovascular diseases, fueled by aging populations, sedentary lifestyles, and rising incidences of obesity, hypertension, and diabetes. Advancements in drug development, particularly in calcium channel blockers, beta-blockers, and long-acting nitrates, are improving treatment efficacy and patient outcomes. Growing awareness of early diagnosis and preventive healthcare is also boosting demand for angina therapies. The expansion of healthcare infrastructure in emerging economies and increasing access to cardiovascular treatments further support market growth. Moreover, the integration of personalized medicine and the development of combination therapies are enhancing treatment approaches, offering tailored solutions to diverse patient populations. Strategic collaborations and R&D investments by pharmaceutical companies are accelerating the pipeline for novel therapeutics targeting chronic stable and unstable angina. Additionally, digital health technologies, such as remote patient monitoring and AI-powered diagnostics, are gaining traction, enabling better disease management and adherence, and contributing to overall market expansion.
The Angina Pectoris Drugs Market exhibits diverse geographical dynamics, with North America leading at 38% market share, followed by Europe at 27%, driven by strong healthcare systems, high disease awareness, and advanced treatment availability. Asia-Pacific holds 22% and is the fastest-growing region due to rising cardiovascular disease prevalence and expanding healthcare access in countries like China, India, and Japan. The Rest of the World, including Latin America, the Middle East, and Africa, accounts for 13% and is gaining momentum through improved healthcare infrastructure and access to generics. Key players shaping the competitive landscape include Pfizer Inc., Merck & Co. Inc., AbbVie Inc., Novartis AG, AstraZeneca, Bayer AG, Teva Pharmaceutical Industries Ltd., Alcon, Bausch Health Companies Inc., Amgen Inc., Astellas Pharma Inc., Aerie Pharmaceuticals Inc., and Amorphex Therapeutics Holdings Inc., all actively involved in expanding portfolios and targeting untapped opportunities across these global regions.
Market Insights
- The Angina Pectoris Drugs Market is projected to grow from USD 12,275.00 million in 2024 to USD 16,415.4 million by 2032, with a CAGR of 3.7%.
- Rising cases of cardiovascular diseases, driven by aging populations, obesity, hypertension, and sedentary lifestyles, are boosting global demand for angina medications.
- Drug innovation, including beta-blockers, long-acting nitrates, and combination therapies, is improving treatment effectiveness and expanding therapeutic options.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East are seeing increased access to angina drugs due to growing infrastructure and healthcare investments.
- Patent expiries and growing generic competition are lowering prices and profit margins for branded drug manufacturers, intensifying market pressure.
- Regulatory complexities and safety requirements delay drug approvals, making it difficult for new players to enter and slowing the pace of innovation.
- North America leads with 38% market share, followed by Europe at 27%, Asia-Pacific at 22%, and the Rest of the World-covering Latin America, the Middle East, and Africa-at 13%.
Market Drivers
Rising Prevalence of Cardiovascular Diseases Globally
The Angina Pectoris Drugs Market is primarily driven by the growing global burden of cardiovascular diseases, including coronary artery disease and hypertension. Sedentary lifestyles, unhealthy diets, and increased stress levels are contributing to the rise in angina cases. It is particularly prevalent among aging populations, which are expanding worldwide. Countries with growing urbanization are reporting higher rates of heart-related illnesses. This trend continues to escalate demand for effective angina treatments. Healthcare systems are responding with expanded screening and prevention programs, which support early diagnosis and treatment initiation.
Growing Awareness and Focus on Preventive Care
Public health campaigns and increased physician advocacy are raising awareness of angina symptoms and the importance of early intervention. The Angina Pectoris Drugs Market benefits from this shift toward preventive healthcare, where patients seek treatment before severe events occur. It helps reduce long-term healthcare costs and enhances patient quality of life. Governments and NGOs are funding initiatives that promote regular heart health screenings. Pharmaceutical companies are also investing in education initiatives. This environment supports higher prescription rates of angina management drugs.
- For instance, SERDIA Pharmaceuticals launched the ‘Angina Awareness INDIA’ campaign, which included in-clinic promotions, video awareness drives, and community contact programs across the country. This initiative reached over 20,000 patients and partnered with leading doctors to educate the public about angina symptoms and early consultation.
Advancements in Drug Development and Therapies
Ongoing innovations in pharmacology and biotechnology are improving the effectiveness and safety profile of angina medications. The Angina Pectoris Drugs Market continues to evolve through the development of novel drug classes and fixed-dose combination therapies. It now includes advanced beta-blockers, long-acting nitrates, and antianginal agents with fewer side effects. These improvements enhance patient adherence and clinical outcomes. Researchers are also identifying new molecular targets to address treatment-resistant angina. Clinical trials are expanding to include diverse populations for broader drug applicability.
- For instnace, Gene therapy approaches are being tested in clinical trials, such as those using viral vectors to deliver vascular endothelial growth factor (VEGF) genes directly to cardiac tissue.
Expansion of Access in Emerging Healthcare Markets
Improved healthcare access and infrastructure in developing economies are contributing significantly to the Angina Pectoris Drugs Market. It is now seeing strong growth in regions such as Asia-Pacific, Latin America, and parts of the Middle East. Governments are prioritizing cardiovascular health through insurance expansion and drug subsidy programs. Local manufacturing and generic drug availability are lowering treatment costs. Hospitals and clinics are equipped with better diagnostic and treatment capabilities. These developments ensure more patients receive timely and effective care.
Market Trends
Increased Adoption of Combination Therapies for Improved Outcomes
Healthcare providers are increasingly favoring combination therapies to manage angina more effectively. These therapies improve treatment adherence by reducing the number of pills a patient must take daily. In the Angina Pectoris Drugs Market, combination treatments are gaining preference due to their ability to target multiple symptoms and mechanisms. It helps optimize cardiovascular function and reduces the frequency of angina episodes. Patients benefit from improved symptom control and lower risk of adverse effects. Pharmaceutical companies are investing in developing fixed-dose combinations that align with clinical guidelines.
- For instance, Pfizer’s Norvasc (amlodipine), a calcium channel blocker, is frequently combined with beta-blockers like atenolol or metoprolol in patients with stable angina who do not achieve sufficient symptom control with monotherapy.
Rising Demand for Personalized and Precision Medicine Approaches
The shift toward personalized medicine is shaping the future of the Angina Pectoris Drugs Market. Physicians are leveraging genetic and biomarker data to tailor treatment plans that suit individual patient profiles. It leads to more accurate dosing, improved therapeutic response, and minimized drug-related complications. Advances in diagnostics and digital health tools support this trend, enabling deeper clinical insights. Drug developers are focusing on agents that work in specific subpopulations. This trend aligns with broader healthcare goals to enhance outcomes through individualized care strategies.
- For instance, FDA-approved for angina pectoris, TOPROM-XL is a cardio-selective beta-blocker prescribed based on patient-specific risk profiles and comorbidities, illustrating how tailored therapy improves safety and efficacy in heart disease management.
Expansion of Digital Health and Remote Monitoring Integration
Digital health innovations are making a significant impact on how angina is managed and monitored. In the Angina Pectoris Drugs Market, remote patient monitoring systems and wearable technologies are enabling continuous cardiovascular tracking. It allows healthcare professionals to adjust therapies in real-time based on patient data. These tools are helping reduce hospital visits and emergency interventions. Integration of AI-driven analytics is supporting earlier detection of complications. This digital shift is reshaping patient engagement and supporting proactive treatment models.
Emergence of Next-Generation Drug Candidates and Delivery Systems
The drug pipeline for angina treatment is evolving, with next-generation therapies under clinical investigation. These candidates aim to improve bioavailability, reduce dosing frequency, and offer better patient convenience. The Angina Pectoris Drugs Market is witnessing interest in novel drug delivery technologies such as transdermal patches and sublingual tablets. It is helping expand treatment options for patients with comorbidities or swallowing difficulties. Research is also targeting drugs with dual action on heart rate and vascular resistance. These innovations may redefine standard care in the coming years.
Market Challenges Analysis
- Patent Expiry and Generic Drug Competition Impact Profit Margins
One of the major challenges in the Angina Pectoris Drugs Market is the patent expiration of widely used medications. It leads to the introduction of generics, which reduces the market share and revenue of branded drug manufacturers. While generics increase accessibility, they also intensify price competition and reduce profit margins for pharmaceutical companies. It creates pressure on innovators to invest heavily in R&D to maintain competitiveness. Delays in launching novel therapies further compound this issue. Companies must balance innovation with affordability to remain viable in the long term.
- For instance, Pfizer’s Lipitor (atorvastatin), once the top-selling drug globally, saw its U.S. sales nosedive by 87% after patent expiry, leading to a 14% decline in Pfizer’s overall profit during the subsequent quarter.
Regulatory Hurdles and Safety Concerns Limit Drug Development
Stringent regulatory requirements for cardiovascular drugs present another barrier for market players. The Angina Pectoris Drugs Market faces prolonged approval timelines and costly clinical trial phases due to the high safety standards for cardiac medications. It slows down the availability of new treatments and increases development costs. Regulatory agencies demand robust efficacy and long-term safety data, especially for drugs targeting chronic conditions. Any adverse effects or safety signals during trials can lead to delays or withdrawal. This environment increases the risk for new entrants and limits innovation pace.
Market Opportunities
Untapped Potential in Emerging Healthcare Markets
Expanding healthcare infrastructure in emerging economies offers a strong growth avenue for the Angina Pectoris Drugs Market. Rising incomes, increased healthcare spending, and growing awareness of cardiovascular diseases are driving demand in regions such as Asia-Pacific, Latin America, and the Middle East. It creates opportunities for both multinational firms and regional players to introduce affordable and accessible treatments. Governments in these regions are implementing national health plans that prioritize cardiovascular care. Local partnerships and generic drug production further facilitate market entry. This trend supports long-term growth and expanded patient reach.
Innovation in Drug Delivery and Digital Therapeutics
The need for improved patient adherence and treatment outcomes is creating space for innovation in drug delivery methods. The Angina Pectoris Drugs Market is witnessing opportunities in developing non-oral delivery systems such as transdermal patches, sublingual sprays, and long-acting injectables. It can enhance convenience for elderly patients or those with swallowing difficulties. Digital therapeutics and telemedicine platforms also offer new avenues to complement pharmacological treatments. These technologies support continuous monitoring, timely intervention, and personalized care. Market players that integrate digital tools with traditional therapies can strengthen their competitive edge.
Market Segmentation Analysis:
By Type
The Angina Pectoris Drugs Market is segmented into Stable Angina, Unstable Angina, and Others. Stable angina holds the largest share due to its chronic nature and high prevalence among elderly and at-risk populations. Unstable angina, though less common, requires immediate and aggressive treatment, driving demand for hospital-administered therapies. It presents a critical area for intervention and pharmaceutical innovation. The “Others” segment includes variant angina and microvascular angina, which are gaining clinical recognition with advancements in diagnostic tools. Each type demands a tailored treatment approach, supporting diversified drug development.
- For instance, Pfizer’s Norvasc (amlodipine), a calcium channel blocker, demonstrated significant reductions in ischemic events and symptom duration for patients with stable angina, mirroring the benefits of Lipitor in the same clinical research.
By Drug Class
Based on drug class, the Angina Pectoris Drugs Market includes Beta Blockers, Anticoagulants, and Others. Beta blockers dominate the market due to their proven efficacy in reducing myocardial oxygen demand and preventing angina episodes. Anticoagulants are essential for patients at risk of clot formation, especially in acute and unstable angina cases. It contributes significantly to the hospital-based treatment segment. The “Others” category includes nitrates, calcium channel blockers, and novel antianginal agents, expanding treatment choices and improving patient outcomes.
- For instance, Lupin Pharmaceuticals launched Ranolazine extended-release tablets in the US for chronic angina, providing an alternative for patients with persistent symptoms despite standard therapies.
By Route of Administration
The market is categorized into Oral, Parenteral, Transdermal, and Others based on route of administration. Oral drugs remain the most widely used due to ease of use and cost-effectiveness in chronic angina management. Parenteral formulations are preferred in acute care settings for faster therapeutic action. It is vital in emergency and inpatient treatments. Transdermal routes offer benefits for long-term, steady drug release and better adherence. The “Others” segment includes sublingual and buccal forms that address specific patient needs.
Segments:
Based on Type:
- Stable Angina
- Unstable Angina
- Others
Based on Drug Class
- Beta Blockers
- Anticoagulants
- Others
Based on Route of Administration
- Oral
- Parenteral
- Transdermal
- Others
Based on End Users
- Hospitals
- Homecare
- Specialty Clinics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the Angina Pectoris Drugs Market, accounting for 38% of the global revenue. The region benefits from a well-established healthcare system, high prevalence of cardiovascular diseases, and strong insurance coverage. It sees high adoption of advanced angina therapies and continuous drug innovation by leading pharmaceutical companies. The United States leads in both market size and research investment. Strong regulatory support and availability of combination therapies enhance treatment outcomes. Increasing awareness and routine cardiovascular screenings contribute to sustained market growth.
Europe
Europe accounts for 27% of the global Angina Pectoris Drugs Market share, driven by a growing elderly population and increased public health spending. Countries like Germany, the United Kingdom, and France play key roles in advancing treatment standards and clinical guidelines. It benefits from a high diagnosis rate and widespread access to generics and branded medications. Healthcare systems across the region actively support preventive care initiatives. Strategic partnerships between healthcare providers and pharma companies are common. The market continues to expand through innovation and regulatory harmonization.
Asia-Pacific
Asia-Pacific represents 22% of the Angina Pectoris Drugs Market and is the fastest-growing region due to rising cardiovascular disease prevalence and improving healthcare infrastructure. China, India, and Japan lead the regional growth through increased healthcare access and investment. It offers strong opportunities for generic drug manufacturers and emerging biotech firms. Governments are expanding public health programs that target heart disease prevention. Urbanization, changing lifestyles, and rising awareness fuel long-term demand. Local players are entering the market to meet regional treatment needs.
Rest of the World
The Rest of the World, including Latin America, the Middle East, and Africa, holds 13% of the Angina Pectoris Drugs Market. It experiences steady growth due to increasing public and private investment in healthcare infrastructure. Access to essential medications is improving in urban centers. It remains a price-sensitive market where generics dominate. Awareness campaigns and regional partnerships are helping close treatment gaps. Governments are prioritizing chronic disease management within broader healthcare reforms.
Key Player Analysis
- Novartis AG (Switzerland)
- Amorphex Therapeutics Holdings, Inc (U.S.)
- Pfizer Inc. (U.S.)
- Bayer AG (Germany)
- Abbvie, Inc (U.S.)
- Alcon (Switzerland)
- Teva Pharmaceutical Industries Ltd. (Israel)
- AERIE PHARMACEUTICALS, INC. (U.S.)
- Amgen Inc. (U.S.)
- AstraZeneca (U.K.)
- Bausch Health Companies, Inc (U.S.)
- Merck & Co. Inc. (U.S.)
- Astellas Pharma Inc. (Japan)
Competitive Analysis
The Angina Pectoris Drugs Market features a competitive landscape with both global pharmaceutical giants and emerging biotech firms actively developing and marketing treatments. Leading companies such as Pfizer Inc., Merck & Co. Inc., AbbVie Inc., and Novartis AG focus on expanding their cardiovascular drug portfolios through strategic R&D investments and partnerships. It is characterized by a mix of branded and generic drug offerings, where price competitiveness and therapeutic efficacy are key differentiators. Companies are pursuing innovation in drug delivery systems and combination therapies to enhance patient compliance and outcomes. Regulatory approvals for new indications and reformulated products strengthen market positions. Collaborations between multinational corporations and regional players help expand market access in developing regions. The market remains dynamic, with continuous efforts to gain first-mover advantage in emerging therapeutic segments and patent-protected solutions. This competitive intensity drives sustained product advancement and broader global reach for leading and mid-tier players alike.
Recent Developments
- In July 2023, Riparian Pharmaceuticals entered into a partnership with Pfizer, granting the latter exclusive rights to a preclinical cardiovascular program. This collaboration aims to support Riparian’s ongoing efforts in identifying new drug targets for vasoprotection.
- In May 2024, Novartis entered into a collaboration with AC Health aimed at enhancing access to cardiovascular treatments, including angina management therapies, in Southeast Asia.
- In 2024, Auxilius Pharma secured Investigational New Drug (IND) approval from the FDA for AUX‑001-a once‑daily extended-release oral formulation of nicorandil-targeted at chronic stable angina. The company anticipates initiating a Phase Ib trial in early 2025.
Market Concentration & Characteristics
The Angina Pectoris Drugs Market is moderately concentrated, with a mix of established pharmaceutical giants and smaller specialized companies contributing to its competitive structure. It is characterized by strong brand loyalty, especially for long-standing therapies like beta-blockers and calcium channel blockers, which maintain a dominant market presence. While large players such as Pfizer, Merck, and Novartis lead in innovation and global reach, generics manufacturers are gaining ground through cost-effective alternatives. The market exhibits high clinical dependency, where therapeutic efficacy, safety, and patient adherence determine product success. Regulatory oversight remains strict, particularly due to the chronic nature of angina and the high-risk cardiovascular patient base. The introduction of novel drug delivery systems and combination therapies reflects an ongoing shift toward enhanced convenience and compliance. It also features regional fragmentation, with pricing, access, and treatment preferences varying significantly across geographies. This dynamic environment encourages continuous investment in R&D, partnerships, and portfolio diversification.
Report Coverage
The research report offers an in-depth analysis based on Type, Drug Class, Route of Administartion, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for angina drugs will continue rising due to the growing global burden of cardiovascular diseases.
- Pharmaceutical companies will focus on developing fixed-dose combination therapies to improve treatment adherence.
- Digital health tools and remote monitoring will become more integrated with angina management.
- Emerging markets will offer strong growth opportunities driven by expanding healthcare access.
- Personalized medicine approaches will gain traction, enabling more targeted and effective treatment plans.
- Innovation in drug delivery systems will enhance convenience and patient compliance.
- Patent expiries will lead to increased competition from generic manufacturers.
- Regulatory bodies will maintain strict safety and efficacy requirements for new drug approvals.
- Strategic collaborations and licensing agreements will support new product development and market expansion.
- Market players will invest in real-world evidence and data analytics to support clinical decision-making.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases Globally
The increasing incidence of cardiovascular diseases, including coronary artery disease and hypertension, is driving demand for angina pectoris treatments. Aging populations, sedentary lifestyles, and urbanization are contributing to a higher patient pool requiring effective angina management.
Advancements in Drug Development and Combination Therapies
Ongoing innovation in pharmacology, such as the development of advanced beta-blockers, long-acting nitrates, and fixed-dose combination therapies, is improving treatment efficacy and patient adherence. These advancements expand therapeutic options and address unmet clinical needs.
Expansion of Healthcare Access in Emerging Markets
Improved healthcare infrastructure and increased government investment in regions like Asia-Pacific, Latin America, and the Middle East are making angina drugs more accessible. Local manufacturing and generic drug availability are reducing costs and expanding patient reach.
Growing Awareness and Preventive Care Initiatives
Public health campaigns and physician advocacy are raising awareness about angina symptoms and the importance of early intervention. This shift toward preventive healthcare is increasing diagnosis rates and driving higher prescription volumes for angina medications.
Integration of Digital Health and Remote Monitoring
The adoption of digital health technologies, such as remote patient monitoring and AI-powered diagnostics, is enhancing disease management and medication adherence. These tools enable proactive treatment adjustments and support better long-term outcomes for angina patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Angina Pectoris Treatment market?
Who are the major players in the global Angina Pectoris Treatment market?
What are the major market drivers of the Angina Pectoris Treatment industry?
What are the major market restraints of the Angina Pectoris Treatment industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Stable Angina
- 1.2.2 Unstable Angina
- 1.2.3 Others
- 1.3 By End Users
- 1.3.1 Hospitals
- 1.3.2 Homecare
- 1.3.3 Specialty Clinics
- 1.3.4 Others
- 1.4 By Drug Class
- 1.4.1 Beta Blockers
- 1.4.2 Anticoagulants
- 1.4.3 Others
- 1.5 By Route of Administration
- 1.5.1 Oral
- 1.5.2 Parenteral
- 1.5.3 Transdermal
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,275.00 million → 2032: USD 16,415.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Angina Pectoris Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Angina Pectoris Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Angina Pectoris Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Angina Pectoris Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Angina Pectoris Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Angina Pectoris Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Angina Pectoris Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Angina Pectoris Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,275.00 million → 2032: USD 16,415.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Angina Pectoris Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stable Angina
- 12.3.7.2 Unstable Angina
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Users - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Homecare
- 12.4.7.3 Specialty Clinics
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Drug Class - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Beta Blockers
- 12.5.7.2 Anticoagulants
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oral
- 12.6.7.2 Parenteral
- 12.6.7.3 Transdermal
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Angina Pectoris Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Angina Pectoris Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Angina Pectoris Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Angina Pectoris Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merck & Co. Inc.
- 18.4 AbbVie Inc.
- 18.5 Novartis AG
- 18.6 AstraZeneca
- 18.7 Bayer AG
- 18.8 Teva Pharmaceutical Industries Ltd.
- 18.9 Amgen Inc.
- 18.10 Astellas Pharma Inc.
- 18.11 Bausch Health Companies Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

