
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
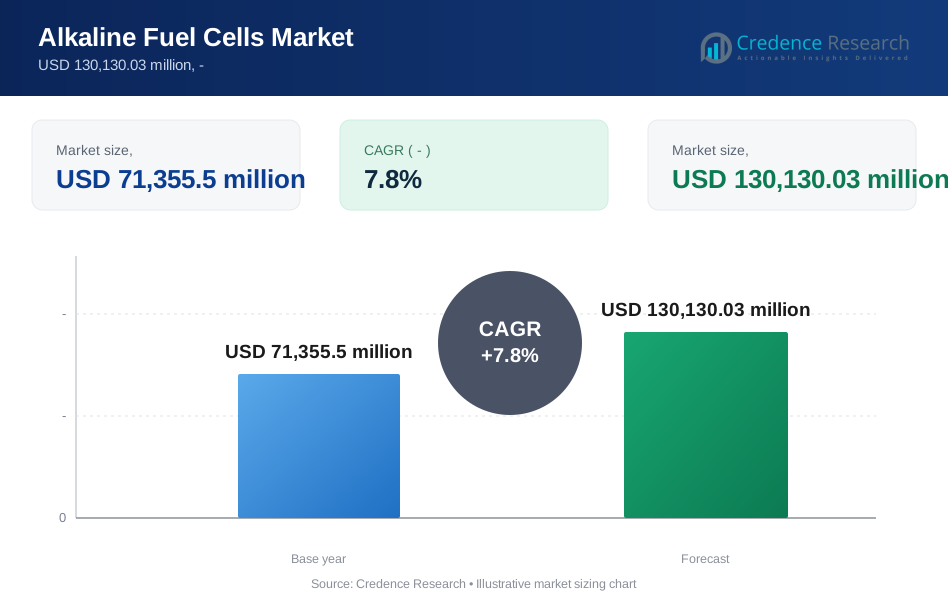
| Alkaline Fuel Cells Market Size 2024 | USD 71,355.5 million |
| Alkaline Fuel Cells Market, CAGR | 7.8% |
| Alkaline Fuel Cells Market Size 2032 | USD 130,130.03 million |
Market Overview:
The Alkaline Fuel Cells Market is poised for robust growth, fueled by the increasing demand for clean and efficient energy solutions. As of 2024, the global Alkaline Fuel Cells Market is valued at approximately USD 71,355.5 million and is projected to grow at a compound annual growth rate (CAGR) of 7.8% over the forecast period, reaching around USD 130,130.03 million by 2032. This growth is driven by the rising need for sustainable energy sources and the implementation of stringent environmental regulations across various industries.
Several key factors are contributing to the market's expansion. The growing emphasis on reducing carbon emissions and reliance on fossil fuels is leading to increased investments in hydrogen-based technologies, including alkaline fuel cells. Additionally, advancements in fuel cell technology are improving efficiency and reducing costs, making these solutions more accessible for commercial and residential applications.
Regionally, North America is currently the largest market for alkaline fuel cells, driven by significant investments in clean energy initiatives and supportive government policies. Europe follows closely, with a strong focus on renewable energy integration and environmental sustainability. The Asia-Pacific region is expected to exhibit substantial growth during the forecast period, fueled by rapid industrialization, increasing energy demands, and growing governmental support for hydrogen fuel technologies. Emerging economies in this region, particularly China and India, present lucrative opportunities for market growth due to their large populations and accelerating investments in clean energy infrastructure.
Market Drivers:
Increasing Demand for Clean Energy Solutions:
The global push towards sustainable energy has significantly influenced the growth of the alkaline fuel cells market. Governments and international organizations are emphasizing the need for cleaner energy alternatives to combat climate change and reduce carbon emissions. For instance, the International Energy Agency (IEA) projects that renewable energy sources will account for around 30% of global energy consumption by 2025, highlighting the escalating demand for cleaner energy solutions. Furthermore, as nations commit to achieving net-zero emissions, they are implementing policies that incentivize the development of clean energy technologies. The United Nations Environment Programme (UNEP) indicates that investments in renewable energy technologies, including fuel cells, are expected to grow by 50% by 2025. This surge in investment creates a favorable environment for alkaline fuel cell adoption across various sectors, including transportation and stationary power generation.
Technological Advancements and Innovation:
Technological advancements play a crucial role in enhancing the performance and efficiency of alkaline fuel cells. Ongoing research and development efforts are leading to significant improvements in fuel cell design, materials, and overall efficiency. For instance, the U.S. Department of Energy (DOE) has identified alkaline fuel cells as a key technology in the transition to a hydrogen economy, investing in projects aimed at improving their efficiency and reducing production costs by 30% by 2030. Research institutions are focusing on developing advanced catalysts and membranes that can enhance the performance of alkaline fuel cells, making them more competitive with other fuel cell technologies. The Global Fuel Cell and Hydrogen Energy Association (GFCH) notes that ongoing innovations could potentially increase the operational life and efficiency of alkaline fuel cells by over 20% by 2030. Such advancements are critical in attracting investments and encouraging adoption in various applications, from portable power systems to large-scale energy storage solutions.
Growing Adoption in the Transportation Sector
The transportation sector is one of the primary markets for alkaline fuel cells, driven by the need for clean and efficient alternatives to traditional fossil fuels. Governments worldwide are promoting the use of fuel cell vehicles (FCVs) as part of their strategies to reduce emissions from the transport sector. For instance, the European Union aims to have at least 2 million hydrogen fuel cell vehicles on the road by 2030, which aligns with its broader Green Deal initiatives aimed at reducing emissions by at least 55% by 2030. As battery technology continues to face challenges related to range and charging times, alkaline fuel cells present a viable alternative for powering vehicles, especially in heavy-duty and long-range applications. According to the IEA, hydrogen-powered vehicles could account for approximately 10% of the global automotive market by 2030. This growing adoption not only drives demand for alkaline fuel cells but also encourages investments in infrastructure, such as hydrogen refueling stations, further enhancing market prospects.
Supportive Government Policies and Incentives:
Government policies and incentives play a pivotal role in fostering the growth of the alkaline fuel cells market. Many countries have implemented supportive measures, such as subsidies, tax incentives, and research grants, to accelerate the development and commercialization of fuel cell technologies. For instance, the U.S. government, through the DOE, has set ambitious goals for hydrogen production and fuel cell deployment, aiming to reduce the cost of fuel cells by 50% by 2030. According to the World Bank, such policies not only drive technological advancements but also create a stable market environment that encourages investment. Additionally, international collaborations and partnerships, facilitated by organizations like the International Renewable Energy Agency (IRENA), are enhancing knowledge sharing and accelerating the adoption of alkaline fuel cells globally. The alkaline fuel cells market is driven by a combination of increasing demand for clean energy solutions, technological advancements, growing adoption in the transportation sector, and supportive government policies. As these drivers continue to influence the market landscape, alkaline fuel cells are poised to play a significant role in the transition towards a more sustainable energy future.
Market Trends:
Increased Focus on Hydrogen Economy:
As the global energy landscape shifts towards hydrogen as a clean fuel source, alkaline fuel cells are poised to play a critical role. Governments and organizations worldwide are recognizing hydrogen's potential in reducing greenhouse gas emissions. For instance, the International Renewable Energy Agency (IRENA) reports that the global hydrogen economy could reach $2.5 trillion by 2050, emphasizing the strategic importance of hydrogen technologies. This shift is reflected in various national strategies, such as Germany’s National Hydrogen Strategy, which allocates €9 billion to develop hydrogen technologies and infrastructure. The U.S. Department of Energy (DOE) has established initiatives aiming to produce 10 million metric tons of clean hydrogen annually by 2030, indicating a broader commitment to advancing the hydrogen economy. As a result, alkaline fuel cells are increasingly being integrated into hydrogen production systems, making them a vital component of this transition.
Growth in Stationary and Portable Applications:
Another significant trend in the alkaline fuel cells market is the growing adoption of these systems in stationary and portable applications. The need for reliable, off-grid power sources has surged, especially in remote areas and during emergencies. For instance, the World Bank highlights that over 700 million people globally lack access to electricity, creating a substantial market for portable energy solutions like alkaline fuel cells. Additionally, alkaline fuel cells are being explored for backup power systems in critical infrastructure, such as hospitals and data centers, due to their reliability and efficiency. The U.S. Department of Energy has emphasized that investments in fuel cell technologies could help provide resilient energy solutions, projecting a 25% increase in the deployment of fuel cell backup systems by 2025. As these trends continue to develop, alkaline fuel cells are expected to gain further traction across various sectors, reinforcing their role as a cornerstone in the transition to a sustainable energy future.
Market Challenge Analysis:
Technological Limitations:
One of the primary challenges facing the Alkaline Fuel Cells Market is the inherent technological limitations associated with fuel cell efficiency and performance. While alkaline fuel cells are known for their potential in providing clean energy, issues such as durability and overall efficiency still need to be addressed. For instance, the membranes used in these fuel cells can degrade over time, leading to reduced performance and lifespan. This degradation not only affects the reliability of the fuel cells but also increases maintenance costs, making them less attractive to potential users. Additionally, the sensitivity of alkaline fuel cells to impurities in hydrogen fuel can lead to decreased operational efficiency, which poses a significant barrier to widespread adoption. Manufacturers and developers are focusing on improving these technological aspects, but ongoing research and development require significant investment and time. As the industry strives for advancements, the current limitations may hinder the market's growth and slow the transition to cleaner energy solutions, necessitating sustained efforts to overcome these challenges.
Market Competition and Economic Factors:
Another major challenge in the Alkaline Fuel Cells Market is the intense competition and economic factors that influence pricing and market entry. The energy sector is highly competitive, with various alternatives available, such as lithium-ion batteries and other fuel cell technologies like proton exchange membrane fuel cells (PEMFCs). These alternatives often offer lower costs and better performance in specific applications, making it difficult for alkaline fuel cells to gain traction. For instance, the automotive industry is increasingly favoring battery electric vehicles (BEVs) over hydrogen fuel cell vehicles due to advancements in battery technology that provide longer ranges and faster refueling times at a lower cost. Additionally, fluctuations in the price of raw materials, such as platinum and nickel, which are used in fuel cell production, can affect the overall cost structure. Economic instability can further exacerbate these challenges, as potential customers may hesitate to invest in new technologies during uncertain times. The combination of strong competition and economic pressures creates a challenging landscape for alkaline fuel cells, requiring companies to innovate continuously and demonstrate clear advantages to attract customers and secure market share. In summary, addressing technological limitations and navigating competitive and economic challenges are crucial for the Alkaline Fuel Cells Market to achieve sustainable growth. Continued investment in research and development, along with effective strategies to differentiate from competing technologies, will be essential for stakeholders in this evolving industry.
Market Segmentation Analysis:
By Type
The Alkaline Fuel Cells Market can be segmented by type into two main categories: portable fuel cells and stationary fuel cells. Portable fuel cells are designed for mobility and are primarily used in applications such as backup power systems, portable electronics, and military applications. Their lightweight and compact design make them ideal for environments where space and weight are critical. In contrast, stationary fuel cells are utilized for power generation in fixed installations, such as residential buildings, commercial properties, and industrial facilities. This segment benefits from the growing demand for reliable and sustainable power sources, particularly in areas seeking to reduce their carbon footprint.
By Technology
In terms of technology, the market is primarily segmented into two main types: traditional alkaline fuel cells and advanced alkaline fuel cells. Traditional alkaline fuel cells utilize potassium hydroxide as an electrolyte and are characterized by their lower cost and simplicity of design. However, they face challenges regarding durability and sensitivity to impurities in hydrogen. Advanced alkaline fuel cells, on the other hand, incorporate innovations in materials and design to improve efficiency, lifespan, and overall performance. These advancements aim to address the limitations of traditional systems and enhance their competitiveness against other fuel cell technologies.
By End-User
By end-user, the market is segmented into several key industries, including transportation, stationary power generation, and portable applications. The transportation segment encompasses vehicles powered by alkaline fuel cells, such as buses and trucks, which are increasingly being adopted to reduce greenhouse gas emissions. Stationary power generation covers applications in residential, commercial, and industrial sectors where fuel cells serve as primary or backup power sources. Lastly, portable applications cater to the needs of consumers and businesses requiring mobile power solutions, such as in remote locations or during emergencies. This diverse segmentation reflects the broad applicability of alkaline fuel cells across various sectors, highlighting their potential to meet the growing demand for clean energy solutions.
Segmentation:
Based on Product Type:
- Portable Fuel Cells
- Stationary Fuel Cells
Based on Technology:
- Traditional Alkaline Fuel Cells
- Advanced Alkaline Fuel Cells
Based on End-User:
- Transportation
- Stationary Power Generation
- Portable Applications
Based on Region:
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of the World
- Brazil
- South Africa
- Middle Eastern countries
Regional Analysis:
North America (40% Market Share)
North America holds the largest share of the Alkaline Fuel Cells Market, accounting for approximately 40% of the global market. This dominance is primarily attributed to substantial investments in clean energy initiatives and supportive government policies aimed at promoting renewable energy sources. The region has seen significant advancements in hydrogen infrastructure, with various states implementing programs to encourage the adoption of hydrogen technologies. Major players in the U.S. and Canada are actively engaged in research and development, focusing on improving fuel cell efficiency and reducing costs. Additionally, the automotive sector in North America is increasingly integrating alkaline fuel cells into their sustainable transportation solutions, which further bolsters market growth. The presence of well-established manufacturers and a strong focus on innovation contribute to a competitive environment, fostering collaborations and partnerships that accelerate technological advancements. Moreover, the growing awareness of climate change and environmental sustainability is pushing both consumers and businesses to seek cleaner energy alternatives, driving demand for alkaline fuel cells. With ongoing investments and a favorable regulatory landscape, North America is well-positioned to maintain its leadership in the alkaline fuel cells market.
Europe (30% Market Share)
Europe accounts for approximately 30% of the global Alkaline Fuel Cells Market, benefiting from a robust commitment to renewable energy and environmental sustainability. The European Union has set ambitious targets for carbon neutrality, prompting countries to invest heavily in hydrogen and fuel cell technologies. Key players in this region are focusing on integrating alkaline fuel cells into various applications, including public transportation and stationary power generation. Germany, France, and the United Kingdom are leading the charge, with significant government support for research and development initiatives aimed at advancing hydrogen technologies. The market in Europe is characterized by a collaborative approach, with various stakeholders, including governments, research institutions, and private companies, working together to foster innovation and accelerate the adoption of fuel cells. The strong regulatory framework and financial incentives for clean energy projects further enhance the attractiveness of the market. As European nations continue to prioritize sustainable energy solutions, the alkaline fuel cells market is expected to witness steady growth, driven by advancements in technology and increased demand for cleaner alternatives.
Asia-Pacific (30% Market Share)
The Asia-Pacific region is emerging as a significant player in the Alkaline Fuel Cells Market, currently holding about 30% of the global market share. Rapid industrialization, urbanization, and increasing energy demands are propelling the region's growth in hydrogen technologies. Countries like China, Japan, and India are investing heavily in alkaline fuel cell research and development, recognizing the potential of hydrogen as a clean energy source. China, in particular, is focusing on expanding its hydrogen infrastructure, with ambitious plans to integrate fuel cells into transportation and other sectors. The government’s support for hydrogen initiatives, coupled with a growing awareness of environmental issues, is driving the adoption of alkaline fuel cells across various applications. Moreover, the increasing need for energy security and diversification of energy sources is prompting countries in the region to explore hydrogen solutions. As awareness of the benefits of clean energy continues to rise, the Asia-Pacific region is poised for substantial growth in the alkaline fuel cells market. With emerging economies leading the charge and an emphasis on sustainability, this region presents lucrative opportunities for industry stakeholders looking to capitalize on the growing demand for clean energy solutions.
Key Player Analysis:
- AFC Energy PLC
- NGK Insulators, Ltd.
- Toyota Motor Corporation
- Ballard Power Systems
- Plug Power
- De Nora
- Astris Energi, Inc.
- Horizon Fuel Cell Technologies
- Nedstack Fuel Cell Technology
- PowerCell Sweden AB
- McPhy Energy
- Proton Power Systems
- ITM Power
- Ceres Power Holdings
- Hydrogenics
- Ovonics Battery Company
Competitive Analysis:
The competitive landscape of the Alkaline Fuel Cells Market is dynamic, featuring a diverse array of players that range from established industry leaders to innovative startups. Major companies are investing significantly in research and development to enhance the efficiency and reduce the costs of alkaline fuel cell technology. This focus on innovation is critical, as advancements in performance and durability are essential for broader market adoption. Key competitors are also forming strategic partnerships and alliances to leverage complementary capabilities, enhance supply chain efficiencies, and expand market reach. Furthermore, companies are increasingly prioritizing sustainability in their operations, aligning their product offerings with global efforts to reduce carbon emissions and promote renewable energy. Emerging players are carving out niche segments by focusing on specific applications, such as portable power solutions and backup energy systems, thereby increasing market fragmentation. The competitive dynamics are further influenced by regulatory frameworks and government incentives that encourage clean energy technologies, prompting companies to adapt swiftly to changing market conditions. As the industry evolves, companies must navigate challenges such as cost competitiveness and technological barriers while capitalizing on opportunities in growing markets, particularly in the Asia-Pacific region. Ultimately, the competitive analysis highlights a robust ecosystem where innovation, strategic collaboration, and sustainability efforts are crucial for gaining market share and driving long-term growth in the alkaline fuel cells sector.
Recent Developments:
- In January 2024, NASA's Moon-Shot initiative launched the commercial fuel cell industry, marking a significant advancement in energy technology. This initiative aims to foster innovation and development within the sector, paving the way for more sustainable energy solutions.
- In 2023, Alkaline Fuel Cell Power Corp. unveiled its prototype, the Jupiter 1.0. This robust fuel cell system is specifically designed for residential and small building applications, highlighting the company's commitment to providing efficient energy alternatives. The announcement also included a management update, reflecting the company's ongoing progress and strategic direction.
Market Concentration & Characteristics:
The Alkaline Fuel Cells Market exhibits moderate concentration, characterized by a mix of established players and emerging companies striving to innovate in this rapidly evolving sector. Key market participants include prominent manufacturers and technology developers who are investing heavily in research and development to enhance fuel cell efficiency and performance. The competitive landscape is marked by strategic partnerships, joint ventures, and collaborations, which aim to leverage complementary strengths in technology and market access. These collaborations are essential for advancing hydrogen infrastructure and developing cost-effective solutions that can meet growing energy demands. Additionally, the market features a diverse range of applications, from transportation to stationary power generation, which attracts a variety of stakeholders, including automotive companies, energy providers, and government agencies. The characteristics of the market also reflect a growing trend towards sustainability, with companies prioritizing environmentally friendly practices and solutions. Regulatory support and incentives from governments worldwide further stimulate competition, pushing firms to innovate and adopt cleaner technologies. As awareness of the environmental impact of traditional energy sources increases, new entrants are encouraged to explore niche markets and specialized applications of alkaline fuel cells. Overall, the market's concentration and characteristics highlight a dynamic environment that fosters innovation while addressing the pressing need for sustainable energy solutions.
Report Coverage:
This report provides a comprehensive analysis of the Alkaline Fuel Cells Market, highlighting its current status, growth prospects, and key trends shaping the industry. It covers the market dynamics influencing demand, including the increasing emphasis on clean energy solutions and the implementation of stringent environmental regulations. The report explores technological advancements that are improving the efficiency and cost-effectiveness of alkaline fuel cells, making them more accessible for various applications across commercial and residential sectors. Additionally, the regional analysis delves into market performance across North America, Europe, and the Asia-Pacific region, identifying North America as the largest market due to robust investments in clean energy initiatives and favorable government policies. The report also examines emerging economies, particularly in Asia, where rapid industrialization and growing energy demands present significant opportunities for growth. Key players in the market are discussed, along with their strategies for innovation and collaboration to drive advancements in hydrogen-based technologies. The report concludes with insights into future trends and challenges, providing stakeholders with a thorough understanding of the landscape and actionable recommendations to navigate the evolving market. This analysis serves as a valuable resource for industry professionals, investors, and policymakers seeking to understand the potential and direction of the alkaline fuel cells market in the coming years.
Future Outlook:
- The Alkaline Fuel Cells Market will continue to grow as industries prioritize clean energy solutions.
- Technological advancements will enhance the efficiency and affordability of alkaline fuel cells, broadening their applications.
- Increased investments in hydrogen infrastructure will facilitate the adoption of alkaline fuel cells across various sectors.
- Governments will implement more supportive policies and incentives to promote clean energy initiatives.
- The focus on reducing carbon emissions will drive companies to seek alternative energy sources, boosting demand for fuel cells.
- Collaboration between public and private sectors will accelerate research and development efforts in fuel cell technology.
- Emerging economies will present significant growth opportunities due to rising energy needs and investments in clean technologies.
- The automotive industry will increasingly integrate alkaline fuel cells into their sustainable transport solutions.
- Increased awareness of environmental sustainability will encourage consumers to adopt cleaner energy alternatives.
- The development of advanced materials will improve the durability and performance of alkaline fuel cells, enhancing their market viability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Clean Energy Solutions
Global efforts to reduce carbon emissions and reliance on fossil fuels are driving investments in hydrogen-based technologies, including alkaline fuel cells, across sectors such as transportation and stationary power generation.
Technological Advancements and Innovation
Ongoing R&D is improving the efficiency, durability, and cost-effectiveness of alkaline fuel cells, making them more competitive and expanding their use in commercial, residential, and portable applications.
Growing Adoption in the Transportation Sector
Governments and industries are promoting fuel cell vehicles as part of emission reduction strategies, with alkaline fuel cells offering viable alternatives for heavy-duty and long-range transport, thus boosting market demand.
Supportive Government Policies and Incentives
Subsidies, tax incentives, and research grants from governments worldwide are accelerating the development and commercialization of alkaline fuel cell technologies, creating a favorable environment for market growth.
Expansion of Hydrogen Infrastructure
Significant investments in hydrogen production and refueling infrastructure, especially in North America, Europe, and Asia-Pacific, are facilitating the broader adoption of alkaline fuel cells in both stationary and mobile applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Alkaline Fuel Cells Market?
What is the projected growth rate for the Alkaline Fuel Cells Market?
What are the main drivers of growth in the Alkaline Fuel Cells Market?
Which regions are leading in the Alkaline Fuel Cells Market?
How is technology impacting the Alkaline Fuel Cells Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Transportation
- 1.2.2 Stationary Power Generation
- 1.2.3 Portable Applications
- 1.3 By Technology
- 1.3.1 Traditional Alkaline Fuel Cells
- 1.3.2 Advanced Alkaline Fuel Cells
- 1.4 By Product Type
- 1.4.1 Portable Fuel Cells
- 1.4.2 Stationary Fuel Cells
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 71,355.5 million → Forecast year: USD 130,130.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Alkaline Fuel Cells Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Alkaline Fuel Cells Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Alkaline Fuel Cells Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Alkaline Fuel Cells Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Alkaline Fuel Cells Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Alkaline Fuel Cells Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Alkaline Fuel Cells Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Alkaline Fuel Cells Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 71,355.5 million → Forecast year: USD 130,130.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Alkaline Fuel Cells Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Transportation
- 12.3.7.2 Stationary Power Generation
- 12.3.7.3 Portable Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Traditional Alkaline Fuel Cells
- 12.4.7.2 Advanced Alkaline Fuel Cells
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Portable Fuel Cells
- 12.5.7.2 Stationary Fuel Cells
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Alkaline Fuel Cells End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Alkaline Fuel Cells Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Alkaline Fuel Cells Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Alkaline Fuel Cells Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AFC Energy PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NGK Insulators, Ltd.
- 18.4 Toyota Motor Corporation
- 18.5 Ballard Power Systems
- 18.6 Plug Power
- 18.7 De Nora
- 18.8 Horizon Fuel Cell Technologies
- 18.9 Nedstack Fuel Cell Technology
- 18.10 PowerCell Sweden AB
- 18.11 Ceres Power Holdings
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

