
Alternative Fuel Engine Market Overview:
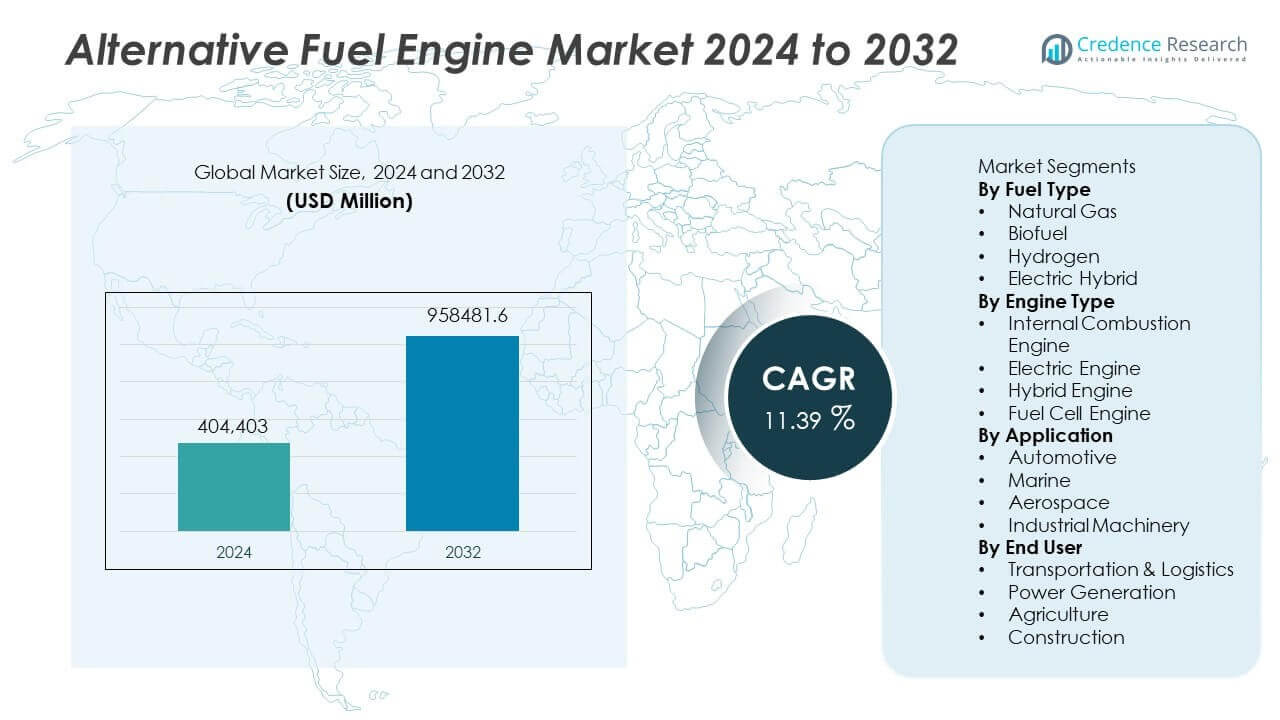
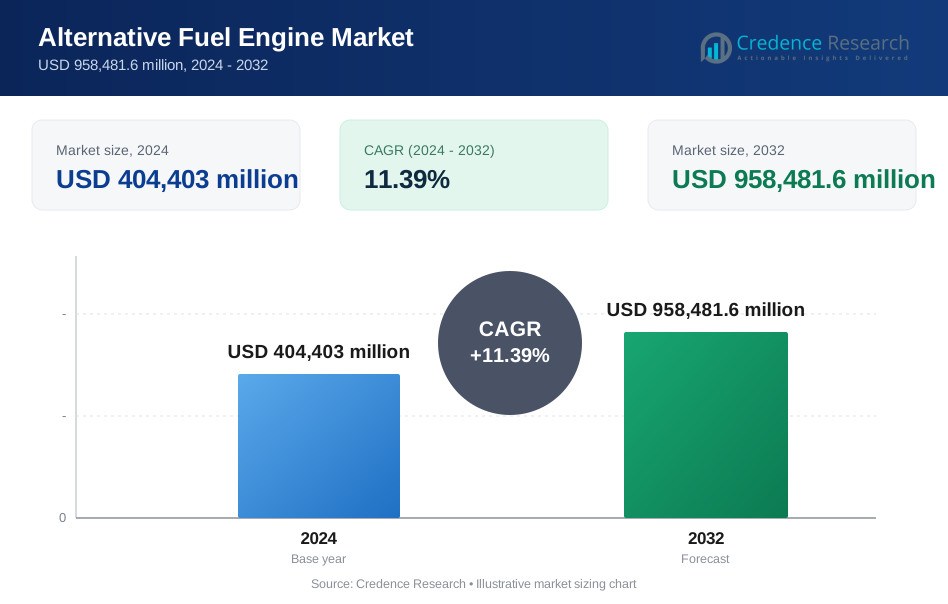
Alternative Fuel Engine market size stood at USD 404,403 million in 2024, and the value is projected to reach USD 958,481.6 million by 2032, reflecting a CAGR of 11.39% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Alternative Fuel Engine Market Size 2024 | USD 404,403 million |
| Alternative Fuel Engine Market, CAGR | 11.39% |
| Alternative Fuel Engine Market Size 2032 | USD 958,481.6 million |
Alternative Fuel Engine Market Insights
- Rising emission rules and clean fuel goals drive strong market uptake, led by natural gas engines with 42% share. Automotive applications dominate with 61% share in 2024 as fleets shift to gas, hybrid, and electric power.
- Key trends include growth in hydrogen and fuel cell systems, digital powertrain tools, and hybrid range gains. Global players invest in R&D to raise output, efficiency, and uptime.
- Market restraints include high upfront cost and limited fuel and charging access, slowing scale for small fleets and heavy-duty roles.
- North America leads with 34% share in 2024, followed by Europe with 31% and Asia Pacific with 27%. Strong policy support and fleet trials in these regions shape long-term growth and technology spread.
Market Segmentation Analysis:
By Fuel Type
Natural gas leads this segment with 42% share in 2024. Strong focus on clean transport drives adoption across trucks and buses. The fuel offers lower emissions than diesel and cuts running cost. Biofuel ranks next due to rising blending rules in major regions. Hydrogen grows as nations invest in fuel cell systems for long-haul fleets. Electric hybrid fuel types gain pace through better batteries and charging reach. OEMs invest in compatible engines and expand fleets with clean models. Supportive tax credits and green fleet goals help natural gas remain dominant in the forecast period.
- For instance, Toyota fuel cell trucks logged 480 km range per fill at the Port of Los Angeles trial. Electric hybrid fuel types gain pace through better batteries and charging reach.
By Engine Type
Internal combustion engines hold 55% share in 2024 due to wide supply and lower price. These engines use natural gas and biofuel to cut emissions across transport fleets. Hybrid engines grow fast as automakers pair motors with improved batteries. Electric engines expand in light duty fleets and city travel. Fuel cell engines gain use in heavy duty roles for long range. OEMs upgrade power output and service reach for each type. Supportive policy and fleet renewal plans drive hybrid demand, yet internal combustion engines stay in lead due to base volume and retrofit options.
- For instance, MAN natural gas engines reached 228 kW output with Euro 6 compliance in logistics fleets.
By Application
Automotive holds 61% share in 2024, driven by strong fleet change in road transport. Trucks, buses, and passenger cars shift toward clean engines backed by rules and cost targets. Marine use grows with LNG engines for cargo ships. Aerospace sees early use of hydrogen and hybrid test units. Industrial machinery adopts biofuel and gas engines to cut fuel spend and emissions. Carmakers expand model lines and engine supply across regions to meet fleet goals. Strong freight demand and urban rules keep the automotive segment in lead through the forecast period.
Key Growth Drivers
Rising Emission Regulations and Decarbonization Goals
Governments push lower carbon output through strict emission rules and fleet targets. These measures guide engine makers toward cleaner fuels, hybrid units, and electric power. Road transport, marine, and industrial fleets upgrade engines to meet air quality norms. Public agencies support these shifts through tax credits and grants. Large firms invest in LNG, biofuel, and hydrogen engines to meet net-zero plans. This driver boosts long-term demand as cleaner engines replace older units and help users cut lifetime running cost and emissions.
- For instance, Cummins certified an engine platform that achieved 0.02 g NOx per brake horsepower-hour under CARB HD standards.
Shift Toward Cost-Effective and Clean Fuel Choices
Users adopt gas and biofuel engines to lower fuel spend and reduce carbon output. Gas engines cut fuel cost per mile and offer stable supply. Biofuel blends help owners decarbonize without major fleet change. Hybrid and electric power reduce idling loss and improve energy use. Growing fuel access, fast fill stations, and local supply support scale. This driver supports steady growth across trucking, buses, and industrial use as buyers aim for total cost gains.
- For instance, Scania engines ran B100 biofuel at 360 kW rated power in logistics fleets. Hybrid and electric power reduce idling loss and improve energy use.
Advances in Engine Efficiency and Power Density
Engine makers improve thermal efficiency, torque control, and heat loss. New parts, sensors, and software raise power density and extend run time. Hybrid and fuel cell platforms expand range and load capacity. These gains help clean engines match or exceed diesel roles in heavy duty use. Lower service needs and higher uptime attract fleet owners. Strong R&D and OEM partnerships support faster launch cycles and wider product lines. This driver builds user trust and speeds adoption.
Key Trends and Opportunities
Scale-Up of Hydrogen and Fuel Cell Systems
Hydrogen moves into heavy trucks, rail, and marine roles. Users seek long range and fast fill, which support fuel cell use. Growth in green hydrogen plants and storage hubs improves supply. Engine and stack makers form deals to cut cost and improve load output. Public and private fleets test early units under real duty cycles. This trend opens strong revenue paths as hydrogen engines move from pilot to scale.
- For instance, Hyundai XCIENT fuel cell trucks logged 120 kW stack power and 400 km range in fleet runs.
Growth of Connected and Smart Powertrains
Digital control units and remote checks improve uptime, range use, and service plans. Smart powertrains adjust load and fuel use to match drive needs. Telematics and data tools cut idle time and support predictive service. These gains raise fleet value and shorten payback time. The trend creates paths for service revenue, software updates, and long-term user ties. Makers of hybrid, electric, and gas engines use digital tools to stand out.
- For instance, Volvo connected diagnostics reduced unplanned stops by 24 events per 100 trucks each year.
Key Challenges
Fuel Supply and Infrastructure Gaps
Access to gas, hydrogen, and fast charging shapes market pace. Sparse station networks slow fleet change and raise routing limits. Marine and heavy truck roles need wide coverage and high capacity sites. Storage cost and safety rules add delay. These gaps force users to keep mixed fleets and limit scale. Growth needs broad action from fuel firms, grid players, and public bodies.
Higher Upfront Cost and Payback Concerns
Clean engines and hybrid units cost more than diesel peers. Users weigh long-term fuel and service gains against short-term spend. Payback varies by duty cycle, fuel price, and route. Small fleets face tight budgets and risk barriers. Makers must cut system cost and offer service plans and finance tools. Clear total cost data and proven uptime help ease these concerns and support wider use.
Regional Analysis
North America
North America holds 34% share in 2024, driven by strong focus on clean transport and fleet renewal. Users in trucking, municipal services, and industrial sectors adopt gas, hybrid, and hydrogen engines. Tax credits, emission rules, and infrastructure grants support growth in the United States and Canada. Local OEMs expand supply, while energy firms invest in LNG and hydrogen hubs. Rising freight movement, urban air goals, and fast progress in charging networks sustain growth. This region remains a key hub for early commercial use and advanced pilot projects across heavy duty and light duty fleets.
Europe
Europe accounts for 31% share in 2024 as strict emission norms guide fleet change. Road and marine users shift to natural gas, biofuel, hybrid, and fuel cell engines to meet climate goals. Strong backing from EU green funds and national policies accelerates rollout. OEMs launch new models and expand supply lines for trucks, buses, and off-road roles. Ports invest in LNG bunkering and hydrogen trials for vessels. The region’s clear policy path, strong charging reach, and rising carbon costs keep demand steady.
Asia Pacific
Asia Pacific holds 27% share in 2024, supported by fast industrial growth and large transport fleets. China, Japan, South Korea, and India invest in gas, hybrid, and hydrogen engines to cut emissions and fuel use. Public transit upgrades and freight expansion drive engine demand. Local makers scale battery, gas, and fuel cell lines. Growing fuel access and R&D support long-term gains. Infrastructure buildout in ports, transit, and industry enhances uptake. The region posts strong growth as nations balance cost and clean energy goals.
Latin America
Latin America captures 5% share in 2024, driven by interest in gas and biofuel engines across road and industrial roles. Brazil and Mexico lead adoption with incentives and strong biofuel supply chains. Fleet users aim to reduce fuel spend and emissions. Infrastructure limits and higher capital cost slow scale, yet new LNG stations and hybrid bus programs improve outlook. Local assembly, policy support, and fuel diversity build momentum. The region shows steady progress as economic recovery, urban growth, and climate goals shape future demand.
Middle East & Africa
Middle East & Africa represent 3% share in 2024, shaped by early-stage projects in gas, hydrogen, and hybrid engines. Gulf states invest in hydrogen hubs and clean mobility pilots. Industrial sites adopt gas engines to cut operating cost and emissions. Limited charging and fuel networks curb near-term scale, but new corridors and port upgrades enhance reach. Off-road and marine roles show promise as users seek cost and carbon gains. Long-term growth aligns with energy diversification and industrial plans across key countries.
Alternative Fuel Engine Market Segmentations:
By Fuel Type
- Natural Gas
- Biofuel
- Hydrogen
- Electric Hybrid
By Engine Type
- Internal Combustion Engine
- Electric Engine
- Hybrid Engine
- Fuel Cell Engine
By Application
- Automotive
- Marine
- Aerospace
- Industrial Machinery
By End User
- Transportation & Logistics
- Power Generation
- Agriculture
- Construction
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape features major companies including Cummins Inc., Caterpillar Inc., Toyota Motor Corporation, Ford Motor Company, General Motors Company, Weichai Power Co. Ltd., Hyundai Motor Company, Honda Motor Co. Ltd., MAN Energy Solutions SE, and Yanmar Holdings Co. Ltd. These companies focus on clean engine platforms, covering gas, hybrid, electric, and fuel cell powertrains. They invest in R&D to improve output, range, and durability. Strategic partnerships with fuel suppliers, tech firms, and fleet owners speed deployment. Many firms expand regional manufacturing and service networks to support uptime and lower lifecycle cost. Mergers, product launches, and pilot fleet programs remain common. Competitive analysis shows rising focus on digital tools that boost efficiency and service value. Leading firms build scale through strong dealer links and retrofit options, while new entrants target niche roles in hydrogen and fuel cell engines. This landscape supports fast technology upgrades and wider fuel choice across sectors.
Key Player Analysis
- Cummins Inc.
- Caterpillar Inc.
- Toyota Motor Corporation
- Ford Motor Company
- General Motors Company
- Weichai Power Co. Ltd.
- Hyundai Motor Company
- Honda Motor Co. Ltd.
- MAN Energy Solutions SE
- Yanmar Holdings Co. Ltd.
Recent Developments
- In November 2025, Toyota advanced hydrogen combustion tech with the liquid hydrogen GR Corolla concept at a race event.
- In January 2025, Cummins unveiled its next-gen HELM engine platform and hydrogen fuel delivery system for cleaner trucks, with hydrogen pressure tech and BSVI-compliant engines.
- In September 2024, Caterpillar highlighted development of flexible engines that run on biofuels, hydrogen and natural gas to support emissions goals.
Report Coverage
The research report offers an in-depth analysis based on Fuel Type, Engine Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will grow as fleets replace diesel units with cleaner engines.
- Hydrogen engines and fuel cells will gain scale in heavy-duty roles.
- Hybrid systems will expand due to long range and flexible use.
- Electric engines will rise in light-duty transport and short-route fleets.
- Fuel access networks will expand for gas, hydrogen, and charging.
- Engine efficiency gains will boost power density and uptime.
- Digital tools will improve service planning and total cost control.
- Regional policies will guide technology mix and fleet timing.
- OEM and energy partnerships will shape product launch and scale.
- Lower system cost and clear payback will support wider adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Alternative Fuel Engine market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Alternative Fuel Engine market projected to grow between 2024 and 2032?
Which Alternative Fuel Engine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Alternative Fuel Engine market?
Who are the leading companies in the Alternative Fuel Engine market?
Which region commanded the largest share of the Alternative Fuel Engine market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 404,403 million → 2032: USD 958,481.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Alternative Fuel Engine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Alternative Fuel Engine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Alternative Fuel Engine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Alternative Fuel Engine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Alternative Fuel Engine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Alternative Fuel Engine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Alternative Fuel Engine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Alternative Fuel Engine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 404,403 million → 2032: USD 958,481.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Alternative Fuel Engine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Alternative Fuel Engine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Alternative Fuel Engine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Alternative Fuel Engine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

