
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Alternative Sweeteners Market Size 2024 | USD 4,910 Million |
| Alternative Sweeteners Market, CAGR | 5% |
| Alternative Sweeteners Market Size 2032 | USD 7,254.3 Million |
Market Overview:
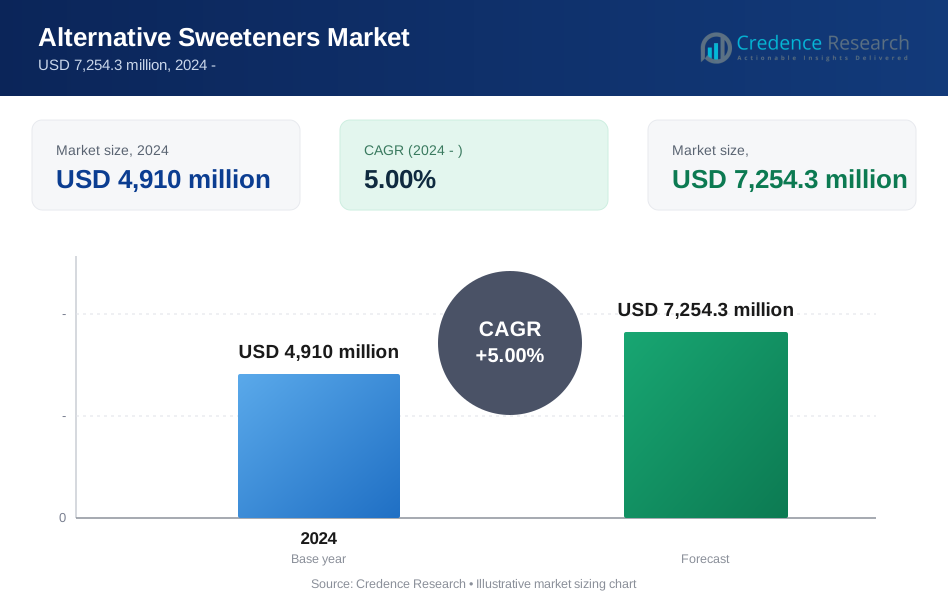
The global Alternative Sweeteners Market is anticipated to grow from USD 4,910 million in 2024 to USD 7,254.3 million by 2032, with a compound annual growth rate (CAGR) of 5%. Alternative sweeteners, which include natural and artificial options like stevia, aspartame, and sucralose, are used to provide sweetness without the caloric impact of sugar, making them popular in food, beverage, and pharmaceutical industries. Increasing consumer awareness of health issues, such as obesity and diabetes, is driving this market growth, as alternative sweeteners offer a solution for consumers seeking reduced sugar intake. Additionally, the market is expanding into niche segments, including specialty and functional foods, to cater to rising health-conscious and diabetic populations.
Key drivers of the alternative sweeteners market include growing health consciousness, increased prevalence of lifestyle diseases, and regulatory approvals for new sweetening agents. Consumers are actively seeking low-calorie, sugar-free products, prompting food and beverage companies to adopt alternative sweeteners widely. The natural sweetener segment, led by products like stevia and monk fruit, is witnessing strong growth due to consumer demand for plant-based ingredients. Additionally, ongoing research and development enhance the taste and application versatility of these sweeteners, further supporting market expansion.
Regionally, North America holds the largest market share, driven by high demand for low-calorie and sugar-free products in the U.S. and Canada. The presence of leading food and beverage companies and significant consumer health awareness contribute to this dominance. Europe also has a substantial share, with increasing regulations around sugar reduction and a strong focus on health in countries like Germany and the U.K. Meanwhile, the Asia-Pacific region is expected to see the fastest growth, with rising disposable incomes, urbanization, and awareness of lifestyle-related health issues fueling demand for alternative sweeteners, particularly in China, Japan, and India. This regional distribution reflects a global trend toward reduced sugar consumption and growing preference for healthier ingredients.
Market Drivers:
Rising Health Consciousness and Sugar Reduction Trends:
Increasing health consciousness and awareness around the negative health effects of excessive sugar intake drive the demand for alternative sweeteners. Health organizations, including the World Health Organization (WHO), advocate for reduced sugar consumption to lower risks of obesity, diabetes, and cardiovascular diseases. Consequently, consumers are shifting toward low-calorie and sugar-free options in everyday products, propelling demand for alternatives like stevia and monk fruit. The American Heart Association reports that the average American consumes over twice the recommended daily sugar intake, highlighting the need for healthier alternatives.
Government Regulations and Sugar Tax Initiatives:
Government policies and regulations targeting sugar reduction significantly impact the alternative sweeteners market. Sugar taxes in countries such as the United Kingdom, Mexico, and the United Arab Emirates are designed to discourage excessive sugar consumption, pushing food and beverage companies to adopt low-calorie sweeteners to comply with these regulations. For instance, the U.K.'s Soft Drinks Industry Levy has led to a marked increase in sugar-free and reduced-sugar beverage formulations, driving manufacturers to explore alternative sweeteners as compliant ingredients in their products.
Consumer Demand for Natural Ingredients:
Natural alternative sweeteners, including stevia, monk fruit, and agave syrup, are seeing rising popularity as consumers increasingly seek plant-based ingredients. This trend is driven by the clean-label movement, where consumers demand minimally processed, natural products without artificial additives. According to a survey by Innova Market Insights, 60% of global consumers look for natural ingredients in food products. Companies like Cargill and Tate & Lyle have responded by expanding their product lines to include naturally derived sweeteners that appeal to health-conscious consumers.
Technological Advancements in Product Formulation:
Technological advancements in product formulation enhance the taste, stability, and versatility of alternative sweeteners, enabling their use across a broader range of applications. For instance, PureCircle has developed advanced stevia extraction technologies to improve sweetness profiles and reduce the bitter aftertaste often associated with natural sweeteners. Similarly, ongoing research on blending alternative sweeteners allows manufacturers to achieve flavors and textures similar to sugar, making these products suitable for various uses in food and beverage manufacturing. These advancements expand the market’s reach and support the adoption of alternative sweeteners in mainstream and specialty applications.
Market Trends:
Expansion of Natural Sweeteners in Product Offerings:
The alternative sweeteners market is seeing a shift toward natural sweeteners, like stevia and monk fruit, as consumers increasingly prefer plant-based options over synthetic ones. This shift aligns with the clean-label trend, where consumers seek minimally processed products with transparent ingredient lists. For example, PepsiCo reformulated several of its beverages using stevia-based sweeteners to align with consumer preferences for natural ingredients. Similarly, Tate & Lyle reports increased demand for its naturally derived ingredients, highlighting a strong market trend toward natural, plant-based sweeteners in various food and beverage formulations.
Rise of Blended Sweetener Formulations:
To address taste and texture challenges associated with alternative sweeteners, manufacturers are developing blended sweetener formulations that combine multiple sweeteners for enhanced flavor profiles. By blending stevia or monk fruit with erythritol or allulose, companies can improve sweetness without the bitter aftertaste or loss of mouthfeel. For instance, Cargill has introduced blends that pair stevia with other sweeteners to achieve sugar-like taste profiles. This trend of combining sweeteners to achieve optimal flavor is expanding the versatility of alternative sweeteners across multiple applications.
Adoption of Low-Calorie Sweeteners in the Beverage Sector:
The beverage industry remains a significant adopter of alternative sweeteners, especially amid rising health concerns regarding sugar intake in soft drinks and juices. Many beverage brands are introducing low-calorie and zero-calorie drinks using alternative sweeteners to cater to health-conscious consumers. For example, The Coca-Cola Company has expanded its line of reduced-sugar beverages with products that use stevia and aspartame to meet consumer demand for healthier options. According to a report by the International Food Information Council (IFIC), 55% of consumers are concerned about sugar in beverages, a statistic that continues to drive this adoption.
Increased Research on Novel Sweeteners:
Innovations in alternative sweetener sources, such as allulose and brazzein, are becoming prominent as companies invest in research for new ingredients. Allulose, a rare sugar with low-calorie content, has garnered attention for its sugar-like taste and functionality, while brazzein, a protein-based sweetener, offers high sweetness with minimal aftertaste. Companies like Ingredion and ADM are exploring these novel sweeteners to meet evolving consumer expectations for taste and health benefits. This trend highlights the market’s focus on diversifying sweetener options and addressing taste challenges in reduced-sugar products.
Market Challenges Analysis:
Regulatory and Approval Barriers:
The alternative sweeteners market faces significant regulatory hurdles, as government authorities such as the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) require stringent safety evaluations before allowing new sweeteners in food and beverage applications. The approval process can be lengthy and costly, limiting market entry for novel sweeteners. For example, while allulose has gained FDA recognition as generally safe, it remains regulated in other regions, restricting its use in global product formulations. This lack of uniformity creates barriers for manufacturers looking to introduce new sweeteners internationally.
Technical and Taste Challenges:
Many alternative sweeteners, especially natural ones like stevia, present taste challenges due to bitter or lingering aftertastes that can deter consumer acceptance. To improve flavor, manufacturers often blend sweeteners, but this adds complexity and production costs. According to studies by the International Food Information Council (IFIC), consumer satisfaction with alternative sweeteners largely depends on achieving a taste and texture comparable to sugar, a standard that remains difficult to meet consistently across all sweetener types.
High Production and Sourcing Costs:
Natural sweeteners like stevia and monk fruit are more expensive to produce compared to synthetic alternatives, as they involve labor-intensive extraction processes and depend on crop availability. Variable agricultural yields further contribute to cost volatility, impacting manufacturers’ ability to price competitively. The U.S. Department of Agriculture (USDA) notes that fluctuations in stevia production, driven by environmental conditions, can increase costs for companies relying on natural sweeteners. This financial pressure affects their capacity to maintain competitive pricing in a market dominated by low-cost synthetic alternatives.
Consumer Skepticism and Awareness Gaps:
Despite rising health consciousness, some consumers remain skeptical of alternative sweeteners due to unfamiliarity or perceived unnaturalness. The American Heart Association emphasizes the importance of public education to address misconceptions around safety and efficacy. Limited awareness can hinder market growth, particularly in emerging regions where traditional sugar remains more trusted and accessible.
Market Segmentation Analysis:
By Type, the market includes natural sweeteners such as stevia, monk fruit, and agave syrup, alongside artificial sweeteners like aspartame, sucralose, and saccharin. Natural sweeteners are gaining traction due to their plant-based origin and perceived health benefits, while synthetic sweeteners remain popular in large-scale applications for their cost efficiency and stability. The natural segment is growing as consumer preferences shift toward clean-label and plant-based ingredients.
By Technology, the market is categorized into enzymatic conversion, extraction, and fermentation processes. Extraction is widely used, particularly for natural sweeteners like stevia and monk fruit, where advanced extraction methods improve taste and potency. Fermentation, gaining attention for its sustainability, is also used to produce novel sweeteners with enhanced flavor profiles. These technologies support manufacturers in delivering high-quality sweeteners that meet the diverse demands of consumers.
By End User, the market serves food and beverage, pharmaceuticals, and personal care sectors. The food and beverage industry dominates, as alternative sweeteners are essential for sugar reduction in soft drinks, snacks, and baked goods. In pharmaceuticals, sweeteners enhance palatability in medicines and supplements, while personal care applications involve sweeteners in oral care products like toothpaste. This segmentation highlights the adaptability of alternative sweeteners to varied industry needs and evolving consumer preferences.
Segmentations:
By Product Type
- High Fructose Syrup
- High-intensity Sweetener
- Low-intensity Sweetener
By Application
- Food
- Beverage
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America North America holds the largest share of the alternative sweeteners market, accounting for approximately 35% of global revenue. This dominance is largely driven by the high prevalence of health-conscious consumers and widespread awareness of sugar-related health issues, such as obesity and diabetes. The United States, in particular, plays a significant role due to substantial demand for low-calorie and sugar-free products in food and beverages. Regulatory bodies, like the U.S. Food and Drug Administration (FDA), have approved various sweeteners, fostering an environment conducive to product development. Canada also contributes significantly, driven by consumer preferences for plant-based, low-calorie sweeteners in line with clean-label trends. The strong presence of leading companies, such as Cargill and Ingredion, also bolsters North America’s position in the market.
Europe Europe represents around 25% of the global alternative sweeteners market, with a strong focus on natural and plant-based ingredients driven by rising health and wellness awareness. The European Union’s Sugar Reduction Directive and similar health policies across member states encourage manufacturers to lower sugar content in their products, resulting in higher demand for alternatives. The U.K., Germany, and France lead the region, where consumers are increasingly favoring clean-label and sugar-free foods and beverages. Additionally, the European Food Safety Authority (EFSA) actively regulates and approves sweeteners, building consumer trust. Growth in this region is supported by companies like Tate & Lyle, which focus on expanding natural sweetener portfolios that align with consumer preferences for eco-conscious products.
Asia-Pacific Asia-Pacific is anticipated to witness the fastest growth in the alternative sweeteners market, capturing approximately 20% of the global market share by 2032. This growth is fueled by rapid urbanization, rising disposable incomes, and increasing awareness of lifestyle-related health issues across countries like China, Japan, and India. China’s high demand for low-calorie sweeteners in food and beverages reflects the government’s initiatives to reduce sugar consumption to combat rising obesity rates. Japan’s health-conscious population also supports the market, with high demand for alternative sweeteners in functional and traditional foods. The presence of local manufacturers developing affordable, innovative sweetener options, combined with support from regulatory bodies like Japan’s Ministry of Health, drives strong regional market growth.
Latin America and Middle East & Africa Latin America and the Middle East & Africa (MEA) together account for around 10% of the global alternative sweeteners market. In Latin America, Brazil and Mexico are the main markets, with growing consumer awareness around health issues and rising demand for low-calorie products. Although the market is smaller than in North America and Europe, sugar taxes in countries like Mexico encourage the use of alternative sweeteners. In MEA, demand is mainly concentrated in urban centers, with the UAE and South Africa leading growth due to an increase in health-conscious consumers seeking sugar alternatives. However, limited awareness and lower purchasing power in some areas present challenges to widespread adoption in these regions.
Key Player Analysis:
- Cargill, Incorporated
- Archer Daniels Midland Company
- Tate & Lyle PLC
- Ingredion Incorporated
- Ajinomoto Co., Inc.
- Roquette Frères
- International Flavors & Fragrances Inc. (DuPont Nutrition & Health)
- PureCircle Limited
- The Coca-Cola Company
- PepsiCo, Inc.
Competitive Analysis:
The alternative sweeteners market is moderately competitive, led by established players such as Cargill, Incorporated, Tate & Lyle PLC, and Archer Daniels Midland Company. These major companies leverage extensive R&D capabilities and broad distribution networks to meet rising consumer demand for low-calorie and plant-based sweeteners. The market is characterized by rapid innovation, particularly in natural sweeteners like stevia and monk fruit, as consumers increasingly favor clean-label ingredients. Mid-sized firms and specialized companies, such as PureCircle Limited and Ajinomoto Co., Inc., contribute to the competitive landscape by focusing on product differentiation and sustainable production methods. The competition also reflects a regional dynamic, with North American and European firms benefiting from strong regulatory frameworks that promote sugar reduction initiatives. Collectively, these companies emphasize sustainable production and regulatory compliance, maintaining competitiveness as health and wellness trends shape consumer preferences.
Recent Developments:
- Tate & Lyle expanded its market presence in March 2023 by partnering with IMCD to enhance distribution of sweeteners, fibers, and stabilizers in Brazil. This collaboration allows Tate & Lyle to strengthen its footprint in Latin America, meeting rising demand for healthier sweetener options in the region.
- Ingredion launched a new line of natural sweetener blends in 2023 that combine stevia and allulose to mimic sugar’s mouthfeel and flavor without added calories. This move aligns with increased demand for sugar alternatives in beverages and baked goods, especially in North America.
- In 2022, HOWTIAN introduced new specialty stevia blends under its SoPure line to reduce the bitter aftertaste often associated with stevia. This innovation has improved consumer acceptance, enabling stevia’s broader use in foods where flavor quality is crucial, such as dairy and confectionery products.
- International Flavors & Fragrances (IFF) inaugurated its Nourish Innovation Lab in New Jersey in August 2022, aiming to support R&D for alternative sweeteners and other food ingredients. This lab is dedicated to formulating innovative products that cater to health-conscious consumers in the food and beverage industry.
Market Concentration & Characteristics:
The alternative sweeteners market is moderately concentrated, with major players such as Cargill, Incorporated, Tate & Lyle PLC, and Ingredion Incorporated leading due to their robust R&D, extensive distribution channels, and diversified product portfolios. These companies focus on developing innovative, natural sweeteners like stevia and allulose, which meet consumer demand for healthier sugar alternatives. Mid-sized firms, including PureCircle Limited and Ajinomoto Co., Inc., contribute by specializing in niche products and sustainable production processes. The market’s competitive landscape is shaped by growing consumer health awareness and regulatory pressures for sugar reduction, particularly in North America and Europe. This has driven manufacturers to focus on clean-label, plant-based sweeteners to capture market share. As these companies innovate and respond to regional consumer preferences, they foster a dynamic environment that balances large-scale production capabilities with emerging, health-focused solutions in alternative sweeteners.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The alternative sweeteners market is expected to grow as health-conscious consumers increasingly seek sugar-free and low-calorie options across various food and beverage products.
- Rising demand for natural sweeteners, such as stevia and monk fruit, will likely drive the market, as consumers prefer plant-based.
- Government regulations aimed at reducing sugar consumption are anticipated to continue propelling the adoption of alternative sweeteners, particularly in North America and Europe.
- The beverage industry is forecasted to remain a key application sector, with brands developing low-sugar or sugar-free beverages to appeal to health-focused consumers.
- New product formulations using blended sweeteners are expected to expand as companies focus on improving taste profiles and masking aftertastes associated with some sweeteners.
- Asia-Pacific is projected to witness the fastest growth, driven by rising disposable incomes, urbanization, and increasing awareness of sugar-related health concerns.
- Ongoing R&D investments are anticipated to introduce novel sweeteners like allulose and brazzein, expanding the range of options available to manufacturers and consumers.
- Growing popularity of clean-label products will likely boost demand for alternative sweeteners, particularly in the natural sweetener segment.
- E-commerce channels are expected to facilitate growth, making it easier for consumers to access a variety of alternative sweetener products globally.
- Industry collaborations and partnerships between ingredient manufacturers and food companies are expected to drive product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Alternative Sweeteners Market?
What factors are driving the growth of the Alternative Sweeteners Market?
What are some challenges faced by the Alternative Sweeteners Market?
Who are the major players in the Alternative Sweeteners Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Alternative Sweeteners Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Alternative Sweeteners Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 4,910 million → forecast year: USD 7,254.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Alternative Sweeteners Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Alternative Sweeteners Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Alternative Sweeteners Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Alternative Sweeteners Market Drivers
- 3.3 Alternative Sweeteners Market Restraints & Challenges
- 3.4 Alternative Sweeteners Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Alternative Sweeteners Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Alternative Sweeteners Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Alternative Sweeteners category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Alternative Sweeteners Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Alternative Sweeteners Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Alternative Sweeteners market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Alternative Sweeteners Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Alternative Sweeteners Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Alternative Sweeteners Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Alternative Sweeteners (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Alternative Sweeteners Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Alternative Sweeteners Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Alternative Sweeteners Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Alternative Sweeteners Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Alternative Sweeteners Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Alternative Sweeteners Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Alternative Sweeteners Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Alternative Sweeteners Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Alternative Sweeteners Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
