
Market Overview
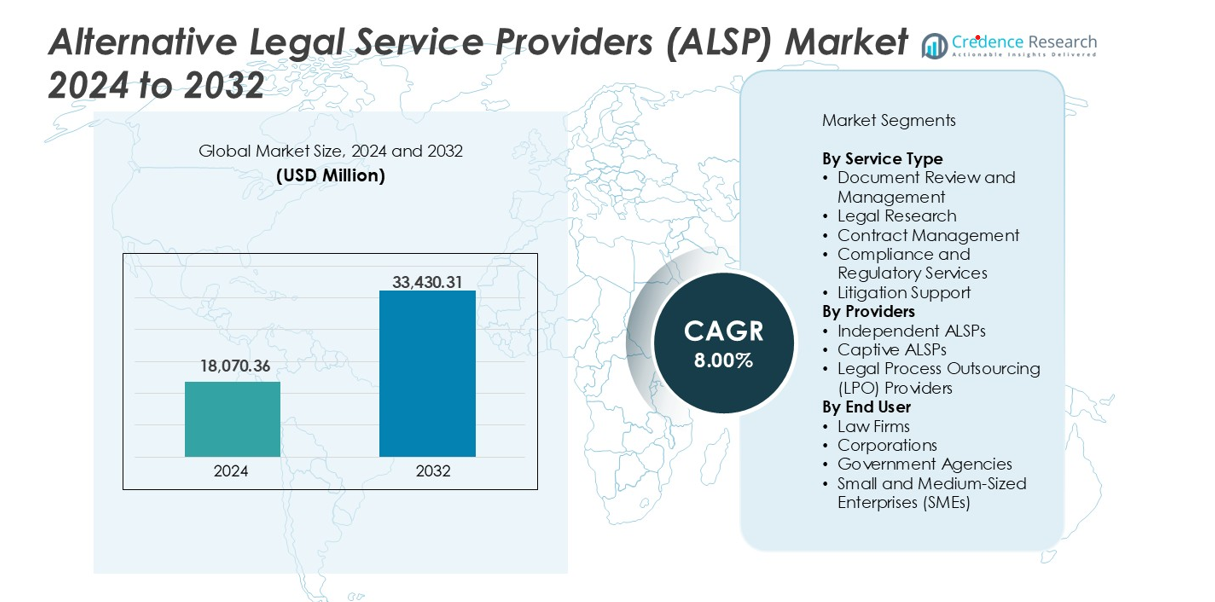
The Alternative Legal Service Providers (ALSP) market size was valued at USD 18,070.36 million in 2024 and is anticipated to reach USD 33,430.31 million by 2032, expanding at a CAGR of 8.00% during the forecast period (2024–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Alternative Legal Service Providers (ALSP) MarketSize 2024 | USD 18,070.36 million |
| Alternative Legal Service Providers (ALSP) Market, CAGR | 8.00% |
| Alternative Legal Service Providers (ALSP) Market Size 2032 | USD 33,430.31 million |
The Alternative Legal Service Providers (ALSP) market is led by major players such as Clifford Chance, Everlaw, Epiq, Integreon, LegalZoom, Lawyers on Demand, Morae Global, QuisLex, and Exigent. These companies dominate through advanced AI-driven legal research, e-discovery, and contract management solutions tailored for corporate and law firm clients. Their focus on automation, cost efficiency, and compliance support enhances global adoption across sectors. North America leads the market with a 41% share in 2024, driven by strong technology integration and mature outsourcing practices, followed by Europe with 28%, supported by robust regulatory compliance frameworks and cross-border legal operations.
Market Insights
- The Alternative Legal Service Providers (ALSP) market was valued at USD 18,070.36 million in 2024 and is projected to reach USD 33,430.31 million by 2032, growing at a CAGR of 8.00% from 2024 to 2032.
- The market is driven by growing demand for cost-efficient legal outsourcing, digital workflow automation, and regulatory compliance management across global law firms and enterprises.
- Emerging trends include AI-powered e-discovery, hybrid legal models, and expansion into niche areas such as ESG, IP management, and data protection services.
- Competition remains strong among players such as Clifford Chance, Everlaw, Epiq, Integreon, LegalZoom, and QuisLex, each focusing on automation and strategic partnerships to gain share.
- North America leads the market with 41% share, followed by Europe (28%) and Asia-Pacific (19%), while the Document Review and Management segment holds the largest service share at 34%.
Market Segmentation Analysis:
By Service Type
Document review and management dominated the Alternative Legal Service Providers (ALSP) market in 2024, accounting for around 34% of the total share. This segment leads due to rising demand for efficient e-discovery, due diligence, and case file management across litigation and corporate transactions. Legal research and contract management are also expanding rapidly, supported by AI-powered tools that enhance speed and accuracy. Increasing use of automation platforms such as Relativity and Everlaw further accelerates the adoption of document review services, enabling law firms and corporations to cut operational costs and improve legal turnaround times.
- For instance, Relativity's cloud-based e-discovery platform has processed over 28 billion documents for its customers, with the largest workspace containing 155 million documents. Meanwhile, Everlaw handles massive amounts of legal data for investigations, with one matter involving over 10 million documents using its GenAI
By Providers
Independent ALSPs held the largest share of about 47% in 2024, driven by their flexibility, scalability, and ability to serve multiple clients across jurisdictions. These providers specialize in delivering customized legal process solutions, including contract lifecycle management and compliance support, without the fixed overhead of captive units. Legal Process Outsourcing (LPO) providers follow closely, boosted by offshoring advantages in countries like India and the Philippines. The growing preference for specialized independent firms stems from their proven expertise, lower cost structures, and ability to integrate advanced analytics for efficient case handling.
- For instance, Integreon is a global provider of legal and business process solutions, serving over 250 corporate and law firm clients through its worldwide network of delivery centers. Similarly, QuisLex is an alternative legal services provider that uses advanced analytics and automation to handle large volumes of legal documents for its clients.
By End User
Law firms represented the leading end-user segment in 2024, capturing nearly 41% of the global share. They rely heavily on ALSPs for document review, e-discovery, and due diligence to manage growing case volumes and complex client requirements. Corporations are emerging as a fast-growing segment, using ALSPs for compliance and contract management to reduce legal spend. The increasing need for scalability, data security, and cost optimization drives outsourcing among law firms and enterprises, while government agencies and SMEs gradually adopt ALSPs to enhance regulatory and litigation efficiency.
Key Growth Drivers
Rising Demand for Cost-Efficient Legal Solutions
The increasing need for affordable legal support is a major growth driver for the ALSP market. Law firms and corporations are outsourcing repetitive legal processes such as document review, contract drafting, and regulatory compliance to reduce overhead expenses. ALSPs offer flexible, scalable solutions that minimize costs while maintaining service quality. The use of automation and AI-driven tools enhances productivity and accuracy, making ALSPs an attractive option compared to traditional in-house teams. Growing pressure on law firms to deliver competitive pricing and improve efficiency continues to accelerate ALSP adoption across global legal ecosystems.
- For instance, Epiq manages large-scale and complex e-discovery tasks for clients, with its global daily processing capacity exceeding 15 terabytes. Epiq also uses AI and advanced analytics to help clients review hundreds of millions of documents annually.
Expansion of Legal Technology and Automation
The integration of advanced technologies, including artificial intelligence, machine learning, and natural language processing, is transforming ALSP capabilities. AI-powered tools automate complex tasks such as e-discovery, predictive case analytics, and contract lifecycle management, allowing faster and more accurate results. These innovations enable legal professionals to focus on strategic advisory roles rather than routine administrative work. Platforms like Relativity, Everlaw, and Kira Systems are leading this shift, enhancing efficiency and reducing manual errors. As law firms increasingly adopt digital workflows, the demand for tech-enabled ALSPs is set to expand significantly across jurisdictions.
- For instance, in 2024, Relativity expanded the reach of its generative AI tools to thousands of customers, with an IDC report commissioned by the company highlighting a substantial increase in AI usage within the legal profession.
Increasing Regulatory and Compliance Complexities
The global regulatory landscape is becoming more complex, prompting organizations to seek specialized compliance support. ALSPs help businesses navigate evolving laws such as GDPR, CCPA, and ESG-related mandates by providing dedicated compliance monitoring and audit services. These providers also assist in due diligence, data governance, and anti-bribery risk assessments. The rise of cross-border transactions and data privacy requirements intensifies the need for expert legal outsourcing. As corporations prioritize risk management and transparency, the reliance on ALSPs for regulatory assurance and governance support continues to grow across financial, healthcare, and technology sectors.
Key Trends & Opportunities
Growing Adoption of Hybrid Legal Service Models
A major trend shaping the ALSP market is the rise of hybrid legal service models combining in-house expertise with outsourced support. Law firms and enterprises increasingly partner with ALSPs to manage fluctuating workloads while retaining control over core legal strategy. This model allows seamless integration between technology-driven processes and traditional legal oversight. ALSPs now collaborate directly with corporate legal departments on strategic projects, including mergers, compliance audits, and litigation support. This partnership-based approach enhances agility and scalability, promoting efficient use of technology and human expertise to deliver high-value legal outcomes.
- For instance, Clifford Chance's Best Delivery initiative uses AI-enabled document review from partners like Kira Systems and Relativity across its global offices. The firm employs these tools for large-scale document review under hybrid workflows, where AI technology is combined with human oversight to handle high volumes of legal documents.
Expansion into Specialized and Emerging Practice Areas
ALSPs are rapidly diversifying into specialized domains such as intellectual property management, cybersecurity, and environmental law compliance. This shift reflects growing client demand for domain-specific legal expertise supported by digital tools. Many providers now offer AI-based trademark monitoring, patent analytics, and ESG due diligence solutions. Expansion into these niche segments enhances value creation and differentiates ALSPs from traditional outsourcing models. As global regulatory expectations evolve, providers that offer tailored solutions in high-risk, high-compliance sectors are positioned to capture new growth opportunities in the legal services landscape.
Key Challenges
Data Security and Confidentiality Concerns
Data protection remains a critical challenge for ALSP adoption. Outsourcing legal processes involves transferring sensitive client data, exposing organizations to potential security breaches. Despite adherence to global standards like ISO 27001 and GDPR, concerns over data integrity and unauthorized access persist. Clients often hesitate to outsource high-risk legal work due to confidentiality issues and regulatory restrictions. To address this, ALSPs must invest in robust cybersecurity infrastructure, encryption technologies, and secure cloud solutions. Maintaining transparency and compliance in data handling is essential to building long-term client trust and sustaining market growth.
Limited Awareness and Resistance to Outsourcing
Despite proven efficiency benefits, resistance to outsourcing persists among traditional law firms and corporate counsels. Many legal professionals still prefer in-house teams due to perceived risks around quality control, confidentiality, and client relationship management. This mindset slows ALSP adoption, especially in regions with conservative legal practices. Additionally, limited awareness of ALSP capabilities and technology-driven advantages restricts market expansion. To overcome this, providers must focus on client education, transparent pricing, and outcome-based engagement models that demonstrate measurable efficiency gains and reliability in delivering legal support services.
Regional Analysis
North America
North America dominated the Alternative Legal Service Providers (ALSP) market in 2024, holding around 41% of the global share. The region’s growth is driven by strong adoption among large law firms and corporate legal departments seeking cost efficiency and scalability. The U.S. leads the market due to advanced legal technology integration and a mature outsourcing ecosystem. Key providers such as UnitedLex, Integreon, and Elevate have established strong footprints. Increasing demand for e-discovery, contract lifecycle management, and compliance monitoring continues to drive market expansion across legal and corporate sectors.
Europe
Europe accounted for approximately 28% of the global ALSP market share in 2024, supported by stringent regulatory frameworks such as GDPR and evolving legal outsourcing practices. The U.K. remains a major hub, hosting several global ALSP firms offering compliance and litigation support. European law firms increasingly collaborate with ALSPs for multilingual document review and cross-border contract management. Growing digitalization, coupled with the need for transparency in legal processes, is fostering steady regional growth. Demand for AI-enabled compliance and data governance solutions continues to strengthen across financial and technology sectors.
Asia-Pacific
Asia-Pacific captured nearly 19% of the ALSP market share in 2024 and is projected to witness the fastest growth through 2032. The region benefits from cost-effective service delivery models and a skilled legal workforce in countries like India and the Philippines. Global firms are expanding operations to tap into outsourcing and offshoring advantages. Rising demand for technology-driven legal services, especially in contract management and due diligence, supports regional expansion. Growing digital infrastructure, rapid business globalization, and supportive government regulations make Asia-Pacific a preferred ALSP outsourcing destination.
Latin America
Latin America held about 7% of the global ALSP market share in 2024, driven by increasing adoption of legal outsourcing across Brazil, Mexico, and Chile. The region’s growing corporate sector is embracing ALSPs to manage compliance and regulatory documentation efficiently. Firms are partnering with global providers to access advanced digital platforms for e-discovery and contract review. The shift toward digital legal transformation and rising cross-border trade disputes are creating opportunities for regional ALSP expansion. However, limited awareness and inconsistent data protection laws continue to challenge large-scale market adoption.
Middle East & Africa
The Middle East & Africa region accounted for roughly 5% of the ALSP market share in 2024. Market growth is fueled by expanding corporate operations, particularly in the UAE, Saudi Arabia, and South Africa. Organizations are increasingly outsourcing compliance, arbitration, and document management services to improve efficiency. Government modernization efforts and investment in digital transformation are fostering ALSP adoption. The growing number of international law firms establishing regional partnerships supports service expansion. However, low digital maturity and limited legal technology infrastructure still restrict full-scale market penetration.
Market Segmentations:
By Service Type
- Document Review and Management
- Legal Research
- Contract Management
- Compliance and Regulatory Services
- Litigation Support
By Providers
- Independent ALSPs
- Captive ALSPs
- Legal Process Outsourcing (LPO) Providers
By End User
- Law Firms
- Corporations
- Government Agencies
- Small and Medium-Sized Enterprises (SMEs)
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Alternative Legal Service Providers (ALSP) market is highly competitive, characterized by a mix of global law firms, technology-driven platforms, and specialized outsourcing companies. Key players such as Clifford Chance, Everlaw, Epiq, Integreon, LegalZoom, Lawyers on Demand, Morae Global, QuisLex, and Exigent dominate through diverse service portfolios covering document review, litigation support, contract management, and compliance solutions. These companies leverage advanced technologies like AI, machine learning, and automation to enhance service delivery and reduce turnaround times. Strategic partnerships, mergers, and geographic expansions are common to strengthen client bases and technological capabilities. Providers increasingly focus on flexible engagement models, pricing transparency, and industry-specific expertise to retain competitive advantage. The market’s competitive intensity continues to rise as traditional law firms and new tech entrants adopt ALSP frameworks to meet growing demand for cost-efficient, scalable, and technology-integrated legal solutions worldwide.
Key Player Analysis
- Clifford Chance
- Everlaw
- Epiq
- Integreon
- LegalZoom
- Lawyers on Demand
- Morae Global
- QuisLex
- Exigent
Recent Developments
- In 2024, Integreon expanded its global footprint by opening a new delivery center in Manila, Philippines. This strategic move aims to enhance Integreon’s service capabilities and support its growing client base in the Asia-Pacific region. The new center focuses on delivering high-quality document review, contract management, and compliance services. By leveraging the skilled workforce in Manila, Integreon aims to provide cost-effective and efficient legal solutions, strengthening its competitive edge in the global market.
- In 2023, Clifford Chance launched its proprietary legal technology platform, Clifford Chance Create. This platform aims to streamline legal processes through advanced automation and AI-driven solutions. By integrating these technologies, Clifford Chance enhances its service efficiency and client experience, positioning itself at the forefront of legal innovation. The platform supports various legal tasks, including document review, contract management, and regulatory compliance, demonstrating Clifford Chance’s commitment to leveraging technology to deliver superior legal services.
- In 2023, LegalZoom introduced a new subscription-based service model called LegalZoom Plus, aimed at small businesses and entrepreneurs. This service offers comprehensive legal support, including business formation, compliance management, and legal consultations, all for a fixed monthly fee. LegalZoom Plus is designed to provide accessible and affordable legal solutions, helping small businesses navigate complex legal landscapes. This development reflects LegalZoom’s commitment to democratizing legal services and supporting the growth of small enterprises.
- In 2022, Everlaw announced a significant upgrade to its e-discovery platform, incorporating advanced AI and machine learning capabilities. This enhancement aims to improve the speed and accuracy of document review and data analysis in litigation support. The new features include predictive coding, automated document classification, and advanced data visualization tools. These upgrades are designed to help legal teams manage large volumes of data more efficiently, reinforcing Everlaw’s position as a leader in the e-discovery market.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Providers, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The ALSP market will continue expanding as law firms increase outsourcing to reduce costs.
- Technology integration such as AI and machine learning will enhance document review and compliance services.
- Hybrid legal models combining in-house teams with ALSP support will gain strong traction.
- Demand for specialized services in ESG compliance, data privacy, and IP management will rise.
- Automation and predictive analytics will improve contract management and risk assessment accuracy.
- Strategic partnerships between law firms and ALSPs will strengthen cross-border service delivery.
- Cloud-based collaboration tools will become standard for secure document sharing and workflow efficiency.
- Emerging markets in Asia-Pacific and Latin America will see accelerated adoption of ALSP solutions.
- Growing regulatory complexities will increase reliance on outsourced legal compliance services.
- Continuous investment in cybersecurity and data governance will remain critical for maintaining client trust.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Cost-Efficient Legal Outsourcing
Law firms and corporations are increasingly outsourcing routine legal processes such as document review and contract drafting to ALSPs to reduce overhead and operational costs, making legal services more affordable and scalable.
Expansion of Legal Technology and Automation
The integration of AI, machine learning, and automation tools enables ALSPs to deliver faster, more accurate, and efficient legal services, particularly in areas like e-discovery and contract management, driving adoption among law firms and enterprises.
Increasing Regulatory and Compliance Complexities
As global regulations such as GDPR and ESG mandates become more stringent, organizations turn to ALSPs for specialized compliance monitoring, audit services, and risk management, fueling market growth.
Growing Adoption of Hybrid Legal Service Models
Law firms and corporate legal departments are increasingly combining in-house expertise with outsourced ALSP support to manage fluctuating workloads and complex projects, enhancing agility and efficiency.
Expansion into Specialized and Emerging Practice Areas
ALSPs are diversifying into niche domains like intellectual property management, cybersecurity, and environmental law compliance, meeting rising client demand for domain-specific expertise and creating new growth opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Alternative Legal Service Providers (ALSP) Market in 2023 and 2032, along with its compound annual growth rate (CAGR)?
What is driving the growth of the ALSP market?
How do ALSPs differentiate themselves from traditional legal firms?
Which regions are witnessing significant growth in the ALSP market?
What are the key services offered by ALSPs?
How do ALSPs address data security and compliance challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Law Firms
- 1.2.2 Corporations
- 1.2.3 Government Agencies
- 1.2.4 Small and Medium-Sized Enterprises (SMEs)
- 1.3 By Providers
- 1.3.1 Independent ALSPs
- 1.3.2 Captive ALSPs
- 1.3.3 Legal Process Outsourcing (LPO) Providers
- 1.4 By Service Type
- 1.4.1 Document Review and Management
- 1.4.2 Legal Research
- 1.4.3 Contract Management
- 1.4.4 Compliance and Regulatory Services
- 1.4.5 Litigation Support
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18,070.36 million → 2032: USD 33,430.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Alternative Legal Service Providers (ALSP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Alternative Legal Service Providers (ALSP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Alternative Legal Service Providers (ALSP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Alternative Legal Service Providers (ALSP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Alternative Legal Service Providers (ALSP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Alternative Legal Service Providers (ALSP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Alternative Legal Service Providers (ALSP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Alternative Legal Service Providers (ALSP) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18,070.36 million → 2032: USD 33,430.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Alternative Legal Service Providers (ALSP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Law Firms
- 12.3.7.2 Corporations
- 12.3.7.3 Government Agencies
- 12.3.7.4 Small and Medium-Sized Enterprises (SMEs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Providers - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Independent ALSPs
- 12.4.7.2 Captive ALSPs
- 12.4.7.3 Legal Process Outsourcing (LPO) Providers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Document Review and Management
- 12.5.7.2 Legal Research
- 12.5.7.3 Contract Management
- 12.5.7.4 Compliance and Regulatory Services
- 12.5.7.5 Litigation Support
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Alternative Legal Service Providers (ALSP) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Alternative Legal Service Providers (ALSP) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Alternative Legal Service Providers (ALSP) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Alternative Legal Service Providers (ALSP) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Clifford Chance
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Everlaw
- 18.4 Epiq
- 18.5 Integreon
- 18.6 LegalZoom
- 18.7 Lawyers on Demand
- 18.8 Morae Global
- 18.9 QuisLex
- 18.10 Exigent
- 18.11 UnitedLex
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

