
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aluminium Extrusion Market Size 2024 | USD 83,945 Million |
| Aluminium Extrusion Market, CAGR | 8.4% |
| Aluminium Extrusion Market Size 2032 | USD 160,040 Million |
Market Overview
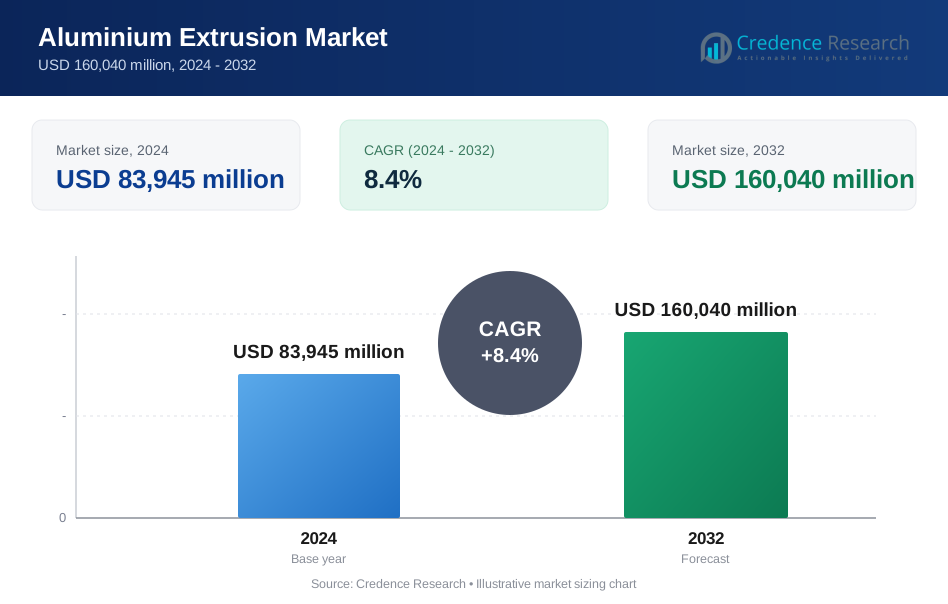
The global Aluminium Extrusion Market is expected to grow from USD 83,945 million in 2024 to USD 160,040 million by 2032, at a CAGR of 8.4%.
The aluminium extrusion market is driven by the growing demand for lightweight, durable materials in industries like automotive, construction, and aerospace. Increased focus on energy efficiency and sustainability is encouraging the use of aluminium for its recyclability and energy-saving properties. Technological advancements in extrusion processes are improving product precision and expanding applications. The rise of electric vehicles and green building trends also fuels demand, as aluminium is favored for its strength-to-weight ratio and corrosion resistance. Additionally, government regulations promoting energy-efficient materials further contribute to market growth.
The aluminium extrusion market is geographically diverse, with significant growth driven by regions such as Asia-Pacific, North America, and Europe. Asia-Pacific dominates due to rapid industrialization, infrastructure development, and growing demand for lightweight materials in automotive and construction industries. Key players in the global market include Arconic Corp., Hindalco Industries Ltd., Norsk Hydro ASA, Gulf Extrusions Co. LLC, Bahrain Aluminum Extrusion Company, Alupco, Constellium N.V., Kaiser Aluminum, and QALEX, which are known for their strong market presence and advanced manufacturing capabilities across various industrial sectors. These companies are expanding operations to meet regional demand and innovation needs.
Market Drivers
Automotive Industry Growth:
Aluminium extrusions are gaining significant traction in the automotive industry, primarily due to their role in lightweighting. Reducing vehicle weight enhances fuel efficiency and overall vehicle performance, making aluminium a popular choice for car manufacturers. For instance, a survey by the Aluminum Association found that the average North American passenger vehicle contained about 27 pounds of aluminum extrusion in 2012. With the rising demand for electric vehicles (EVs), the need for lightweight, durable materials like aluminium is even more pronounced. As EV manufacturers strive to increase battery efficiency and vehicle range, the use of aluminium extrusions in vehicle components continues to grow, benefiting the industry’s transition to cleaner, more sustainable technologies.
Construction and Infrastructure Demand:
The construction industry is a key driver of the aluminium extrusion market. Aluminium is favored for its recyclability and energy efficiency, which makes it ideal for green buildings and sustainable construction projects. For example, the International Aluminium Institute (IAI) reports that aluminium is used in 80% to 90% of the components needed to produce an aircraft. The demand for environmentally conscious structures is pushing the use of aluminium extrusions in window frames, facades, and structural elements. Additionally, global infrastructure development, including both commercial and residential projects, continues to propel the market. Aluminium’s strength, corrosion resistance, and design flexibility are integral to meeting the demands of modern construction projects worldwide.
Aerospace and Consumer Goods:
In the aerospace industry, aluminium extrusions play a crucial role in reducing the weight of aircraft, improving fuel efficiency, and enhancing performance. Lightweight and high-strength aluminium alloys are essential for manufacturing key aircraft components. Similarly, aluminium is increasingly used in consumer goods such as electronics and furniture. In electronics, it is used in smartphones, laptops, and home appliances for its lightweight and aesthetic appeal. For furniture manufacturing, aluminium’s durability and versatility have led to its widespread adoption in creating modern, sleek designs.
Technological Advancements and Sustainability:
Technological innovations in extrusion processes have enabled the production of more complex and precise aluminium profiles, expanding the material’s range of applications across various industries. Aluminium’s high recyclability further enhances its appeal, making it an eco-friendly choice for manufacturers. With governments worldwide implementing regulations that promote energy efficiency and the use of sustainable materials, aluminium extrusions are positioned for continued growth, meeting both environmental and market demands.
Market Trends
Technological Advancements, Regional Trends, and Supply Chain Dynamics:
The aluminium extrusion industry is benefitting from advancements in extrusion techniques, including high-pressure die casting and direct extrusion methods. These technologies enable the production of more complex and precise aluminium profiles, expanding the material’s applications in various industries. Additionally, the adoption of digitalization, including 3D printing and simulation tools, is improving design, production, and quality control processes, enhancing efficiency and product quality. For instance, 3D printing technology is being used to produce complex extrusion dies, allowing for new design possibilities and reducing time and costs associated with traditional die-making. Regionally, the Asia-Pacific region is expected to dominate the global aluminium extrusion market due to rapid industrialization, urbanization, and infrastructure development, while North America and Europe, though mature markets, continue to see growth driven by the demand for energy-efficient and sustainable products. On the supply side, fluctuating raw material costs, particularly aluminium prices, are a significant challenge that can impact profitability. Additionally, global supply chain disruptions, such as those caused by the COVID-19 pandemic, can affect the availability of raw materials and components. However, these challenges present opportunities for innovation, prompting the development of new alloys, more efficient production methods, and alternative supply chains that can help mitigate supply chain risks and further improve the overall aluminium extrusion market landscape.
Lightweighting, Sustainability, and Emerging Applications:
The growing emphasis on lightweighting and sustainability is a major driver for aluminium extrusions across multiple industries. In the automotive sector, the push for fuel efficiency and reduced emissions has led to increased demand for lightweight aluminium components. For instance, replacing 2 kg of traditional materials with 1 kg of aluminium results in significant weight savings, enhancing overall vehicle efficiency. These extrusions play a critical role in vehicle design, where reducing weight directly contributes to enhanced fuel economy. In the construction industry, aluminium is being embraced for green building applications due to its recyclability, durability, and energy efficiency. Aluminium extrusions are commonly used in window frames, facades, and structural components for sustainable construction. The aerospace sector continues to heavily rely on aluminium extrusions for their high strength-to-weight ratio, which improves performance and reduces fuel consumption in aircraft. Moreover, the renewable energy sector has seen a rise in the use of aluminium extrusions, particularly in solar panels and wind turbines, owing to the material's durability and resistance to environmental elements. In electronics, the demand for lightweight yet durable devices has further accelerated the adoption of aluminium extrusions in smartphones, laptops, and other gadgets. These trends indicate that aluminium extrusions will continue to thrive in both established and emerging sectors.
Market Challenges Analysis
Raw Material Price Volatility and Energy Costs:
One of the significant challenges faced by aluminium extrusion manufacturers is raw material price volatility. The price of aluminium, which is crucial to the production process, can fluctuate considerably due to various factors such as global economic conditions, geopolitical tensions, and supply chain disruptions. These price changes create uncertainty in production costs, complicating manufacturers' efforts to plan and budget effectively. Additionally, aluminium extrusion is an energy-intensive process, and the rising cost of energy is another major challenge for manufacturers. Energy costs directly impact production costs, and the pressure to reduce energy consumption is intensifying. Manufacturers are increasingly focused on implementing energy-efficient technologies to mitigate the impact of higher energy costs, but this comes with the need for significant investment in new systems and processes. The combination of raw material price instability and escalating energy prices adds financial pressure on manufacturers, making it difficult to maintain profit margins and control production expenses.
Supply Chain Disruptions, Labor Shortages, and Environmental Regulations:
Global supply chain disruptions, such as those triggered by the COVID-19 pandemic, pose another significant challenge for the aluminium extrusion industry. These disruptions affect the timely availability of raw materials and components, resulting in production delays, increased costs, and potential loss of business. For example, the global aluminium industry has faced significant supply chain disruptions since 2020, leading to increased costs and longer lead times. Manufacturers are also grappling with labor shortages, particularly in skilled labor, which is necessary for machine operation, quality control, and maintenance. The high demand for skilled workers makes it difficult to attract and retain talent, further adding to the strain on production efficiency. In addition, the growing emphasis on environmental responsibility has led to stricter environmental regulations, forcing manufacturers to invest in pollution control systems and adopt sustainable practices. Compliance with these regulations increases operational costs and necessitates significant adjustments to production processes. To address these challenges, manufacturers need to focus on diversification, innovation, and cost optimization while ensuring sustainable practices and improving supply chain resilience.
Market Segmentation Analysis:
By Product:
The aluminium extrusion market is segmented by product type, each serving distinct industries and applications. Automotive chassis, profiles for poles, and profiles for bridges are crucial for enhancing the strength, lightweight nature, and durability of structural elements in transportation and infrastructure. Profiles for rail tracks, door and window profiles, and curtain walls are essential components in the construction industry, offering aesthetic appeal, energy efficiency, and weather resistance. Additionally, profiles for heat exchangers and machinery components play a vital role in sectors like energy and manufacturing by improving operational efficiency. Other products in the aluminium extrusion segment cater to diverse industries, contributing to lightweight, corrosion-resistant, and high-strength material solutions. The continuous demand for high-performance and sustainable materials drives the growth of these product types, with applications spanning across automotive, construction, aerospace, and more.
By End-User:
Aluminium extrusions are widely used across multiple end-user industries, driven by their lightweight, durable, and sustainable properties. In aerospace, they are vital for creating high-strength, low-weight components that enhance fuel efficiency and performance. The building and construction sector benefits from aluminium extrusions for structural components, windows, and facades, aligning with the growing demand for energy-efficient and green buildings. Railways and seaways also utilize extrusions for transportation infrastructure, ensuring durability and corrosion resistance. The energy sector leverages aluminium extrusions in solar panels and wind turbines, contributing to renewable energy generation. Additionally, the defense industry relies on these materials for various military applications, demanding precision and high-performance capabilities. As industries focus on sustainability, energy efficiency, and performance, aluminium extrusions continue to be a preferred material in numerous sectors, with innovations and technologies further expanding their potential.
Segments:
Based on Product:
- Automotive Chassis
- Profile for Poles
- Profile for Bridges
- Profile for Rail Tracks
- Door & Window Profiles
- Curtain Walls
- Profile for Heat Exchangers
- Machinery Components
- Others
Based on End-User:
- Aerospace
- Building & Construction
- Railways & Seaways
- Energy
- Defense
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
The aluminium extrusion market is seeing robust growth, with the Asia-Pacific region holding the largest market share, accounting for over 40% of global demand. This region is driven by rapid industrialization, urbanization, and significant investments in infrastructure projects, particularly in China and India. The demand for lightweight, durable, and cost-effective materials in automotive, construction, and energy sectors continues to grow, driving the adoption of aluminium extrusions. Additionally, government initiatives supporting the use of sustainable materials and the push for green buildings and renewable energy projects have further propelled market expansion in the region. As industrial growth continues, Asia-Pacific is expected to remain the dominant market for aluminium extrusion.
North America
In contrast, North America holds a substantial market share of approximately 25%, with the United States leading in demand. This growth is driven by ongoing infrastructure developments, particularly in the automotive, aerospace, and construction sectors. The growing focus on lightweighting in vehicles and energy-efficient buildings fuels the demand for aluminium extrusions in the region. Moreover, technological advancements and the shift toward renewable energy, including solar and wind power, are expected to further enhance the market’s growth. North America continues to witness innovations in extrusion technologies, making the region a key player in the global aluminium extrusion market.
Key Player Analysis
- Arconic Corp.
- Hindalco Industries Ltd.
- Norsk Hydro ASA
- Gulf Extrusions Co. LLC
- Bahrain Aluminum Extrusion Company
- Alupco
- Constellium N.V.
- Kaiser Aluminum
- QALEX
Competitive Analysis
The aluminium extrusion market is highly competitive, with key players such as Arconic Corp., Hindalco Industries Ltd., Norsk Hydro ASA, Gulf Extrusions Co. LLC, Bahrain Aluminum Extrusion Company, Alupco, Constellium N.V., Kaiser Aluminum, and QALEX holding significant market share. These companies leverage advanced technologies, strong distribution networks, and robust manufacturing capabilities to meet the increasing demand for lightweight materials across industries like automotive, construction, aerospace, and energy. Leading players are investing in innovation to improve product quality, expand production capacity, and reduce environmental impact through sustainable practices. Intense competition in terms of pricing, product differentiation, and regional expansion is prevalent, pushing these companies to adapt to changing market dynamics. Strategic collaborations, mergers, and acquisitions are key strategies being used to strengthen their market position and meet the growing demand for high-performance aluminium extrusions in various applications.
Recent Developments
- In April 2024, Norsk Hydro ASA (Hydro) invested USD 16.91 million in a new scrap sorting facility at the recycling plant in Wrexham, United Kingdom. Through this investment, the company expanded its product portfolio across the country.
- In March 2024, Daejoo Kores Co. Ltd announced plans to construct a new manufacturing facility in Gimje-si, Jeollabuk-do, with an estimated investment of around USD 2 million. The upcoming plant in Gimje is set to specialize in the production of billets, which are a crucial raw material used in aluminum extrusion processes. This strategic expansion will enhance the company's supply chain capabilities by establishing an integrated system that encompasses billet production, extrusion, machining, and assembly, ensuring a reliable and consistent supply capacity.
- In September 2023, Hindalco Industries Ltd. and Metra SpA entered into a partnership agreement to build aluminum rail coaches in India. The Italian company would assist the Indian manufacturer with latest aluminum extrusion technologies for building railway coaches.
- In December 2022, Norsk Hydro ASA announced an agreement to acquire Hueck’s Aluminum in Germany. The Norway-based market leader has acquired the German aluminum extrusion and window, façade, and door system manufacturer to expand its business portfolio across Europe. This acquisition will enhance Norsk’s stake in the German market and enable both businesses to grow simultaneously.
Market Concentration & Characteristics
The aluminium extrusion market is characterized by moderate to high concentration, with a few large players dominating the global landscape, while numerous smaller manufacturers cater to regional needs. Major players like Arconic Corp., Norsk Hydro ASA, and Hindalco Industries Ltd. command significant market share, benefiting from economies of scale and advanced technological capabilities. The market is also marked by diverse applications, spanning industries such as automotive, aerospace, construction, and energy. Aluminium extrusions are valued for their lightweight, durable, and recyclable properties, making them essential for modern manufacturing. While the industry is competitive, barriers to entry exist due to high capital investment requirements and the need for specialized technology. Key trends driving market dynamics include demand for sustainable products, lightweight solutions, and innovation in extrusion processes. The market is also shaped by regional variations in demand, with Asia-Pacific, North America, and Europe being prominent contributors.
Report Coverage
The research report offers an in-depth analysis based on Product, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for aluminium extrusion is expected to increase as industries focus on lightweight and durable materials for fuel efficiency.
- Rising investments in electric vehicle (EV) manufacturing will drive demand for aluminium extrusions in automotive applications.
- The construction of green buildings will promote the use of aluminium extrusions due to their energy efficiency and recyclability.
- Technological advancements in extrusion processes will enable the production of more complex and precise aluminium profiles.
- The aerospace sector will continue to rely on aluminium extrusions for weight reduction and improved fuel efficiency in aircraft.
- Aluminium extrusions will play a significant role in the growing renewable energy market, especially in solar and wind energy applications.
- The increasing emphasis on sustainability will drive the use of aluminium due to its recyclability and low environmental impact.
- Growth in infrastructure development across emerging economies will contribute to increased demand for aluminium extrusions in construction projects.
- Rising energy costs may prompt manufacturers to invest in energy-efficient extrusion technologies.
- Asia-Pacific will maintain dominance in the global aluminium extrusion market due to rapid industrialization and urbanization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aluminium Extrusion Market?
What factors are driving the growth of the Aluminium Extrusion Market?
What are the key segments within the Aluminium Extrusion Market?
What are some challenges faced by the Aluminium Extrusion Market?
Who are the major players in the Aluminium Extrusion Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aluminium Extrusion Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aluminium Extrusion Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 83,945 million → 2032: USD 160,040 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aluminium Extrusion Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aluminium Extrusion Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aluminium Extrusion Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aluminium Extrusion Market Drivers
- 3.3 Aluminium Extrusion Market Restraints & Challenges
- 3.4 Aluminium Extrusion Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aluminium Extrusion Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aluminium Extrusion Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aluminium Extrusion category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aluminium Extrusion Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aluminium Extrusion Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aluminium Extrusion market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aluminium Extrusion Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aluminium Extrusion Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aluminium Extrusion Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aluminium Extrusion (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aluminium Extrusion Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aluminium Extrusion Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aluminium Extrusion Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aluminium Extrusion Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aluminium Extrusion Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aluminium Extrusion Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aluminium Extrusion Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aluminium Extrusion Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aluminium Extrusion Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
