
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Port Infrastructure Market Size 2023 | USD 164,496.528 Million |
| Port Infrastructure Market, CAGR | 5.84% |
| Port Infrastructure Market Size 2032 | USD 278,327.52 Million |
Market Overview
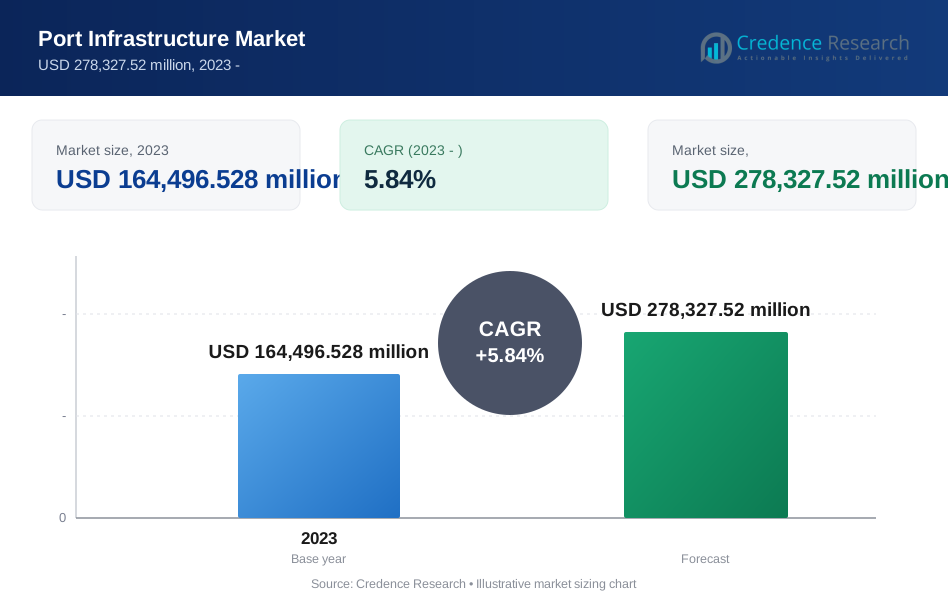
The Port Infrastructure Market is projected to grow from USD 164,496.528 million in 2023 to USD 278,327.52 million by 2032, expanding at a compound annual growth rate (CAGR) of 5.84%.
The Port Infrastructure Market is experiencing significant growth driven by global trade expansion and the increasing demands of cargo volume management. As international trade corridors expand, there is a pressing need for modernized port facilities equipped with automated and efficient cargo handling systems. Additionally, trends towards green port initiatives that focus on sustainability and reducing environmental impact are shaping developments within the industry. Governments and private sector investments in port infrastructure improvements and expansions are further bolstering market growth. These investments are crucial for accommodating larger vessels and enhancing port operational efficiencies, directly impacting global trade dynamics.
The Port Infrastructure Market is witnessing robust growth across key regions, with Asia-Pacific leading due to rapid industrialization and expanding trade activities in countries like China and India. North America and Europe also show significant activity, supported by strong regulatory frameworks and advanced technological integration in port operations. Key players influencing this market include major infrastructure giants like Essar Ports Ltd., Adani Ports and SEZ, which are deeply involved in the development and expansion of port facilities worldwide. These companies are pivotal in driving innovation and efficiency in port infrastructure to accommodate the escalating scale and complexity of global maritime trade.
Market Drivers
Accelerating Global Trade and Infrastructure Needs
As international trade volumes grow, the demand for more capable port facilities that can efficiently manage increased cargo volumes is critical. This growth necessitates not only the expansion of existing ports but also the modernization of facilities to streamline the movement of goods globally. Such enhancements include upgrading docking facilities and storage areas to accommodate the larger cargo ships that are becoming the standard in maritime transport, ensuring ports can effectively support the escalating flow of global commerce. For instance, more than 80 percent of global merchandise trade (by volume) is transported via sea routes.
Advancements in Port Automation and Efficiency
To keep pace with the demands of modern commerce, ports are increasingly turning to automation technologies. Investments in advanced container handling cranes, automated stacking systems, and sophisticated cargo tracking software are becoming prevalent. These technologies enhance the efficiency of port operations, significantly reduce cargo handling times, and minimize human error, leading to faster turnaround times and increased throughput. For instance, automated ports are safer than conventional ones. The number of human-related disruptions falls, and performance becomes more predictable.
Government Leadership in Port Development
Recognizing the strategic importance of port infrastructure to national and regional economic growth, governments worldwide are actively investing in port development projects. These initiatives include the expansion of current port facilities, construction of new ports, and integration of cutting-edge technologies to foster efficient and secure trade corridors. Such governmental support is crucial for enhancing trade capacities and improving the economic competitiveness of nations, thereby facilitating smoother and more effective integration into the global trading system. For instance, the Indian Maritime sector has seen significant growth with 2 ports (JNPT - 33, Mundra - 37) in the top 40 container ports. About 54% of total Indian cargo is handled at 12 Major Ports.
Specialization and Sustainability in Port Expansion
The rising global demand for Liquefied Natural Gas (LNG) has specifically spurred the development of specialized LNG port facilities, which require unique storage and handling capabilities to ensure safety and efficiency. Additionally, environmental sustainability is becoming a central focus in port infrastructure development. Ports are investing in green technologies such as shore power systems that allow docked ships to operate without running diesel engines, the use of renewable energy sources, and sustainable waste management practices. These efforts not only minimize the environmental impact of port operations but also align with global sustainability goals and regulatory requirements, further shaping the future landscape of port infrastructure development.
Market Trends
Technological Innovation and Intermodal Connectivity in Port Infrastructure
Ports are rapidly adopting smart technologies to improve operational efficiency and enhance security. The implementation of AI-powered systems for traffic management, automated container terminals, and real-time cargo tracking are integral components of developing "smart ports". For instance, key components of the smart port include smart infrastructure, smart traffic flows, and smart logistics. The smart infrastructure aims to increase productivity and utilization of digital technology, essential for automatic port operations.
There is a strong emphasis on intermodal connectivity, facilitating seamless integration between ports, railways, and roadways. The development of intermodal transportation hubs is crucial for optimizing logistics networks. For example, a port container yard is a major form of intermodal connectivity by allowing containers to be transloaded between maritime transportation, trucks, or rail (on-dock rail terminal).
Specialization, Cybersecurity, and Sustainability Focus in Ports
The port infrastructure market is witnessing a trend towards the construction of megaports and specialized facilities. Megaports, designed to handle ultra-large container vessels, and ports specializing in specific types of cargo such as LNG, bulk cargo, or automobiles, are becoming more prevalent. For instance, the government of India has planned six megaports under the Sagarmala project.
Alongside physical infrastructure developments, there is an increasing focus on cybersecurity due to the heightened reliance on digital technologies. Ports are investing in robust cybersecurity measures to safeguard operations against cyber threats. For example, a study of port cyberattacks from 2011 to 2023 revealed that weaknesses in cybersecurity procedures and a lack of awareness among staff members emerged as significant contributors to cyber vulnerabilities.
Furthermore, sustainability initiatives are gaining momentum, with ports investing in green building materials, renewable energy sources, and clean cargo handling technologies to minimize environmental impact and adhere to global sustainability standards. For instance, the World Ports Sustainability Program aims to demonstrate global leadership of ports in contributing to the Sustainable Development Goals of the United Nations. These efforts are complemented by Public-Private Partnerships (PPPs), where governments and private entities collaborate to leverage private expertise and funding, accelerating the development and modernization of port infrastructure while ensuring economic and environmental goals are met efficiently. For example, the PPP model has enabled managing port operations and new port infrastructure development that was exclusively the functions of the government in India.
Market Challenges Analysis
Financial Challenges in Port Infrastructure Development
The construction and maintenance of modern port infrastructure entail substantial financial outlays, including the costs associated with dredging harbors to accommodate increasingly large ships, constructing new terminals, and integrating cutting-edge technologies. These significant expenditures can severely strain government budgets, particularly when balancing other fiscal responsibilities. Additionally, smaller ports often face financial neglect due to the high costs associated with such upgrades, limiting their capacity for growth and modernization. Compounding these financial burdens are funding gaps and intense competition for limited resources. Governments frequently find themselves in a position where they must compete with other critical infrastructure projects for funding. This competition can be particularly challenging when attempting to attract private sector investment, which is often deterred by the high upfront costs and long-term return on investment associated with port infrastructure projects.
Environmental and Operational Challenges in Expanding Port Capabilities
Ports face the dual challenge of expanding their capabilities while also addressing environmental concerns and sustainability pressures. Dredging and other expansion activities can have detrimental effects on marine ecosystems, and port operations are significant contributors to air and water pollution. Implementing sustainable practices to mitigate these impacts often requires additional investment, exacerbating financial strains and complicating development efforts. Moreover, geopolitical tensions and trade disruptions can further complicate the landscape for port investments. Trade wars, political disputes, and regional conflicts can disrupt global trade patterns, leading to unpredictable cargo volumes and creating investment uncertainties. On top of these challenges, the rapid pace of technological advancements means that port infrastructure can quickly become outdated, necessitating continual investments in modernization to accommodate new vessel types and cleaner technologies. Lastly, the effectiveness of these technologically advanced ports is contingent upon the availability of a skilled workforce; however, there is often a shortage of professionals trained in automation, technology maintenance, and data analysis, which can impede efficient port operations and delay the adoption of new technologies.
Market Segmentation Analysis:
By Port Type:
The Port Infrastructure Market is segmented into sea ports and inland ports, each catering to distinct types of cargo and operational environments. Sea ports, which are the primary hubs for international trade, handle a significant volume of global cargo and passenger traffic. These ports are critical for the import and export of goods on a large scale, including bulk and container shipments. Inland ports, located along rivers and canals, primarily facilitate the transportation of goods within a country or between neighboring countries. They play a vital role in reducing the congestion of sea ports and are crucial for efficient distribution networks, particularly in landlocked areas where access to sea ports is limited.
By Application:
The market is further segmented by application into passenger and cargo services. Passenger ports are designed to handle cruise ships and ferries, focusing on facilities such as terminals and amenities for travelers. Cargo ports, on the other hand, are equipped to manage the loading, unloading, and storage of goods for commercial transport. These ports are increasingly incorporating advanced technologies to improve handling efficiency and capacity, essential for supporting the growing demands of global trade and commerce. Each segment requires specialized infrastructure to accommodate the specific needs of its operations, influencing the strategies for development and investment within the port infrastructure sector.
Segments:
Based on Port Type:
- Sea
- Inland
Based on Application:
- Passenger
- Cargo
Based on Construction Type:
- Terminal
- Equipment
Based on Infrastructure:
- Container
- Energy
Based on Facility:
- Deep-water seaport
- Seaport
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the market, capturing an impressive 45% share. This region's dominance can be attributed to the presence of major global manufacturing hubs, coupled with the rapidly expanding economies of countries like China, India, and Southeast Asian nations. Robust trade activities and the need for efficient cargo handling have fueled substantial investments in port infrastructure across the region.
Europe
Europe ranks second, accounting for approximately 25% of the global market share. The region's well-established maritime trade routes and the presence of major ports, such as Rotterdam, Antwerp, and Hamburg, have necessitated continuous upgrades and expansions to meet the growing demand for efficient logistics. However, stringent environmental regulations and space constraints in mature markets pose challenges for further development.
Key Player Analysis
- CS Group
- Larsen & Toubro Ltd.
- Man Infraconstruction Ltd.
- Hyundai Engineering
- Colas, Essar Ports Ltd.
- Consolidated Engineering Construction Co
- Bechtel, and Danube Ports Network Company
- Adnani Ports and SEZ
- APM Terminal
- IQPC
Competitive Analysis
In the highly competitive Port Infrastructure Market, leading companies such as APM Terminal, Bechtel, and Adani Ports and SEZ stand out due to their extensive capabilities and global reach. APM Terminal excels in managing port operations with a strong focus on efficiency and technology-driven solutions, while Bechtel is renowned for its large-scale construction expertise, particularly in building robust port facilities. Adani Ports and SEZ is prominent in developing specialized economic zones and ports that enhance regional trade flows. Larsen & Toubro and Hyundai Engineering also contribute significantly to the market with their engineering prowess and infrastructure development capabilities. Companies like Essar Ports Ltd. and Man Infraconstruction Ltd. specialize in port development and maintenance, offering tailored solutions that cater to specific regional needs. Consolidated Engineering Construction Co and Danube Ports Network Company provide crucial services in port management and development, focusing on integrating innovative logistics solutions. These companies collectively drive the market through strategic expansions, technological advancements, and partnerships that address the evolving demands of global trade and port operations.
Recent Developments
In August 2022: Adani Ports Group signed a memorandum of understanding (MoU) with Adani Ports and special economic zone (SEZ) Ltd for strategic joint investments in end-to-end logistics infrastructure and solutions, which include rail, maritime services, port operations, digital services, an industrial zone, and the establishment of maritime academies in Tanzania.
In August 2022: APM Terminals, a subsidiary of Maersk, emerged as the successful bidder in the judicial auction for the acquisition of the isolated Estaleiro Atlantico Sul production unit located in the Port of Suape, Pernambuco, Brazil. The court in Ipojuca, Pernambuco, has officially confirmed APM Terminals as the winner, according to the terminal operator's announcement. This acquisition signifies APM Terminals' strategic expansion in the region and underscores its commitment to further developing its operations in the Port of Suape.
In August 2022: Essar group signed a USD 2.4 billion deal to sell certain ports and power infrastructure to ArcelorMittal Nippon Steel in one of the largest post-pandemic merger and acquisition deals in India.
Market Concentration & Characteristics
The Port Infrastructure Market exhibits a moderate to high level of market concentration, with several large engineering and construction firms dominating the landscape. These key players, including Bechtel, APM Terminals, and Adani Ports and SEZ, leverage their substantial engineering capabilities and extensive experience to undertake massive port infrastructure projects worldwide. These companies often secure large contracts due to their proven track records, comprehensive service offerings, and ability to manage complex, large-scale projects that smaller firms cannot easily execute. The market is characterized by significant barriers to entry, including high capital requirements and the need for advanced technological capabilities, which further consolidates its competitive environment. Additionally, strategic alliances and partnerships between companies are common, aimed at pooling expertise and resources to efficiently manage the logistical and regulatory challenges associated with developing new port facilities or upgrading existing ones. This strategic collaboration enables them to better serve the increasing demands of global trade and to adapt to evolving technological and environmental standards.
Report Coverage
The research report offers an in-depth analysis based on Port Type, Application, Construction Type, Infrastructure, Facility and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Expansion of existing ports and construction of new ports will accelerate to handle increasing global trade volumes.
- Investment in automation and smart technologies will enhance efficiency and security in port operations.
- Sustainable practices and green technologies will become more prevalent as ports aim to reduce environmental impact.
- Increased focus on intermodal connectivity to streamline cargo movement between ships, rail, and trucks.
- Development of specialized facilities for handling specific types of cargo, such as LNG and bulk commodities.
- Public-Private Partnerships (PPPs) will continue to grow as a key strategy for funding and developing port infrastructure projects.
- Adoption of advanced cybersecurity measures to protect against increasing digital threats in port operations.
- Expansion in emerging markets, particularly in Asia and Africa, where economic growth is driving demand for port development.
- Enhancement of passenger facilities to cater to the growth in cruise ship travel and ferry services.
- Implementation of adaptive infrastructure to manage the challenges posed by climate change and rising sea levels.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Accelerating Global Trade and Infrastructure Needs
The expansion of international trade corridors and rising cargo volumes are driving the need for modernized and expanded port facilities, enabling efficient handling of larger vessels and supporting the growing scale of global commerce.
Advancements in Port Automation and Efficiency
The adoption of automation technologies such as automated cranes, stacking systems, and cargo tracking software is enhancing operational efficiency, reducing turnaround times, and minimizing human error, making ports more competitive and capable of handling increased throughput.
Government Leadership and Investment
Governments worldwide are prioritizing port infrastructure development through direct investments, public-private partnerships, and regulatory support, recognizing ports as critical to economic growth and global trade integration.
Specialization and Sustainability Initiatives
The development of specialized facilities for LNG and bulk cargo, along with investments in green technologies and sustainable practices, is enabling ports to meet evolving cargo demands while aligning with environmental regulations and global sustainability goals.
Technological Innovation and Intermodal Connectivity
The integration of smart technologies, AI-powered systems, and enhanced intermodal connectivity between ports, rail, and road networks is optimizing logistics, improving security, and supporting seamless cargo movement across global supply chains.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Port Infrastructure Market?
What factors are driving the growth of the Port Infrastructure Market?
What are the key segments within the Port Infrastructure Market?
What are some challenges faced by the Port Infrastructure Market?
Who are the major players in the Port Infrastructure Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Facility
- 1.2.1 Deep-water seaport
- 1.2.2 Seaport
- 1.3 By Port Type
- 1.3.1 Sea
- 1.3.2 Inland
- 1.4 By Application
- 1.4.1 Passenger
- 1.4.2 Cargo
- 1.5 By Construction Type
- 1.5.1 Terminal
- 1.5.2 Equipment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 164,496.528 million → 2032: USD 278,327.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Port Infrastructure Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Port Infrastructure Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Port Infrastructure Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Port Infrastructure Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Port Infrastructure Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Port Infrastructure Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Port Infrastructure Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Port Infrastructure Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 164,496.528 million → 2032: USD 278,327.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Port Infrastructure Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Facility - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Deep-water seaport
- 12.3.7.2 Seaport
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Port Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sea
- 12.4.7.2 Inland
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger
- 12.5.7.2 Cargo
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Construction Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Terminal
- 12.6.7.2 Equipment
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Port Infrastructure End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Port Infrastructure Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Port Infrastructure Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Port Infrastructure Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 APM Terminals
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bechtel
- 18.4 Adani Ports and SEZ
- 18.5 Larsen & Toubro Ltd.
- 18.6 Hyundai Engineering
- 18.7 Essar Ports Ltd.
- 18.8 Man Infraconstruction Ltd.
- 18.9 Colas
- 18.10 Consolidated Engineering Construction Co
- 18.11 Danube Ports Network Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

