
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aluminum Forging Market Size 2024 | USD 23,935 Million |
| Aluminum Forging Market, CAGR | 6.9% |
| Aluminum Forging Market Size 2032 | USD 40,818.3 Million |
Market Overview:
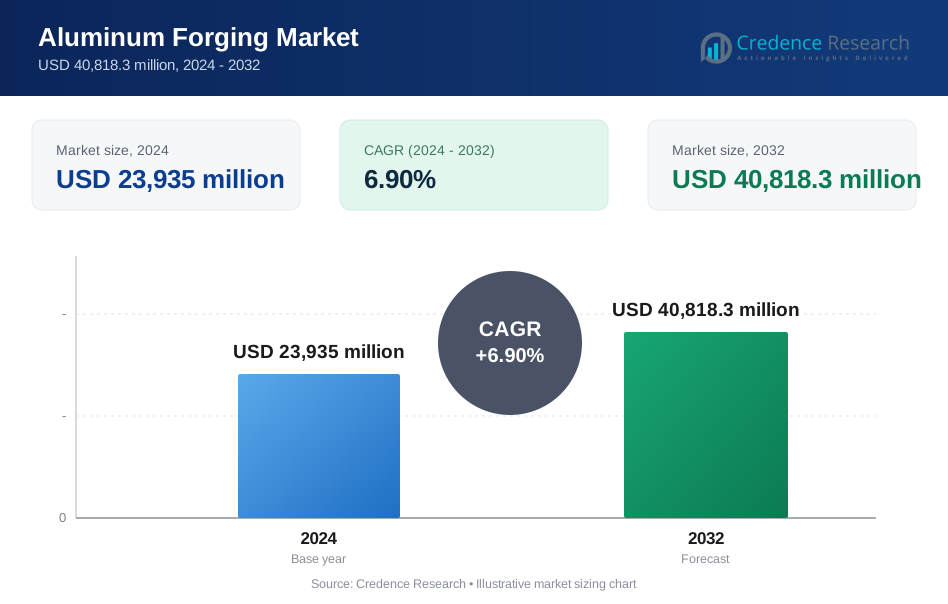
The Aluminum Forging Market is projected to grow from USD 23,935 million in 2024 to USD 40,818.3 million by 2032, registering a compound annual growth rate (CAGR) of 6.9% over the forecast period. This growth is driven by the increasing demand for lightweight, high-strength components across industries such as automotive, aerospace, defence, and industrial machinery. Aluminum forging offers significant advantages, including superior mechanical properties, enhanced corrosion resistance, and excellent strength-to-weight ratios, making it a preferred material for critical applications. The shift towards fuel efficiency and emission reduction further promotes the adoption of aluminum forging in transportation sectors, where weight reduction is crucial.
Key market drivers include the rising demand for lightweight materials in the automotive and aerospace industries to improve fuel efficiency and reduce emissions. Automakers are increasingly using aluminum-forged components to comply with stringent emission regulations and enhance vehicle performance. The growing adoption of electric vehicles (EVs) further accelerates demand for lightweight and durable aluminum forgings. In the aerospace sector, the need for high-performance, durable components propels the use of forged aluminum in aircraft manufacturing. Advancements in forging technologies, including precision forging and hybrid processes, are driving market growth by enabling complex component production with enhanced structural integrity.
Regionally, North America holds a significant market share, driven by robust demand from the automotive and aerospace sectors and a strong presence of key market players. Europe follows, supported by stringent environmental regulations, high automotive production, and the growing adoption of lightweight materials. The Asia-Pacific region is expected to witness the fastest growth, fueled by rapid industrialization, increasing automotive production, and strong demand for aluminum forgings in countries such as China, Japan, and India. Latin America and the Middle East & Africa present emerging growth opportunities due to expanding industrial and infrastructure activities and increasing focus on lightweight, energy-efficient materials.
Market Drivers:
Automotive Industry Transformation:
The automotive sector is driving significant growth in aluminum forging technologies, with manufacturers increasingly adopting lightweight materials to enhance fuel efficiency. For instance, according to the International Organization of Motor Vehicle Manufacturers (OICA), vehicle production in China reached 30.16 million units in 2023, representing a 12% increase from 2022. German automakers like BMW, Volkswagen, and Mercedes-Benz are actively incorporating aluminum forgings to manufacture lightweight, high-strength components. Ramkrishna Forgings Ltd is investing INR 575 million in a new aluminum forging facility focused on the electric vehicle segment, with an annual capacity of 3,000 tonnes, demonstrating the industry's commitment to vehicle lightweighting and performance optimization.
Aerospace and Defence Applications:
Aerospace and defence industries are experiencing remarkable demand for advanced aluminum forging technologies. The sector benefits from aluminum's superior properties, including lightweight characteristics, strength, and corrosion resistance. For instance, Critical aerospace components such as wings, fuselage frames, landing gear, and engine parts rely on precision-engineered aluminum forgings. ILJIN's strategic investment of USD 100 million in a new aluminum forging plant in Auburn, Alabama, highlights the industry's focus on developing specialized forging capabilities for high-performance aerospace and automotive applications.
Sustainability and Technological Innovation:
The aluminum forging market is witnessing significant advancements driven by sustainability and technological innovation. Aluminum's recyclability allows it to be reused multiple times without losing mechanical properties, making it an environmentally sustainable choice. The energy required to recycle aluminum is substantially lower compared to primary aluminum production, positioning it as a cost-effective and eco-friendly solution. For instance, Japan's electronics industry demonstrated remarkable growth, producing goods worth JPY 5,452.56 million from January to June 2024, representing a 104.7% increase compared to the previous year.
Global Market Expansion:
The aluminum forging market is experiencing robust growth across multiple regions, with Asia-Pacific emerging as the fastest-growing market. China's urbanization drive, targeting a 70% urban rate by 2030, is creating substantial demand for construction and infrastructure development. The electronics sector in the region is experiencing significant expansion, with forged aluminum parts enhancing component performance by reducing weight and energy consumption. These factors, combined with increasing investments in renewable energy infrastructure and electric vehicle manufacturing, are driving the global aluminum forging market's expansion.
Market Trends:
Advanced Manufacturing Technologies:
AI and machine learning are revolutionizing aluminum forging processes by optimizing material behaviour and predictive maintenance. Cast & Alloys reports emerging innovations in precision forging techniques that enable near-net-shape manufacturing with minimal material waste. Machina Labs has developed robotic forging technologies that can reduce production times from months to days, utilizing advanced AI-driven systems for complex component manufacturing. These technological advancements allow for uninterrupted 24/7 operations, maximizing productivity and enhancing overall manufacturing efficiency through sophisticated robotic and computational approaches.
Sustainable Recycling Innovations:
Aluminum recycling technologies are experiencing significant breakthroughs, with researchers developing solid-state recycling processes that can reduce energy demand by up to 90%. Recycling aluminum saves approximately 95% of the energy required for primary production, generating greenhouse gas emissions of just 5% compared to traditional manufacturing methods. For instance, Innovative techniques like accumulative roll bonding (ARB) and cold pressing are emerging as environmentally friendly alternatives, with some processes emitting as low as 0.003 kg CO2 equivalent during manufacturing. The development of unialloys and expanded alloy specifications is enabling more efficient recycling of diverse aluminum scrap materials.
Digital Twin and Simulation Technologies:
The emergence of digital twin technologies is transforming aluminum forging capabilities. For instance, Researchers at the UK's Advanced Forming Research Centre are developing digital twin models that can predict microstructure changes, residual stress generation, and component distortion throughout the entire forging process. These virtual representations enable manufacturers to simulate real-world conditions, proactively identify potential bottlenecks, and optimize energy utilization. The technology promises to reduce asset downtime, improve productivity, and increase market agility through comprehensive process simulation and optimization.
Global Industry Adaptation:
The aluminum forging industry is witnessing significant regional transformations, with Asia-Pacific emerging as a critical market. For instance, China's automotive production reached 30.16 million units in 2023, representing a 12% increase from 2022. The United States continues to lead in advanced manufacturing, with companies like Bharat Forge expanding their global manufacturing capabilities. Emerging technologies are focusing on developing lightweight, high-performance aluminum alloys for critical applications in automotive, aerospace, and industrial sectors, demonstrating the industry's commitment to innovation and technological advancement.
Market Challenges Analysis:
High Costs of Production and Raw Material Fluctuations:
The Aluminum Forging Market faces significant challenges due to the high costs associated with aluminum forging processes and raw material price volatility. The production of high-quality aluminum-forged components requires substantial investments in specialized equipment, skilled labor, and energy, driving up overall production costs. Fluctuations in the price of aluminum, driven by supply chain disruptions and global demand dynamics, further create uncertainty and pressure on profit margins for manufacturers.
Regulatory Compliance and Environmental Constraints:
Stringent environmental regulations imposed by government authorities such as the U.S. Environmental Protection Agency (EPA) and the European Union’s (EU) environmental directives present additional challenges for market participants. Compliance with regulations governing emissions, waste management, and energy consumption often requires the adoption of cleaner, energy-efficient technologies and practices, which can be costly and complex to implement. These regulatory requirements, while necessary for sustainability, can impact the competitiveness of smaller market players with limited resources.
Technological Complexity and Skill Shortages:
The aluminum forging process involves intricate techniques, such as precision forging and hybrid manufacturing processes, to achieve complex geometries and high-strength components. These technologies demand skilled labor and expertise, which may not always be readily available. Skill shortages in specialized areas, such as toolmaking and process optimization, present challenges in maintaining consistent product quality and operational efficiency.
Competition from Alternative Materials:
The market faces competition from alternative lightweight materials, such as high-strength steel composites and carbon fiber-reinforced plastics, which offer similar strength and weight reduction benefits. Automotive and aerospace manufacturers continuously explore material alternatives that offer cost savings and performance enhancements, potentially impacting the demand for aluminum forgings.
Supply Chain Disruptions:
Global supply chain disruptions, driven by geopolitical tensions and trade policies, can affect the availability of aluminum and related inputs, creating additional challenges for manufacturers. Ensuring a stable supply of high-quality raw materials remains critical for maintaining consistent production and meeting customer demands.
Market Segmentation Analysis:
By Type, the market is divided into open-die forging, closed-die forging, and rolled-ring forging. Closed-die forging holds a significant share due to its ability to produce high-precision and complex components with superior mechanical properties, making it suitable for automotive, aerospace, and industrial applications. Open-die forging is favored for large, custom components requiring high strength, while rolled-ring forging is used extensively in applications requiring high durability and seamless rings, such as in power generation and heavy machinery.
By Technology, the market is categorized into conventional forging and precision forging. Precision forging is gaining traction due to its ability to produce high-quality, near-net-shape components with minimal material waste and improved structural integrity. This technology is particularly advantageous in producing automotive and aerospace components where weight reduction and dimensional accuracy are critical. Conventional forging remains relevant for producing standard components in industrial and construction applications.
By End User, the market serves sectors such as automotive, aerospace, defense, industrial machinery, and construction. The automotive sector leads due to the growing adoption of lightweight, high-strength aluminum components to improve fuel efficiency and meet stringent emission regulations. The aerospace sector follows, driven by the demand for high-performance, durable components in aircraft manufacturing. The industrial machinery and construction sectors also contribute significantly to market growth, leveraging aluminum forgings for durable and cost-effective solutions.
Segmentations:
By Forging Type
- Open Die
- Closed Die
- Ring Rolled
By End-use Industry
- Aerospace and Defence
- Automotive & Transportation
- Industrial Machinery
- Construction
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America region holds a substantial share of the Aluminum Forging Market, accounting for approximately 30% of the global market. This dominance is driven by strong demand from the automotive and aerospace sectors, which prioritize lightweight, high-strength materials to improve fuel efficiency and meet stringent emission standards. The United States leads the region, supported by robust manufacturing capabilities, technological advancements in forging processes, and significant investments in electric vehicles (EVs) and aerospace innovations. North America’s focus on sustainability and energy efficiency further boosts the demand for aluminum forgings across various applications.
Europe represents around 25% of the market share, supported by a strong automotive industry, stringent environmental regulations, and a commitment to reducing carbon emissions. Countries such as Germany, France, and the United Kingdom are at the forefront of adopting lightweight materials in automotive manufacturing to enhance vehicle performance and comply with emission norms. The aerospace and defence sectors also contribute significantly, utilizing forged aluminum components for high-performance, durable solutions. The European Union’s policies promoting the circular economy and resource efficiency drive demand for sustainable materials like aluminum forgings.
Asia-Pacific region accounts for approximately 35% of the market share and is expected to witness the fastest growth over the forecast period. Rapid industrialization, increasing automotive production, and growing demand for lightweight materials in countries such as China, Japan, and India are key growth drivers. China, in particular, stands out as a major market due to its expansive manufacturing capabilities, strong automotive sector, and emphasis on reducing vehicle weight for energy efficiency. Government initiatives promoting the adoption of electric vehicles and green technologies further accelerate market growth in the region.
Latin America and the Middle East & Africa collectively account for the remaining 10% of the market share. While these regions currently represent a smaller portion of the market, they offer emerging growth opportunities due to expanding industrial and infrastructure activities, increasing focus on energy-efficient solutions, and rising investments in manufacturing capabilities. In Latin America, countries like Brazil and Mexico are leading in terms of industrial development and automotive production. Meanwhile, the MEA region benefits from growing demand for durable materials in construction and infrastructure projects.
Key Player Analysis:
- Aichi Steel
- Alcoa Corporation
- Bharat Forge Limited
- Nippon Steel Corporation
- ThyssenKrupp AG
- Aluminum Precision Products
- American Handforge
- KITZ Corporation
- Ellwood Group Inc.
- Arconic Inc.
Competitive Analysis:
The Aluminum Forging Market is highly competitive, driven by major players such as Alcoa Corporation, Bharat Forge Limited, and ThyssenKrupp AG, who leverage advanced forging technologies and extensive industry expertise to meet the diverse needs of automotive, aerospace, and industrial sectors. These companies focus on innovation, precision forging, and the production of lightweight, high-strength components to maintain a competitive edge. Smaller and niche players contribute by offering specialized solutions and customized forgings tailored to specific applications. The market’s competitive landscape is shaped by continuous advancements in manufacturing processes, the adoption of sustainable practices, and increasing demand for lightweight materials in transportation and industrial applications. Strategic partnerships, technological innovations, and compliance with stringent environmental regulations are key strategies for market participants aiming to enhance their market positions and capitalize on the rising demand for efficient, durable, and high-performance aluminum forgings.
Recent Developments:
- In 2023 Alcoa Corporation announced plans to enhance its low-carbon aluminum offerings by investing in advanced smelting technologies. This initiative aims to reduce greenhouse gas emissions and meet the growing demand for sustainable aluminum products in automotive and aerospace sectors.
- In 2022 Bharat Forge Limited completed the acquisition of Sanghvi Forging and Engineering Ltd., expanding its product portfolio and strengthening its position in the high-end forging market. This strategic move enables Bharat Forge to cater to a broader range of industries, including oil and gas, power, and defence.
- In 2023 ThyssenKrupp AG introduced a new line of lightweight aluminum forged components designed for electric vehicles (EVs). These components aim to enhance vehicle efficiency and performance by reducing overall weight, aligning with the automotive industry's shift towards electrification.
- In 2024 Nippon Steel Corporation announced a significant investment in upgrading its aluminum forging facilities to incorporate state-of-the-art technologies. This upgrade is expected to improve production efficiency, product quality, and the company's ability to meet increasing global demand for high-performance forged aluminum parts.
Market Concentration & Characteristics:
The Aluminum Forging Market is moderately concentrated, with major players such as Alcoa Corporation, Bharat Forge Limited, and ThyssenKrupp AG leading through extensive industry expertise, advanced manufacturing capabilities, and robust global presence. The market is characterized by a focus on lightweight, high-strength components, driven by demand from automotive, aerospace, and industrial sectors seeking to improve efficiency and meet stringent environmental regulations. High barriers to entry, including the need for specialized equipment, skilled labor, and compliance with regulatory standards, favor established players while posing challenges for smaller firms. Technological innovation, such as precision forging and hybrid manufacturing processes, plays a critical role in maintaining competitive advantage and meeting evolving customer needs. Increasing demand for sustainable and energy-efficient solutions further shapes market dynamics, compelling participants to invest in clean technologies and resource optimization strategies to enhance their market standing.
Report Coverage:
The research report offers an in-depth analysis based on Forging Type, End-use Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will experience growth driven by increasing demand for lightweight, high-strength components across automotive and aerospace industries.
- Expansion of electric vehicles (EVs) will propel demand for forged aluminum components to enhance performance and reduce weight.
- Advancements in forging technology, including precision forging and hybrid processes, will enable production of complex, high-quality components.
- Growing focus on sustainability and carbon reduction will drive investments in low-carbon aluminum forging solutions.
- Strategic collaborations and partnerships between manufacturers and end-users will accelerate innovation and market penetration.
- Rising infrastructure development and industrial activities in emerging markets will create new growth opportunities for aluminum forging.
- Adoption of automation and digital technologies will improve production efficiency, consistency, and cost-effectiveness.
- Increasing regulatory requirements for emissions reduction will push manufacturers to adopt lightweight solutions, boosting demand for forged aluminum.
- Technological developments will enhance the recyclability of aluminum, aligning with circular economy initiatives and environmental goals.
- Intense competition from alternative lightweight materials, such as composites, will drive innovation and differentiation within the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automotive Industry Transformation
Automakers are increasingly adopting aluminum-forged components to reduce vehicle weight, improve fuel efficiency, and comply with stringent emission regulations. The shift toward electric vehicles further accelerates demand for lightweight, high-strength aluminum forgings.
Aerospace and Defence Applications
The aerospace and defence sectors require high-performance, durable components, and aluminum forging offers superior strength-to-weight ratios and corrosion resistance. Precision-engineered aluminum forgings are critical for aircraft structures, landing gear, and engine parts.
Sustainability and Technological Innovation
Aluminum's recyclability and advancements in forging technologies, such as precision and hybrid processes, support environmental goals and cost efficiency. The ability to recycle aluminum with minimal energy input makes it a preferred material for sustainable manufacturing.
Expansion in Asia-Pacific and Emerging Markets
Rapid industrialization, urbanization, and increasing automotive and infrastructure development in Asia-Pacific, especially China, Japan, and India, are driving significant demand for aluminum forgings. Government initiatives promoting electric vehicles and green technologies further boost market growth.
Advancements in Manufacturing Technologies
The adoption of AI, machine learning, and digital twin technologies in forging processes enables the production of complex, high-quality components with improved efficiency and reduced material waste, supporting the market's growth and competitiveness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aluminum Forging Market?
What factors are driving the growth of the Aluminum Forging Market?
What are some challenges faced by the Aluminum Forging Market?
Who are the major players in the Aluminum Forging Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Conventional Forging
- 1.2.2 Precision Forging
- 1.3 By Forging Type
- 1.3.1 Open Die
- 1.3.2 Closed Die
- 1.3.3 Ring Rolled
- 1.4 By End-use Industry
- 1.4.1 Aerospace and Defence
- 1.4.2 Automotive & Transportation
- 1.4.3 Industrial Machinery
- 1.4.4 Construction
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23,935 million → 2032: USD 40,818.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminum Forging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminum Forging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminum Forging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminum Forging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminum Forging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminum Forging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminum Forging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminum Forging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23,935 million → 2032: USD 40,818.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminum Forging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Conventional Forging
- 12.3.7.2 Precision Forging
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Forging Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Open Die
- 12.4.7.2 Closed Die
- 12.4.7.3 Ring Rolled
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aerospace and Defence
- 12.5.7.2 Automotive & Transportation
- 12.5.7.3 Industrial Machinery
- 12.5.7.4 Construction
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminum Forging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminum Forging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminum Forging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminum Forging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Alcoa Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bharat Forge Limited
- 18.4 ThyssenKrupp AG
- 18.5 Aichi Steel
- 18.6 Nippon Steel Corporation
- 18.7 Aluminum Precision Products
- 18.8 American Handforge
- 18.9 KITZ Corporation
- 18.10 Ellwood Group Inc.
- 18.11 Arconic Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

