
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Animal Feed Processing Equipment Market Size 2024 | USD 23,102.5 million |
| Animal Feed Processing Equipment Market, CAGR | 4.4% |
| Animal Feed Processing Equipment Market Size 2032 | USD 32,603.4 million |
Market Overview
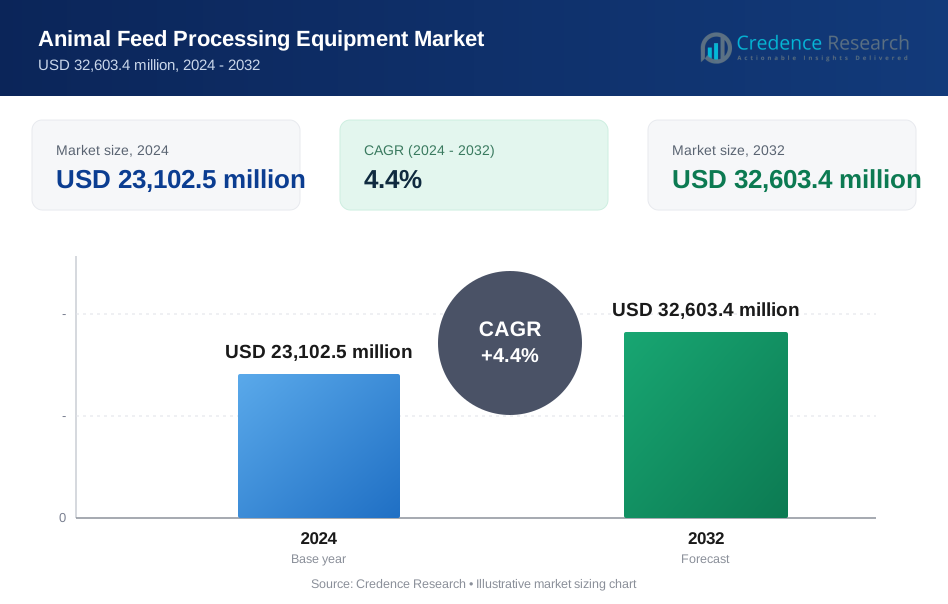
The Animal Feed Processing Equipment Market is projected to grow from USD 23,102.5 million in 2024 to an estimated USD 32,603.4 million by 2032, with a compound annual growth rate (CAGR) of 4.4% from 2024 to 2032.
Key drivers of the animal feed processing equipment market include the rising global demand for high-quality animal feed due to the growing population and increasing meat consumption. As livestock production intensifies to meet food security needs, the demand for advanced processing equipment is surging. Additionally, growing awareness about animal nutrition and the shift towards more sustainable and efficient feed production methods are further fueling market growth. Technological advancements in feed processing equipment, such as automation, improved mixing techniques, and the incorporation of AI-driven solutions, are boosting efficiency and productivity in feed manufacturing.
Regionally, North America and Europe dominate the animal feed processing equipment market due to their large-scale livestock industries and strong agricultural sectors. In particular, the United States and European countries have stringent regulations on animal feed quality and safety, driving the adoption of advanced equipment. In the Asia Pacific region, the demand for animal feed processing equipment is expanding rapidly, particularly in countries like China and India, where industrialization in livestock farming is accelerating. Latin America and the Middle East & Africa regions are also witnessing growth as their agricultural sectors modernize and expand to meet rising food demand, contributing to the market’s global expansion.
Market Insights
- The Animal Feed Processing Equipment Market is projected to grow from USD 23,102.5 million in 2024 to USD 32,603.4 million by 2032, at a CAGR of 4.4%.
- Increasing global demand for high-quality animal feed due to growing meat consumption and the need for sustainable feed production are key growth drivers.
- Automation, AI-driven solutions, and improved feed mixing techniques are enhancing productivity and efficiency in feed processing.
- High initial investment costs for advanced equipment and fluctuating raw material prices can hinder market growth.
- North America and Europe lead the market, driven by strong agricultural sectors and strict regulations on animal feed quality.
- Rapid industrialization in countries like China and India is significantly driving the demand for feed processing equipment in the region.
- Latin America and the Middle East & Africa are expanding their agricultural industries, boosting the adoption of feed processing equipment
Market Drivers
Rising Global Demand for Animal Protein
The global demand for animal protein continues to rise, primarily driven by increasing populations and evolving dietary patterns. This surge in demand for meat and dairy products is directly driving the need for more efficient feed production systems. Governments in key agricultural markets are responding by investing in technologies that support higher livestock production. For instance, the World Bank reported that meat consumption in Asia is expected to double by 2030, with China being the largest consumer, followed by India. In response to this, China’s government allocated over $13 billion in agricultural modernization in 2023, focusing on livestock production and feed efficiency. These investments are aimed at modernizing agricultural practices and increasing feed production efficiency to meet the growing demand.
Technological Advancements in Feed Processing Equipment
The development of new technologies in feed processing equipment, such as automation, AI, and IoT, has revolutionized the industry by enhancing productivity and reducing costs. Automation and AI-driven systems are helping manufacturers optimize production processes and improve feed consistency. These technologies also enable the use of real-time data to manage feed quality, monitor nutritional inputs, and reduce waste, which significantly improves efficiency. For instance, the European Commission's Horizon 2020 program has allocated €100 million to fund research in precision farming and the modernization of feed production systems in the EU. These initiatives show the critical role that technological advancements are playing in enhancing feed processing systems.
Increasing Focus on Sustainable and Efficient Feed Production
Sustainability has become a key factor driving changes in animal feed production. Governments around the world are implementing stricter environmental regulations on agricultural practices to reduce emissions and waste. As part of the Paris Agreement, many countries are setting ambitious targets to reduce emissions by 2030, including emissions from the agriculture sector, which accounts for a significant portion of global greenhouse gases. For instance, the European Union's Green Deal allocated €1 trillion in investments over the next decade to achieve carbon neutrality by 2050. This includes funding for sustainable farming practices, with a focus on reducing emissions in feed production.
Government Support and Investments in Agricultural Modernization
Governmental support and investments are critical drivers for the adoption of advanced feed processing technologies. With the global demand for food rising, many governments are prioritizing agricultural modernization through subsidies, grants, and investments aimed at improving feed production technologies. These initiatives are helping to increase the efficiency and sustainability of feed production systems, enabling companies to meet rising demand while minimizing environmental impact. For instance, the U.S. government, through the USDA, allocated $10 billion in 2023 to support agricultural innovations and the modernization of the food production system, including feed processing. This budget includes funding for feed efficiency projects and sustainable livestock farming practices. The Indian government’s National Mission for Sustainable Agriculture (NMSA) has also committed to investing $1.6 billion to support sustainable agricultural practices, including the development of eco-friendly feed production technologies.
Market Trends
Increasing Adoption of Automation and AI Technology
The adoption of automation and AI in feed processing is becoming a major trend, as it enhances efficiency, reduces human error, and minimizes production costs. Automation technologies enable real-time monitoring, ensuring consistent feed quality and optimized production processes. The integration of AI into feed manufacturing systems is helping manufacturers enhance productivity by predicting maintenance needs and adjusting production parameters dynamically. For instance, the Australian government to fund research on advanced manufacturing technologies, including automation and AI for sustainable agricultural practices, in 2022. The initiative is aimed at improving production efficiency and reducing operational costs across agriculture, including feed production systems. In addition, Canada's Natural Resources Agency has been investing in AI-powered feed processing projects as part of their sustainable agriculture initiatives, focusing on enhancing precision in feed quality and nutrient control.
Shift Toward Sustainable Feed Ingredients
Sustainability continues to be a key focus in feed production, with an increasing demand for alternative feed ingredients that reduce environmental impact. Insect proteins, algae-based feed, and other plant-based alternatives are gaining popularity due to their lower resource usage and potential to reduce the carbon footprint of animal agriculture. For instance, the U.S. Department of Agriculture (USDA) recently allocated $80 million to promote research and development in alternative feed ingredients such as algae and insect proteins. This investment aims to reduce the environmental impact of feed production by supporting the commercialization of sustainable alternatives.
Expansion of Feed Processing Equipment in Emerging Markets
The demand for advanced feed processing equipment is growing in emerging markets, particularly in Asia-Pacific, as industrialization and urbanization drive the need for more efficient livestock farming practices. Countries like China and India are investing heavily in their agricultural sectors to support the increasing demand for animal protein, which is driving the demand for advanced feed processing technologies. For instance, the Government of China, through the Ministry of Agriculture, has set aside $1 billion for agricultural modernization, including upgrading livestock feed production facilities. This investment is aimed at meeting the country’s growing demand for animal products while improving feed production efficiency.
Government Support for Agricultural Modernization
Governments across the globe are heavily investing in the modernization of their agricultural sectors, including the adoption of advanced feed processing technologies. These investments are designed to improve food security, reduce environmental impact, and support the transition to more sustainable agricultural practices. For instance, the United Kingdom’s Department for Environment, Food & Rural Affairs (DEFRA) to fund agricultural innovation, focusing on enhancing feed production systems. In Brazil, the Ministry of Agriculture’s Rural Development Program allocated $2 billion for technological advancements in livestock farming, including improving feed processing capabilities.
Market Challenges Analysis
Supply Chain and Raw Material Costs
One of the key challenges faced by the animal feed processing equipment market is the volatility in raw material costs and supply chain disruptions. The price of essential ingredients like grains, soy, and other feed additives has been rising due to climate change, global trade issues, and labor shortages. These fluctuations in supply chain costs can significantly impact feed production, affecting the demand for processing equipment. Manufacturers may face difficulties in forecasting costs and ensuring a consistent supply of raw materials, especially during unpredictable times like economic downturns or natural disasters. Similarly, disruptions in global shipping caused by the COVID-19 pandemic led to supply chain delays, further escalating costs. As feed manufacturers strive to manage these rising input costs, the demand for more cost-effective processing equipment is increasing, as producers seek to maintain profitability while dealing with unpredictable expenses.
Regulatory Compliance and Safety Standards
Another significant challenge in the market is the evolving regulatory landscape. Governments worldwide are increasingly focusing on ensuring animal feed safety, quality, and traceability, pushing manufacturers to adopt new equipment and technologies to comply with these standards. These regulations often vary by region and require substantial investments in upgrading or replacing older equipment to meet compliance requirements. Additionally, maintaining certifications for feed safety can add to operational complexity and costs for feed producers, especially in regions with stringent quality controls. Similarly, the U.S. Food and Drug Administration (FDA) has introduced stricter regulations on feed additives and their approval process, forcing manufacturers to invest in more precise processing systems to meet these guidelines. Compliance with these regulations is essential, but it poses challenges for smaller producers who may struggle with the capital investment required for modern equipment.
Market Opportunities
One of the key opportunities in the Animal Feed Processing Equipment Market lies in the ongoing advancements in technology, particularly automation and artificial intelligence. As the demand for higher efficiency and precision in feed production increases, the adoption of automated systems, including smart machines and AI-driven analytics, presents significant growth potential. These technologies can streamline processes such as mixing, pelletizing, and grinding, improving both the speed and quality of production. Automation also allows manufacturers to reduce operational costs, minimize human error, and optimize resource utilization, making feed production more sustainable and cost-effective. The integration of digital tools for monitoring, tracking, and managing production processes offers feed manufacturers real-time insights into performance and efficiency, further enhancing the overall value proposition of advanced feed processing equipment. With the rising trend of Industry 4.0 in agriculture, the market for technologically advanced equipment is expected to expand rapidly, especially in developed economies and larger agricultural regions.
The rapid industrialization and modernization of the agricultural sector in emerging markets, particularly in Asia Pacific, Latin America, and the Middle East & Africa, offer substantial growth opportunities for animal feed processing equipment. As these regions experience increased demand for animal protein due to rising populations and changing dietary patterns, the need for efficient feed production technologies becomes more pronounced. Governments in these regions are also supporting agricultural development through subsidies, policies, and investments in modern farming techniques. This creates a favorable environment for the expansion of feed processing equipment manufacturers, as they tap into new markets and cater to the rising demand for high-quality animal feed. Additionally, local players and international companies are investing in regional manufacturing facilities to cater to the unique needs of these markets, further enhancing growth prospects.
Market Segmentation Analysis
By type, the market is primarily divided into feed milling equipment, mixing equipment, pelleting equipment, grinding equipment, and others. Among these, pelleting equipment holds a significant share, as pelleted feed is widely used in livestock farming due to its nutritional benefits and easy handling. Mixing and grinding equipment also form a crucial part of the market, as efficient mixing and particle size reduction are vital for feed quality.
By technology, the market is categorized into automation, artificial intelligence (AI)-driven technologies, robotics, and traditional manual systems. Automation and AI are gaining traction, as they improve efficiency and reduce human errors in feed production. AI technologies, in particular, are used for monitoring feed quality and optimizing processes. The growing demand for efficiency and consistency in feed quality is pushing the adoption of these advanced technologies in feed processing.
By end-user, the market is segmented into livestock (including poultry, swine, cattle, and aquaculture) and pet food production. The livestock segment dominates the market due to the increasing global demand for meat and dairy products, which drives the need for large-scale feed production. Within the livestock segment, poultry feed processing equipment is the largest sub-segment, given the widespread consumption of poultry products globally. The pet food segment is also experiencing growth due to rising pet ownership and a shift toward higher-quality pet food products.
Segmentations
Based on Product Type:
- Feed Milling Equipment
- Mixing Equipment
- Pelleting Equipment
- Grinding Equipment
- Other Equipment
Based on Technology:
- Automation
- Artificial Intelligence (AI)-Driven Technologies
- Robotics
- Traditional Manual Systems
Based on End-User:
- Livestock (Poultry, Swine, Cattle, Aquaculture)
- Pet Food Production
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a substantial share of the Animal Feed Processing Equipment Market, primarily due to the high demand for meat and dairy products. The region's well-established livestock industry, coupled with the adoption of advanced feed processing technologies, has propelled market growth. The United States and Canada are the major contributors, with the U.S. leading the market due to its large-scale livestock farming and high investment in feed processing equipment. North America's market share is estimated to be around 30%.
Europe
Europe is another significant region in the Animal Feed Processing Equipment Market, accounting for 25% of the market share. The region's growth is driven by the increasing demand for high-quality animal feed, stringent regulations on animal nutrition, and the presence of key market players. Countries such as Germany, France, and the United Kingdom are the major contributors, with Germany leading the market due to its advanced feed processing technologies and high livestock population.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the Animal Feed Processing Equipment Market, with a market share of 35%. The region's growth is attributed to the increasing livestock population, rising demand for animal-based protein, and the adoption of modern feed processing technologies. China and India are the major contributors, with China leading the market due to its large-scale livestock farming and significant investment in feed processing equipment. The region's growth is further supported by the increasing awareness of animal nutrition and the expansion of the feed industry.
Key Player Analysis
- Bühler Group
- Andritz AG
- CPM Holdings, Inc.
- Satake Corporation
- Palsgaard A/S
- Muyang Group
- Amandus Kahl GmbH & Co. KG
- FAMSUN
- Wenger Manufacturing, Inc.
- Liyang Huasheng Machinery Co., Ltd.
Competitive Analysis
The animal feed processing equipment market is highly competitive, with numerous global and regional players striving to meet the growing demand for advanced and efficient feed production technologies. Key players in this market include companies such as Bühler Group, Andritz AG, CPM Holdings, Inc., and Satake Corporation, which are well-established in the industry with strong product portfolios covering various feed processing technologies, including milling, mixing, pelleting, and grinding equipment. These companies are focusing on innovation, leveraging automation, artificial intelligence, and robotics to enhance feed processing efficiency, reduce operational costs, and meet increasingly stringent regulatory requirements. Additionally, many of these market leaders are expanding their footprints in emerging markets, particularly in Asia-Pacific and Latin America, where the demand for modern livestock farming equipment is growing rapidly. Moreover, regional players are also gaining traction by offering customized solutions tailored to specific local needs, such as sustainable and cost-effective feed processing systems. For instance, companies in China and India are capitalizing on the shift towards industrialized farming to provide affordable and scalable feed processing equipment. Strategic partnerships, mergers, and acquisitions are common strategies among key players to expand market reach and improve their technological capabilities. Furthermore, government initiatives promoting agricultural modernization and sustainability are prompting major companies to invest heavily in R&D, leading to the development of new and improved feed processing solutions. Overall, the competition is intensifying as companies seek to strengthen their market positions and meet the evolving needs of the global animal feed industry.
Recent Developments
- June 2023: Aboitiz established feed mills in both China and Vietnam. Pilmico and Gold Coin have earmarked USD 51 million for their international feed mill expansions, specifically targeting Long An in Vietnam and Yunnan in China.
- November 2022: Bühler unveiled its Granulex® 5 series, a new hammer mill lineup featuring numerous innovations that collectively enhance performance. This pioneering modular system not only ensures top-notch product quality and safety standards but also delivers notable energy savings and flexibility
Market Concentration & Characteristics
The animal feed processing equipment market exhibits moderate concentration, with a mix of global and regional players dominating the landscape. A few large, well-established companies such as Bühler Group, Andritz AG, CPM Holdings, Inc., and Satake Corporation hold significant market shares due to their expansive product portfolios, technological advancements, and strong distribution networks. These key players primarily focus on innovation, offering high-tech solutions like automation, AI-driven technologies, and robotics to enhance efficiency and meet regulatory demands. However, the market also features several smaller, regional players that cater to local markets with specialized, cost-effective solutions, often targeting emerging economies in Asia-Pacific, Latin America, and Africa where there is increasing demand for affordable feed processing systems. The market is characterized by a high degree of technological innovation, as companies continuously invest in research and development to improve the efficiency, sustainability, and automation of feed production. Additionally, stringent regulations on feed safety and quality across various regions have led to increased demand for more advanced equipment that can meet these standards. The market’s growth is also driven by the expanding livestock industry, particularly in countries experiencing rapid industrialization, which fuels the need for modernized feed processing technologies. As a result, there is a trend toward greater consolidation within the industry, as larger companies acquire smaller players or form partnerships to enhance their technological capabilities, expand their geographical reach, and respond to shifting market demands. This dynamic fosters both competition and collaboration in the market.
Report Coverage
The research report offers an in-depth analysis based on product type, technology and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for animal feed processing equipment will continue to rise as global livestock production expands to meet the growing need for meat and other animal products.
- Technological innovations, such as AI, automation, and advanced mixing techniques, will play a central role in improving efficiency and reducing operational costs.
- Sustainability concerns will drive the adoption of more eco-friendly and efficient feed production methods, further pushing the development of advanced equipment.
- Increasing awareness of animal nutrition will lead to a demand for more precise and tailored feed processing solutions.
- Governments worldwide are expected to implement stricter regulations on feed safety and quality, creating a need for more advanced processing technologies.
- Asia-Pacific markets, particularly China and India, will see rapid growth due to industrialization in livestock farming and increasing demand for processed feed.
- Automation and digitalization will continue to reshape the market, enhancing the scalability and precision of feed processing operations.
- The rise of alternative feed ingredients, such as plant-based and insect proteins, will drive innovation in feed processing technology.
- Investments in agricultural modernization, particularly in emerging economies, will fuel the expansion of the animal feed processing equipment market.
- Collaborations between technology providers and agricultural companies will accelerate the adoption of next-generation feed processing systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Demand for Animal Protein
Increasing populations and evolving dietary patterns are driving up the demand for meat and dairy products, which in turn fuels the need for efficient and high-capacity animal feed processing equipment to support intensified livestock production.
Technological Advancements in Feed Processing Equipment
The integration of automation, AI, and IoT into feed processing equipment is enhancing productivity, reducing operational costs, and improving feed quality, making advanced equipment more attractive to producers seeking efficiency and compliance.
Focus on Sustainable and Efficient Feed Production
Stricter environmental regulations and the push for sustainability are prompting feed producers to adopt equipment that minimizes waste, reduces emissions, and supports the use of alternative, eco-friendly feed ingredients.
Government Support and Investments in Agricultural Modernization
Substantial government funding and policy initiatives aimed at modernizing agriculture are enabling producers to invest in advanced feed processing technologies, particularly in emerging markets where food security and livestock productivity are priorities.
Stringent Regulatory Compliance and Feed Safety Standards
Increasingly rigorous regulations on animal feed quality and safety, especially in North America and Europe, are compelling producers to upgrade to advanced processing equipment capable of meeting these standards and ensuring traceability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Animal Feed Processing Equipment Market?
What are the key drivers for the growth of the animal feed processing equipment market?
How is technological advancement influencing the market?
Why is there a growing demand for animal feed processing equipment?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Livestock (Poultry, Swine, Cattle, Aquaculture)
- 1.2.2 Pet Food Production
- 1.3 By Technology
- 1.3.1 Automation
- 1.3.2 Artificial Intelligence (AI)-Driven Technologies
- 1.3.3 Robotics
- 1.3.4 Traditional Manual Systems
- 1.4 By Product Type
- 1.4.1 Feed Milling Equipment
- 1.4.2 Mixing Equipment
- 1.4.3 Pelleting Equipment
- 1.4.4 Grinding Equipment
- 1.4.5 Other Equipment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23,102.5 million → 2032: USD 32,603.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Animal Feed Processing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Animal Feed Processing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Animal Feed Processing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Animal Feed Processing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Animal Feed Processing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Animal Feed Processing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Animal Feed Processing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Animal Feed Processing Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23,102.5 million → 2032: USD 32,603.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Animal Feed Processing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Livestock (Poultry, Swine, Cattle, Aquaculture)
- 12.3.7.2 Pet Food Production
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automation
- 12.4.7.2 Artificial Intelligence (AI)-Driven Technologies
- 12.4.7.3 Robotics
- 12.4.7.4 Traditional Manual Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Feed Milling Equipment
- 12.5.7.2 Mixing Equipment
- 12.5.7.3 Pelleting Equipment
- 12.5.7.4 Grinding Equipment
- 12.5.7.5 Other Equipment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Animal Feed Processing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Animal Feed Processing Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Animal Feed Processing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Animal Feed Processing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bühler Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Andritz AG
- 18.4 CPM Holdings, Inc.
- 18.5 Satake Corporation
- 18.6 Palsgaard A/S
- 18.7 Muyang Group
- 18.8 Amandus Kahl GmbH & Co. KG
- 18.9 FAMSUN
- 18.10 Wenger Manufacturing, Inc.
- 18.11 Liyang Huasheng Machinery Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
