
Animal Stem Cell Therapy Market Overview:
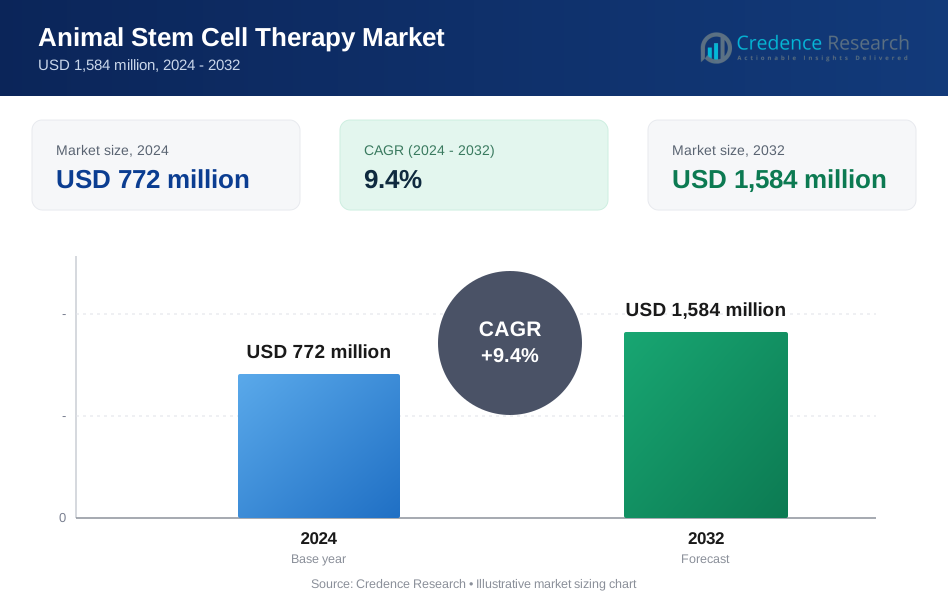
Animal Stem Cell Therapy Market size was valued USD 772 million in 2024 and is anticipated to reach USD 1584 million by 2032, at a CAGR of 9.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Animal Stem Cell Therapy Market Size 2024 | USD 772 million |
| Animal Stem Cell Therapy Market , CAGR | 9.4% |
| Animal Stem Cell Therapy Market Size 2032 | USD 1584 million |
Animal Stem Cell Therapy Market Insights
- A key market driver is the rising prevalence of orthopedic and degenerative conditions in companion and performance animals, supporting strong demand for mesenchymal stem cell (MSC) therapies as the dominant segment with over 60% share due to proven anti-inflammatory and regenerative benefits.
- Market trends indicate growing focus on allogeneic and off-the-shelf therapies, improved cell processing technologies, and closer integration of stem cell treatments with advanced veterinary diagnostics and specialty care.
- The competitive landscape is shaped by global biopharmaceutical companies and specialized biotech firms emphasizing scalable manufacturing, R&D partnerships, and collaborations with veterinary hospitals, while high treatment costs and regulatory complexity remain key restraints.
- Regionally, North America leads with an exact 39% market share, driven by advanced veterinary infrastructure, high pet healthcare spending, and early adoption of regenerative medicine solutions.

Animal Stem Cell Therapy Market Segmentation Analysis:
By Therapy Type
By therapy type, autologous cell therapy dominates the Animal Stem Cell Therapy Market, accounting for an estimated around 58% market share, driven by lower immunogenic risk, higher safety perception, and regulatory acceptance in veterinary practice. Autologous approaches, which use an animal’s own cells, are widely adopted in orthopedic, osteoarthritis, and soft tissue injury treatments, particularly in companion animals. Faster clinical adoption, reduced ethical concerns, and simplified regulatory pathways further support dominance. Allogeneic cell therapy is expanding steadily, supported by scalability, off-the-shelf availability, and growing commercialization of standardized veterinary biologics.
- For instance, Atara Biotherapeutics has demonstrated industry-leading expertise in cell-based platforms through its EBV-specific T-cell therapies, such as tabelecleucel (Ebvallo™). Its manufacturing processes are highly scalable, capable of producing over 1,000 doses from a single healthy donor.
By Cell Type
By cell type, stem cells represent the dominant segment with approximately 67% market share, driven by their regenerative capacity and broad therapeutic applicability. Within stem cells, mesenchymal stem cells (MSCs) lead due to their anti-inflammatory properties, tissue regeneration potential, and ease of isolation. MSCs are extensively used in musculoskeletal, joint, and inflammatory disease management in horses and companion animals. Hematopoietic stem cells (HSCs) and emerging iPSCs and ESCs show niche growth, while non-stem cells, including immune cells and fibroblasts, are gaining interest for immunotherapy and tissue repair applications.
- For instance, MEDIPOST’s proprietary SMUP-Cell® platform is built on allogeneic umbilical cord blood-derived MSCs that are expanded under GMP conditions to achieve over 1×10⁹ viable cells per master cell bank, with in-house data confirming >95% cell viability post-thaw and demonstrated secretion of anti-inflammatory cytokines such as TSG-6 at quantifiable nanogram-level concentrations, underscoring its technically advanced, scalable MSC manufacturing capabilities.
By Cell Source
By cell source, adipose tissue is the leading segment, holding an estimated 42% market share, driven by high cell yield, minimally invasive extraction, and cost efficiency. Adipose-derived cells are widely preferred in veterinary clinics for regenerative orthopedic treatments. Bone marrow remains a key source due to clinical familiarity and proven efficacy. Peripheral blood and umbilical cord blood are gaining traction for their ease of collection and regenerative potential, while placental tissue and engineered or genetically modified cells represent emerging areas supported by advances in veterinary biotechnology and precision regenerative medicine.
Animal Stem Cell Therapy Market Overview
Key Growth Drivers
- Rising Prevalence of Musculoskeletal and Degenerative Conditions in Animals The increasing incidence of osteoarthritis, ligament injuries, and degenerative joint disorders in companion and performance animals strongly drives demand for stem cell therapies. Aging pet populations and the growing use of animals in sports and working roles increase the need for regenerative solutions that address pain and mobility loss. Stem cell therapies offer tissue repair and anti-inflammatory benefits, positioning them as attractive alternatives to long-term pharmaceutical management. Veterinary professionals increasingly recommend these therapies to improve recovery outcomes and quality of life.
- For instance, Johnson & Johnson Services, Inc., through its Janssen and DePuy Synthes research platforms, has advanced cell and tissue–based regenerative science using high-density 3D cell culture systems exceeding 10⁷ cells per scaffold and bioreactor-controlled differentiation protocols operating at oxygen levels as low as 5% to mimic native joint environments.
- Growing Pet Humanization and Willingness to Spend on Advanced Care Pet owners increasingly view animals as family members, driving higher spending on advanced veterinary treatments. This shift supports adoption of innovative regenerative therapies, including stem cell-based interventions. Rising awareness of minimally invasive, long-lasting treatment options encourages demand, particularly in developed markets. Veterinary clinics respond by expanding regenerative medicine offerings, supported by improved diagnostic capabilities and treatment protocols. This behavioral shift among pet owners significantly accelerates market growth.
- For instance, S.BIOMEDICS has demonstrated its technological rigor through core platform development of high-purity cell populations where ventral midbrain-specific dopaminergic progenitor cells are produced under GMP conditions with targeted cell yields sufficient for clinical dosing in its TED-A9 program, and its 3D MSC spheroid platform (FECS-Ad) reliably generates spheroids containing over 500,000 MSCs per unit with maintained viability and paracrine factor secretion profiles per documented company pipelines, reflecting the company’s precision stem cell engineering capabilities directly relevant to advanced regenerative medicine expectations among pet owners.
- Advancements in Veterinary Regenerative Medicine and Cell Processing Technologies Continuous improvements in cell isolation, processing, and cryopreservation technologies strengthen the feasibility of stem cell therapies in veterinary practice. Standardized protocols and improved laboratory infrastructure enhance treatment consistency and safety. These advancements reduce turnaround times and improve clinical outcomes, enabling broader adoption across veterinary hospitals and specialty clinics. Expanding research in animal biotechnology further supports the development of next-generation regenerative therapies.
Key Trends & Opportunities
- Expansion of Allogeneic and Off-the-Shelf Cell Therapies The market is witnessing growing interest in allogeneic stem cell therapies due to their scalability and immediate availability. Off-the-shelf products reduce treatment delays and simplify logistics compared to autologous approaches. This trend creates opportunities for commercialization and wider clinic adoption, particularly in high-volume veterinary practices. Standardized allogeneic products also support consistent dosing and quality control, enhancing clinical confidence.
- For instance, JW Therapeutics has evaluated dose escalation cohorts at 25×10⁶, 50×10⁶, and 100×10⁶ CAR+ T cells for its dual-target CD19/CD20 CAR-T candidate JWCAR201, demonstrating scalable dose exploration consistent with clinical development strategies.
- Increasing Use of Stem Cell Therapy in Companion Animals Companion animals, especially dogs and horses, are emerging as key recipients of stem cell therapies. Applications extend beyond orthopedics into dermatology, neurology, and inflammatory conditions. Growing clinical evidence and positive treatment outcomes create opportunities for expanded indications. This trend supports market diversification and broader revenue streams for veterinary service providers.
- For instance, Thermo Fisher’s Gibco® Cell Therapy Systems (CTS™) portfolio includes devices such as the CTS Rotea™ Counterflow Centrifugation System, which can process up to 1 × 10⁹ cells per run for automated cell isolation, washing, and concentration without open-system steps, supporting consistent cell yields critical for clinical applications.
- Integration with Advanced Diagnostics and Personalized Veterinary Care The integration of stem cell therapies with advanced imaging, biomarker analysis, and personalized treatment planning represents a significant opportunity. Precision diagnostics enable better patient selection and outcome monitoring. Personalized regenerative protocols improve efficacy and strengthen clinician trust, supporting wider adoption across veterinary specialties.
Key Challenges
- High Treatment Costs and Limited Reimbursement The cost of stem cell therapies remains a major challenge, limiting accessibility for many pet owners. Cell harvesting, processing, and specialized laboratory services increase overall treatment expenses. Limited insurance coverage and reimbursement options further constrain adoption. Addressing cost barriers is essential for broader market penetration.
- Regulatory Complexity and Limited Standardization Regulatory uncertainty and varying guidelines across regions pose challenges for market participants. Inconsistent standards for cell sourcing, processing, and clinical use can hinder commercialization. Limited long-term clinical data in some applications also affects regulatory clarity. Establishing standardized frameworks and clearer regulatory pathways remains critical for sustainable market growth.
Regional Analysis
North America
North America leads the Animal Stem Cell Therapy Market with an estimated 39% market share, driven by advanced veterinary infrastructure, high pet ownership rates, and strong adoption of regenerative medicine. The United States dominates regional demand due to widespread availability of specialized veterinary clinics and growing acceptance of stem cell therapies for orthopedic and degenerative conditions in companion animals and horses. High spending on advanced animal healthcare, supportive research ecosystems, and active participation of veterinary biotechnology companies further strengthen the region’s leadership in clinical adoption and commercialization.
Europe
Europe accounts for approximately 28% market share, supported by strong animal welfare standards, expanding veterinary specialty services, and increasing awareness of regenerative therapies. Countries such as Germany, the UK, and France drive regional demand through well-established equine healthcare markets and rising companion animal treatment adoption. Regulatory oversight ensures controlled clinical use, while growing collaboration between veterinary hospitals and research institutions supports steady expansion. Increasing focus on minimally invasive and long-term treatment solutions continues to drive regional market growth.
Asia-Pacific
Asia-Pacific holds an estimated 20% market share and represents the fastest-growing region in the Animal Stem Cell Therapy Market. Growth is fueled by rising pet ownership, expanding veterinary infrastructure, and increasing disposable incomes in countries such as China, Japan, Australia, and South Korea. Demand is particularly strong in equine therapy and companion animal orthopedics. Improving access to advanced veterinary care, growing awareness of regenerative medicine, and investments in animal biotechnology research support rapid regional adoption.
Latin America
Latin America represents around 8% market share, driven by expanding veterinary services and growing use of regenerative therapies in equine and livestock applications. Brazil and Mexico are key contributors, supported by large animal populations and increasing investment in animal health. While adoption remains lower compared to developed regions, improving veterinary training and rising awareness of stem cell-based treatments support gradual growth. Cost sensitivity and limited access to advanced facilities remain challenges but are steadily improving.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% market share, reflecting early-stage but steadily increasing adoption of animal stem cell therapies. Growth is driven by rising investment in equine sports medicine, particularly in Gulf countries, and gradual improvements in veterinary healthcare infrastructure. Demand is primarily concentrated in high-value equine treatments and specialty companion animal care. While limited access and regulatory variability constrain faster growth, increasing awareness and infrastructure development support long-term market potential.
Animal Stem Cell Therapy Market Segmentations:
By Therapy Type:
- Autologous Cell Therapy
- Allogeneic Cell Therapy
By Cell Type:
- Mesenchymal Stem Cells (MSCs)
- Embryonic Stem Cells (ESCs)
By Cell Source:
- Bone Marrow
- Adipose Tissue
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Animal Stem Cell Therapy Market players such as Atara Biotherapeutics, MEDIPOST, Johnson & Johnson Services, Inc., S. BIOMEDICS, Novartis AG, JW Therapeutics, Gilead Sciences, Inc., Anterogen Co., Ltd., Bristol-Myers Squibb Company, JCR Pharmaceuticals Co., Ltd. the Animal Stem Cell Therapy Market is moderately consolidated, with competition shaped by a mix of established biopharmaceutical companies and specialized regenerative medicine developers. Market participants compete primarily on research capabilities, cell processing technologies, and the ability to deliver safe, standardized, and scalable therapies for veterinary applications. Innovation focuses on mesenchymal and allogeneic cell platforms, off-the-shelf solutions, and improved manufacturing consistency. Strategic partnerships with veterinary hospitals, research institutions, and contract manufacturing organizations enhance clinical adoption and market reach. Regulatory preparedness, clinical evidence generation, and cost efficiency increasingly influence competitive positioning, while continued investment in R&D and translational science supports long-term market growth.
Key Player Analysis
- Atara Biotherapeutics
- MEDIPOST
- Johnson & Johnson Services, Inc.
- BIOMEDICS
- Novartis AG
- JW Therapeutics
- Gilead Sciences, Inc.
- Anterogen Co., Ltd.
- Bristol-Myers Squibb Company
- JCR Pharmaceuticals Co., Ltd.
Recent Developments
- In April 2025, Vetirus Pharmaceuticals acquired Kansas-based Enso Discoveries, a move that significantly boosted Vetirus's regenerative medicine offerings, adding Enso's expertise in innovative, accessible therapies like Rebound PRP™ for both animal and human health, aligning with market trends for growth in animal health tech and biologics.
- In March 2025, VetStem secured funding to finalize regulatory steps for StemStat™ Ortho, aiming for the first FDA conditional approval for an "off-the-shelf" (allogeneic) stem cell therapy for canine osteoarthritis, a significant move into a large potential market. This strategic funding allows them to complete submissions, positioning them to offer a regulated, convenient treatment option for dogs with arthritis.
- In April 2024, PromoCell GmbH launched its Cryo-SFM Plus cryopreservation medium designed to safely preserve various sensitive cells like primary cells, stem cells, and established lines, offering a defined, serum-free, and protein-free solution for better post-thaw cell health, integrity, and attachment.
Report Coverage
The research report offers an in-depth analysis based on Therapy Type, Cell Type, Cell Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of stem cell therapies will expand as veterinary clinics increasingly incorporate regenerative medicine into standard treatment protocols.
- Allogeneic and off-the-shelf cell therapies will gain wider acceptance due to scalability and faster treatment availability.
- Companion animals will remain the primary focus, with rising applications in orthopedic, inflammatory, and degenerative conditions.
- Advances in cell processing, preservation, and quality control will improve treatment consistency and clinical outcomes.
- Integration of stem cell therapies with advanced diagnostics will support more personalized veterinary treatment approaches.
- Research into new cell types and combination therapies will broaden therapeutic indications.
- Regulatory frameworks will continue to evolve, providing clearer pathways for commercialization and clinical use.
- Collaboration between biotechnology firms and veterinary hospitals will strengthen clinical validation and adoption.
- Cost optimization and improved manufacturing efficiency will enhance market accessibility over time.
- Growing awareness among pet owners will drive long-term demand for regenerative and minimally invasive animal therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Animal Stem Cell Therapy Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Animal Stem Cell Therapy Market projected to grow between 2024 and 2032?
Which Animal Stem Cell Therapy Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Animal Stem Cell Therapy Market?
Who are the leading companies in the Animal Stem Cell Therapy Market?
Which region commanded the largest share of the Animal Stem Cell Therapy Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Animal Stem Cell Therapy Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Animal Stem Cell Therapy Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 772 million → 2032: USD 1,584 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Animal Stem Cell Therapy Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Animal Stem Cell Therapy Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Animal Stem Cell Therapy Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Animal Stem Cell Therapy Market Drivers
- 3.3 Animal Stem Cell Therapy Market Restraints & Challenges
- 3.4 Animal Stem Cell Therapy Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Animal Stem Cell Therapy Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Animal Stem Cell Therapy Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Animal Stem Cell Therapy category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Animal Stem Cell Therapy Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Animal Stem Cell Therapy Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Animal Stem Cell Therapy market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Animal Stem Cell Therapy Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Animal Stem Cell Therapy Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Animal Stem Cell Therapy Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Animal Stem Cell Therapy (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Animal Stem Cell Therapy Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Animal Stem Cell Therapy Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Animal Stem Cell Therapy Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Animal Stem Cell Therapy Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Animal Stem Cell Therapy Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Animal Stem Cell Therapy Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Animal Stem Cell Therapy Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Animal Stem Cell Therapy Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Animal Stem Cell Therapy Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
