
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
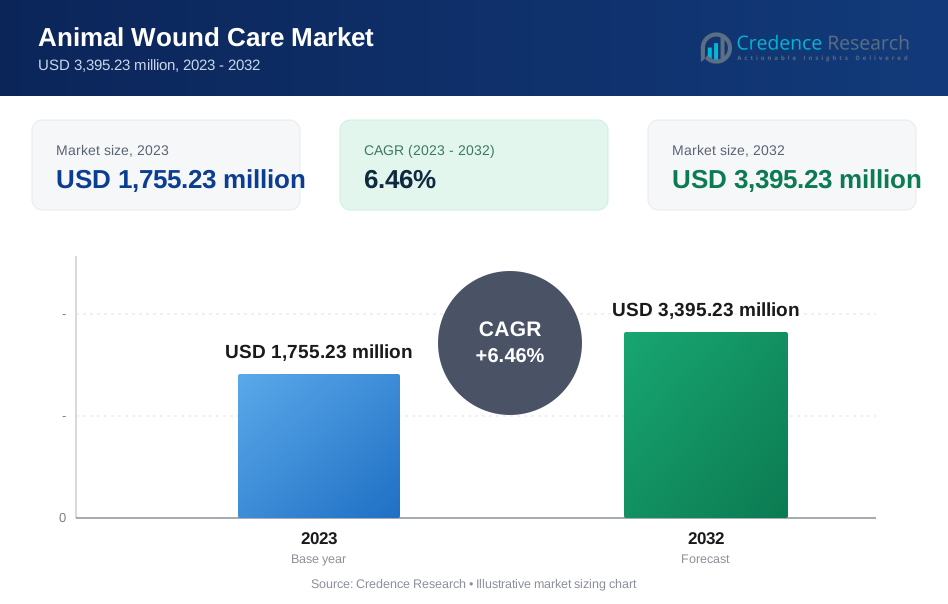
| Animal Wound Care Market Size 2023 | USD 1,755.23 million |
| Animal Wound Care Market, CAGR | 6.46% |
| Animal Wound Care Market Size 2032 | USD 3,395.23 million |
Market Overview:
The animal wound care market is projected to grow from USD 1,755.23 million in 2023 to USD 3,395.23 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.46%.
The animal wound care market is anticipated to undergo significant expansion, driven by various factors shaping the landscape of the animal healthcare industry. One of the primary drivers is the increasing prevalence of pet ownership globally, with pet owners increasingly considering their animals as integral members of their families. This mindset shift translates to higher expenditure on veterinary care, including the demand for advanced wound care solutions to ensure the well-being of pets. Additionally, heightened awareness of animal welfare standards is prompting both pet owners and veterinarians to prioritize effective wound care practices, fostering a need for innovative products that optimize healing and minimize discomfort.
Technological advancements in veterinary medicine are also contributing to the growth of the animal wound care market. These advancements facilitate the development of novel wound care products such as biocompatible dressings and advanced antimicrobial therapies, aimed at accelerating the healing process and reducing the risk of infection. Moreover, the market is witnessing a shift towards preventative care, with a focus on developing medications that can prevent the development or worsening of wounds. This emphasis on preventative measures further augments the demand for wound care solutions, driving market expansion.
Emerging trends such as tele veterinary services, personalized wound care protocols, and a focus on natural and organic products are reshaping the industry. These trends reflect a growing need for convenient and tailored solutions that prioritize animal comfort and well-being. Manufacturers and stakeholders in the animal wound care market have opportunities to capitalize on these trends by developing innovative products, targeting emerging markets with rising pet ownership rates, and investing in education and awareness initiatives to promote the importance of proper wound care practices among pet owners.
Market Drivers:
Increasing Trend of Pet Ownership:
The animal wound care market is expanding significantly, driven by various factors that are reshaping the dynamics of animal healthcare. A primary catalyst for this growth is the increasing trend of pet ownership worldwide. According to the 2021–2022 APPA National Pet Owners Survey, 70% of U.S. households own some type of pet. With pets increasingly regarded as integral family members, there’s a heightened emphasis on their overall well-being, including the management of injuries and wounds.
Rising disposable incomes:
Moreover, rising disposable incomes in many regions enable pet owners to allocate more resources to advanced veterinary care, driving the demand for effective wound care solutions. For instance, Americans had a total of 15.13 trillion dollars in disposable personal income in 2021. This trend is further reinforced by the growing awareness of animal health needs, spurred by public education campaigns and the availability of online resources, which empower pet owners to make informed decisions regarding their pets’ healthcare.
Advancements in Veterinary Medicine and Technology:
Advancements in veterinary medicine and technology play a pivotal role in enhancing the efficacy of wound care treatments. The continuous innovation in wound care solutions, including novel dressings, bandages, and medications, contributes to improved healing outcomes and reduced infection risks. Furthermore, the adoption of minimally invasive surgical techniques and telemedicine consultations elevates the standard of care, providing more efficient and convenient treatment options for both pets and their owners. These technological advancements not only improve treatment efficacy but also enhance the overall patient experience, fostering further growth in the animal wound care market.
Focus on Livestock Health and Productivity:
Beyond companion animals, there’s a growing focus on livestock health and productivity, driving demand for effective wound care solutions in agricultural settings. The livestock industry recognizes the importance of maintaining animal health to ensure herd productivity and safe food production. Regulatory emphasis on animal welfare practices within the industry underscores the need for humane and effective wound care products.
Evolving Regulatory Landscape:
Additionally, the evolving regulatory landscape, with stricter guidelines and an increased focus on antimicrobial resistance, is prompting innovation in wound care solutions. Manufacturers are striving to develop products that comply with evolving regulations while addressing emerging challenges, such as antimicrobial resistance, to meet the evolving needs of the animal healthcare market.
Market Trends:
Rising Pet Ownership and Growing Disposable Income:
A global increase in pet ownership, particularly in developing economies, fuels demand for advanced animal healthcare solutions. As disposable income rises, pet owners are more willing to invest in their furry companions' well-being, including wound care products.
Focus on Advanced Wound Management Techniques:
Veterinary medicine is witnessing a shift towards adopting advanced wound management techniques previously seen primarily in human healthcare. This includes the use of specialized dressings, negative pressure wound therapy, and biomaterials to promote faster healing and minimize complications.
Increasing Prevalence of Chronic Diseases in Animals:
The growing incidence of chronic diseases like diabetes and obesity in pets translates to a higher risk of developing wounds. Additionally, the aging pet population is susceptible to pressure sores and other chronic wound conditions, driving demand for effective wound care solutions.
Technological Advancements and Product Innovation:
Manufacturers are constantly innovating to develop new and improved wound care products for animals. This includes advancements in antimicrobial coatings for dressings, the incorporation of stem cells for faster tissue regeneration, and the development of pain-management solutions specifically designed for animals undergoing wound treatment.
Growing Demand for Minimally Invasive Procedures:
Minimally invasive surgical techniques are gaining traction in veterinary medicine. This minimally disruptive approach to wound creation leads to faster recovery times and reduced pain for animals, increasing the demand for specialized wound care products tailored to these procedures.
Market Restraints and Challenges:
- Limited Awareness and Knowledge in Emerging Economies: In rapidly developing economies, there is often a significant gap in knowledge and understanding of proper animal healthcare practices. Pet owners in these regions may not be aware of the existence or benefits of advanced wound care products, leading to a reliance on traditional, less effective methods. This limited awareness can restrict market growth in these areas.
- High Costs Associated with Veterinary Care: The rising cost of veterinary services and products, including advanced wound care solutions, poses a significant challenge. Pet owners, particularly those with limited disposable income, may be forced to choose more affordable but potentially less effective treatment options for their pets' wounds. Manufacturers need to consider offering cost-effective solutions or exploring alternative pricing models to make wound care products more accessible to a wider range of pet owners.
- Lack of Well-Designed Comparative Studies in Specific Species: While there is ongoing research in animal wound care, the availability of well-designed comparative studies specifically focused on cats and dogs, the two largest segments of the companion animal market, is limited. This lack of robust data comparing the efficacy of different wound care products for these species can make it difficult for veterinarians and pet owners to make informed decisions about treatment options.
- Stringent Regulatory Requirements: The regulatory landscape for veterinary medical devices is often complex and requires rigorous testing and approval processes. This can be a barrier for new and innovative wound care products entering the market, potentially hindering advancements in the field. Additionally, navigating these regulations can be costly and time-consuming for manufacturers, impacting their ability to bring new solutions to market quickly.
- Veterinarian Preference for Established Brands: Veterinarians often rely on established brands and products with a proven track record. This can make it challenging for newer or less well-known brands to gain market share, even if they offer innovative or more cost-effective solutions. New entrants may need to invest in building brand awareness and establishing trust within the veterinary community to overcome this hurdle.
Recent Developments:
- In February 2024, Zoetis established a collaboration with the University of California, Davis to research new regenerative medicine therapies for animals, which may include wound healing solutions.
- In February 2024, Merial introduced a new line of “VetPro Advanced Wound Care” products in Europe, which includes novel dressings and sprays for faster healing and pain relief.
- In January 2024, Pfizer Animal Health obtained regulatory approval in the United States for their novel “Equine Wound Repair Gel,” which is intended to speed up healing in horses.
- In January 2024, Dechra Pharmaceuticals established a strategic alliance with a veterinary technology firm working on a laser therapy device for wound healing in animals.
- In January 2024, Elanco Animal Health presented studies at a veterinary symposium, demonstrating the effectiveness of its novel antibacterial wound treatment for dogs.
- In April 2022, Neogen Corporation announced the introduction of new products to its dependable Prozap insect control line, featuring Prozap Protectus Pour-On Insecticide IGR. This triple-acting formula kills chewing and sucking lice, horn flies, stable flies, horse and deer flies, and other insects on beef cattle and calves.
Segmentation Analysis:
Product Type:
- Advanced Wound Care Products: This segment includes dressings with specialized features like controlled-release medication or negative pressure therapy.
- Traditional Wound Care Products: This segment encompasses bandages, gauze pads, and other basic wound care supplies.
- Surgical Wound Care Products: This segment includes sutures, staplers, and other products used to close surgical incisions.
- Therapy Devices: This segment includes laser therapy devices, ultrasound therapy equipment, and other technologies used to promote wound healing.
Segments:
By Product Type:
- Surgical Wound Care Products
- Sutures and Staplers
- Tissue Adhesives, Sealants, And Glues
- Advanced Wound Care Products
- Foam Dressings
- Hydrocolloid Dressings
- Film Dressings
- Hydrogel Dressings
- Other Advanced Dressings
- Absorbents
- Traditional Wound Care Products
- Tapes
- Dressings
- Bandages
- Absorbents
- Other Traditional Wound Care Products
- Therapy Devices
By Animal Type:
- Companion Animal
- Livestock animal
By End-user:
- Veterinary hospitals & clinics
- Homecare
- Research Institutes
By Distribution Channel:
- Retail
- E-commerce
- Veterinary hospitals & clinics
By Region:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Key player:
- Elanco Animal Health
- Medtronic PLC
- Dechra Pharmaceuticals
- Neogen Corporation
- B. Braun Melsungen AG
- Ethicon, Inc.
- Sonoma Pharmaceuticals Inc.
- Jazz Medical LLC
- Prima-Vet Inc.
- Virbac
- Jorgen Kruuse A/S
Regional Analysis:
North America:
This region is anticipated to hold the largest market share throughout the forecast period. This dominance can be attributed to several factors, including high pet ownership rates, rising disposable income, and increasing awareness of animal health. North American pet owners are more likely to invest in advanced wound care solutions for their furry companions.
Asia Pacific:
The Asia Pacific region is poised for the fastest growth in the animal wound care market. This surge is primarily driven by the burgeoning pet population, growing veterinary infrastructure, and rising disposable income in developing economies within the region. As pet ownership becomes more common and pet healthcare awareness increases, the demand for advanced wound care products is expected to rise significantly.
Europe:
Europe represents another substantial market for animal wound care products. This established market benefits from the presence of major market players and a well-developed veterinary healthcare system. European pet owners have a long history of prioritizing animal health, creating a steady demand for wound care solutions. However, growth in this region is expected to be moderate compared to the Asia Pacific region due to its already mature market.
Future Outlook:
- Rising Demand for Advanced Therapies: Advancements in veterinary medicine will lead to a growing demand for novel wound care therapies like stem cell treatments and biofilms.
- Focus on Preventative Care: Increased awareness of preventative measures for animal injuries will drive the market for wound care products used for post-surgical applications and chronic wound management.
- Growing Pet Ownership: The rising global pet ownership trend, particularly in developing economies, will fuel the demand for animal wound care products.
- Technological Advancements: Continuous technological advancements in areas like telemedicine and wearable diagnostics will enhance remote wound monitoring and treatment protocols.
- Evolving Regulatory Landscape: Regulatory bodies will likely introduce stricter guidelines for animal wound care products, promoting higher quality standards and innovation.
- Personalization of Wound Care: The market will witness a shift towards personalized wound care solutions, catering to specific animal needs and wound types.
- Increased Focus on Companion Animals: A growing emphasis on pet well-being will lead to a rise in premium wound care products specifically designed for companion animals.
- Expansion into Emerging Markets: Emerging economies like China and India will experience significant growth in the animal wound care market due to rising disposable income and pet ownership.
- Growing Importance of Veterinary Telemedicine: The integration of telemedicine consultations for wound monitoring and remote treatment guidance will become more prevalent.
- Focus on Sustainability: Manufacturers will increasingly focus on developing eco-friendly wound care products made from sustainable materials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the animal wound care market?
What factors are driving the growth of the animal wound care market?
How are technological advancements impacting the animal wound care market?
What emerging trends are shaping the animal wound care market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Animal Wound Care Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Animal Wound Care Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,755.23 million → 2032: USD 3,395.23 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Animal Wound Care Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Animal Wound Care Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Animal Wound Care Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Animal Wound Care Market Drivers
- 3.3 Animal Wound Care Market Restraints & Challenges
- 3.4 Animal Wound Care Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Animal Wound Care Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Animal Wound Care Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Animal Wound Care category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Animal Wound Care Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Animal Wound Care Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Animal Wound Care market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Animal Wound Care Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Animal Wound Care Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Animal Wound Care Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Animal Wound Care (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Animal Wound Care Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Animal Wound Care Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Animal Wound Care Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Animal Wound Care Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Animal Wound Care Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Animal Wound Care Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Animal Wound Care Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Animal Wound Care Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Animal Wound Care Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
