
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia-Pacific Luxury Vinyl Tiles Flooring Market Size 2023 | USD 6,734.18 Million |
| Asia-Pacific Luxury Vinyl Tiles Flooring Market, CAGR | 12.10% |
| Asia-Pacific Luxury Vinyl Tiles Flooring Market Size 2032 | USD 18,825.01 Million |
Market Overview
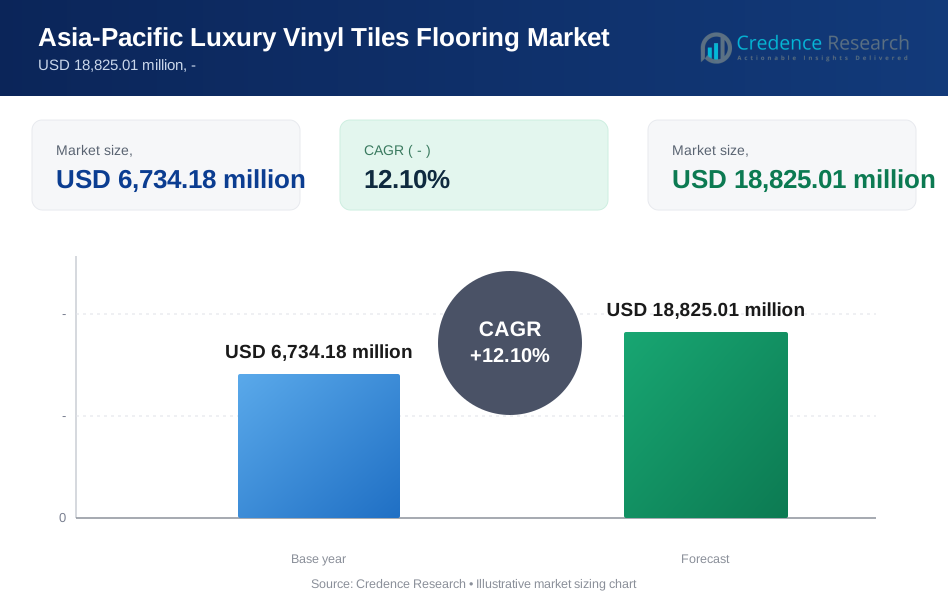
The Asia Pacific Luxury Vinyl Tiles Flooring Market is projected to soar from USD 6,734.18 million in 2023 to USD 18,825.01 million by 2032, with an impressive compound annual growth rate of 12.10%.
In the Asia Pacific Luxury Vinyl Tiles Flooring Market, several key drivers and trends are shaping the industry landscape. Rapid urbanization, coupled with increasing disposable incomes, is fostering the demand for aesthetically pleasing and durable flooring solutions. Moreover, the growing preference for eco-friendly and sustainable materials is driving manufacturers to innovate and offer environmentally conscious luxury vinyl tile options. Additionally, advancements in technology, such as digital printing and embossing techniques, are enhancing the visual appeal of luxury vinyl tiles, further bolstering their popularity among consumers. These factors collectively contribute to the robust growth and evolution of the Asia Pacific luxury vinyl tiles flooring market.
In the Asia Pacific Luxury Vinyl Tiles Flooring Market, geographical analysis reveals diverse trends across the region. Countries like China, Japan, and South Korea exhibit significant market growth owing to rapid urbanization and increasing construction activities. Southeast Asian countries such as Indonesia, Thailand, and Vietnam are also emerging as lucrative markets due to rising infrastructure development projects. Key players dominating this market landscape include Shaw Industries, Tarkett, Armstrong Flooring, Mohawk Industries, and Mannington Mills, among others. These industry leaders are actively engaged in strategic initiatives such as product innovation, mergers, and acquisitions to maintain their competitive edge and expand their market presence across the Asia Pacific region.
Market Drivers
Growth in the Construction Industry:
The Asia Pacific region is experiencing a boom in the construction industry, driven by factors such as urbanization, rising disposable incomes, and government investments in infrastructure development. For instance, the boom is largely driven by urbanization, with more than half of the Indian population under the age of 30. Over the next decade, this demographic is expected to significantly propel the demand for housing.This growth in construction activity is creating a significant demand for LVT flooring, which is a popular choice for both residential and commercial applications.
Rising Disposable Incomes and Living Standards:
Growing economies in the region are leading to rising disposable incomes and living standards. This is increasing consumer preference for high-quality, aesthetically pleasing, and durable flooring solutions, which LVT flooring can provide. The economies in the Asia Pacific region are growing at a significant pace. For instance, the Asia-Pacific region is expected to grow by 4.6 percent in 2023, up from 3.9 percent in 2022. This growth is leading to rising disposable incomes and living standards. As consumers seek to enhance the ambiance of their living spaces, LVT flooring emerges as an attractive option due to its versatility in design, ranging from wood and stone finishes to modern patterns, catering to diverse aesthetic preferences across the Asia Pacific market.
Increasing Urbanization:
Rapid urbanization is leading to a rise in new housing developments and renovation projects in the region. For instance, in India alone, the urban population is expected to reach 590 million by 2030, leading to a surge in housing demand. This trend is mirrored across the region, with the Asia Pacific real estate market showing a year-to-date transaction value of prime office real estate reaching substantial figures by Q3 2023. LVT flooring is a popular choice for these projects due to its ease of installation, low maintenance requirements, and affordability. Urban dwellers are drawn to the convenience and durability offered by LVT flooring, especially in high-traffic areas such as residential complexes, commercial buildings, and public spaces. This trend is expected to drive sustained growth in the Asia Pacific luxury vinyl tiles flooring market.
Growing Demand for Sustainable Products:
Consumers in the Asia Pacific region are becoming increasingly environmentally conscious. LVT flooring can be a sustainable choice, as it is often made from recycled materials and can be easily recycled at the end of its lifespan. Manufacturers are responding to this demand by offering eco-friendly LVT options, incorporating sustainable practices into their production processes, and obtaining certifications to validate their commitment to environmental stewardship. As sustainability continues to gain traction as a key decision-making factor among consumers, the adoption of eco-friendly LVT flooring is poised to escalate, further propelling market growth in the Asia Pacific region.
Market Trends
Rising Demand for Rigid LVT:
Rigid LVT is gaining popularity due to its dimensional stability, improved durability, and ease of installation. This type of LVT is particularly well-suited for high-traffic areas and commercial applications. The rigidity of these tiles ensures they can withstand heavy foot traffic up to 10,000 footfalls per day without warping or damage, making them ideal for use in retail spaces, corporate offices, and hospitality venues. Moreover, the ease of installation, which can be up to 30% faster than traditional tiles, appeals to contractors and homeowners alike, reducing installation time and costs associated with labor by an estimated 20%. As a result, the demand for rigid LVT is expected to continue its upward trajectory in the Asia Pacific region, with a significant increase in adoption rates in countries like China and India, where urbanization and commercial development are on the rise..
Growing Preference for Wood-Look LVT:
Consumers are increasingly opting for LVT flooring that replicates the look of natural wood. For instance, in the United States, the market for Luxury Vinyl Tile (LVT) flooring has seen a significant increase, with sales growing by an estimated 6.5% annually. In particular, wood-look LVT has captured approximately 50% of the LVT market due to its aesthetic appeal and practical benefits. It’s reported that 70% of consumers prefer wood-look LVT for its water resistance, which is especially important in areas prone to spills and moisture. Moreover, the ease of maintenance is a key factor, with 60% of buyers citing it as a primary reason for their choice, as it requires no waxing or sealing unlike traditional hardwood. The affordability of wood-look LVT is also a major draw, costing on average 30% less than hardwood per square foot, making it accessible for a wider range of budgets. In commercial settings, such as offices and hotels, wood-look LVT usage has risen by 40% over the past five years, enhancing the ambiance while providing a durable flooring solution. The growing popularity of wood-look LVT is evident in both residential and commercial settings, where it adds warmth and sophistication to interior spaces. This trend is expected to fuel further innovation in wood-look LVT designs and technologies to meet evolving consumer preferences.
Market Challenges Analysis
Fluctuations in Raw Material Prices:
The LVT flooring industry relies on various raw materials, including PVC, plasticizers, and stabilizers. Fluctuations in the prices of these raw materials can impact production costs and profitability for manufacturers. Sudden increases in raw material prices can squeeze profit margins, while decreases may not necessarily translate to cost savings for manufacturers due to contractual agreements or inventory management practices. Such volatility in raw material prices poses a significant challenge for LVT flooring manufacturers, necessitating proactive strategies such as diversifying supply sources, implementing hedging mechanisms, or exploring alternative materials to mitigate the impact of price fluctuations and maintain competitiveness in the market.
Supply Chain Disruptions:
Global supply chain disruptions can affect the availability and cost of raw materials for LVT flooring production. This can lead to delays in production and price hikes for consumers. Disruptions such as natural disasters, geopolitical tensions, or transportation bottlenecks can disrupt the flow of raw materials from suppliers to manufacturers, causing ripple effects throughout the supply chain. As the Asia Pacific region relies heavily on imported raw materials for LVT flooring production, disruptions in global trade or logistics can pose significant challenges for manufacturers, requiring them to develop robust contingency plans and forge strategic partnerships to ensure a stable and resilient supply chain.
Market Segmentation Analysis:
By Type:
In the Asia Pacific Luxury Vinyl Tiles Flooring Market, the segment is primarily divided into two types: Rigid and Flexible. Rigid LVT flooring is gaining prominence due to its superior dimensional stability, enhanced durability, and suitability for high-traffic areas and commercial applications. On the other hand, Flexible LVT offers versatility in installation, making it a preferred choice for residential settings where subfloor imperfections may exist. The Rigid segment is witnessing robust growth driven by increasing demand from commercial sectors such as hospitality, retail, and healthcare, where durability and performance are paramount. Meanwhile, the Flexible segment remains popular in residential applications, offering homeowners a wide range of design options and ease of installation. Manufacturers are focusing on innovation and product differentiation within each segment to cater to diverse consumer preferences and market demands, driving further growth and evolution in the Asia Pacific Luxury Vinyl Tiles Flooring Market.
By End-user:
The Asia Pacific Luxury Vinyl Tiles Flooring Market is segmented based on end-user into Residential and Non-Residential categories. The Residential segment encompasses applications in homes, apartments, and condominiums, driven by factors such as urbanization, renovation activities, and changing lifestyle preferences. In contrast, the Non-Residential segment includes commercial spaces such as offices, retail stores, hospitality venues, and healthcare facilities. Non-residential applications account for a significant share of the market, fueled by increasing construction activities and the demand for durable, aesthetically pleasing flooring solutions. Both segments offer distinct opportunities and challenges for market players, with the residential segment witnessing higher demand volatility and the non-residential segment characterized by longer sales cycles and stringent performance requirements. Understanding the unique needs and preferences of each end-user segment is crucial for manufacturers and suppliers to effectively target and capitalize on market opportunities in the Asia Pacific Luxury Vinyl Tiles Flooring Market.
Segments:
Based on Type
- Rigid
- Flexible
Based on End-user
- Residential
- Non-Residential
Based on the Geography:
- Asia-Pacific
- China
- India
- Southeast Asian countries (Indonesia, Malaysia, Thailand)
- Japan
- South Korea
- Australia
- New Zealand
- Other Asia Pacific countries
Regional Analysis
China
China holds a dominant position, accounting for approximately 35% of the Asia Pacific LVT flooring market. The country's rapidly expanding construction industry, coupled with a burgeoning middle-class population, has fueled the demand for LVT flooring. India follows closely, with a market share of around 25%, driven by infrastructure development projects and increasing consumer awareness of luxury flooring options.
Southeast Asian
The Southeast Asian countries, including Indonesia, Malaysia, and Thailand, collectively account for approximately 20% of the regional market. The region's robust economic growth, coupled with rising urbanization rates, has boosted the demand for luxury vinyl tiles in both residential and commercial sectors.
Key Player Analysis
- Mohawk Industries
- Shaw Industries Group, Inc.
- Armstrong Flooring
- Mannington Mills, Inc.
- Tarkett
Competitive Analysis
In the fiercely competitive landscape of the Asia Pacific Luxury Vinyl Tiles Flooring Market, the leading players such as Mohawk Industries, Shaw Industries Group, Inc., Armstrong Flooring, Mannington Mills, Inc., and Tarkett continually vie for market dominance through strategic initiatives and product differentiation. Mohawk Industries, with its extensive product portfolio and global reach, maintains a strong presence across the region, leveraging its innovative designs and sustainable practices to capture market share. Shaw Industries Group, Inc. distinguishes itself with its focus on research and development, consistently introducing cutting-edge technologies and design trends to meet evolving consumer preferences. Armstrong Flooring stands out for its commitment to quality and durability, offering a wide range of LVT solutions tailored to residential and commercial applications. Mannington Mills, Inc. emphasizes design versatility and customization, catering to niche market segments and fostering brand loyalty among discerning consumers. Tarkett, renowned for its eco-friendly initiatives and sustainable manufacturing processes, resonates with environmentally conscious consumers, positioning itself as a trusted leader in the Asia Pacific Luxury Vinyl Tiles Flooring Market. As these industry giants continue to innovate and adapt to market dynamics, competition intensifies, driving forward the evolution and growth of the regional LVT flooring market.
Recent Developments
In 2022, Tarkett has partnered with Squarefoot in India to launch a carpet recycling initiative. Tarkett will collect discarded carpet tiles from restoration sites and recycle both the backing and the yarn. The yarn is used to manufacture recycled paper bags, while the backing material is upcycled in the car and construction industries.
In 2022, AsanaTM, NidraTM, and ZenscapeTM are three new heterogeneous sheet products from Armstrong Flooring. Diamond 10® Technology, an unique wear layer that utilizes cultivated diamonds to deliver the ultimate in scratch, stain, and scuff resistance while removing the need for polish, is included in each collection.
Market Concentration & Characteristics
In the Asia Pacific Luxury Vinyl Tiles Flooring Market, market concentration is evident, with a handful of key players dominating a significant portion of the market share. These leading companies exhibit characteristics of established industry incumbents, leveraging their brand reputation, extensive distribution networks, and diverse product portfolios to maintain their competitive edge. Market concentration is driven by factors such as economies of scale, technological prowess, and strategic acquisitions, allowing dominant players to exert considerable influence over pricing dynamics and industry trends. Despite the presence of smaller and niche players, market concentration remains pronounced, with larger companies often enjoying greater bargaining power with suppliers and retailers. However, market characteristics also reflect a dynamic landscape, characterized by continuous innovation, evolving consumer preferences, and regulatory shifts towards sustainability. As a result, market concentration is not static but subject to ongoing changes influenced by factors such as mergers and acquisitions, technological advancements, and shifts in consumer behavior, shaping the future trajectory of the Asia Pacific Luxury Vinyl Tiles Flooring Market.
Report Coverage
The research report offers an in-depth analysis based on Type, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The Asia Pacific Luxury Vinyl Tiles Flooring Market is poised for sustained expansion, driven by urbanization, infrastructure development, and rising disposable incomes.
- Technological Advancements: Innovations in digital printing and embossing techniques will enhance the visual appeal and realism of luxury vinyl tile designs.
- Increasing Demand for Sustainable Solutions: Consumer preference for eco-friendly materials will drive manufacturers to develop more sustainable LVT flooring options.
- Growth in Non-Residential Sector: Expansion of commercial sectors such as retail, healthcare, and hospitality will fuel demand for LVT flooring in non-residential applications.
- Market Consolidation: Mergers, acquisitions, and strategic partnerships will reshape the competitive landscape, leading to increased market consolidation.
- Shift towards Rigid LVT: The popularity of rigid LVT flooring will continue to rise, fueled by its superior durability and dimensional stability, particularly in high-traffic areas.
- Online Sales Growth: E-commerce platforms will play an increasingly significant role in LVT flooring sales, offering consumers convenience and a wide range of product options.
- Regulatory Compliance: Manufacturers will need to adhere to stringent regulations and certifications, particularly regarding environmental sustainability and indoor air quality standards.
- Regional Expansion: Market players will focus on expanding their presence in emerging markets within the Asia Pacific region, capitalizing on growing demand and infrastructure development.
- Consumer Education: Increased efforts towards consumer education and awareness campaigns will be essential to promote the benefits and versatility of luxury vinyl tile flooring, especially in regions with lower awareness levels.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Luxury Vinyl Tiles Flooring Market?
What factors are driving the growth of the Asia Pacific Luxury Vinyl Tiles Flooring Market?
What are the key segments within the Asia Pacific Luxury Vinyl Tiles Flooring Market?
What are some challenges faced by the Asia Pacific Luxury Vinyl Tiles Flooring Market?
Who are the major players in the Asia Pacific Luxury Vinyl Tiles Flooring Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia-Pacific Luxury Vinyl Tiles Flooring Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia-Pacific Luxury Vinyl Tiles Flooring Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 6,734.18 million → forecast year: USD 18,825.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia-Pacific Luxury Vinyl Tiles Flooring Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia-Pacific Luxury Vinyl Tiles Flooring Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia-Pacific Luxury Vinyl Tiles Flooring Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia-Pacific Luxury Vinyl Tiles Flooring Market Drivers
- 3.3 Asia-Pacific Luxury Vinyl Tiles Flooring Market Restraints & Challenges
- 3.4 Asia-Pacific Luxury Vinyl Tiles Flooring Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia-Pacific Luxury Vinyl Tiles Flooring Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia-Pacific Luxury Vinyl Tiles Flooring Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia-Pacific Luxury Vinyl Tiles Flooring category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia-Pacific Luxury Vinyl Tiles Flooring Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia-Pacific Luxury Vinyl Tiles Flooring Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia-Pacific Luxury Vinyl Tiles Flooring market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia-Pacific Luxury Vinyl Tiles Flooring Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia-Pacific Luxury Vinyl Tiles Flooring Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia-Pacific Luxury Vinyl Tiles Flooring Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia-Pacific Luxury Vinyl Tiles Flooring (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia-Pacific Luxury Vinyl Tiles Flooring Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia-Pacific Luxury Vinyl Tiles Flooring Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia-Pacific Luxury Vinyl Tiles Flooring Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia-Pacific Luxury Vinyl Tiles Flooring Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
