
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia Pacific Last Mile Delivery Market Size 2024 | USD 48,933.28 million |
| Asia Pacific Last Mile Delivery Market, CAGR | 9.25% |
| Asia Pacific Last Mile Delivery Market Size 2032 | USD 1,07,769.61 million |
Market Overview
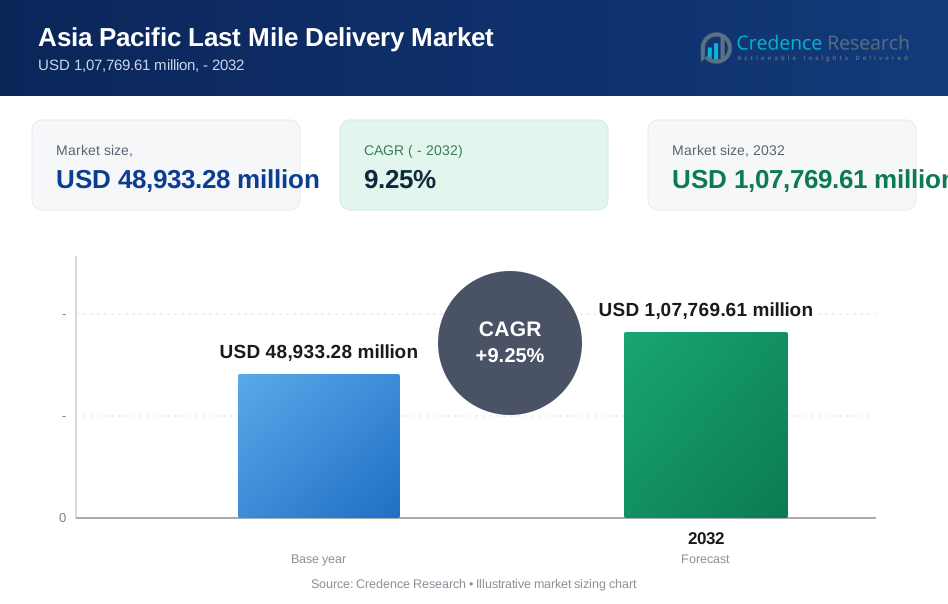
The Asia Pacific Last Mile Delivery Market is projected to grow from USD 48,933.28 million in 2023 to an estimated USD 1,07,769.61 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.25% from 2024 to 2032. This growth is driven by the rapid expansion of e-commerce platforms, increasing consumer demand for fast and efficient delivery services, and technological advancements in logistics solutions.
Key drivers of the market include the growing popularity of same-day and next-day deliveries, the integration of advanced technologies like artificial intelligence, and the adoption of electric vehicles (EVs) in delivery fleets to meet sustainability goals. Additionally, the rise of online grocery shopping, particularly after the COVID-19 pandemic, has accelerated demand for efficient delivery systems. Companies are focusing on optimizing their supply chains and reducing delivery costs, contributing to the market's expansion.
Geographically, China, Japan, and India dominate the Asia Pacific Last Mile Delivery Market due to their vast e-commerce sectors and dense urban populations. These countries are leading in the adoption of innovative delivery technologies and infrastructure improvements. Key players in the market include DHL Express, FedEx, Amazon, and SF Express, who are investing in advanced delivery solutions and expanding their presence in the region to capture growing demand.
Market Drivers
Rapid Expansion of E-commerce and Digital Retail Platforms
The surge in e-commerce across the Asia Pacific region is one of the most prominent drivers of the last mile delivery market. With more consumers shifting towards online shopping, the demand for efficient, reliable, and fast delivery services has increased exponentially. Countries such as China, India, Japan, and Southeast Asian nations are witnessing significant growth in digital retail, fueled by rising internet penetration, smartphone adoption, and an expanding middle class. This shift is propelling the need for enhanced last mile delivery services to meet customer expectations for speed and convenience. The e-commerce industry has also diversified, extending beyond traditional retail to include segments such as grocery, food delivery, and pharmaceuticals, further intensifying the need for last mile logistics solutions. For instance, in 2024, consumers in Asia Pacific are projected to spend an average of $125 on fast food annually, with 72% of fast-food consumers expected to utilize food delivery apps. This trend underscores the growing demand for convenient and quick meal options, directly impacting the last mile delivery market in the region. Additionally, the growing preference for same-day and next-day deliveries has placed added pressure on logistics providers to optimize their last mile operations. To meet these demands, companies are increasingly investing in infrastructure and technologies that enable faster delivery times, such as automated warehouses, smart routing, and real-time tracking systems. This shift is expected to continue driving the market's expansion as e-commerce penetration deepens across the region.
Advancements in Technology and Innovation in Logistics Solutions
Technological advancements are transforming the logistics and delivery landscape in the Asia Pacific region, driving the growth of the last mile delivery market. The integration of cutting-edge technologies such as artificial intelligence (AI), machine learning, Internet of Things (IoT), and big data analytics is enabling logistics companies to streamline their operations and enhance delivery efficiency. These technologies allow for better route optimization, real-time tracking, predictive analytics, and inventory management, all of which are critical in improving the customer experience and reducing delivery times.Automation is playing a crucial role in revolutionizing last mile delivery. Innovations such as autonomous delivery vehicles, drones, and robotics are being explored to address the challenges of labor shortages, traffic congestion, and the high cost of last mile logistics. For example, in densely populated urban areas, drone deliveries and autonomous ground vehicles offer a potential solution to bypass traffic and reduce delivery times. Additionally, smart lockers and pickup points are becoming more common, offering flexible delivery options for customers and reducing the burden on delivery fleets. These technological innovations are not only helping logistics companies optimize costs but are also essential in meeting the growing expectations of customers for quick, reliable, and hassle-free deliveries. As technology continues to evolve, its impact on the last mile delivery market is expected to be profound, fueling further growth and transformation.
Rising Consumer Demand for Fast and Convenient Deliveries
The growing expectation for fast, convenient, and flexible delivery options is a key driver of the last mile delivery market in the Asia Pacific region. Modern consumers, particularly in urban areas, have become accustomed to the convenience of e-commerce and expect their purchases to be delivered quickly, often within the same day or the next. This expectation has led to increased demand for efficient last mile delivery solutions that can meet tight delivery windows while maintaining accuracy and reliability. The rise of on-demand services, particularly in sectors such as food delivery and groceries, has further amplified the need for fast and flexible last mile logistics. Consumers now expect their orders to arrive within hours of placing them, creating new challenges and opportunities for logistics providers. In response, many companies are investing in urban fulfillment centers, dark stores, and micro-warehouses that enable quicker dispatch and delivery to nearby customers. Moreover, offering flexible delivery options, such as same-day delivery, scheduled delivery, and contactless delivery, has become a competitive differentiator in the market. The emphasis on customer-centric delivery models has also led to an increased focus on enhancing the overall delivery experience, with real-time tracking, communication, and customizable delivery preferences becoming standard features. The ability to meet these rising consumer expectations is critical to sustaining growth in the last mile delivery market.
Government Initiatives and Sustainability Goals
Government policies and initiatives aimed at improving transportation infrastructure and promoting sustainable logistics practices are playing a significant role in the growth of the last mile delivery market in the Asia Pacific region. Many governments across the region are investing heavily in improving road networks, developing urban logistics hubs, and enhancing transportation systems to support the growing demand for e-commerce and last mile delivery services.At the same time, there is a growing emphasis on sustainability within the logistics industry, driven by both government regulations and consumer preferences for eco-friendly practices. In many Asia Pacific countries, governments are implementing policies to reduce carbon emissions and promote the use of electric vehicles (EVs) in delivery fleets. For instance, China has been at the forefront of promoting EV adoption, and logistics companies are increasingly incorporating electric vans and bikes into their delivery networks. Similarly, cities across the region are adopting policies to reduce traffic congestion and pollution, encouraging the use of environmentally friendly delivery modes such as bicycles and electric scooters.These initiatives not only help reduce the environmental impact of last mile deliveries but also align with the sustainability goals of many companies operating in the region. The focus on green logistics is expected to be a significant growth driver for the market in the coming years, as both consumers and regulators place greater importance on environmental responsibility.
Market Trends
Adoption of Advanced Technology and Automation
One of the most prominent trends in the Asia Pacific Last Mile Delivery Market is the increasing adoption of advanced technologies and automation in logistics operations. Companies are integrating artificial intelligence (AI), machine learning, and data analytics to optimize delivery routes, enhance fleet management, and improve the overall efficiency of the last mile delivery process. AI-powered tools allow for better demand forecasting, enabling companies to plan deliveries based on predictive analytics, reducing delivery times, and cutting costs.The use of automation is also growing, particularly in warehousing and fulfillment centers. Automated picking systems, robotics, and autonomous vehicles are being explored and implemented to streamline the delivery process and mitigate challenges like labor shortages and high operational costs. Moreover, the use of drones and autonomous delivery vehicles is becoming more prevalent, especially in urban areas where traffic congestion can hinder timely deliveries. These innovations not only boost operational efficiency but also allow companies to offer faster, more reliable delivery options, meeting the rising consumer demand for same-day and next-day deliveries.
Focus on Sustainable and Eco-Friendly Delivery Solutions
As environmental concerns grow, sustainability has become a key focus for companies operating in the Asia Pacific last mile delivery market. The increasing pressure from governments and consumers for greener logistics solutions is pushing companies to adopt eco-friendly practices. One of the major trends in this space is the adoption of electric vehicles (EVs) in delivery fleets. Countries like China and Japan are leading the region in EV integration, with logistics companies transitioning to electric vans, bikes, and scooters to reduce their carbon footprint. Additionally, companies are exploring alternative delivery methods, such as bicycle deliveries and the use of electric-powered micro-mobility solutions for shorter distances in dense urban areas. There is also a growing emphasis on optimizing packaging to reduce waste and adopting green supply chain practices that minimize environmental impact. Sustainable last mile logistics not only align with corporate social responsibility goals but also resonate with environmentally conscious consumers, driving brand loyalty and customer satisfaction. As sustainability becomes a priority, eco-friendly delivery solutions are expected to become a long-term trend in the Asia Pacific region. For instance, a study conducted in 2023 revealed that 68% of consumers in Indonesia have adopted sustainable purchasing practices in the last 12 months, highlighting the growing demand for eco-friendly delivery solutions in the Asia Pacific region. Additionally, FedEx Thailand reported that their existing electric vehicles have contributed to an estimated savings of 153.06 metric tons of CO2 emissions since entering service in 2022, demonstrating the tangible impact of sustainable delivery methods.
Market Restraints and Challenges
High Operational Costs and Low Profit Margins
One of the major restraints in the Asia Pacific Last Mile Delivery Market is the high operational costs associated with last mile logistics. The final leg of delivery, which involves transporting goods from distribution centers to the customer’s doorstep, is often the most expensive and complex part of the supply chain. Factors such as traffic congestion, inefficient delivery routes, and the need for rapid deliveries (e.g., same-day or next-day) significantly increase fuel and labor costs. Additionally, failed deliveries, particularly in rural or difficult-to-access areas, further add to operational expenses. The growing consumer demand for faster and more flexible delivery options, including free or low-cost shipping, has put immense pressure on logistics companies to meet expectations while maintaining profitability. In many cases, the cost of offering expedited deliveries exceeds the revenue generated from the service, leading to thinner profit margins. As competition intensifies and customer expectations continue to rise, companies face the ongoing challenge of balancing service quality with cost efficiency.
Infrastructure Limitations and Urbanization Challenges
Infrastructure limitations and the rapid pace of urbanization in the Asia Pacific region present significant challenges for last mile delivery providers. Many countries, particularly emerging markets in Southeast Asia and South Asia, struggle with inadequate road networks, traffic congestion, and inconsistent address systems, making timely and efficient deliveries difficult. In densely populated urban areas, the lack of proper logistics infrastructure, such as dedicated delivery hubs and optimized roadways, further complicates last mile logistics. Additionally, urbanization is leading to increased population density, which heightens demand for last mile deliveries but creates bottlenecks in transportation networks. In cities with poor infrastructure or inefficient public transportation, delivery vehicles are often delayed, negatively impacting service levels. Overcoming these infrastructure challenges requires significant investment in logistics networks and collaboration with local governments to improve transportation systems. Until these issues are addressed, they will continue to act as constraints on the growth and efficiency of the last mile delivery market in the region.
Market Segmentation Analysis
By Service type
The Asia Pacific Last Mile Delivery Market is segmented into Business-to-Consumer (B2C), Business-to-Business (B2B), and Consumer-to-Consumer (C2C) services. The B2C segment holds the largest share, driven by the rapid expansion of e-commerce and online retail, with increasing consumer demand for timely delivery of products ranging from electronics to groceries. To meet these demands, companies are optimizing routes, enhancing tracking systems, and offering flexible delivery options such as same-day or next-day services. The B2B segment is also growing as e-commerce platforms for business customers rise, requiring reliable delivery services that can handle larger, bulk shipments with strict delivery windows. As businesses continue to digitalize their operations, steady growth in the B2B segment is expected. Meanwhile, the C2C segment, though smaller, is expanding with the growth of peer-to-peer platforms and marketplaces, driving demand for cost-effective, flexible last mile delivery solutions with lower service expectations compared to B2C and B2B segments.
By Application
The Asia Pacific Last Mile Delivery Market is driven by various application segments, each contributing to its growth. The food and beverage segment is expanding rapidly, fueled by the rise of online food delivery platforms and consumer demand for fast, on-demand services, with companies focusing on optimizing delivery times and maintaining product freshness. Retail and e-commerce represent the largest segment, supported by the e-commerce boom in countries like China, India, and Southeast Asia, where the need for fast, reliable deliveries spans diverse products from electronics to apparel. The healthcare segment is also gaining prominence, especially with the demand for timely, secure, and temperature-controlled deliveries of medical supplies and pharmaceuticals, underscored by the COVID-19 pandemic. Additionally, other sectors such as automotive parts, industrial goods, and personal services require specialized last mile delivery solutions, diversifying the market and driving its continued growth.
Segments
Based on Service Type
- Business-to-Consumer (B2C)
- Business-to-Business (B2B)
- Consumer-to-Consumer (C2C)
Based on Application
- Food & Beverages
- Retail & E-commerce
- Healthcare
- Others
Based on Region
- China
- India
- Japan and Southeast Asia
Regional Analysis
China (35%)
China holds the largest share in the Asia Pacific Last Mile Delivery Market, accounting for approximately 35% of the total market. This dominance is fueled by the country’s massive e-commerce industry, which is the largest in the world. With leading e-commerce giants such as Alibaba, JD.com, and Pinduoduo, China has become a hub for last mile delivery innovation. The country’s well-developed logistics infrastructure, combined with technological advancements like AI-driven delivery systems, autonomous vehicles, and drone deliveries, contributes to its leadership position. Urbanization and a high density of online shoppers, particularly in metropolitan areas, have further driven the demand for faster and more reliable last mile solutions.
India (20%)
India is the second-largest market in the region, accounting for approximately 20% of the total market share. The rapid expansion of the e-commerce sector, boosted by players like Flipkart, Amazon India, and Reliance JioMart, has significantly increased the demand for last mile delivery services. India’s growing middle class, coupled with rising internet penetration and smartphone usage, has contributed to a surge in online shopping. However, the market faces challenges in terms of infrastructure, particularly in rural areas, where inconsistent address systems and poor road conditions hinder delivery efficiency. Despite these hurdles, India’s last mile delivery market is projected to grow substantially as infrastructure improves and companies invest in localized delivery networks.
Key players
- DHL Group
- United Parcel Service Inc (UPS)
- FedEx Corp
- com Inc
- Kerry Logistics Network Ltd
- Power Link Expedite
- XPO
- A2Z Drone Delivery
Competitive Analysis
The Asia Pacific Last Mile Delivery Market is highly competitive, with global logistics giants like DHL Group, UPS, and FedEx Corp leading the market through their extensive service networks, advanced technologies, and robust infrastructure. DHL, with its vast product portfolio and strong financials, focuses on sustainable and innovative last mile solutions. UPS and FedEx emphasize efficiency and precision in their deliveries, leveraging advanced tracking and automation technologies. Amazon.com Inc is a disruptive player, transforming the market through its dedicated logistics arm and aggressive investment in faster, more flexible delivery services, including drones. Regional players like Kerry Logistics Network Ltd and Power Link Expedite focus on localized strategies, addressing specific market needs in Asia with tailored solutions. XPO and A2Z Drone Delivery are also making strides by incorporating cutting-edge technologies like AI, drones, and automation to improve efficiency and meet the growing demand for faster, cost-effective last mile services.
Recent Developments
- In January 2024, DHL Global Forwarding completed the acquisition of shares in Danzas AEI Emirates, rebranding all facilities to DHL. This integration enhances operational capabilities in the UAE, GCC, and MEA regions, strengthening DHL's position in freight forwarding and logistics in Dubai.
- In April 2024, UPS launched a new flight connecting its intra-Asia hub in Shenzhen to Sydney Kingsford Smith Airport, offering next-day delivery between Asia and Australia. This service improvement covers mainland China, Japan, South Korea, Taiwan, Malaysia, the Philippines, Singapore, Thailand, Vietnam, Indonesia, and Hong Kong.
- In October 2024, FedEx expanded its electric vehicle fleet in Thailand, introducing four new zero-tailpipe emissions electric vehicles to support parcel pickup and delivery operations in high-traffic areas of Bangkok and Pathum Thani.
- In March 2024, Kerry Logistics Network launched a new air-sea solution between Europe and Oceania, which is 50% cheaper than airfreight and three times faster than sea freight on the same lanes.
- In April 2024, A2Z Drone Delivery announced the immediate availability of several new safety features and hardware upgrades for their commercial drone delivery winch, the RDS2. They also introduced a new weatherproof cover and an auto-releasing bag hook for payload delivery without a recipient present.
Market Concentration and Characteristics
The Asia Pacific Last Mile Delivery Market is characterized by moderate market concentration, with a mix of global logistics giants and regional players competing for market share. Major international companies like DHL, FedEx, UPS, and Amazon dominate the market due to their extensive networks, advanced technological capabilities, and substantial investments in infrastructure. However, regional players such as Kerry Logistics and Power Link Expedite also play a significant role, offering localized solutions tailored to specific market needs in countries like China, India, and Southeast Asia. The market is highly dynamic, with increasing adoption of innovative technologies such as AI, automation, and drones, alongside a strong focus on sustainability. This competitive landscape encourages continuous innovation and efficiency improvements, as companies strive to meet rising consumer demands for faster, more flexible, and eco-friendly delivery services.
Report Coverage
The research report offers an in-depth analysis based on Deployment Service Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Asia Pacific last mile delivery market will see sustained growth, driven by the continued expansion of e-commerce platforms, especially in China, India, and Southeast Asia.
- Logistics companies will increasingly adopt automation technologies such as robotics, AI, and autonomous vehicles to enhance delivery speed, efficiency, and cost-effectiveness.
- Consumer demand for same-day and next-day delivery services will surge, pushing companies to optimize their last mile operations for faster and more reliable delivery times.
- The focus on sustainability will grow, with companies adopting electric vehicles (EVs), bicycles, and other eco-friendly delivery methods to reduce carbon emissions and align with environmental regulations.
- To meet the demand for faster deliveries, companies will invest in urban fulfillment centers and micro-warehouses, enabling quicker dispatch and shorter delivery times in dense urban areas.
- Advanced technologies like AI, IoT, and real-time tracking will become standard in last mile delivery operations, improving transparency and enhancing the overall customer experience.
- The use of drones and autonomous vehicles will expand, especially in urban areas, reducing delivery times and bypassing traffic challenges.
- In addition to B2C services, the B2B and healthcare delivery segments will see significant growth, as businesses and healthcare providers increasingly rely on efficient last mile logistics.
- The competitive landscape will intensify, with global players like DHL, FedEx, and Amazon expanding their presence, while regional players focus on localized, cost-effective solutions.
- Governments in emerging markets like India and Southeast Asia will invest in improving logistics infrastructure, including road networks and address systems, enhancing last mile delivery efficiency in these regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Expansion of E-commerce and Digital Retail Platforms
The surge in e-commerce across Asia Pacific, driven by rising internet penetration, smartphone adoption, and a growing middle class, is fueling demand for efficient last mile delivery services. This trend is further intensified by the diversification of online retail into groceries, food, and pharmaceuticals, requiring robust logistics solutions.
Advancements in Technology and Innovation in Logistics Solutions
Integration of AI, IoT, automation, and data analytics is enabling logistics companies to optimize routes, improve real-time tracking, and enhance delivery efficiency. The adoption of drones, autonomous vehicles, and smart lockers is helping address urban congestion and labor shortages, making last mile delivery faster and more reliable.
Rising Consumer Demand for Fast and Convenient Deliveries
Consumers in urban Asia Pacific increasingly expect same-day or next-day delivery, especially for food, groceries, and retail goods. This demand is pushing logistics providers to invest in urban fulfillment centers, micro-warehouses, and flexible delivery options to meet tight delivery windows and enhance customer satisfaction.
Government Initiatives and Sustainability Goals
Regional governments are investing in logistics infrastructure and promoting sustainable practices, such as the adoption of electric vehicles and green delivery methods. These initiatives help reduce carbon emissions and align with both regulatory requirements and consumer preferences for eco-friendly delivery.
Urbanization and Infrastructure Development
Rapid urbanization in major Asia Pacific cities is increasing the density of online shoppers and creating new challenges for last mile logistics. Investments in road networks, address systems, and urban logistics hubs are essential for overcoming congestion and ensuring timely deliveries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Asia Pacific Last Mile Delivery Market in 2023, andwhat is it projected to reach by 2032?
What are the key drivers of the Asia Pacific Last Mile Delivery Market?
How is the food and beverage segment contributing to the market growth?
What technological trends are shaping the Asia Pacific Last Mile Delivery Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Food & Beverages
- 1.2.2 Retail & E-commerce
- 1.2.3 Healthcare
- 1.2.4 Others
- 1.3 By Service Type
- 1.3.1 Business-to-Consumer (B2C)
- 1.3.2 Business-to-Business (B2B)
- 1.3.3 Consumer-to-Consumer (C2C)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 48,933.28 million → 2032: USD 1,07,769.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Last Mile Delivery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Last Mile Delivery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Last Mile Delivery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Last Mile Delivery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Last Mile Delivery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Last Mile Delivery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Last Mile Delivery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Last Mile Delivery Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 48,933.28 million → 2032: USD 1,07,769.61 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Last Mile Delivery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverages
- 12.3.7.2 Retail & E-commerce
- 12.3.7.3 Healthcare
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Business-to-Consumer (B2C)
- 12.4.7.2 Business-to-Business (B2B)
- 12.4.7.3 Consumer-to-Consumer (C2C)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Last Mile Delivery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Last Mile Delivery Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Last Mile Delivery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Last Mile Delivery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DHL Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 United Parcel Service Inc (UPS)
- 18.4 FedEx Corp
- 18.5 Amazon.com Inc
- 18.6 Kerry Logistics Network Ltd
- 18.7 Power Link Expedite
- 18.8 SF Express
- 18.9 XPO
- 18.10 A2Z Drone Delivery
- 18.11 JD Logistics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

