
At-Home Pregnancy Testing Market Overview:
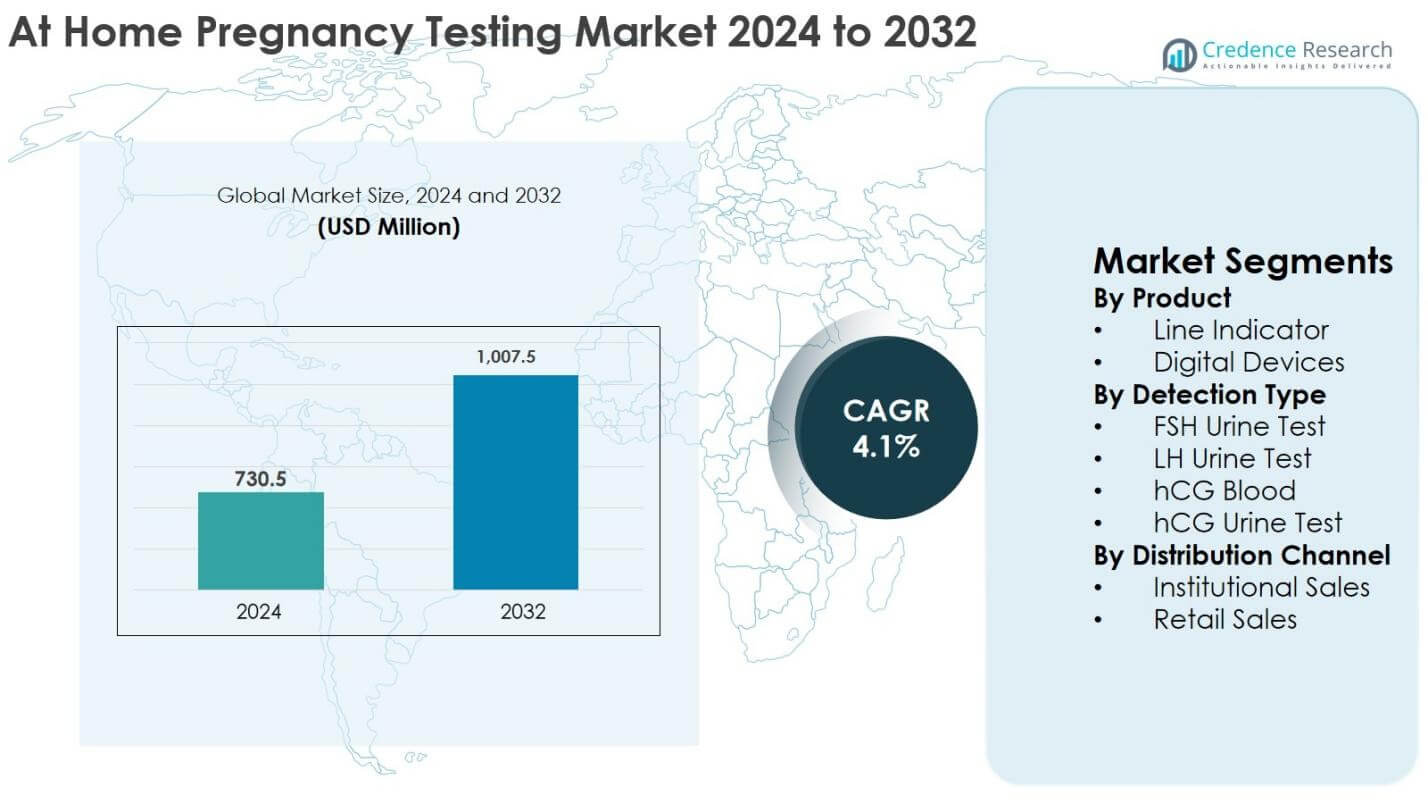
At Home Pregnancy Testing market size was valued at USD 730.5 million in 2024 and is anticipated to reach USD 1,007.5 million by 2032, growing at a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| At Home Pregnancy Testing Market Size 2024 | USD 730.5 million |
| At Home Pregnancy Testing Market, CAGR | 4.1% |
| At Home Pregnancy Testing Market Size 2032 | USD 1,007.5 million |
At-Home Pregnancy Testing Market Insights
- Market growth is driven by rising awareness of early pregnancy detection, increasing preference for privacy and convenience, and strong penetration of over-the-counter diagnostic products, with line indicator tests leading the product segment at 62.4% share due to affordability and ease of use.
- Key market trends include growing adoption of digital pregnancy tests, expansion of e-commerce sales channels, and increasing integration of fertility and cycle-tracking solutions, while hCG urine tests dominate detection type with 68.9% market share.
- The market shows moderate competitive intensity, with global brands focusing on accuracy, brand trust, and wide retail reach, while regional players compete through cost-effective offerings and private-label products.
- Regionally, North America leads with 34.6% market share, followed by Europe at 27.3%, Asia Pacific at 24.1%, Latin America at 8.2%, and Middle East & Africa at 5.8%, reflecting differences in awareness, affordability, and retail infrastructure.
At-Home Pregnancy Testing Market Segmentation Analysis:
By Product
The At Home Pregnancy Testing market by product is led by line indicator tests, which accounted for 62.4% market share in 2024, supported by their affordability, ease of use, and wide availability across retail pharmacies and supermarkets. These products remain the preferred choice among first-time and price-sensitive consumers, particularly in emerging economies. Digital devices held 37.6% share, driven by rising adoption in developed markets due to clear “pregnant/not pregnant” readouts, reduced user error, and increasing consumer preference for technologically advanced and reliable testing solutions.
- For instance, traditional strip and cassette tests sold under brands like Prega News (Mankind Pharma) in India and similar pharmacy-own-label tests in markets such as the UK and US are widely distributed through chain pharmacies and general stores, making them accessible even in semi‑urban and rural areas.
By Detection Type
By detection type, hCG urine tests dominated the At Home Pregnancy Testing market with 68.9% market share in 2024, owing to their high accuracy, non-invasive nature, and suitability for early pregnancy detection. These tests are widely commercialized and supported by strong clinical validation. LH urine tests and FSH urine tests together accounted for 21.3% share, primarily used in fertility tracking and ovulation monitoring. hCG blood tests represented 9.8% share, limited mainly to clinical and confirmatory testing applications.
- For instance, manufacturers highlight laboratory‑evaluated accuracy rates (often marketed as “over 99% accurate from the day of the expected period”) when used as directed, reinforcing consumer trust in hCG urine formats.
By Distribution Channel
Retail sales emerged as the dominant distribution channel, capturing 71.2% market share in 2024, driven by strong pharmacy networks, over-the-counter availability, and increasing consumer reliance on self-diagnostic products. Supermarkets, drugstores, and online pharmacies play a key role in expanding accessibility. Institutional sales accounted for 28.8% share, supported by hospitals, clinics, and diagnostic centers using pregnancy tests for confirmatory screening. Growth in retail channels is further reinforced by discreet purchasing options and rising e-commerce penetration.
Key Growth Drivers
Rising Awareness of Early Pregnancy Detection and Reproductive Health
Increasing awareness of early pregnancy detection and reproductive health management strongly drives the At Home Pregnancy Testing market. Educational initiatives by healthcare providers, public health agencies, and digital health platforms have improved understanding of conception timing and the importance of early confirmation. Women increasingly prefer early testing to support timely lifestyle, nutritional, and medical decisions. This awareness is particularly evident among urban, working, and digitally connected populations seeking quick and discreet solutions. Easy access to reproductive health information through mobile apps and online forums further reinforces adoption. As preventive healthcare and self-monitoring behaviors continue to strengthen globally, at-home pregnancy tests remain a trusted first step, supporting consistent demand growth across developed and emerging markets.
- For instance, organizations such as the WHO and CDC emphasize early prenatal care and timely pregnancy recognition in their maternal health guidance, encouraging women to confirm pregnancy as soon as possible.
Convenience, Privacy, and Ease of Use of At-Home Testing Solutions
Convenience and privacy are core factors accelerating adoption in the At Home Pregnancy Testing market. These products eliminate the need for clinic visits, reducing time, cost, and emotional discomfort. Simple usage steps, rapid results within minutes, and minimal sample requirements enhance user confidence. Privacy is especially important in conservative regions and among younger consumers, where discreet testing is preferred. Manufacturers continue to improve usability through clearer result indicators, ergonomic designs, and improved sensitivity. As self-care and home diagnostics gain broader acceptance, consumers increasingly favor pregnancy tests that integrate seamlessly into daily routines, reinforcing sustained market expansion.
- For instance, brands such as Clearblue and First Response market tests that provide results in about 3 minutes with straightforward, one-step procedures, allowing users to test at home without scheduling appointments.
Expansion of Retail and E-Commerce Distribution Networks
The expansion of retail pharmacies and e-commerce platforms significantly supports market growth. Wide availability of pregnancy tests across drugstores, supermarkets, and online channels has improved accessibility and visibility. E-commerce platforms enable discreet purchasing, competitive pricing, and doorstep delivery, appealing to privacy-conscious consumers. Retailers are also promoting private-label and value-based offerings, increasing affordability and consumer choice. In emerging economies, growth in organized retail and digital commerce has expanded reach beyond major cities. This strengthening distribution ecosystem continues to enhance penetration, volume sales, and overall market scalability.
Key Trends & Opportunities
Shift Toward Digital and Smart Pregnancy Testing Devices
A notable trend in the At Home Pregnancy Testing market is the shift toward digital and smart testing devices. Consumers increasingly prefer digital formats that provide clear, easy-to-read results, minimizing interpretation errors. Integration with mobile applications that track cycles, fertility data, and pregnancy timelines adds further value. These features appeal strongly to tech-savvy users seeking connected and data-driven health solutions. Manufacturers are investing in advanced sensors, user-friendly displays, and app compatibility to differentiate premium offerings. As digital health adoption continues to expand, smart pregnancy tests present strong opportunities for product innovation and higher-margin growth.
- For instance, smart pregnancy and fertility solutions that sync results with apps such as connected thermometers and ovulation systems from Modern Fertility (Ro) or Ava illustrate growing consumer demand for app‑linked, data‑driven reproductive health tools.
Growth Opportunities in Emerging and Underserved Markets
Emerging and underserved markets offer substantial opportunities due to improving healthcare awareness, rising female literacy, and increasing disposable incomes. Government programs and non-governmental initiatives focused on maternal health and early screening are improving acceptance of self-testing solutions. Affordable product variants, localized packaging, and expanded retail outreach are helping manufacturers penetrate rural and semi-urban areas. Cultural shifts toward women’s health autonomy further support demand. As healthcare infrastructure and distribution networks mature, these regions are expected to contribute significantly to future market growth.
- For instance, national safe‑motherhood and reproductive health programs in countries such as India and several sub‑Saharan African nations, often run in collaboration with agencies like UNFPA and UNICEF, promote early pregnancy recognition and community‑level distribution of basic maternal health tools.
Key Challenges
Accuracy Concerns and Consumer Trust Issues
Accuracy-related concerns remain a key challenge in the At Home Pregnancy Testing market. Incorrect usage, testing too early, or inconsistent product quality can result in false readings, undermining consumer trust. In price-sensitive markets, the presence of low-quality alternatives further amplifies skepticism. Discrepancies between home test results and clinical confirmation can discourage repeat use. To address this, manufacturers must focus on stringent quality control, clear usage instructions, and consumer education. Building and maintaining trust through reliability and transparency is critical to sustaining long-term adoption.
Regulatory Compliance and Pricing Pressure
Regulatory compliance and pricing pressure pose additional challenges for market participants. Pregnancy tests are subject to strict quality, safety, and approval standards, increasing development timelines and compliance costs. Navigating varying regulatory frameworks across regions further complicates market entry. Simultaneously, intense competition and low-cost alternatives exert downward pressure on pricing, impacting margins. Balancing affordability, innovation, and regulatory adherence remains a critical strategic challenge. Manufacturers must optimize operational efficiency and regulatory planning to maintain competitiveness while ensuring product safety and performance.
Regional Analysis
North America
North America accounted for 34.6% market share in the At Home Pregnancy Testing market in 2024, driven by high awareness of reproductive health, strong purchasing power, and widespread adoption of self-diagnostic products. Consumers in the United States and Canada favor early pregnancy detection, supported by extensive pharmacy networks and strong online retail penetration. The region also benefits from the availability of advanced digital pregnancy tests and high trust in branded products. Favorable regulatory frameworks and continuous product innovation further support market stability. Demand remains strong among working women seeking convenience, privacy, and rapid results.
Europe
Europe held 27.3% market share in the At Home Pregnancy Testing market in 2024, supported by well-established healthcare systems and strong awareness of women’s health. Countries such as Germany, the UK, and France show high adoption due to easy access through pharmacies and supermarkets. Increasing emphasis on preventive healthcare and reproductive planning continues to drive demand. The region also benefits from the presence of premium digital pregnancy tests and strict quality standards that enhance consumer confidence. Growing acceptance of self-care diagnostics and rising e-commerce usage further contribute to steady market growth across Europe.
Asia Pacific
Asia Pacific captured 24.1% market share in 2024 and represents the fastest-growing region in the At Home Pregnancy Testing market. Rising female literacy, increasing urbanization, and improving access to healthcare products strongly support demand. Countries such as China, India, and Japan are witnessing growing acceptance of self-testing solutions due to expanding retail pharmacies and online platforms. Affordable line indicator tests dominate sales, while digital products are gaining traction in urban centers. Government initiatives focused on maternal health awareness and early pregnancy detection continue to strengthen market penetration across both urban and semi-urban areas.
Latin America
Latin America accounted for 8.2% market share in the At Home Pregnancy Testing market in 2024, driven by improving healthcare awareness and expanding retail distribution networks. Brazil and Mexico are key contributors, supported by growing pharmacy chains and rising demand for affordable diagnostic products. Increasing awareness of early pregnancy care and gradual cultural acceptance of self-testing are supporting adoption. However, price sensitivity remains a key factor, favoring low-cost line indicator tests. Expansion of e-commerce platforms and private-label offerings is improving accessibility, supporting moderate but consistent regional growth.
Middle East & Africa
The Middle East & Africa region held 5.8% market share in 2024, reflecting gradual adoption of at-home pregnancy testing products. Urban areas across the Gulf Cooperation Council countries show higher penetration due to better healthcare access and retail infrastructure. In parts of Africa, growth is supported by rising awareness of maternal health and expanding pharmacy networks, though rural penetration remains limited. Privacy concerns and affordability drive preference for basic line indicator tests. Ongoing improvements in healthcare outreach, retail expansion, and women’s health education are expected to support steady market development across the region.
At-Home Pregnancy Testing Market Segmentations:
By Product
- Line Indicator
- Digital Devices
By Detection Type
- FSH Urine Test
- LH Urine Test
- hCG Blood
- hCG Urine Test
By Distribution Channel
- Institutional Sales
- Retail Sales
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the At Home Pregnancy Testing market is characterized by the presence of well-established global brands and a growing number of regional manufacturers competing on accuracy, brand trust, pricing, and distribution reach. Key players such as Abbott Laboratories, Church & Dwight Co., Inc., Procter & Gamble Co., Quidel Corporation, Prestige Brands Holdings, Inc., Swiss Precision Diagnostics GmbH, bioMérieux SA, Geratherm Medical AG, Mankind Pharma, and Alere Inc. focus on strong retail penetration and continuous product enhancements. Leading companies leverage brand recognition and regulatory compliance to maintain dominance, particularly in North America and Europe. Meanwhile, Asian manufacturers including Hangzhou Laihe Biotech and Yancheng Cordial Medlab are strengthening their positions through cost-competitive offerings and expanding distribution in emerging markets. Product differentiation through digital testing devices, improved sensitivity, and discreet packaging remains central to competitive positioning, while private-label and online sales intensify price competition across regions.
Key Player Analysis
- Hangzhou Laihe Biotech Co., Ltd.
- Abbott Laboratories
- Geratherm Medical AG
- Mankind Pharma
- Swiss Precision Diagnostics GmbH
- Procter & Gamble Co.
- Yancheng Cordial Medlab Co., Ltd.
- Church & Dwight Co., Inc.
- Prestige Brands Holdings, Inc.
- Quidel Corporation
Recent Developments
- In September 2025, the startup Phaeosynt launched “Hey Mela,” the first vegan pregnancy test on the market, designed with plant-based antibodies without animal-derived components, marking product innovation in at-home pregnancy testing.
- In March 2025, Abingdon Health partnered with NeutraPharma and leading German retailers to launch the Salistick saliva-based pregnancy test in major European pharmacies, bringing a novel non-urine based at-home pregnancy test format to consumers.
- In May 2024, Abingdon Health plc launched a Boots-branded saliva pregnancy self-test in the UK and Ireland, expanding distribution of its non-urine based pregnancy test product in retail pharmacy channels.
Report Coverage
The research report offers an in-depth analysis based on Product, Detection Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for at-home pregnancy testing will continue to grow steadily, supported by increasing awareness of early pregnancy confirmation and reproductive health monitoring.
- Line indicator tests will retain strong volume demand due to affordability, while digital tests will gain higher adoption in urban and developed markets.
- Technological improvements will enhance test sensitivity and accuracy, supporting earlier pregnancy detection and improved user confidence.
- E-commerce and online pharmacy channels will play a larger role in product distribution, driven by convenience and discreet purchasing preferences.
- Emerging economies will witness faster adoption as healthcare access, female literacy, and self-care awareness improve.
- Manufacturers will focus on user-friendly designs and clearer result displays to reduce interpretation errors.
- Private-label and store-brand products will increase competition, particularly in price-sensitive markets.
- Regulatory compliance and quality assurance will remain critical for maintaining brand trust and market acceptance.
- Strategic partnerships with digital health platforms will support product differentiation and consumer engagement.
- Growing emphasis on women’s health autonomy will continue to strengthen long-term market outlook.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Awareness of Early Pregnancy Detection and Reproductive Health
Educational initiatives and digital health platforms have increased understanding of conception timing and the importance of early pregnancy confirmation, leading more women to use at-home pregnancy tests for timely lifestyle and medical decisions.
Convenience, Privacy, and Ease of Use
At-home pregnancy tests offer a discreet, quick, and simple alternative to clinic visits, appealing especially to younger and privacy-conscious consumers and driving adoption across both developed and emerging markets.
Expansion of Retail and E-Commerce Distribution Networks
Wider availability through pharmacies, supermarkets, and online channels has improved accessibility and visibility, while e-commerce enables discreet purchasing and competitive pricing, further boosting market penetration.
Shift Toward Digital and Smart Testing Devices
Consumers are increasingly adopting digital pregnancy tests for their clear results and integration with mobile apps, reducing user error and supporting the trend toward connected, data-driven reproductive health solutions.
Growth Opportunities in Emerging and Underserved Markets
Improving healthcare awareness, rising female literacy, and expanding retail infrastructure in emerging economies are enabling greater adoption of at-home pregnancy tests, especially as governments and NGOs promote early pregnancy recognition.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for At Home Pregnancy Testing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the At Home Pregnancy Testing market projected to grow between 2024 and 2032?
Which At Home Pregnancy Testing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the At Home Pregnancy Testing market?
Who are the leading companies in the At Home Pregnancy Testing market?
Which region commanded the largest share of the At Home Pregnancy Testing market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Line Indicator
- 1.2.2 Digital Devices
- 1.3 By Detection Type
- 1.3.1 FSH Urine Test
- 1.3.2 LH Urine Test
- 1.3.3 hCG Blood
- 1.3.4 hCG Urine Test
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 730.5 million → 2032: USD 1,007.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global At-Home Pregnancy Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global At-Home Pregnancy Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global At-Home Pregnancy Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global At-Home Pregnancy Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global At-Home Pregnancy Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global At-Home Pregnancy Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global At-Home Pregnancy Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global At-Home Pregnancy Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 730.5 million → 2032: USD 1,007.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global At-Home Pregnancy Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Line Indicator
- 12.3.7.2 Digital Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Detection Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 FSH Urine Test
- 12.4.7.2 LH Urine Test
- 12.4.7.3 hCG Blood
- 12.4.7.4 hCG Urine Test
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global At-Home Pregnancy Testing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global At-Home Pregnancy Testing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global At-Home Pregnancy Testing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Abbott Laboratories
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Church & Dwight Co., Inc.
- 17.4 Procter & Gamble Co.
- 17.5 Quidel Corporation
- 17.6 Prestige Brands Holdings, Inc.
- 17.7 Swiss Precision Diagnostics GmbH
- 17.8 bioMérieux SA
- 17.9 Geratherm Medical AG
- 17.10 Mankind Pharma
- 17.11 Hangzhou Laihe Biotech Co., Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

