
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| At-Home Cancer Testing Market Size 2024 | USD 8,047.53 million |
| At-Home Cancer Testing Market, CAGR | 4.33% |
| At-Home Cancer Testing Market Size 2032 | USD 11,576.07 million |
Market Overview
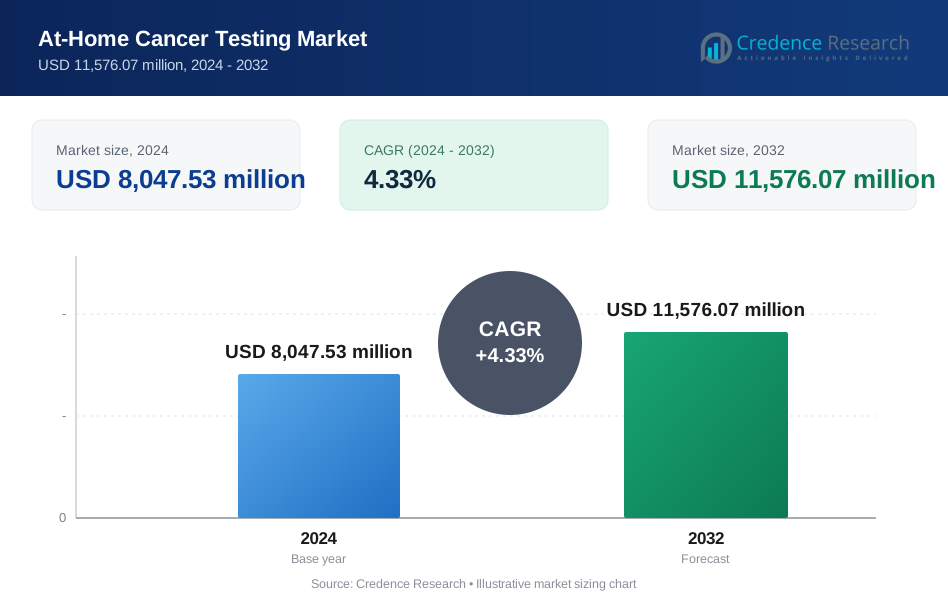
The At-Home Cancer Testing Market size was valued at USD 6,037.48 million in 2018, reached USD 8,047.53 million in 2024, and is anticipated to reach USD 11,576.07 million by 2032, growing at a CAGR of 4.33% during the forecast period.
The At-Home Cancer Testing market is highly competitive, with key players such as Exact Sciences Corporation, Guardant Health, Grail, Inc., Everlywell, Natera, Illumina Inc., Cisco, Myriad Genetics Inc., NeoGenomics Laboratories, and Freenome Holdings Inc. driving innovation and market expansion. These companies focus on developing advanced, user-friendly diagnostic solutions, leveraging technologies like liquid biopsy, genetic screening, and direct-to-consumer platforms. North America leads the market, accounting for approximately 32.1% of the global share in 2024, driven by high consumer awareness, advanced healthcare infrastructure, and early adoption of home-based diagnostics. Asia Pacific follows closely with significant growth potential, supported by rising cancer prevalence, increasing healthcare investments, and expanding digital health ecosystems.

Market Insights
- The At-Home Cancer Testing market was valued at USD 8,047.53 million in 2024 and is projected to reach USD 11,576.07 million by 2032, growing at a CAGR of 4.33% during the forecast period.
- Rising demand for early cancer detection, increasing awareness of preventive healthcare, and growing preference for home-based testing solutions are key drivers supporting market growth globally.
- The market is witnessing trends such as the rapid expansion of online pharmacies, increasing adoption of direct-to-consumer models, and integration of digital health platforms and telemedicine for seamless patient support.
- Competitive dynamics are shaped by key players like Exact Sciences Corporation, Guardant Health, Grail, Inc., Everlywell, and Natera, focusing on technological advancements, strategic partnerships, and product portfolio expansion to strengthen their market positions.
- North America leads with a 32.1% share in 2024, followed by Asia Pacific with 41.5%; the blood sample segment holds the largest market share due to its ease of use and higher accuracy.
Market Segmentation Analysis:
By Cancer Type
In the At-Home Cancer Testing market, the colon cancer segment holds the largest market share, driven by the rising prevalence of colorectal cancer and the increasing demand for early detection methods. Colon cancer tests are widely accepted due to their non-invasive nature and their ability to detect cancer at an early stage, significantly improving survival rates. The convenience of home-based stool DNA testing kits and growing awareness of routine screening among the aging population further support the segment’s dominance. Continuous advancements in test accuracy and accessibility also contribute to its market leadership.
- For instance, Exact Sciences Corporation’s Cologuard test, a non-invasive stool DNA test, has been used in over 10 million completed screenings in the United States as of 2023, demonstrating widespread adoption and clinical impact.
By Sample Type
The blood sample segment dominates the At-Home Cancer Testing market, accounting for the highest market share owing to its ease of collection, high patient compliance, and increasing preference for minimally invasive procedures. Blood-based tests, particularly liquid biopsies, offer efficient detection of multiple cancer types with high accuracy and faster turnaround times. Technological advancements in biomarker identification and the growing availability of blood-based home testing kits are further propelling this segment’s growth. Additionally, healthcare providers and patients increasingly prefer blood samples for their reliability in monitoring disease progression and treatment effectiveness.
- For instance, Guardant Health’s Guardant360 liquid biopsy has been utilized in more than 400,000 clinical tests worldwide as of 2023, underscoring the growing preference for blood-based diagnostics in oncology.
By Distribution Channel
Online pharmacies lead the distribution channels in the At-Home Cancer Testing market, capturing the largest market share due to their convenience, wide product availability, and discrete purchasing options. The rapid expansion of e-commerce platforms and improved access to home testing kits have significantly boosted online sales. Additionally, rising consumer trust in digital health solutions and the availability of direct-to-consumer cancer testing kits have further accelerated segment growth. The ease of home delivery and the increasing preference for privacy and self-management in health monitoring are key drivers sustaining the dominance of online pharmacies.
Market Overview
Rising Demand for Early Cancer Detection
The increasing focus on early diagnosis is a major growth driver in the At-Home Cancer Testing market. Early detection significantly improves survival rates and treatment outcomes, encouraging individuals to adopt convenient home-based testing solutions. Growing public awareness, supported by government and non-profit initiatives, is further promoting preventive healthcare practices. The shift towards proactive health monitoring, combined with the aging global population prone to cancer risks, is accelerating the demand for accessible, timely, and user-friendly at-home cancer detection kits.
- For instance, Grail, Inc.’s Galleri multi-cancer early detection test has screened over 60,000 patients as part of its PATHFINDER and REFLECTION clinical programs by 2023, reflecting the strong consumer and clinical interest in early cancer detection.
Advancements in Testing Technologies
Technological advancements, particularly in liquid biopsy, biomarker identification, and genetic testing, are driving the At-Home Cancer Testing market forward. Innovations have improved the accuracy, sensitivity, and reliability of home testing kits, making them competitive with traditional diagnostic methods. These advancements allow for multi-cancer detection from a single sample and enable faster processing times. The integration of digital platforms and AI for result interpretation further enhances the consumer experience, strengthening trust and adoption rates across diverse population groups.
- For instance, Illumina’s NovaSeq 6000 platform can sequence up to 48 whole human genomes in under two days, enabling high-throughput genomic analysis that supports the rapid development of at-home genetic cancer screening solutions.
Growing Preference for Home-Based Healthcare Solutions
The preference for home-based healthcare has surged, especially post-pandemic, fostering significant growth in the At-Home Cancer Testing market. Consumers increasingly value privacy, convenience, and reduced exposure to clinical settings. This trend is amplified by busy lifestyles, rising healthcare costs, and improved access to over-the-counter and online testing kits. Direct-to-consumer models empower individuals to take charge of their health, which is particularly attractive to those seeking discreet cancer screening options without the need for extensive hospital visits or consultations.
Key Trends & Opportunities
Expansion of Online Distribution Channels
The rapid growth of online pharmacies and e-commerce platforms presents a key opportunity in the At-Home Cancer Testing market. Online availability enhances accessibility and supports discreet purchasing, encouraging consumer adoption. Partnerships between test manufacturers and digital health platforms further streamline product distribution and awareness. With the increasing use of mobile apps and telehealth services, online channels offer an efficient pathway for consumers to order, use, and receive guidance on at-home cancer testing kits, boosting market penetration.
- For instance, Everlywell has distributed over 2 million at-home health test kits, including cancer screening products, through its online platform as of 2023, making it one of the largest direct-to-consumer testing providers in the U.S.
Integration of Telehealth and Digital Platforms
The integration of telehealth services and digital reporting platforms is transforming the At-Home Cancer Testing market. Consumers now expect seamless digital experiences, including online consultations, virtual result discussions, and real-time guidance. This trend not only improves patient engagement but also enhances test accuracy through professional oversight. Companies leveraging telemedicine can build trust and offer added value, providing a comprehensive at-home diagnostic ecosystem that appeals to a tech-savvy consumer base and expands market growth opportunities.
- For instance, Myriad Genetics launched its digital platform, Myriad Complete, in 2023, which has processed over 100,000 virtual consultations, providing patients with remote access to genetic counselors and test interpretation services.
Key Challenges
Regulatory and Quality Assurance Complexities
The At-Home Cancer Testing market faces stringent regulatory hurdles related to product approvals, accuracy standards, and consumer safety. Ensuring test reliability outside clinical settings presents a major challenge, as home users may not always follow procedures correctly. Regulatory bodies require extensive validation and compliance, often leading to delayed market entry. Continuous monitoring, post-market surveillance, and ensuring consistency in home-use environments remain critical concerns for manufacturers aiming to sustain credibility and consumer trust.
Limited Awareness and Accessibility in Developing Regions
Despite growing global demand, limited awareness and accessibility in low- and middle-income countries pose significant challenges. Factors such as lack of consumer education, low digital penetration, and insufficient distribution networks restrict market growth in these regions. Additionally, cultural stigma surrounding cancer and home diagnostics can hinder adoption. Companies must invest in targeted awareness campaigns and affordable product offerings to overcome these barriers and unlock untapped potential in emerging markets.
Risk of Misinterpretation and False Results
One of the key challenges in the At-Home Cancer Testing market is the risk of users misinterpreting results, leading to false reassurance or unnecessary anxiety. Unlike clinical settings where professionals guide the process, home testing relies heavily on user accuracy and understanding. False positives or negatives can result in either overlooked treatment or undue psychological stress. Addressing this issue requires robust user instructions, follow-up telehealth support, and the development of highly intuitive testing kits to minimize user error.
Regional Analysis
North America
In 2018, North America accounted for USD 1,939.42 million in the At-Home Cancer Testing market, holding a market share of approximately 32.1%. The region's market is projected to reach USD 2,548.61 million in 2024 and is anticipated to grow to USD 3,679.98 million by 2032, registering a CAGR of 4.4% during the forecast period. North America maintains its dominance due to advanced healthcare infrastructure, high consumer awareness, and early adoption of home-based health technologies. The increasing prevalence of cancer and the expansion of direct-to-consumer testing services further support sustained regional growth.
Europe
Europe held a market value of USD 1,131.73 million in 2018, contributing around 18.7% to the global At-Home Cancer Testing market. By 2024, the market is expected to reach USD 1,426.21 million and is projected to grow to USD 1,866.33 million by 2032, with a CAGR of 3.1%. The region’s growth is driven by rising cancer incidence, growing preference for home-based screening, and supportive government initiatives promoting early detection. However, regulatory complexities and cost concerns somewhat moderate growth, despite the increasing availability of advanced home testing kits across key European countries.
Asia Pacific
Asia Pacific dominated the global market in 2018, valued at USD 2,405.63 million and commanding the largest market share of approximately 39.8%. The market is forecasted to reach USD 3,336.39 million in 2024 and USD 5,119.23 million by 2032, expanding at the fastest CAGR of 5.2%. Rapid urbanization, increasing healthcare awareness, and a growing middle-class population are key drivers of regional growth. Additionally, the rising burden of cancer and growing digital health adoption across countries such as China, India, and Japan significantly contribute to the strong market potential in this region.
Latin America
Latin America accounted for USD 279.78 million in 2018, representing about 4.6% of the global At-Home Cancer Testing market. By 2024, the market is expected to reach USD 368.20 million and is projected to grow to USD 467.59 million by 2032, at a CAGR of 2.7%. The region’s growth is supported by improving healthcare access, gradual adoption of home testing solutions, and increasing cancer awareness initiatives. However, limited consumer awareness in rural areas and affordability concerns may restrict faster market penetration compared to more developed regions.
Middle East
The At-Home Cancer Testing market in the Middle East was valued at USD 171.77 million in 2018, capturing approximately 2.8% of the global market share. The market is estimated to grow to USD 209.59 million in 2024 and reach USD 255.18 million by 2032, registering a CAGR of 2.2%. Growing investments in healthcare infrastructure and the gradual adoption of advanced diagnostic technologies are driving market expansion. Nevertheless, the uptake of home-based cancer testing remains limited due to lower awareness and cultural hesitancy toward self-diagnosis, posing moderate growth challenges.
Africa
Africa contributed USD 109.16 million to the At-Home Cancer Testing market in 2018, holding the smallest market share of approximately 1.8%. The market is forecasted to reach USD 158.54 million in 2024 and is anticipated to grow to USD 187.78 million by 2032, at a modest CAGR of 1.8%. While awareness about cancer and home diagnostic options is gradually increasing, significant barriers such as limited healthcare infrastructure, low affordability, and insufficient distribution channels hinder widespread adoption. The region offers potential for growth, but requires substantial investment in awareness programs and healthcare accessibility.

Market Segmentations:
By Cancer Type
- Colon
- Breast
- Prostate
- Blood
- Bladder
- Others
By Sample Type
- Blood
- Urine
- Cell
- Stool
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The At-Home Cancer Testing market is characterized by the presence of several key players actively engaged in developing innovative, user-friendly diagnostic solutions. Companies such as Exact Sciences Corporation, Guardant Health, Grail, Inc., Everlywell, and Natera are focusing on expanding their product portfolios to cover a wider range of cancer types, including colon, breast, and prostate cancers. Market leaders are leveraging technological advancements like liquid biopsy, genetic screening, and AI-driven diagnostics to improve accuracy and convenience. Strategic collaborations, acquisitions, and partnerships are common approaches to enhance distribution networks and accelerate market penetration. Additionally, players like Illumina Inc. and Myriad Genetics Inc. are investing significantly in research and development to maintain competitive advantage. The growing trend of direct-to-consumer models and the expansion of online sales channels further intensify competition. Continuous product innovation and regulatory approvals remain crucial factors shaping the competitive dynamics in this rapidly evolving market.
Key Player Analysis
- Exact Sciences Corporation
- Guardant Health
- Grail, Inc.
- Everlywell
- Natera
- Illumina Inc.
- Cisco
- Myriad Genetics Inc.
- NeoGenomics Laboratories
- Freenome Holdings Inc.
Recent Developments
- In June 2025, GRAIL announced positive preliminary results from the PATHFINDER 2 study of its Galleri multi-cancer early detection (MCED) blood test. The study showed improved cancer detection and predictive accuracy compared to previous studies. GRAIL is preparing to submit these results to the FDA to seek full marketing approval for the Galleri test.
- In June 2025, Everlywell announced a collaboration with Grail to offer the Galleri MCED test via prescription through Everlywell’s online platform, expanding at-home access to this multi-cancer blood test.
- In May 2025, Guardant Health launched the Guardant Hereditary Cancer test, a blood-based germline panel designed to identify inherited genetic variants linked to cancer risk. This test analyzes 82 genes across more than 12 tumor types, aiding in personalized cancer screening and prevention strategies. It helps identify individuals with an elevated risk for certain cancers, enabling tailored screening and preventative measures.
- In April 2025, Exact Sciences was indeed a prominent player in the multi-cancer early detection (MCED) market, specifically focusing on blood-based minimal residual disease (MRD) tests. They were actively developing these tests and were planning to launch their own competitor, Oncodetect™, in the second quarter of 2025.
Market Concentration & Characteristics
The At-Home Cancer Testing Market demonstrates a moderately concentrated structure with a mix of established diagnostic companies and emerging technology-driven players. It features strong competition among key participants such as Exact Sciences Corporation, Guardant Health, Grail, Inc., Everlywell, and Natera, each focusing on expanding their product portfolios and improving test accuracy. The market shows high barriers to entry due to strict regulatory standards and the need for proven clinical efficacy. It benefits from the growing consumer shift toward personalized healthcare and self-monitoring solutions, which continue to support steady demand. It relies heavily on technological innovation, with companies introducing user-friendly kits, digital reporting, and telehealth integration to strengthen market presence. The market is shaped by the rising importance of convenience and privacy in cancer screening, which drives consumers toward home-based solutions. Strong regional concentration is evident in North America and Asia Pacific, where consumer awareness, digital infrastructure, and cancer prevalence create favorable growth environments.
Report Coverage
The research report offers an in-depth analysis based on Cancer Type, Sample Type, Distribution Channel, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The At-Home Cancer Testing market is expected to grow steadily with increasing consumer preference for convenient and non-invasive cancer screening solutions.
- Advances in liquid biopsy and genetic testing technologies will significantly improve test accuracy and broaden cancer detection capabilities.
- The direct-to-consumer model will become more dominant as companies focus on offering easy-to-use home testing kits with digital support.
- Integration of telehealth services and mobile health applications will enhance user engagement and facilitate real-time consultation and result interpretation.
- Online pharmacies and e-commerce platforms will continue to expand, offering wider access to at-home cancer testing kits globally.
- North America will maintain a strong market presence due to high consumer awareness, while Asia Pacific will emerge as the fastest-growing region driven by healthcare advancements and rising cancer cases.
- Companies will prioritize partnerships and collaborations to strengthen distribution networks and expand their global reach.
- The blood sample segment will remain the preferred testing method due to its simplicity, accuracy, and wide application range.
- Continuous efforts to improve affordability and accessibility will increase product penetration in developing regions.
- Regulatory approvals and quality assurance will remain critical factors influencing new product launches and market entry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Early Cancer Detection Focus
The increasing emphasis on early diagnosis significantly improves survival rates and treatment outcomes, driving adoption of at-home cancer testing solutions as individuals seek convenient and timely screening options.
Technological Advancements in Testing
Innovations in liquid biopsy, genetic screening, and biomarker identification have enhanced the accuracy, sensitivity, and reliability of at-home cancer tests, making them more competitive with traditional diagnostics and expanding their use for multi-cancer detection.
Expansion of Online Pharmacies and Direct-to-Consumer Models
The rapid growth of e-commerce and online pharmacies has made at-home cancer testing kits more accessible, supporting discreet purchasing and encouraging consumer adoption, especially among those seeking privacy and convenience.
Integration of Digital Health and Telemedicine
The incorporation of telehealth services and digital reporting platforms enables seamless patient support, real-time result interpretation, and virtual consultations, which increases user engagement and trust in at-home testing.
Rising Healthcare Awareness and Preventive Screening
Growing public awareness campaigns, government initiatives, and the aging global population have heightened the focus on preventive healthcare, leading to increased demand for accessible, user-friendly at-home cancer detection kits.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the At-Home Cancer Testing Market?
What are the key segments within the At-Home Cancer Testing Market?
What are some challenges faced by the At-Home Cancer Testing Market?
Who are the major players in the At-Home Cancer Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cancer Type
- 1.2.1 Colon
- 1.2.2 Breast
- 1.2.3 Prostate
- 1.2.4 Blood
- 1.2.5 Bladder
- 1.2.6 Others
- 1.3 By Sample Type
- 1.3.1 Blood
- 1.3.2 Urine
- 1.3.3 Cell
- 1.3.4 Stool
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,047.53 million → 2032: USD 11,576.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global At-Home Cancer Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global At-Home Cancer Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global At-Home Cancer Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global At-Home Cancer Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global At-Home Cancer Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global At-Home Cancer Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global At-Home Cancer Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global At-Home Cancer Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,047.53 million → 2032: USD 11,576.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global At-Home Cancer Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cancer Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Colon
- 12.3.7.2 Breast
- 12.3.7.3 Prostate
- 12.3.7.4 Blood
- 12.3.7.5 Bladder
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sample Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Blood
- 12.4.7.2 Urine
- 12.4.7.3 Cell
- 12.4.7.4 Stool
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global At-Home Cancer Testing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global At-Home Cancer Testing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global At-Home Cancer Testing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Exact Sciences Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Guardant Health
- 17.4 Grail, Inc.
- 17.5 Everlywell
- 17.6 Natera
- 17.7 Illumina Inc.
- 17.8 Myriad Genetics Inc.
- 17.9 NeoGenomics Laboratories
- 17.10 Freenome Holdings Inc.
- 17.11 Cisco
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
