
Market Overview:
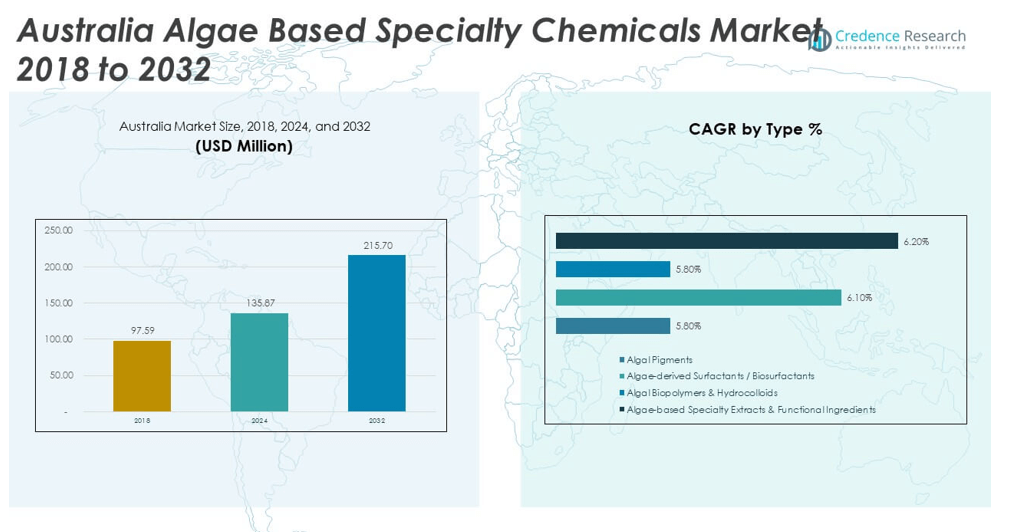
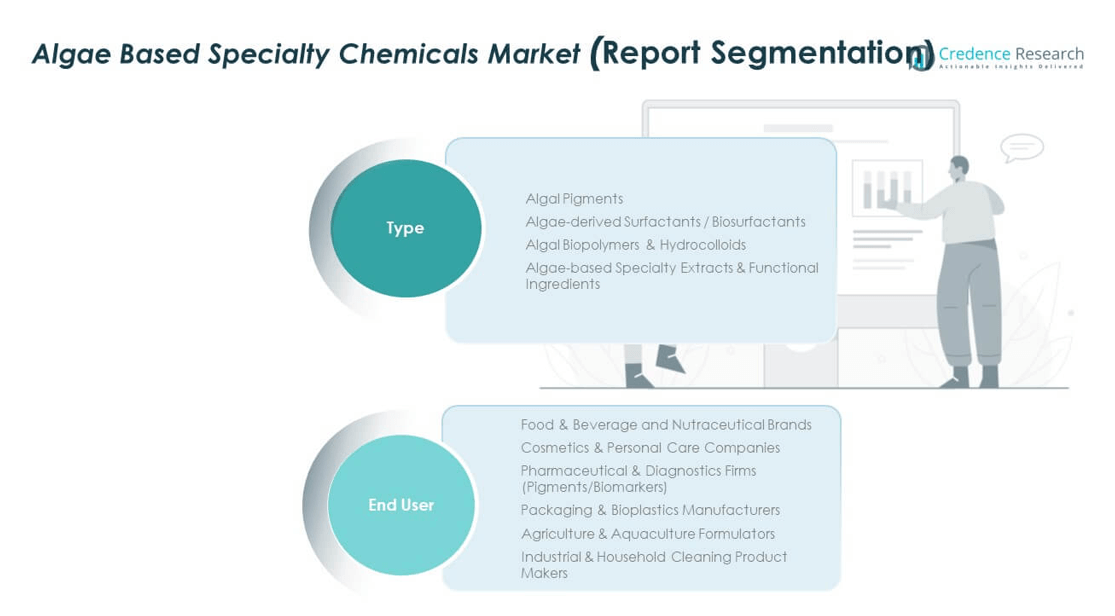
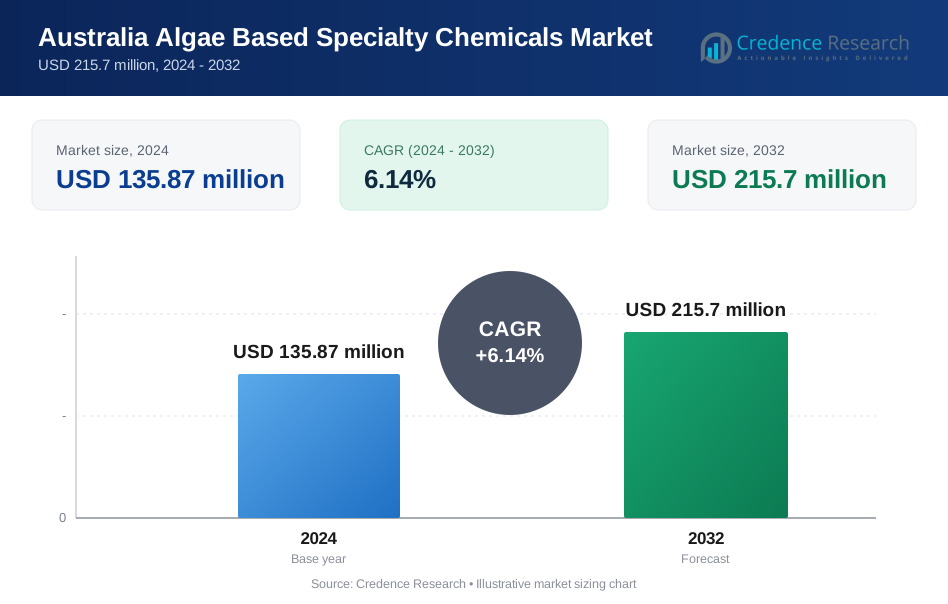
The Australia Algae Based Specialty Chemicals Market size was valued at USD 97.59 million in 2018 to USD 135.87 million in 2024 and is anticipated to reach USD 215.7 million by 2032, at a CAGR of 6.14% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Algae Based Specialty Chemicals Market Size 2024 | USD 135.87 million |
| Australia Algae Based Specialty Chemicals Market, CAGR | 6.14% |
| Australia Algae Based Specialty Chemicals Market Size 2032 | USD 215.7 million |
Growth in the market is driven by rising demand for sustainable and renewable raw materials across multiple industries. Algae-based specialty chemicals offer applications in pharmaceuticals, food and beverages, cosmetics, and agriculture. Companies are investing in advanced cultivation and extraction technologies to improve scalability and efficiency. Government policies promoting eco-friendly products further support adoption. Increasing consumer awareness of clean-label ingredients and bio-based solutions strengthens industry growth. Manufacturers leverage algae’s versatility to produce pigments, biopolymers, and functional ingredients. This trend positions algae as a reliable alternative to petroleum-based chemicals.
Regionally, Eastern Australia leads due to strong industrial clusters, advanced biotechnology research, and access to coastal resources that support algae cultivation. Southern Australia shows significant growth potential with applications in agriculture, aquaculture, and bioplastics. Western and Northern regions are emerging markets, benefiting from aquaculture development and government-backed diversification projects. Neighboring countries like China, India, and Japan strengthen regional collaboration through trade and research partnerships. It benefits from proximity to these markets, enhancing its export potential. This geographic spread highlights a balanced market structure with established hubs and emerging growth zones.
Market Insights
- The Australia Algae Based Specialty Chemicals Market was valued at USD 97.59 million in 2018, grew to USD 135.87 million in 2024, and is projected to reach USD 215.7 million by 2032, at a CAGR of 6.14%.
- Eastern Australia accounted for 42% of the market in 2024, supported by industrial clusters, coastal resources, and biotechnology research, while Southern Australia followed with 33% driven by agriculture and aquaculture.
- Western and Northern Australia jointly represented 25% share, benefiting from aquaculture development and government-backed initiatives, though still limited in large-scale infrastructure.
- Algal pigments held the largest share at 38% of the total market in 2024, driven by strong use in pharmaceuticals, nutraceuticals, and cosmetics.
- Algal biopolymers and hydrocolloids accounted for 27% share, supported by their rising role in packaging, food processing, and bio-based material applications.
Market Drivers
Rising Preference for Sustainable Alternatives Across Industrial Applications
The Australia Algae Based Specialty Chemicals Market benefits from industries replacing petroleum-based products with eco-friendly alternatives. Algae-derived compounds reduce dependency on finite fossil resources and lower carbon footprints. Demand from pharmaceuticals, agriculture, and cosmetics encourages research in product diversification. Manufacturers view algae as a sustainable raw material that can support long-term supply security. Policy initiatives favor renewable feedstocks and create stable demand. Industrial end-users prioritize materials that meet environmental compliance standards. The increasing focus on sustainability strengthens investment in scalable algae processing technologies. This transformation positions algae-based products as viable industrial inputs.
- For example, Aurora Algae operated a demonstration facility in Karratha, Western Australia, featuring six open ponds that produced up to 15 tonnes of dried algal biomass per month, supplying industries such as nutraceuticals, aquaculture, and pharmaceuticals.
Government Policies Encouraging Bio-Based Chemical Development
Supportive regulations and national strategies push investments in renewable chemical development. Subsidies for clean technology adoption encourage production expansion. It supports companies aiming to achieve environmental targets. Government partnerships promote large-scale algae cultivation in coastal zones. National agencies emphasize reducing industrial emissions by replacing traditional chemicals with bio-based options. The Australia Algae Based Specialty Chemicals Market aligns with these long-term policies. Incentives for renewable feedstock development encourage innovation and infrastructure growth. Policy stability ensures investor confidence in this emerging chemical domain.
- For example, MBD Energy, with support from the Australian government’s CRC Mining initiative, developed a proof-of-concept algae biosequestration facility at Tarong Power Station in Queensland that used coal-fired flue gas to cultivate microalgae for biomass and by-product research.
Advancements in Algae Cultivation and Extraction Technologies
Breakthroughs in photobioreactor designs and harvesting methods improve production efficiency. Modern extraction techniques ensure higher purity levels and consistent output. Enhanced cultivation technologies reduce operational costs and expand industrial scalability. These advances make algae-based chemicals more competitive with synthetic substitutes. Integration of automation improves yield monitoring and reduces waste levels. Pilot projects highlight promising commercial applications across varied sectors. The Australia Algae Based Specialty Chemicals Market leverages these innovations to attract industry partnerships. Continuous R&D ensures greater adaptability in production systems.
Consumer Awareness Driving Demand for Green and Natural Products
Shifting consumer preferences influence the chemical industry to adopt bio-based formulations. Natural and safe product attributes drive demand in personal care and nutraceuticals. Food producers integrate algae-based additives for health-conscious buyers. Retailers highlight eco-friendly products to match consumer expectations. Public awareness campaigns about sustainable sourcing add credibility to algae-based solutions. This growing preference accelerates industry interest in reliable supply chains. The Australia Algae Based Specialty Chemicals Market gains momentum from customer-driven sustainability trends. It motivates companies to strengthen transparency and traceability in production.
Market Trends
Expanding Role of Algae-Based Ingredients in High-Value Personal Care Segments
Cosmetics and skincare industries integrate algae-derived compounds for moisturizing and antioxidant properties. These bioactive materials enhance product safety while supporting premium positioning. Personal care companies market algae-based solutions to attract eco-conscious consumers. New formulations in sunscreens and anti-aging creams increase visibility of algae-based innovation. Demand for marine-sourced active ingredients boosts R&D partnerships. The Australia Algae Based Specialty Chemicals Market benefits from such consumer-focused innovation. It creates opportunities for localized suppliers to scale and export. The trend ensures algae-based chemicals penetrate long-lasting consumer goods segments.
Integration of Algae-Derived Compounds in Functional Foods and Beverages
Nutraceutical and health beverage producers use algae-derived omega-3s and proteins. These functional compounds strengthen claims of improved nutrition and wellness. The rising interest in plant-based diets supports algae-based food additives. Companies explore fortified beverages and supplements enriched with algae. It enables producers to differentiate products in competitive retail markets. The Australia Algae Based Specialty Chemicals Market finds opportunities in expanding health-focused industries. Supply chain partnerships with food processors enhance commercial success. Functional nutrition remains a long-term trend shaping algae utilization.
- For example, Marinova, an Australian biotechnology company, specializes in extracting fucoidan from brown seaweed and supplies it to global nutrition, functional food, and supplement markets, with active research collaborations evaluating its bioactive efficacy in areas such as immunity, gut health, and healthy aging.
Commercial Adoption of Algae-Based Bioplastics and Packaging Solutions
Bioplastics made from algae provide biodegradable alternatives to conventional plastics. Packaging companies integrate these materials to meet circular economy targets. Governments and brands aim to reduce plastic waste through innovation. Algae-derived polymers offer strength and flexibility for packaging applications. Companies demonstrate algae-based bottles and films at commercial scale. It positions algae chemicals as a vital solution in sustainable packaging markets. The Australia Algae Based Specialty Chemicals Market tracks this demand shift toward eco-friendly materials. The trend accelerates with rising consumer support for biodegradable solutions.
Collaborations Between Research Institutions and Industry Players
Academic institutions partner with companies to accelerate algae-based chemical innovation. Research centers support pilot-scale algae farms with commercial viability studies. Industry groups fund projects to identify high-value compounds. Collaborations improve technology adoption and knowledge transfer. It ensures efficient scaling of algae-based specialty chemicals. The Australia Algae Based Specialty Chemicals Market leverages public-private partnerships for rapid growth. R&D alliances encourage patent development and new intellectual property. Joint ventures promote investment confidence and market entry.
- For example, Algenie, spun out from University of Technology Sydney and its C3 climate cluster, deployed a patented helix-shaped photobioreactor capable of producing 100 tonnes of algae annually in a shipping container-sized unit. It leverages automation and AI for strain optimisation and aims to supply feedstocks for fuels, plastics, and sustainable materials.
Market Challenges Analysis
High Production Costs and Technological Limitations in Large-Scale Manufacturing
Production of algae-based chemicals requires advanced cultivation and extraction infrastructure. High operational costs reduce competitiveness against conventional chemicals. Limited commercial-scale photobioreactors restrict output efficiency. Capital-intensive technology investment creates barriers for small producers. It affects scalability and impacts profitability across the supply chain. The Australia Algae Based Specialty Chemicals Market must overcome these cost and technology gaps. Limited access to advanced processing facilities slows industry expansion. Balancing affordability with innovation remains a critical challenge.
Supply Chain Constraints and Limited Consumer Awareness in Niche Markets
Supply chains for algae-based inputs face logistical and quality control issues. Climatic conditions impact algae yield reliability. Limited domestic suppliers restrict continuous production volumes. Consumer awareness of algae-based chemicals outside food and cosmetics remains low. It prevents wide-scale adoption in industrial and construction applications. The Australia Algae Based Specialty Chemicals Market requires strong marketing and outreach strategies. Distribution networks need reinforcement to ensure consistent market presence. Overcoming awareness gaps is essential for expanding commercial acceptance.
Market Opportunities
Expanding Industrial Applications Across Pharmaceuticals, Agriculture, and Nutraceuticals
Pharmaceutical companies integrate algae-based compounds into drug formulations for therapeutic benefits. Agricultural inputs such as biofertilizers and biostimulants adopt algae-derived nutrients. It opens opportunities for sustainable farming solutions aligned with eco-standards. Nutraceuticals explore algae proteins and omega-3 fatty acids for dietary supplements. The Australia Algae Based Specialty Chemicals Market expands into high-growth industries with proven demand. End-user diversification ensures long-term business security. Industrial applications strengthen resilience against single-sector dependency.
Growing Export Potential Through Innovation and Regional Collaborations
Australian producers can supply algae-based specialty chemicals to Asia-Pacific and global markets. Regional trade partnerships increase export competitiveness. It creates avenues for wider market penetration. Innovation in high-value compounds positions domestic producers as global suppliers. The Australia Algae Based Specialty Chemicals Market gains advantage from regional collaborations. Export-driven strategies support revenue expansion and global recognition. Collaboration with nearby economies encourages cost-effective logistics. Market opportunities grow with innovation-driven partnerships.
Market Segmentation Analysis
By type, algal pigments hold a dominant position in the Australia Algae Based Specialty Chemicals Market due to their extensive use in pharmaceuticals, nutraceuticals, and cosmetics for natural coloring and antioxidant properties. Algae-derived surfactants and biosurfactants gain traction in eco-friendly cleaning and personal care products, supported by rising consumer demand for biodegradable alternatives. Algal biopolymers and hydrocolloids see expanding adoption in packaging and food processing due to their stabilizing and thickening abilities. Algae-based specialty extracts and functional ingredients strengthen their presence in nutraceuticals, driven by the increasing preference for plant-based health solutions.
- For example, Evonik’s Rheance® D50 is a glycolipid biosurfactant produced from renewable raw materials in Europe, marketed for use in sustainable personal care formulations and suitable for certified natural cosmetics.
By end user, food and beverage and nutraceutical brands represent the leading segment with widespread use of algae-derived proteins, pigments, and omega-3s. Cosmetics and personal care companies integrate algae-based compounds for natural formulations that appeal to eco-conscious consumers. Pharmaceutical and diagnostics firms explore algae for pigments, biomarkers, and therapeutic compounds, driving niche demand. Packaging and bioplastics manufacturers embrace algae biopolymers to replace petroleum-based plastics and align with sustainability standards. Agriculture and aquaculture formulators use algae-based fertilizers and stimulants to improve crop yields and animal nutrition. Industrial and household cleaning product makers adopt algae biosurfactants to create safe, biodegradable cleaning solutions, ensuring broad market penetration.
- For example, E.I.D. Parry’s Parry Nutraceuticals produces organic Spirulina recognized for its exceptionally high protein content, typically reported in the 60–70% range of dry weight, and supplies it globally for use in nutritional supplements.
Segmentation
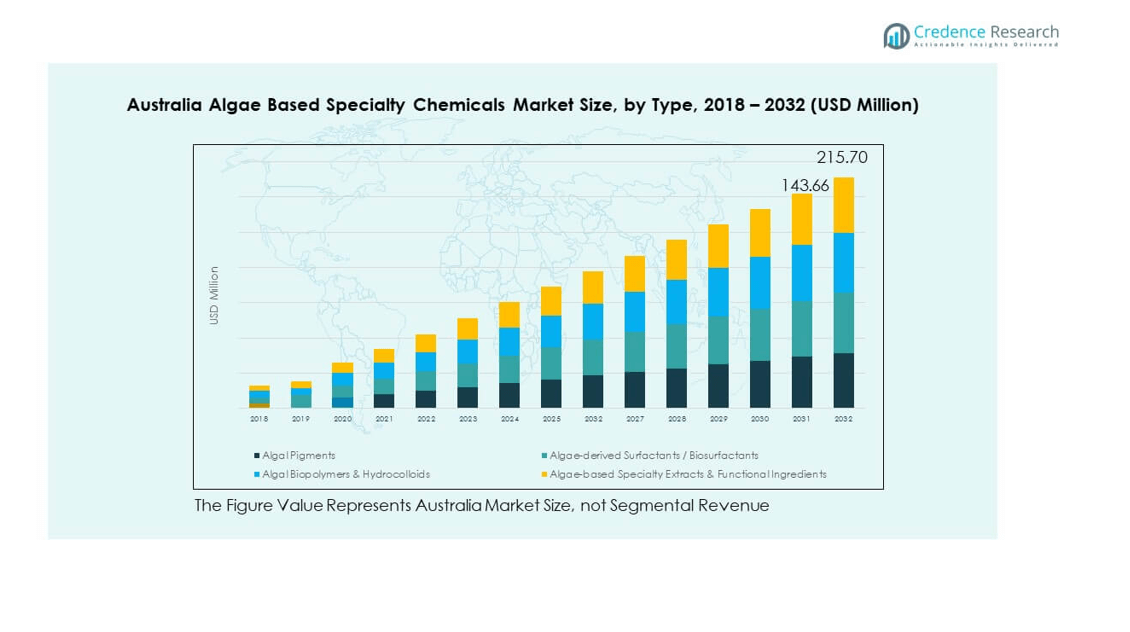
By Type
- Algal Pigments
- Algae-derived Surfactants / Biosurfactants
- Algal Biopolymers & Hydrocolloids
- Algae-based Specialty Extracts & Functional Ingredients
By End User
- Food & Beverage and Nutraceutical Brands
- Cosmetics & Personal Care Companies
- Pharmaceutical & Diagnostics Firms (Pigments/Biomarkers)
- Packaging & Bioplastics Manufacturers
- Agriculture & Aquaculture Formulators
- Industrial & Household Cleaning Product Makers
Regional Analysis
Eastern Australia
Eastern Australia holds the largest share of the Australia Algae Based Specialty Chemicals Market, accounting for 42% of the total market. This dominance stems from strong industrial clusters, advanced biotechnology hubs, and proximity to coastal resources. Universities and research centers in Sydney and Brisbane drive innovations in algae cultivation and processing. Food and pharmaceutical companies in the region integrate algae-derived compounds into their production pipelines. It benefits from established supply chain infrastructure and government-backed sustainability programs. The region remains the core base for large-scale commercial deployment.
Southern Australia
Southern Australia represents 33% of the market, driven by agriculture, aquaculture, and industrial applications. Adelaide acts as a center for R&D collaborations and pilot projects that promote bioplastics and specialty ingredients. It demonstrates strong adoption of algae-based fertilizers and bio-stimulants in sustainable farming practices. The cosmetics and nutraceutical sectors in this region increase demand for algae-derived extracts. It benefits from supportive regional programs that encourage clean technology investments. Southern Australia emerges as a balanced hub combining agriculture with industrial innovation.
Western and Northern Australia
Western and Northern Australia together contribute 25% of the market, with rising interest in algae-based products. Western Australia benefits from mining-linked environmental initiatives and coastal conditions favorable for algae farms. Northern Australia shows gradual adoption in aquaculture, supported by government-funded programs to diversify regional industries. It demonstrates potential in sustainable packaging through algae-based biopolymers. Infrastructure limitations reduce large-scale production, yet investment opportunities continue to expand. The combined subregions provide growth prospects for future expansion and export capabilities.
Key Player Analysis
- CABB Chemicals
- BASF SE
- Accepta
- Cyanotech Corporation
- Earthrise Nutritionals
- Omega Chemicals Pty Ltd
- CP Kelco
- Cargill
- DSM
- Other Key Players
Competitive Analysis
The Australia Algae Based Specialty Chemicals Market features a competitive landscape shaped by global leaders and domestic innovators. Companies such as BASF SE, DSM, and Cargill leverage global expertise and advanced R&D to introduce high-value algae-based products. Local firms like Omega Chemicals Pty Ltd strengthen regional supply through tailored formulations and close partnerships with end users. It creates an environment where international companies focus on scale while domestic players emphasize customization and niche applications. Strategic collaborations, acquisitions, and new product launches remain central to building market positions. The competitive environment is marked by continuous innovation, with companies prioritizing sustainable solutions and expanding algae-based product portfolios to meet rising demand across diverse industries.
Recent Developments
- In February 2025, GC Rieber VivoMega launched "Algae 1060 TG Premium," an algae-based EPA and DHA product designed for dietary supplements and functional foods. This new product expands the range of algae-derived specialty chemistry in the Australian market and is intended to support the growing demand for plant-based omega-3 ingredients in nutrition and food applications.
- In April 2023, Green Water Labs introduced an innovative algae control product specifically formulated to eliminate and prevent algae growth in various applications. While Green Water Labs is a global player, their bio-based solution is designed for safe use around people, pets, and within environmentally sensitive markets, potentially including the expanding Australian algae-based chemicals sector.
Report Coverage
The research report offers an in-depth analysis based on Type and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australia Algae Based Specialty Chemicals Market will expand with increasing adoption across pharmaceuticals, nutraceuticals, and cosmetics.
- Demand for bio-based raw materials will strengthen due to policy support and sustainability commitments.
- Research advancements in photobioreactors and extraction methods will improve production efficiency and scalability.
- Algae-derived bioplastics will gain traction in packaging industries seeking biodegradable solutions.
- Nutritional applications will grow with higher demand for omega-3s, proteins, and functional extracts.
- Strategic collaborations between universities, research centers, and private firms will accelerate innovation pipelines.
- Regional players will scale operations to capture domestic demand and strengthen export competitiveness.
- Industrial applications in agriculture and aquaculture will expand through biofertilizers and stimulants.
- Consumer-driven demand for clean-label and eco-friendly products will elevate market visibility.
- Investments in large-scale algae cultivation farms will create a resilient foundation for long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Algae Based Specialty Chemicals Market, and what is its projected size in 2032?
Which Australia Algae Based Specialty Chemicals Market segment held the largest share in 2024?
At what Compound Annual Growth Rate is the Australia Algae Based Specialty Chemicals Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Australia Algae Based Specialty Chemicals Market?
Who are the leading companies in the Australia Algae Based Specialty Chemicals Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Algae Based Specialty Chemicals Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Algae Based Specialty Chemicals Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 135.87 million → 2032: USD 215.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Algae Based Specialty Chemicals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Algae Based Specialty Chemicals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Algae Based Specialty Chemicals Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Algae Based Specialty Chemicals Market Drivers
- 3.3 Australia Algae Based Specialty Chemicals Market Restraints & Challenges
- 3.4 Australia Algae Based Specialty Chemicals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Algae Based Specialty Chemicals Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Algae Based Specialty Chemicals Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Algae Based Specialty Chemicals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Algae Based Specialty Chemicals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Algae Based Specialty Chemicals Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Algae Based Specialty Chemicals market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Algae Based Specialty Chemicals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Algae Based Specialty Chemicals Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Algae Based Specialty Chemicals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Algae Based Specialty Chemicals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Algae Based Specialty Chemicals Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Algae Based Specialty Chemicals Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Algae Based Specialty Chemicals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Algae Based Specialty Chemicals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Algae Based Specialty Chemicals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Algae Based Specialty Chemicals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Algae Based Specialty Chemicals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Algae Based Specialty Chemicals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Algae Based Specialty Chemicals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
