
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automated Barriers and Bollards Market Size 2023 | USD 2,552.5 Million |
| Automated Barriers and Bollards Market, CAGR | 3.34% |
| Automated Barriers and Bollards Market Size 2032 | USD 3,319.81 Million |
Market Overview
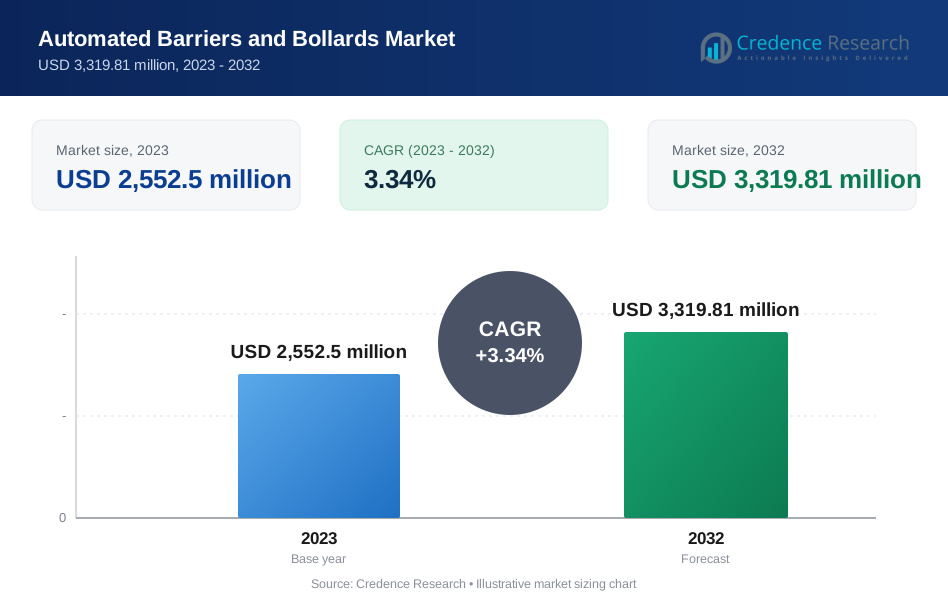
The global Automated Barriers and Bollards market is projected to grow from USD 2,552.5 million in 2023 to an estimated USD 3,319.81 million by 2032, with a compound annual growth rate (CAGR) of 3.34% from 2024 to 2032. This growth signifies an increasing reliance on security solutions that integrate seamlessly with urban infrastructure to manage vehicle and pedestrian traffic effectively. As cities worldwide continue to expand and focus on securing public and private spaces, automated barriers and bollards serve as critical components in traffic management systems, providing enhanced security against unauthorized access and potential threats.
Several key factors drive the demand for automated barriers and bollards. Urbanization and the subsequent need for sophisticated traffic control solutions in densely populated areas contribute significantly to market expansion. Additionally, heightened security concerns due to an increase in terrorist activities and the need to protect pedestrians in public spaces have led to a greater implementation of these automated systems. The market is also benefiting from technological advancements, including the integration of IoT and machine learning, which improve the functionality and reliability of these systems, making them more adaptable to the specific needs of modern urban environments.
Geographically, the Automated Barriers and Bollards market is witnessing substantial growth in regions such as North America, Europe, and Asia-Pacific. North America leads the market due to stringent safety regulations, technological advancements, and the widespread adoption of security systems in both public and private sectors. Europe follows closely, driven by the high priority for security measures and traffic management in its urban centers. The Asia-Pacific region is expected to show significant growth, fueled by rapid urban development and increasing investments in infrastructure projects. Key players in this market include BFT S.p.A., FAAC Group, Avon Barrier Corporation Ltd, and Delta Scientific Corporation, who are continually innovating and expanding their product offerings to meet the diverse needs of the global market.
Market Drivers
Rising Urbanization and Infrastructure Development:
As urban centers expand and populations increase, the demand for effective traffic management solutions becomes critical. For instance, in a city with a population of 10 million, even a 1% increase in population can lead to thousands of additional vehicles on the road. Automated barriers and bollards are integral to modern traffic systems, helping to regulate the flow of vehicles and pedestrians in congested areas. These systems are increasingly being adopted in new infrastructure projects, such as business districts, shopping centers, and residential complexes, where controlling access is essential for safety and organization. This growth in urbanization directly correlates with the need for sophisticated access control mechanisms, propelling the demand for automated barriers and bollards.
Heightened Security Needs Due to Increasing Global Security Threats:
In an era where security concerns are escalating, including threats from terrorism and crime, there is a heightened need for robust security measures. For instance, in the past decade, incidents of vehicle-ramming attacks have increased by 200%, highlighting the need for effective perimeter security. Automated barriers and bollards provide a reliable solution for protecting sensitive areas such as government buildings, embassies, military bases, and commercial hubs. These systems act as physical and psychological deterrents to unauthorized access and are capable of withstanding high-impact collisions, making them essential components of a comprehensive security strategy. Their ability to quickly deploy in response to threats adds an additional layer of security in emergency situations, thereby driving their adoption across various sectors.
Technological Advancements and Integration of Smart Technologies:
The market for automated barriers and bollards is also benefiting from continuous technological enhancements. Modern systems are equipped with cutting-edge technologies such as IoT connectivity, artificial intelligence, and machine learning, which enable features like automatic number plate recognition (ANPR) and biometric access control. These technologies not only enhance the operational effectiveness of barriers and bollards but also increase their adaptability to different environments and requirements. The integration of smart technologies ensures that these systems are more efficient, responsive, and easier to manage remotely, thus appealing to a broader range of consumers seeking advanced security solutions.
Government Regulations and Standards for Safety and Security:
Regulatory frameworks and safety standards play a pivotal role in driving the adoption of automated barriers and bollards. Governments worldwide are implementing regulations that mandate the use of such systems in specific areas to enhance public safety and security. For instance, the implementation of anti-ramming legislation in certain regions requires the installation of barriers capable of stopping vehicles to prevent attacks. Compliance with these regulations compels property owners and city planners to integrate automated barriers and bollards into their security systems, thereby fueling the market growth.
Market Trends
Integration with Smart City Infrastructure:
As cities become smarter, the integration of automated barriers and bollards with other urban technologies is becoming more prevalent. For instance, in a smart city project involving 500 interconnected devices, automated barriers and bollards could constitute up to 20% of these devices. These systems are now part of larger networks that include surveillance cameras, traffic control systems, and emergency response technologies, all interconnected through IoT platforms. This integration enhances the overall efficiency and responsiveness of urban infrastructure, facilitating smoother operations and improved public safety.
Adoption of Solar-Powered Units:
In response to the growing emphasis on sustainability, manufacturers are increasingly developing solar-powered barriers and bollards. These eco-friendly alternatives not only reduce operational costs by minimizing electricity usage but also support environmental sustainability initiatives. For instance, a solar-powered unit can save up to 70% of energy costs compared to a conventional unit. Solar-powered models are particularly appealing for installations in remote areas where wiring complications and energy costs can be prohibitive.
Increased Use of Wireless Technology:
Wireless technology is becoming a standard feature in the automated barriers and bollards industry. The elimination of physical connections reduces installation complexity and costs, while also allowing for more flexible placement options. For example, the use of wireless technology can reduce installation costs by up to 30%. Wireless systems can be remotely operated and monitored via smartphones or other devices, enhancing their convenience and adaptability to various environments.
Enhanced Durability and Aesthetics:
There is a growing trend towards not only functional but also aesthetically pleasing barriers and bollards. Manufacturers are offering customizable designs that blend seamlessly with the surrounding architecture without compromising on security. Additionally, these systems are being constructed with advanced materials to increase their durability and resistance to weather, vandalism, and collisions. For instance, a barrier made with high-strength steel and anti-corrosion coating can last up to 10 years longer than a conventional barrier.
Expansion of Automated Access in Residential Areas:
Automated barriers and bollards are becoming more common in residential areas as part of comprehensive home security systems. They are used to control access to gated communities and private residences, enhancing security for homeowners. This trend is supported by the increasing affordability of automation technology, making it accessible to a wider market.
Regulatory Compliance and Standardization:
As governments worldwide tighten security regulations, compliance is becoming a significant focus for the industry. Manufacturers are ensuring that their products meet international safety and quality standards, which is becoming a key competitive advantage. Standardization also helps in simplifying maintenance and compatibility with other security components, further driving market growth.
Rise in Anti-Terrorism Security Measures:
Given global security challenges, there is an increasing implementation of barriers and bollards as anti-terrorism measures. High-impact resistance models capable of stopping vehicles are being installed in sensitive areas such as pedestrian zones, markets, and near important government buildings to prevent vehicular attacks. This trend is significant in enhancing public spaces' safety and is a critical driver for the deployment of robust barrier systems.
Market Restraints and Challenges
High Installation and Maintenance Costs:
One of the significant barriers to the wider adoption of automated barriers and bollards is the high cost associated with their installation and ongoing maintenance. These systems often require sophisticated setup, including integration with existing security networks, which can be costly. Additionally, the maintenance of advanced technologies like hydraulic or pneumatic mechanisms, sensors, and communication systems can further increase operational expenses. These costs can be prohibitive for small to medium enterprises or low-budget municipal projects, thereby restraining market growth.
Technological Complexity and Reliability Issues:
The advanced technology that makes automated barriers and bollards effective can also be a double-edged sword. Complex systems may face reliability issues, especially in harsh weather conditions or in the case of power failures. Ensuring these systems are fail-safe and can operate effectively under all conditions is a constant challenge. Any failure in operation can compromise security and disrupt traffic, leading to a potential reevaluation of their deployment.
Regulatory and Standards Compliance:
Navigating the regulatory landscape can be challenging for market players. Different regions may have varied standards and regulations regarding the deployment of security and traffic management systems, affecting the design, implementation, and operation of automated barriers and bollards. Compliance with these diverse regulations can be resource-intensive and can slow down market penetration and scalability.
Market Saturation and Competitive Pressure:
In highly developed markets, saturation becomes a significant challenge as many urban areas have already implemented automated security solutions. This scenario limits new sales opportunities and intensifies competition among existing players, pushing down prices and margins. Companies must innovate continually and differentiate their offerings to sustain growth and profitability in such an environment.
Resistance to Change and Adoption:
There is often resistance to the adoption of new technologies, especially from sectors that are traditionally not tech-savvy or where budget constraints are significant. Convincing municipal authorities, business owners, and residential communities of the long-term benefits versus upfront costs requires substantial marketing efforts and education, which can slow down market adoption rates.
Cybersecurity Concerns:
As automated barriers and bollards become more integrated with other systems and the Internet, they are increasingly vulnerable to cyber-attacks. Ensuring the security of these systems from hackers who could potentially gain control and cause disruption is a growing concern. This challenge requires continuous updates and improvements in cybersecurity measures, adding to the complexity and cost of these systems.
Market Segmentation Analysis
By Product
Push button automated barriers are the simplest and most cost-effective, ideal for low-security areas where convenience is key. Remote-controlled barriers offer enhanced security and ease of use, particularly beneficial in adverse weather conditions or high-security zones. RFID tags readers are increasingly popular in commercial and industrial settings, providing seamless access control essential for high throughput and security. Loop detectors, widely used in traffic management and parking systems, efficiently manage traffic flow by detecting vehicles and triggering barrier operations.
By End-user
The Automated Barriers and Bollards market encompasses three main segments: Residential, catering to gated communities and private properties with a focus on heightened security and privacy; Commercial, serving office buildings, malls, and public venues, necessitating efficient access control for both vehicular and pedestrian traffic management; and Industrial, where factories, warehouses, and other industrial settings utilize automated barriers and bollards to ensure premise security and regulate access, enhancing safety and operational efficiency.
Segments
Based on Product
- Push Button
- Remote Controlled
- RFID Tags Reader
- Loop Detectors
Based on End-user
- Residential
- Commercial
- Industrial
Based on Region
- North America
- Europe
- Asia-Pacific
- Middle East & Africa
- Rest of the World
Regional Analysis
North America (35% Market Share)
North America holds a substantial portion of the market share, driven by advanced infrastructure requirements and stringent security protocols. The United States and Canada are leaders in implementing automated security solutions due to their emphasis on terrorism prevention and the need to secure public and private premises. High-end technology adoption and a strong presence of industry leaders also contribute to the robust market growth in this region. As urban areas continue to expand, and investments in smart city projects increase, the demand for automated barriers and bollards is expected to rise further.
Europe (30% Market. Share)
Europe follows closely, with a significant focus on safety and the standardization of security equipment across the European Union. Countries like Germany, the UK, France, and Italy are at the forefront, driven by their need to upgrade security in response to rising concerns about vehicular attacks in public spaces. European market growth is also supported by governmental regulations mandating the use of such technologies in specific zones to enhance pedestrian safety and protect critical infrastructure.
Asia-Pacific (20% Market Share)
The Asia-Pacific region is witnessing rapid market growth, largely due to extensive urban development, particularly in China, India, Japan, and Southeast Asia. The increasing urban population and rising investments in infrastructure development are major drivers. Additionally, the growing awareness of security needs in both public and private sectors is pushing the demand for automated barriers and bollards. The region's market expansion is further fueled by economic growth, which allows for greater expenditure on security measures.
Key players
- BFT S.p.A.
- FAAC Group
- Avon Barrier Corporation Ltd
- Delta Scientific Corporation
- Automatic Systems
- CAME S.p.A.
- Nice S.p.A.
- Houston System Inc.
- APT Controls Ltd.
- Mokai Barrier Systems
Competitive Analysis
In the competitive landscape of the Automated Barriers and Bollards market, these key players are engaged in intense rivalry, primarily focusing on technological innovation, reliability, and integration capabilities. Companies are investing in research and development to enhance the functionality of their offerings, making them more adaptable to diverse environments and capable of integration with advanced security systems. They also emphasize expanding their global footprint through strategic partnerships and acquisitions, aiming to tap into emerging markets. Additionally, customization in product offerings to meet specific regional and industry-specific requirements is a prevalent strategy to gain competitive advantage. This competitive environment drives the continuous improvement of products and services, ensuring that the needs of a diverse and demanding client base are met effectively.
Recent Developments
In May 2022, Delta Scientific, a leader in developing vehicle access control equipment, announced that its DSC550 barrier has achieved a significant milestone. The barrier is capable of stopping a 15,000-pound vehicle traveling at 50 mph and has met the United States Department of State's rigorous criteria for continuous operation over 1 million cycles. This achievement underscores Delta Scientific's commitment to providing high-performance security solutions that meet the stringent standards required for protecting sensitive installations.
In January 2023, Bollard Systems, a prominent US-based manufacturer of automated bollards, secured a significant financial boost with a USD 10 million investment led by VEI Partners. This infusion of capital will enable Bollard Systems to enhance and diversify its product portfolio and bolster its presence on the international stage. The investment reflects confidence in Bollard Systems' growth trajectory and its ability to innovate within the global security barriers market.
In February 2023, Automatic Barriers, a UK-based company specializing in the manufacture of automated barriers, received a strategic investment of USD 5.40 million from Octopus Investments. This funding is earmarked for the development of new products and the expansion of the company’s sales and marketing efforts. This initiative is poised to strengthen Automatic Barriers' market position and enhance its ability to meet the growing demand for reliable and efficient traffic management solutions.
In March 2023, DoorKing, a US-based manufacturer known for its automated barriers and gates, announced a substantial investment of USD 20 million from Great Hill Partners. This capital will be utilized to expand the company's range of products and to extend its reach into international markets. DoorKing's strategic expansion aims to capitalize on the increasing global need for advanced security and access control solutions, positioning it as a leader in the industry.
In April 2023, Rotalock, a UK-based manufacturer of automated bollards, received a significant investment of USD 10.80 million led by BGF. The funds are slated for enhancing Rotalock’s product offerings and furthering its international market penetration. This investment signifies a strong endorsement of Rotalock’s innovative capabilities and its potential for growth in the burgeoning market of security and traffic management solutions.
Market Concentration and Characteristics
The Automated Barriers and Bollards market is moderately concentrated, featuring a blend of established global players and a multitude of smaller companies specializing in niche technologies and regional markets. Key players like Delta Scientific, FAAC Group, and BFT S.p.A. dominate the market due to their extensive product ranges, brand reputation, and ability to invest in advanced technology and global distribution networks. The market is characterized by high barriers to entry due to the technical expertise required in manufacturing and the significant capital investment needed for R&D and compliance with international safety standards. Additionally, the market is driven by innovations aimed at enhancing the integration capabilities, durability, and aesthetic qualities of barriers and bollards, catering to the security, commercial, and urban planning sectors. Competitive dynamics are influenced by technological advancements, regulatory requirements, and partnerships that facilitate entry into new markets and sectors.
Report Coverage
The research report offers an in-depth analysis based on Product, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see enhanced integration of IoT technologies in automated barriers and bollards, facilitating smarter and more efficient operations in urban traffic management and security systems.
- As urbanization continues, there will be greater market penetration into emerging economies where urban infrastructure development is accelerating, boosting demand for advanced security solutions.
- Continued investment in research and development will drive the evolution of more sophisticated, reliable automated barriers and bollards, focusing on user-friendly and highly adaptable systems.
- There will be a significant shift towards the development of eco-friendly, energy-efficient automated barriers and bollards, using solar power and other sustainable technologies to meet environmental standards.
- With increasing digitization, the focus on cybersecurity measures will intensify, ensuring that automated barriers and bollards are secure from cyber threats and breaches.
- Stricter safety and security regulations will shape product designs and market strategies, as companies must adhere to regional and global standards to ensure compliance and market acceptance.
- Customizable and aesthetically pleasing designs will become more prevalent, as barriers and bollards need to integrate seamlessly into various architectural environments without compromising functionality.
- Strategic alliances and partnerships will become crucial for market expansion and to leverage new technologies, enabling companies to enhance their market reach and technological capabilities.
- The market will increasingly focus on developing barriers and bollards with anti-terrorism capabilities, capable of withstanding high-impact forces, to address the growing global security threats.
- Smart city initiatives around the world will significantly drive the demand for automated barriers and bollards, as part of integrated security and traffic management solutions to support safe and efficient urban living.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Infrastructure Development
As cities expand and populations grow, the need for effective traffic management and access control in urban environments is increasing, driving the adoption of automated barriers and bollards in new infrastructure projects.
Heightened Security Needs Due to Global Threats
The rise in terrorism and crime, including vehicle-ramming attacks, has led to greater demand for robust perimeter security solutions, making automated barriers and bollards essential for protecting sensitive and high-traffic areas.
Technological Advancements and Smart Integration
Integration of IoT, AI, and machine learning technologies is enhancing the functionality, reliability, and adaptability of automated barriers and bollards, making them more attractive for modern urban and commercial applications.
Government Regulations and Safety Standards
Stricter regulations and safety standards are mandating the use of automated barriers and bollards in public and private spaces, compelling compliance and fueling market growth.
Expansion of Smart City Initiatives
The global push towards smart city development is increasing the deployment of automated barriers and bollards as part of integrated security and traffic management systems, supporting safer and more efficient urban living.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Automated Barriers and Bollards market?
What are the primary drivers of market demand?
Which regions are witnessing significant growth in the market?
Who are the leading players in the market?
What are the challenges hindering market expansion?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Push Button
- 1.2.2 Remote Controlled
- 1.2.3 RFID Tags Reader
- 1.2.4 Loop Detectors
- 1.3 By End-user
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,552.5 million → 2032: USD 3,319.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automated Barriers and Bollards Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automated Barriers and Bollards Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automated Barriers and Bollards Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automated Barriers and Bollards Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automated Barriers and Bollards Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automated Barriers and Bollards Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automated Barriers and Bollards Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automated Barriers and Bollards Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,552.5 million → 2032: USD 3,319.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automated Barriers and Bollards Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Push Button
- 12.3.7.2 Remote Controlled
- 12.3.7.3 RFID Tags Reader
- 12.3.7.4 Loop Detectors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automated Barriers and Bollards End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automated Barriers and Bollards Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automated Barriers and Bollards Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automated Barriers and Bollards Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BFT S.p.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 FAAC Group
- 18.4 Avon Barrier Corporation Ltd
- 18.5 Delta Scientific Corporation
- 18.6 Automatic Systems
- 18.7 CAME S.p.A.
- 18.8 Nice S.p.A.
- 18.9 Houston System Inc.
- 18.10 APT Controls Ltd.
- 18.11 Mokai Barrier Systems
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

