
Market Overview
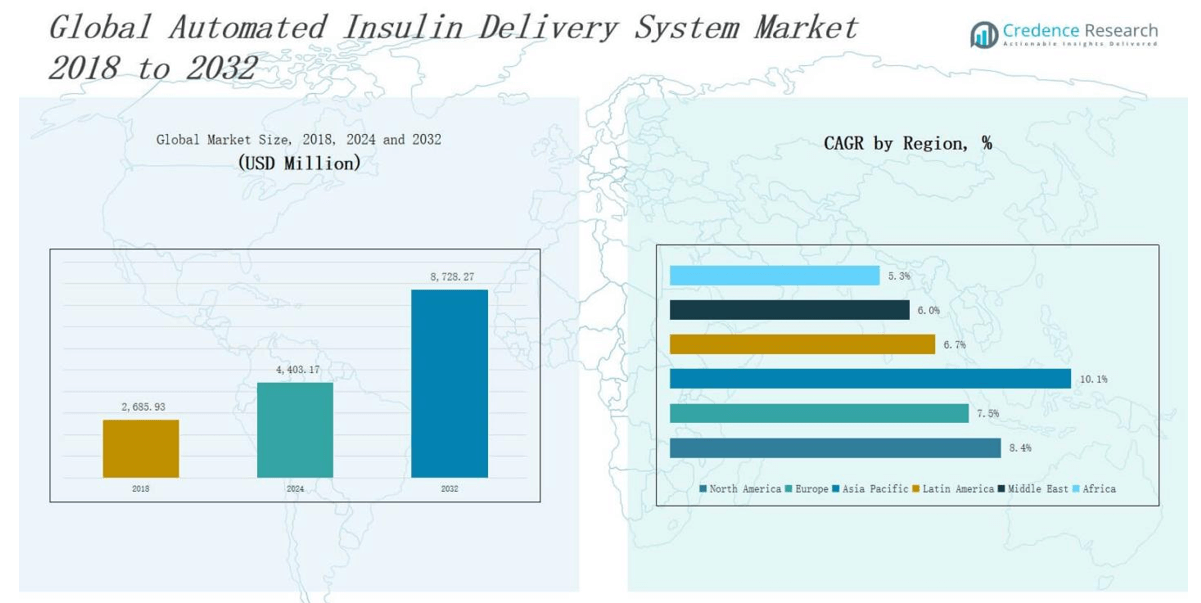
The Automated Insulin Delivery System Market size was valued at USD 2,685.93 million in 2018 to USD 4,403.17 million in 2024 and is anticipated to reach USD 8,728.27 million by 2032, at a CAGR of 8.32 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automated Insulin Delivery System Market Size 2024 | USD 4,403.17 million |
| Automated Insulin Delivery System Market, CAGR | 8.32% |
| Automated Insulin Delivery System Market Size 2032 | USD 8,728.27 million |
The Automated Insulin Delivery System Market is driven by the rising global prevalence of diabetes, increasing demand for personalized and continuous glucose management, and growing adoption of wearable medical technologies. Advancements in closed-loop systems, integration with continuous glucose monitors (CGMs), and real-time data analytics enhance system precision and patient outcomes. Key trends include the development of hybrid and fully automated insulin delivery systems, AI-enabled dosing algorithms, and smartphone integration for remote monitoring. Market players are focusing on compact, user-friendly designs and interoperability, while regulatory support and reimbursement policies further accelerate market adoption across developed and emerging regions.
The Automated Insulin Delivery System Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in adoption, followed by strong growth in Europe and rapid expansion in Asia Pacific. Latin America, the Middle East, and Africa show steady potential driven by improving healthcare access. Key players operating globally include Medtronic, Insulet Corporation, Tandem Diabetes Care, Dexcom, Abbott, Roche Diabetes Care, Ypsomed AG, Bigfoot Biomedical, Diabeloop, Beta Bionics, EOFlow, and Senseonics Holdings, strengthening competition and innovation across all regions.
Market Insights
- The Automated Insulin Delivery System Market reached USD 4,403.17 million in 2024 and is projected to hit USD 8,728.27 million by 2032, growing at a CAGR of 8.32%.
- Rising global diabetes prevalence, especially type 1 diabetes, continues to drive demand for precise, continuous insulin management solutions.
- Technological advancements such as AI-based dosing, improved CGMs, and smartphone connectivity enhance usability and patient outcomes.
- High device cost and limited reimbursement access, especially in emerging regions, remain key barriers to broader market adoption.
- North America leads the market with USD 1,901.31 million in 2024, driven by strong infrastructure, favorable policies, and early adoption.
- Asia Pacific is the fastest-growing region with a CAGR of 10.1%, supported by rising healthcare investments and government-backed diabetes programs.
- Key players including Medtronic, Insulet, Tandem, Dexcom, Abbott, and Roche are focusing on innovation, partnerships, and regional expansion to strengthen their global footprint.
Market Drivers
Rising Diabetes Prevalence and Demand for Improved Glycemic Control
The Automated Insulin Delivery System Market is primarily driven by the global surge in diabetes cases, particularly type 1 diabetes, where precise insulin dosing is critical. Patients and healthcare providers seek advanced systems that ensure tighter glucose control and reduce long-term complications. It addresses these needs through continuous glucose monitoring paired with automated insulin adjustments. Rising awareness of the benefits of closed-loop systems increases demand. Growing healthcare expenditure further supports adoption. The need for reducing hypoglycemia risk strengthens market growth.
- For instance, in 2023, Medtronic’s MiniMed 780G system was approved by the FDA, offering real-time adjustments every 5 minutes and delivering auto-corrections to help users maintain target glucose levels, especially overnight.
Technological Advancements in Sensor and Algorithm Integration
Innovations in continuous glucose monitoring and insulin pump technologies significantly contribute to the Automated Insulin Delivery System Market. It benefits from AI-driven algorithms that enable predictive insulin dosing and adaptive learning based on user behavior. Enhanced sensor accuracy, real-time alerts, and cloud-based data sharing improve decision-making. Wireless connectivity and smartphone integration improve usability. Market players invest in research to deliver compact, intelligent systems. These technological improvements expand appeal among younger, tech-savvy diabetic populations.
- For instance, Tandem Diabetes Care’s t:slim X2 insulin pump with Control-IQ technology integrates with CGMs and uses predictive modeling to reduce both hyperglycemia and hypoglycemia events.
Growing Preference for Wearable and User-Friendly Devices
User comfort and device simplicity drive adoption of automated insulin delivery systems. The Automated Insulin Delivery System Market is responding with wearable solutions that blend into daily routines. Lightweight, discreet designs with intuitive interfaces appeal to both adult and pediatric users. It offers freedom from manual insulin injections and reduces patient burden. Healthcare providers favor such systems for their ease of training and compliance. This shift toward patient-centric design broadens the user base significantly.
Supportive Regulatory Framework and Reimbursement Policies
Supportive regulatory pathways and favorable reimbursement structures boost the Automated Insulin Delivery System Market. It receives increasing attention from health agencies recognizing its role in reducing diabetes-related complications. Regulatory bodies streamline approval processes for integrated technologies. Public and private insurers now cover many devices, encouraging early adoption. Governments and NGOs promote awareness and funding for diabetes management programs. These factors improve accessibility, especially in developed economies. This regulatory support accelerates innovation and commercial success.
Market Trends
Integration of Artificial Intelligence and Adaptive Algorithms Enhances Personalization
The Automated Insulin Delivery System Market is experiencing a shift toward AI-powered systems that personalize insulin dosing based on real-time data. Advanced algorithms analyze glucose trends, meal patterns, and activity levels to make precise dosing decisions. These systems reduce hypoglycemia risk and improve time-in-range outcomes. AI integration supports predictive adjustments, helping patients maintain stable glucose levels. It enables smarter, patient-specific insulin delivery with minimal manual input. Continuous algorithm refinement improves reliability and user confidence.
- For instance, the iLet® Bionic Pancreas from Beta Bionics uses machine learning to automate insulin delivery with no need for users to input carb counts, making personalized dosing more seamless and accessible for people with type 1 diabetes.
Smartphone Connectivity and Remote Monitoring Drive User Engagement
Smartphone integration has emerged as a core trend in the Automated Insulin Delivery System Market, offering real-time tracking and data visualization. Patients and caregivers access glucose and insulin data remotely through apps, improving engagement and adherence. It enables physicians to monitor trends and adjust treatment plans promptly. Enhanced user interfaces and alerts support informed decision-making. Remote monitoring increases system value, particularly for pediatric and elderly users. Connectivity transforms diabetes management into a more responsive and transparent process.
Hybrid Closed-Loop Systems Evolve Toward Fully Automated Solutions
The market is moving from hybrid closed-loop systems to fully automated insulin delivery, aiming for complete hands-off glucose control. Hybrid systems require periodic manual input, while newer models automate most dosing decisions. It reflects increasing demand for convenience and precision. Major players are investing in R&D to remove the need for carbohydrate counting or user overrides. Fully automated systems offer superior glycemic outcomes with minimal user burden. This trend positions them as the future standard in diabetes care.
- For instance, Beta Bionics’ iLet Bionic Pancreas, FDA-cleared in 2023, adjusts insulin dosing automatically based solely on the user’s body weight, requiring no carb-counting or manual adjustments from users.
Emphasis on Compact Design and Wearability Expands Patient Adoption
Wearable comfort and discreet design play a crucial role in accelerating demand within the Automated Insulin Delivery System Market. Compact, tubeless systems that adhere to the body offer greater mobility and freedom. It appeals to active users and pediatric patients who prioritize convenience. Manufacturers focus on lightweight, waterproof, and skin-friendly materials to enhance daily usability. Ease of use supports consistent wear and treatment adherence. These advancements make automated delivery systems more approachable for a broader population.
Market Challenges Analysis
High Cost of Devices and Limited Reimbursement Hinder Widespread Adoption
The Automated Insulin Delivery System Market faces significant barriers due to the high upfront cost of devices and associated components. Many patients, particularly in low- and middle-income regions, cannot afford these systems without insurance support. Limited or inconsistent reimbursement policies restrict access even in developed countries. Insurers often hesitate to cover advanced systems due to unclear long-term cost-benefit data. This limits market penetration and creates inequality in diabetes management. It remains a challenge for manufacturers to balance innovation with affordability. Expanding access depends on stronger payer-provider collaborations and value-based pricing models.
Technical Limitations and Regulatory Complexity Delay Market Expansion
The Automated Insulin Delivery System Market also struggles with technical and regulatory challenges that delay product rollout and adoption. Sensor inaccuracies, delayed insulin absorption, and software glitches compromise system reliability. Regulatory agencies enforce strict safety standards, requiring extensive clinical validation and slowing approval timelines. It faces hurdles in ensuring real-time data accuracy, cybersecurity, and interoperability across platforms. Device recalls and data privacy concerns also affect user trust. Navigating these technical and compliance issues increases development costs and extends time-to-market. Industry players must address these concerns to scale adoption effectively.
Market Opportunities
Expansion into Emerging Markets with Growing Diabetic Population Creates New Demand
The Automated Insulin Delivery System Market holds strong growth potential in emerging economies where diabetes prevalence continues to rise. Countries across Asia-Pacific, Latin America, and the Middle East are witnessing increased diagnosis rates and a growing need for advanced diabetic care. Rising healthcare investments and improved infrastructure support device adoption. Governments and NGOs are launching awareness campaigns and funding programs to expand access. It can leverage this demand by introducing cost-effective models and building local distribution networks. Collaborating with regional healthcare providers and policymakers can accelerate product acceptance. These markets offer untapped growth opportunities for scalable and adaptable solutions.
Integration with Digital Health Platforms and AI Enhances System Value
The Automated Insulin Delivery System Market benefits from the growing shift toward connected healthcare ecosystems. Integration with mobile apps, wearable devices, and AI-driven analytics enables personalized, data-backed insulin management. It allows real-time monitoring, remote physician access, and improved patient adherence. Expanding partnerships with digital health startups and telehealth platforms enhances ecosystem value. This creates a pathway for insurers to support device use through outcome-based models. It also opens doors for continuous upgrades through software enhancements without requiring hardware replacements. These innovations position the market to evolve beyond traditional diabetes management.
Market Segmentation Analysis:
By Product Type
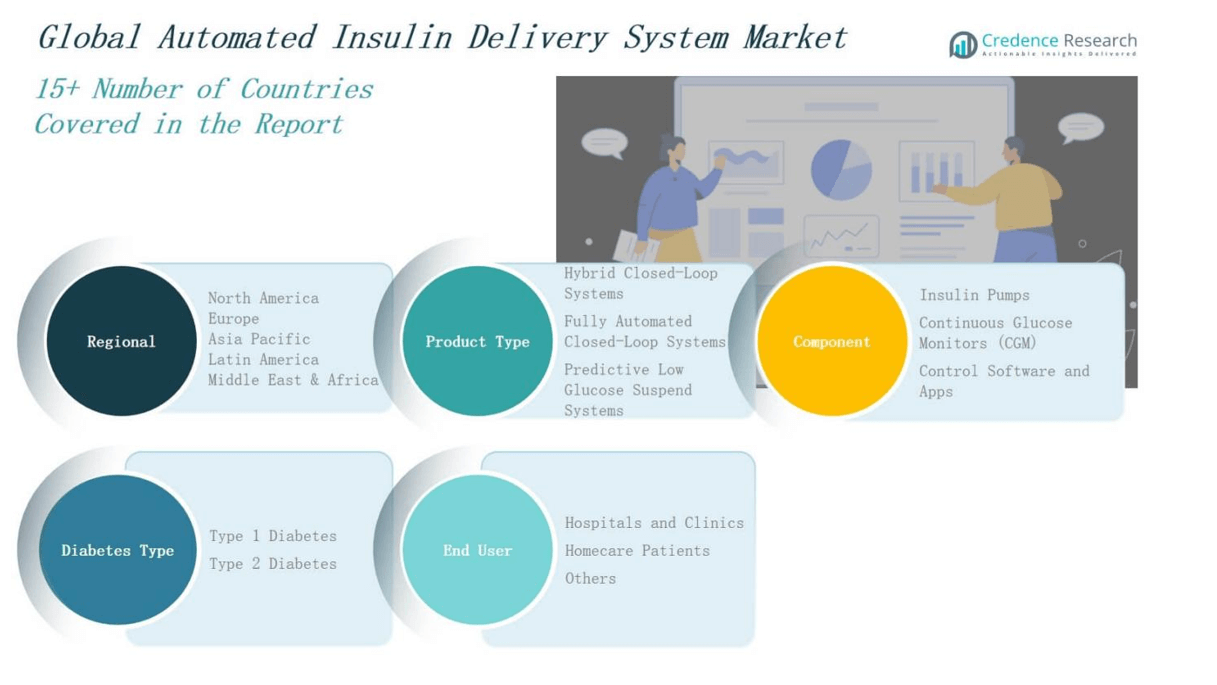
The Automated Insulin Delivery System Market includes hybrid closed-loop systems, fully automated closed-loop systems, and predictive low glucose suspend (PLGS) systems. Hybrid systems dominate due to their proven performance and user familiarity. Fully automated systems are gaining momentum with increased preference for hands-free operation and improved glycemic control. PLGS systems offer targeted intervention to prevent hypoglycemia, making them valuable for nocturnal use and pediatric patients. Each product type serves distinct clinical needs, allowing manufacturers to address varied diabetic populations. It continues to evolve as innovation pushes systems toward greater automation and personalized dosing.
- For instance, the Omnipod 5 system, notable as the first tubeless hybrid closed-loop pump, combines with Dexcom G6 CGM to deliver automated basal insulin dosing but still relies on users for bolus insulin at meals, offering freedom from tubing while managing glucose effectively.
By Component
The market comprises insulin pumps, continuous glucose monitors (CGMs), and control software and apps. CGMs hold a large share due to their critical role in real-time glucose tracking. Insulin pumps are central to the delivery mechanism and are being refined for accuracy and portability. Control software and apps enhance system functionality by integrating data analytics, remote access, and customization features. The Automated Insulin Delivery System Market benefits from the seamless integration of these components. It supports patient adherence and clinical oversight through connected and intelligent device ecosystems.
- For instance, Roche unveiled its Accu-Chek SmartGuide CGM with predictive AI technology that forecasts glucose trends up to two hours ahead, helping users proactively manage glucose levels and avoid hypoglycemia through advanced pattern recognition and digital tools.
By Diabetes Type
Type 1 diabetes accounts for the largest share in the Automated Insulin Delivery System Market due to the intensive insulin management it requires. These systems offer significant benefits in reducing glucose variability and minimizing hypoglycemia risk. Type 2 diabetes represents a growing opportunity as insulin-dependent patients seek alternatives to manual injection regimens. It supports a shift toward technology-driven chronic disease management. Manufacturers are expanding indications to cater to this broader diabetic group with scalable system options.
Segments:
Based on Product Type
- Hybrid Closed-Loop Systems
- Fully Automated Closed-Loop Systems
- Predictive Low Glucose Suspend System
Based on Component
- Insulin Pumps
- Continuous Glucose Monitors (CGM)
- Control Software and Apps
Based on Diabetes Type
- Type 1 Diabetes
- Type 2 Diabetes
Based on End User
- Hospitals and Clinics
- Homecare Patients
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Automated Insulin Delivery System Market size was valued at USD 1,171.98 million in 2018 to USD 1,901.31 million in 2024 and is anticipated to reach USD 3,779.39 million by 2032, at a CAGR of 8.4% during the forecast period. North America holds the largest market share, driven by high diabetes prevalence, advanced healthcare infrastructure, and strong adoption of medical technology. The U.S. leads regional growth due to favorable reimbursement policies and widespread use of insulin pumps and CGMs. Key players actively launch new automated systems and expand clinical trials. It benefits from government support for digital health and chronic disease management. The presence of major manufacturers and early technology adopters strengthens North America's dominance in the global landscape.
Europe
The Europe Automated Insulin Delivery System Market size was valued at USD 792.97 million in 2018 to USD 1,254.91 million in 2024 and is anticipated to reach USD 2,347.93 million by 2032, at a CAGR of 7.5% during the forecast period. Europe holds the second-largest market share, supported by strong public healthcare systems and increasing focus on diabetes control. Countries like Germany, France, and the UK lead in device adoption and reimbursement access. It experiences growth through clinical guidelines favoring automated insulin delivery systems. Regulatory alignment and CE approvals facilitate swift market entry for new devices. Growing demand for non-invasive glucose monitoring further boosts regional expansion.
Asia Pacific
The Asia Pacific Automated Insulin Delivery System Market size was valued at USD 473.64 million in 2018 to USD 847.50 million in 2024 and is anticipated to reach USD 1,921.22 million by 2032, at a CAGR of 10.1% during the forecast period. Asia Pacific is the fastest-growing region due to rising diabetes cases, urbanization, and expanding access to advanced medical technologies. China, India, Japan, and South Korea lead demand with increasing healthcare investments and awareness. It benefits from improving affordability and domestic manufacturing of CGMs and insulin pumps. Government-backed diabetes programs and digital health adoption support long-term growth. Local partnerships and distribution networks help market penetration across rural and semi-urban areas.
Latin America
The Latin America Automated Insulin Delivery System Market size was valued at USD 129.25 million in 2018 to USD 209.29 million in 2024 and is anticipated to reach USD 368.10 million by 2032, at a CAGR of 6.7% during the forecast period. Latin America shows steady growth driven by increasing diabetes diagnosis and a shift toward modern diabetes management. Brazil and Mexico are the primary contributors, supported by expanding private healthcare infrastructure. It faces cost-related adoption barriers but gains momentum through NGO-led awareness and pilot programs. Regional demand grows for affordable and easy-to-use insulin delivery devices. Innovation in mobile-linked systems appeals to tech-savvy populations in urban areas.
Middle East
The Middle East Automated Insulin Delivery System Market size was valued at USD 75.82 million in 2018 to USD 113.71 million in 2024 and is anticipated to reach USD 190.48 million by 2032, at a CAGR of 6.0% during the forecast period. The Middle East market benefits from rising diabetes incidence, government health initiatives, and increasing insurance coverage. GCC countries lead regional demand with strong healthcare investments and early device adoption. It sees growing interest in wearable solutions and mobile-integrated platforms. Multinational companies expand presence through local partnerships and clinical collaborations. Market growth relies on balancing affordability with high-end features for long-term management.
Africa
The Africa Automated Insulin Delivery System Market size was valued at USD 42.28 million in 2018 to USD 76.44 million in 2024 and is anticipated to reach USD 121.16 million by 2032, at a CAGR of 5.3% during the forecast period. Africa presents untapped potential in the automated insulin delivery space, driven by rising diabetes awareness and healthcare development. South Africa and Egypt are key growth hubs with improving infrastructure and medical device access. It faces challenges in affordability, diagnosis rates, and specialist availability. Market penetration depends on NGO support, government health programs, and mobile health platforms. Long-term growth will rely on low-cost innovations and training of healthcare providers.
Key Player Analysis
- Diabeloop
- Dexcom Inc.
- Ascensia Diabetes Care
- Medtronic
- Senseonics Holdings, Inc.
- EOFlow Co., Ltd.
- Bigfoot Biomedical
- Tandem Diabetes Care
- Roche Diabetes Care
- Sooil Development Co., Ltd.
- Ypsomed AG
- Cellnovo Group SA (Acquired by Tandem)
- Abbott Laboratories
- Insulet Corporation
- Beta Bionics
Competitive Analysis
The Automated Insulin Delivery System Market features intense competition led by established medical device companies and innovative startups. Major players such as Medtronic, Tandem Diabetes Care, and Insulet Corporation dominate through extensive product portfolios and strong distribution networks. Companies like Dexcom and Abbott contribute with advanced CGM technologies that integrate seamlessly with insulin pumps. Emerging players, including Beta Bionics, Bigfoot Biomedical, and Diabeloop, focus on algorithm-driven automation and closed-loop innovations. It witnesses frequent product launches, strategic collaborations, and clinical trials to gain regulatory approvals and market share. Players invest in AI-based solutions, compact hardware, and user-friendly platforms to differentiate offerings. Market competitiveness depends on pricing, integration capabilities, and digital support features.
Recent Developments
- In April 2025, Medtronic submitted FDA 510(k) applications to enable its MiniMed 780G insulin pump and SmartGuard algorithm to operate with Abbott’s CGM platform, advancing their interoperability partnership.
- In March 2025, Tandem Diabetes Care launched the Control-IQ+ system, expanding its automated insulin delivery technology to support individuals as young as two years old with type 1 diabetes.
- On April 29, 2025, Sequel Med Tech entered into a collaboration with Senseonics to co-develop an AID system that incorporates a one-year implantable CGM, marking a significant innovation in long-term monitoring.
- On June 23, 2025, Tandem Diabetes Care partnered with Abbott to integrate Abbott’s dual glucose-ketone sensor into Tandem’s AID platform, enhancing metabolic monitoring capabilities.
Market Concentration & Characteristics
The Automated Insulin Delivery System Market is moderately concentrated, with a few dominant players holding significant market share due to established brand presence, advanced technologies, and extensive distribution networks. Companies like Medtronic, Insulet Corporation, Tandem Diabetes Care, and Dexcom lead through continuous innovation and integration of CGMs and insulin pumps. It features high entry barriers due to stringent regulatory requirements, complex product development, and the need for clinical validation. The market emphasizes reliability, real-time data integration, and user-centric design. Growth depends on product differentiation, AI-enabled automation, and interoperability across platforms. Smaller players and startups focus on specialized algorithms and regional market customization to gain traction. It also reflects high R&D intensity and strategic partnerships to enhance market presence and meet evolving patient needs. Market dynamics favor companies capable of balancing innovation, affordability, and scalability in response to increasing global diabetes burden.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Component, Diabetes Type, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for fully automated closed-loop systems will grow due to rising preference for hands-free insulin management.
- Integration of AI and machine learning will enhance dosing precision and personalization.
- Smartphone apps and cloud platforms will support remote monitoring and patient engagement.
- Compact, wearable, and discreet devices will attract younger and active diabetic users.
- Regional expansion in Asia Pacific, Latin America, and the Middle East will drive new revenue streams.
- Partnerships between tech firms and healthcare providers will accelerate innovation and adoption.
- Regulatory support and favorable reimbursement policies will improve market accessibility.
- Companies will invest in interoperable platforms to integrate pumps, CGMs, and software seamlessly.
- Low-cost models tailored for emerging markets will increase adoption in underserved regions.
- Growing awareness and education around diabetes technology will support long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Diabetes Prevalence
The increasing incidence of diabetes, particularly type 1 diabetes, is driving demand for advanced insulin management solutions that offer precise and continuous glucose control, fueling market growth.
Technological Advancements in Automation and Integration
Innovations such as AI-driven dosing algorithms, improved CGMs, and seamless integration with smartphones and cloud platforms are enhancing system accuracy, usability, and patient outcomes, making automated insulin delivery systems more attractive.
Growing Adoption of Wearable and User-Friendly Devices
The shift toward compact, discreet, and easy-to-use wearable devices is expanding the user base, especially among younger and active patients who seek convenience and improved quality of life.
Supportive Regulatory and Reimbursement Policies
Favorable regulatory frameworks and expanding insurance coverage in developed regions are lowering adoption barriers, encouraging early uptake, and accelerating the commercialization of new automated insulin delivery technologies.
Expansion in Emerging Markets
Rising healthcare investments, government-backed diabetes programs, and increasing awareness in Asia Pacific, Latin America, and the Middle East & Africa are creating new opportunities for market penetration and growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automated Insulin Delivery System Market?
What are the key segments within the Automated Insulin Delivery System Market?
What are some challenges faced by the Automated Insulin Delivery System Market?
Who are the major players in the Automated Insulin Delivery System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals and Clinics
- 1.2.2 Homecare Patients
- 1.2.3 Others
- 1.3 By Component
- 1.3.1 Insulin Pumps
- 1.3.2 Continuous Glucose Monitors (CGM)
- 1.3.3 Control Software and Apps
- 1.4 By Product Type
- 1.4.1 Hybrid Closed-Loop Systems
- 1.4.2 Fully Automated Closed-Loop Systems
- 1.4.3 Predictive Low Glucose Suspend Systems
- 1.5 By Diabetes Type
- 1.5.1 Type 1 Diabetes
- 1.5.2 Type 2 Diabetes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,403.17 million → 2032: USD 8,728.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automated Insulin Delivery System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automated Insulin Delivery System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automated Insulin Delivery System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automated Insulin Delivery System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automated Insulin Delivery System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automated Insulin Delivery System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automated Insulin Delivery System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automated Insulin Delivery System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,403.17 million → 2032: USD 8,728.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automated Insulin Delivery System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Clinics
- 12.3.7.2 Homecare Patients
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Insulin Pumps
- 12.4.7.2 Continuous Glucose Monitors (CGM)
- 12.4.7.3 Control Software and Apps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hybrid Closed-Loop Systems
- 12.5.7.2 Fully Automated Closed-Loop Systems
- 12.5.7.3 Predictive Low Glucose Suspend Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Diabetes Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Type 1 Diabetes
- 12.6.7.2 Type 2 Diabetes
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automated Insulin Delivery System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automated Insulin Delivery System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automated Insulin Delivery System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automated Insulin Delivery System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Insulet Corporation
- 18.4 Tandem Diabetes Care
- 18.5 Dexcom
- 18.6 Abbott Laboratories
- 18.7 Roche Diabetes Care
- 18.8 Ypsomed AG
- 18.9 Bigfoot Biomedical
- 18.10 Diabeloop
- 18.11 Beta Bionics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

