
Automated Cell Counter Market Overview:
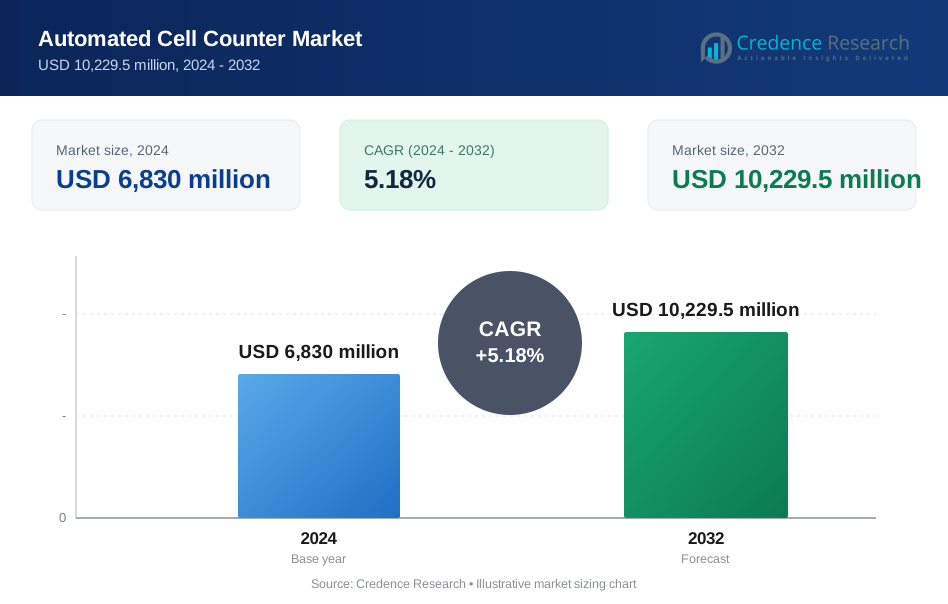
Automated Cell Counter Market size was valued USD 6830 million in 2024 and is anticipated to reach USD 10229.5 million by 2032, at a CAGR of 5.18% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automated Cell Counter Market Size 2024 | USD 6830 million |
| Automated Cell Counter Market, CAGR | 5.18% |
| Automated Cell Counter Market Size 2032 | USD 10229.5 million |
Automated Cell Counter Market Insights
- Market growth is driven by rising adoption of automated laboratory workflows, increasing cell-based research, and strong demand from biopharmaceutical manufacturing and cell therapy development requiring high accuracy and reproducibility.
- Key market trends include rapid adoption of image-based and fluorescence-enabled cell counters, integration of AI-driven software analytics, and growing preference for compact, user-friendly benchtop systems across laboratories.
- Competitive dynamics remain strong as leading players invest in R&D, expand consumables portfolios, enhance software capabilities, and strengthen global distribution and after-sales service networks.
- Regionally, North America leads with an exact market share of 41% due to advanced laboratory infrastructure and high biotechnology activity, while image-based automated cell counters dominate the product segment with the largest adoption share.

Market Segmentation Analysis:
By Product Type
By product type, flow cytometers dominate the automated cell counter market, accounting for approximately 45–48% market share, driven by their high-throughput capability, multi-parameter analysis, and strong adoption in advanced research and clinical laboratories. These systems enable simultaneous measurement of cell size, granularity, and fluorescence markers, supporting complex phenotyping workflows. Fluorescence image-based cell counters follow, gaining traction due to ease of use, lower training requirements, and suitability for routine cell viability and concentration analysis. Coulter counters retain steady demand in standardized cell sizing applications, particularly where electrical impedance-based accuracy is prioritized.
- For instance, NucleoCounter NC-200, the one-step measurement time is approximately 50 seconds. The 30-second measurement time cited in the claim is a specific improvement introduced with the newer NC-202 model.
By Application
By application, blood cell analysis represents the dominant segment with an estimated 40–43% market share, supported by widespread use in hematology diagnostics, clinical laboratories, and hospital settings. Automated cell counters are integral to complete blood count workflows, enabling rapid and reproducible analysis. Cell line analysis follows closely, driven by expanding biopharmaceutical R&D, cell therapy development, and vaccine production. Microbial cell applications show consistent growth in pharmaceutical quality control and food safety testing, while other applications, including stem cells and primary cells, benefit from increasing adoption in regenerative medicine research.
- For instance, Sysmex Corporation’s XN-1000 hematology analyzer processes up to 100 samples per hour, measures more than 30 reportable parameters per sample, and uses fluorescence flow cytometry with a semiconductor laser operating at 633 nm, enabling leukocyte differential counts with a coefficient of variation below 2% for key parameters, as documented in Sysmex technical manuals and product validation reports.
By End User
By end user, pharmaceutical and biotechnology companies hold the leading position with approximately 34–37% market share, fueled by intensive use of automated cell counters across drug discovery, biologics manufacturing, and cell-based assay development. High demand for accuracy, reproducibility, and regulatory compliance supports sustained investment in advanced systems. Hospitals represent the next major segment, driven by routine diagnostic testing and hematology workflows. Diagnostic laboratories maintain strong adoption due to high sample volumes, while research institutes continue to drive demand for flexible, multi-application platforms supporting basic and translational research.
Key Growth Drivers
Rising Demand for High-Throughput and Accurate Cell Analysis
The Automated Cell Counter Market benefits strongly from growing demand for rapid, high-throughput, and reproducible cell analysis across research and clinical laboratories. Pharmaceutical and biotechnology companies increasingly rely on automated counters to accelerate drug discovery, cell therapy development, and biologics production, where consistent cell viability and concentration data are critical. Compared to manual hemocytometers, automated systems reduce human error, improve data consistency, and shorten processing time. The expansion of large-scale cell culture workflows and time-sensitive experiments continues to drive sustained adoption of automated cell counting solutions.
- For instance, Agilent Technologies NovoCyte Advanteon is engineered with one, two, or three spatially separated lasers operating at wavelengths of 405 nm (Violet), 488 nm (Blue), and 640 nm (Red).
Expansion of Cell-Based Research and Biopharmaceutical Manufacturing
The rapid growth of cell-based research, including stem cell research, immunotherapy, and regenerative medicine, significantly drives the Automated Cell Counter Market. Biopharmaceutical manufacturers require precise cell density and viability measurements to maintain process control, optimize yields, and comply with quality standards. Automated cell counters support standardized workflows in upstream bioprocessing, enabling scalable production and batch-to-batch consistency. Increasing investments in biologics, biosimilars, and advanced therapies strengthen demand for robust analytical tools, positioning automated cell counters as essential instruments in modern biomanufacturing environments.
- For instance, Rigel S2 integrates brightfield imaging with dual-fluorescence channels (specifically utilizing 480 nm and 525 nm excitation wavelengths). This system is primary used for AO/PI (Acridine Orange/Propidium Iodide) viability assays, which provide more accurate results than brightfield-only methods in complex samples.
Increasing Adoption in Clinical and Diagnostic Laboratories
Clinical and diagnostic laboratories increasingly adopt automated cell counters to improve efficiency, accuracy, and standardization in routine testing. These systems support applications such as blood cell analysis, microbial counting, and cell line validation with minimal operator intervention. Automation helps laboratories manage rising sample volumes while maintaining compliance with regulatory and accreditation requirements. The shift toward digital laboratory workflows and the need for faster turnaround times further reinforce adoption. As healthcare systems emphasize operational efficiency and data reliability, automated cell counters gain wider acceptance in clinical settings.
Key Trends & Opportunities
Integration of Advanced Imaging and Fluorescence Technologies
A major trend in the Automated Cell Counter Market is the integration of advanced imaging and fluorescence-based technologies. These capabilities enable multiparametric analysis, including cell size, morphology, and viability, beyond simple cell counts. Fluorescence-based counters support complex assays in oncology, immunology, and cell therapy research by differentiating live, dead, and specific cell populations. This trend creates opportunities for manufacturers to offer high-value systems that address advanced research needs, supporting premium pricing and deeper penetration into specialized laboratory applications.
- For instance, the Olympus R1 Cell Counter incorporates an automatic liquid-lens autofocus system that captures high-clarity images across a cell concentration range from 5 × 10⁴ to 1 × 10⁷ cells per milliliter and supports cell diameter measurements from 3 μm to 60 μm, delivering total/live/dead counts in under 15 seconds with size- and roundness-based declustering algorithms, as outlined in Olympus R1 technical documentation.
Growing Demand for Compact and User-Friendly Instruments
Laboratories increasingly prefer compact, benchtop automated cell counters that are easy to operate and require minimal training. User-friendly interfaces, touchscreen controls, and preconfigured protocols enhance workflow efficiency and reduce dependency on highly skilled technicians. This trend is particularly strong in academic laboratories, contract research organizations, and small biopharma facilities with limited space and resources. Manufacturers that focus on ergonomic design, simplified maintenance, and rapid setup can expand adoption across a broader customer base, creating new growth opportunities in decentralized laboratory environments.
- For instance, Danaher’s Beckman Coulter Life Sciences Vi-CELL BLU cell viability analyzer features a fully enclosed benchtop design with an integrated touchscreen interface, analyzes samples using trypan blue staining with automated image analysis, processes a sample in approximately 3 minutes, supports cell diameter measurements from 2 µm to 70 µm, and delivers validated viability and concentration results using a fixed 200 µL sample volume, as specified in Beckman Coulter Vi-CELL BLU product documentation, highlighting Danaher’s focus on compact design and operator-independent performance.
Digital Connectivity and Data Management Integration
The adoption of digital connectivity and data integration features represents a significant opportunity in the Automated Cell Counter Market. Modern laboratories increasingly demand instruments that seamlessly connect with laboratory information management systems and data analytics platforms. Automated data capture, storage, and traceability improve compliance, reproducibility, and audit readiness. As laboratories move toward fully digitized and automated ecosystems, cell counters with connectivity and software integration capabilities gain competitive advantage, supporting long-term customer retention and value-added service offerings.
Key Challenges
High Initial Investment and Cost Sensitivity
The relatively high upfront cost of advanced automated cell counters presents a key challenge, particularly for small laboratories and academic institutions with limited budgets. In cost-sensitive environments, manual counting methods may still be preferred despite lower accuracy and efficiency. Additionally, ongoing expenses related to consumables, maintenance, and software upgrades can affect total cost of ownership. Vendors must balance advanced functionality with affordability to address diverse customer segments and overcome purchasing barriers in emerging and resource-constrained markets.
Technical Complexity and Standardization Issues
Despite automation, technical complexity remains a challenge in the Automated Cell Counter Market. Variability in cell types, sample preparation methods, and assay conditions can affect measurement accuracy and comparability across systems. Laboratories may face difficulties in standardizing protocols, especially when transitioning from manual to automated counting methods. Inconsistent results can limit user confidence and slow adoption. Addressing this challenge requires robust calibration methods, validated protocols, and comprehensive user training to ensure reliable and reproducible outcomes across applications.
Regional Analysis
North America
North America dominates the Automated Cell Counter Market with an estimated 38% share, supported by advanced life-science infrastructure and high adoption across pharmaceutical, biotechnology, and clinical laboratories. Strong R&D spending, widespread use of flow cytometry–based and image-based counters, and early integration of AI-enabled analytics drive demand. The United States leads regional revenue due to large biopharma pipelines, routine use of automated hematology workflows, and strong academic research funding. Additionally, stringent quality standards and the need for reproducible, high-throughput cell analysis further accelerate replacement of manual counting methods.
Europe
Europe accounts for approximately 27% of the Automated Cell Counter Market, driven by strong biomedical research activity and a well-established diagnostics ecosystem. Countries such as Germany, the United Kingdom, and France lead adoption due to extensive clinical trials, cell therapy research, and public healthcare laboratory networks. Growth is supported by increasing automation in hospital laboratories and rising use of fluorescence-based counters for precision diagnostics. Regulatory emphasis on data accuracy and standardization favors automated solutions. Furthermore, expanding biopharmaceutical manufacturing and EU-funded research programs continue to sustain steady regional demand.
Asia-Pacific
Asia-Pacific holds around 25% of the Automated Cell Counter Market and represents the fastest-growing region. Rapid expansion of biotechnology industries in China, Japan, South Korea, and India drives adoption of automated cell analysis tools. Rising investments in drug discovery, regenerative medicine, and vaccine development support demand for high-throughput cell counters. Increasing healthcare expenditure and the expansion of diagnostic laboratories further strengthen market penetration. Additionally, cost-effective manufacturing, growing academic research output, and rising awareness of laboratory automation position Asia-Pacific as a key growth engine over the forecast period.
Latin America
Latin America contributes roughly 6% to the Automated Cell Counter Market, with growth driven by gradual modernization of clinical laboratories and expanding pharmaceutical research. Brazil and Mexico lead regional adoption due to improving healthcare infrastructure and increasing participation in global clinical trials. Demand is supported by the need to enhance laboratory efficiency and reduce manual errors in hematology and cell culture applications. However, budget constraints and uneven access to advanced laboratory technologies limit faster uptake. Ongoing investments in diagnostics and rising collaborations with global life-science companies support steady, incremental growth.
Middle East & Africa
The Middle East & Africa region accounts for about 4% of the Automated Cell Counter Market, reflecting an emerging but developing landscape. Growth is concentrated in the Gulf Cooperation Council countries, where investments in advanced healthcare facilities and research centers are increasing. Automated cell counters gain traction in tertiary hospitals and reference laboratories seeking accuracy and workflow efficiency. In Africa, adoption remains limited due to cost sensitivity and infrastructure gaps, although international funding and public-health initiatives are improving laboratory capabilities. Overall, the region shows gradual adoption with long-term growth potential.
Automated Cell Counter Market Segmentations:
By Product Type:
- Flow cytometer
- Fluorescence image-based cell counter
By Application:
- Blood cells
- Cell lines
By End User:
- Pharmaceutical & biotechnology companies
- Hospitals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The automated cell counter market players such as Chemometec A/S, Sysmex Corporation, Agilent Technologies, Inc., Countstar, Inc., MERCK KGaA, Olympus Corporation, Danaher, Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories, Inc. The automated cell counter market is characterized by intense competition centered on analytical accuracy, system automation, and ease of use across research, clinical, and biopharmaceutical laboratories. Market participants focus on advancing image-based and fluorescence technologies to deliver reliable cell concentration, viability, and morphology analysis while minimizing operator variability. Integration with laboratory information systems, cloud-enabled data management, and AI-driven analysis tools strengthens workflow efficiency and regulatory compliance. Vendors emphasize compact footprints, rapid processing times, and multi-assay compatibility to support high-throughput environments. Competitive differentiation increasingly depends on software sophistication, service reliability, and the ability to support cell therapy, biologics, and precision medicine applications. Ongoing investments in R&D, global service infrastructure, and application-specific customization continue to intensify competition and support sustained market expansion.
Key Player Analysis
- Chemometec A/S
- Sysmex Corporation
- Agilent Technologies, Inc.
- Countstar, Inc.
- MERCK KGaA
- Olympus Corporation
- Danaher
- Thermo Fischer Scientific Inc.
- Hoffmann-La Roche Ltd
- Bio-Rad Laboratories, Inc
Recent Developments
- In October 2024, BD launched robotics-compatible reagent kits in collaboration with Hamilton to automate single-cell analysis, specifically the BD OMICS-One XT WTA Assay, for high-throughput genetic sequencing, streamlining workflows in oncology and immunology by reducing manual steps and increasing consistency for large-scale studies.
- In August 2024, DeNovix launched the CellDrop FLi Automated Cell Counter in August 2024, featuring upgraded hardware and software with new machine-learning powered applications, notably for challenging cells like hepatocytes, improving accuracy for diverse cell types and reducing reliance on disposable slides by using their unique DirectPipette™ tech.
- In June 2024, Bio-Rad launched the ddSEQ™ Single-Cell 3' RNA-Seq Kit and Omnition v1.1 analysis software, offering a more cost-effective, high-throughput method for single-cell gene expression analysis, supporting research in oncology, neurology, and immunology by enabling efficient, affordable transcriptome profiling.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Automated cell counters will see wider adoption in cell and gene therapy workflows due to growing demand for precise viability and concentration analysis.
- Integration of AI and advanced image analytics will enhance accuracy, reduce manual intervention, and improve reproducibility.
- Demand for fluorescence-based and multiparameter cell counting systems will continue to increase in life science research.
- Compact and user-friendly benchtop instruments will gain traction across small and mid-sized laboratories.
- Cloud-enabled data management and connectivity with laboratory information systems will become more common.
- Expansion of biopharmaceutical manufacturing will drive demand for high-throughput and scalable cell counting solutions.
- Regulatory emphasis on data integrity and standardization will encourage adoption of automated platforms.
- Emerging markets will experience faster growth due to expanding research infrastructure and healthcare investment.
- Continuous innovation in reagents and consumables will support recurring revenue models.
- Strategic collaborations between instrument providers and research institutions will accelerate technology advancement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of Automated Laboratory Workflows
Laboratories are increasingly automating cell counting processes to improve throughput, reduce human error, and ensure reproducibility, which is critical for both research and clinical diagnostics. Automated cell counters streamline workflows, enabling faster and more reliable results compared to manual methods.
Expansion of Cell-Based Research and Biopharmaceutical Manufacturing
The growth of cell therapy, regenerative medicine, and biologics manufacturing requires precise, high-throughput cell analysis for process control and quality assurance. Automated cell counters are essential tools for maintaining consistency and compliance in these expanding sectors.
Integration of Advanced Imaging and Fluorescence Technologies
The shift toward image-based and fluorescence-enabled cell counters allows for multiparametric analysis, including viability, morphology, and phenotyping, supporting complex research and clinical applications. This technological advancement drives demand for newer, more capable systems.
Increasing Demand in Clinical and Diagnostic Laboratories
Automated cell counters are widely adopted in clinical settings for blood cell analysis and other routine diagnostics, helping laboratories manage higher sample volumes and meet regulatory standards for accuracy and data integrity.
Preference for Compact and User-Friendly Instruments
Smaller laboratories and decentralized testing sites are seeking benchtop, easy-to-use automated cell counters that require minimal training and maintenance, broadening the market beyond large research and hospital labs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automated Cell Counter Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automated Cell Counter Market projected to grow between 2024 and 2032?
Which Automated Cell Counter Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automated Cell Counter Market?
Who are the leading companies in the Automated Cell Counter Market?
Which region commanded the largest share of the Automated Cell Counter Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Pharmaceutical & biotechnology companies
- 1.2.2 Hospitals
- 1.2.3 Diagnostic laboratories
- 1.2.4 Research institutes
- 1.3 By Application
- 1.3.1 Blood cell analysis
- 1.3.2 Cell line analysis
- 1.3.3 Microbial cell analysis
- 1.3.4 Stem and primary cell analysis
- 1.4 By Product Type
- 1.4.1 Flow cytometer
- 1.4.2 Fluorescence image-based cell counter
- 1.4.3 Coulter counter
- 1.4.4 Others (e.g., brightfield image-based, impedance-based)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,830 million → 2032: USD 10,229.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automated Cell Counter Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automated Cell Counter Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automated Cell Counter Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automated Cell Counter Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automated Cell Counter Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automated Cell Counter Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automated Cell Counter Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automated Cell Counter Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,830 million → 2032: USD 10,229.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automated Cell Counter Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical & biotechnology companies
- 12.3.7.2 Hospitals
- 12.3.7.3 Diagnostic laboratories
- 12.3.7.4 Research institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Blood cell analysis
- 12.4.7.2 Cell line analysis
- 12.4.7.3 Microbial cell analysis
- 12.4.7.4 Stem and primary cell analysis
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flow cytometer
- 12.5.7.2 Fluorescence image-based cell counter
- 12.5.7.3 Coulter counter
- 12.5.7.4 Others (e.g., brightfield image-based, impedance-based)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automated Cell Counter End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automated Cell Counter Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automated Cell Counter Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automated Cell Counter Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Chemometec A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sysmex Corporation
- 18.4 Agilent Technologies, Inc.
- 18.5 Countstar, Inc.
- 18.6 MERCK KGaA
- 18.7 Olympus Corporation
- 18.8 Danaher
- 18.9 Thermo Fisher Scientific Inc.
- 18.10 F. Hoffmann-La Roche Ltd
- 18.11 Bio-Rad Laboratories, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

