
Market Overview
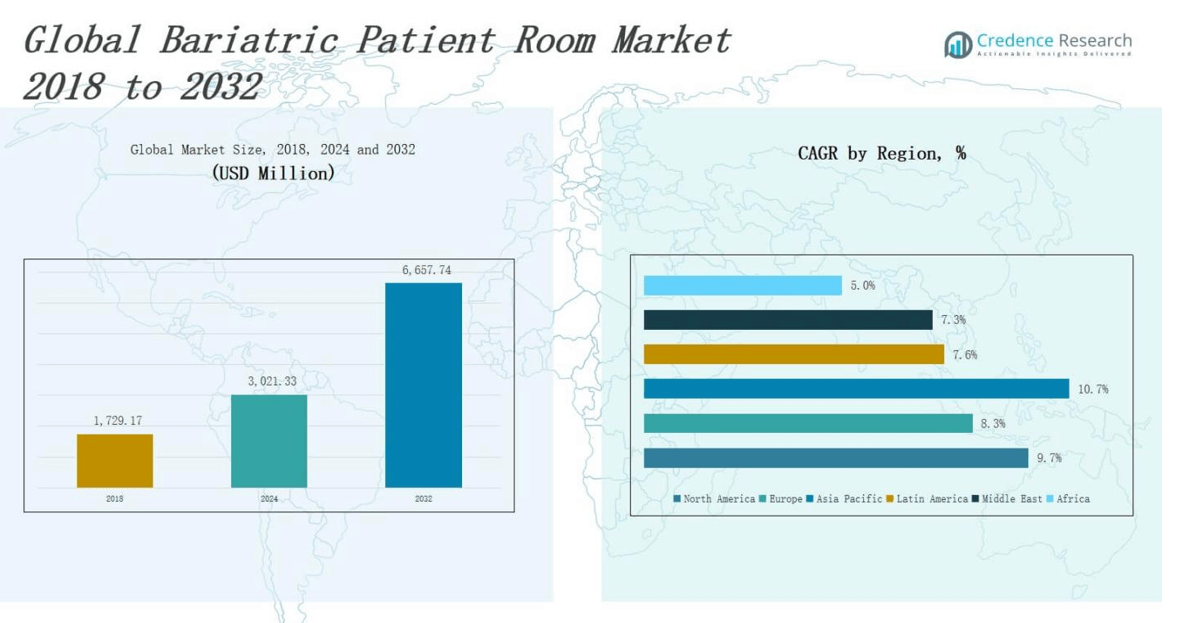
The Bariatric Patient Room Market size was valued at USD 1,729.17 million in 2018 to USD 3,021.33 million in 2024 and is anticipated to reach USD 6,657.74 million by 2032, at a CAGR of 9.67 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bariatric Patient Room Market Size 2024 | USD 3,021.33 million |
| Bariatric Patient Room Market, CAGR | 9.67% |
| Bariatric Patient Room Market Size 2032 | USD 6,657.74 million |
The Bariatric Patient Room market is driven by the rising global prevalence of obesity, which has led to increased demand for specialized healthcare infrastructure tailored to the needs of bariatric patients. Healthcare providers are investing in dedicated rooms equipped with reinforced furniture, wider doorways, ceiling lifts, and high-capacity beds to enhance patient safety, comfort, and mobility. The growing emphasis on patient-centric care and regulatory pressure to meet accessibility standards further accelerates this transition. Technological advancements in hospital equipment-such as motorized transport systems and integrated monitoring solutions-are improving operational efficiency and caregiver ergonomics. Market trends include the integration of smart room technologies for real-time patient monitoring, adoption of modular designs for space optimization, and use of antimicrobial, easy-to-clean materials to maintain hygiene. Additionally, the expansion of private healthcare facilities and increased funding in public hospital infrastructure, especially in North America and Europe, are reinforcing the adoption of bariatric patient rooms as part of broader hospital modernization initiatives.
The Bariatric Patient Room Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads the market due to advanced healthcare infrastructure and high obesity prevalence, followed by Europe with strong regulatory standards and hospital modernization. Asia Pacific shows rapid growth driven by rising healthcare investments and expanding medical facilities. Latin America and the Middle East are emerging markets supported by public hospital upgrades and rising bariatric procedures. Africa holds early-stage potential with increasing focus on healthcare capacity building. Key players operating across these regions include Hillrom (a Baxter company), Stryker Corporation, Arjo AB, LINET Group SE, Invacare Corporation, Drive DeVilbiss Healthcare, Gendron, Inc., Medline Industries, Joerns Healthcare, GF Health Products, Inc., Haelvoet, and Direct Healthcare Group, all competing through innovation, regional expansion, and tailored product offerings for diverse care environments.
Market Insights
- The Bariatric Patient Room Market size grew from USD 1,729.17 million in 2018 to USD 3,021.33 million in 2024 and is projected to reach USD 6,657.74 million by 2032, registering a CAGR of 9.67% during the forecast period.
- Rising global obesity rates are driving demand for reinforced beds, ceiling lifts, and wider rooms, with hospitals prioritizing patient safety and comfort.
- Compliance with regulatory standards and modernization of healthcare infrastructure are prompting upgrades in room design and equipment.
- High capital costs and space limitations remain key barriers, especially for older hospitals that require expensive retrofitting and structural changes.
- North America leads with 35% market share due to advanced infrastructure and government-backed investment in bariatric care facilities.
- Asia Pacific follows with 30% share and the fastest CAGR of 10.7%, supported by rapid healthcare expansion in China, India, and Southeast Asia.
- Key players include Hillrom, Stryker, Arjo, LINET, Invacare, Drive DeVilbiss, Gendron, Medline, Joerns, Haelvoet, GF Health, and Direct Healthcare Group.
Market Drivers
Rising Obesity Rates and Demand for Specialized Care
The global increase in obesity is a primary driver for the Bariatric Patient Room Market. Hospitals and healthcare facilities are under pressure to accommodate patients with higher body mass indexes who require specialized care environments. Standard rooms often lack the infrastructure to support bariatric patients safely and comfortably. The market is expanding as healthcare systems prioritize inclusive treatment spaces. It reflects the growing need for reinforced equipment, larger spaces, and ergonomic solutions. The rising awareness of obesity-related complications further supports the shift toward dedicated bariatric facilities. The Bariatric Patient Room Market is benefiting from this trend, with investments steadily increasing in high-capacity infrastructure.
- For instance, Stryker Corporation launched the SmartBed 2.0 featuring voice-activated controls and predictive fall-risk detection in early 2025.
Healthcare Infrastructure Modernization and Compliance Mandates
The modernization of healthcare facilities to comply with safety, accessibility, and regulatory guidelines strongly influences the Bariatric Patient Room Market. Healthcare institutions are updating older infrastructure to meet guidelines set by ADA, Joint Commission, and other regulatory bodies. These mandates emphasize the need for properly equipped rooms for bariatric patients. It includes requirements for larger doorways, reinforced furniture, and safer patient handling systems. Market growth is tied closely to these compliance initiatives. The demand for retrofitting existing facilities and designing new hospitals with bariatric-friendly features continues to accelerate investment in the market.
- For instance, Manning Hospital in Australia implemented a comprehensive bariatric equipment upgrade, supplying electric beds with higher safe working loads, increasing the availability of bariatric wheelchairs, and introducing a facility-wide protocol for safe patient handling and mobility assessments
Emphasis on Patient Safety and Staff Efficiency
Patient safety and staff ergonomics are critical drivers in the Bariatric Patient Room Market. Lifting and transferring bariatric patients without appropriate equipment increases the risk of injury to both patients and caregivers. Healthcare providers are investing in ceiling lifts, motorized beds, and transfer aids to reduce manual handling. It ensures better outcomes and minimizes staff fatigue or injury. The market responds to this demand by offering integrated systems that support safe, efficient patient care. Optimizing workflow while enhancing safety is central to modern room design.
Technological Advancements and Smart Room Integration
Technological innovations play a key role in expanding the Bariatric Patient Room Market. Smart technologies-such as automated monitoring, adjustable room controls, and mobile care integration-are becoming standard features in bariatric care settings. These solutions improve patient comfort, assist in real-time monitoring, and streamline clinical operations. It aligns with hospitals’ goals of digital transformation and outcome-driven care. The market is witnessing strong interest in AI-enabled systems and IoT-connected equipment tailored for bariatric use. Enhanced user interfaces and data-driven care features are reshaping patient room functionality and driving sustained market growth.
Market Trends
Integration of Smart Technologies and Real-Time Monitoring
Smart healthcare solutions are shaping the evolution of the Bariatric Patient Room Market. Hospitals are incorporating real-time patient monitoring systems, automated lighting, voice-activated controls, and integrated nurse call systems to improve safety and responsiveness. These features enable caregivers to monitor vital signs, movement, and comfort levels without physical intervention. It enhances patient care and reduces staff workload. The adoption of IoT-enabled equipment and data-driven decision-making supports efficient patient management. The Bariatric Patient Room Market is steadily embracing this digital transformation to improve outcomes and operational efficiency.
- For instance, Hillrom launched an advanced bariatric bed in 2024 with built-in pressure-relief surfaces and automated adjustment mechanisms, directly addressing patient comfort and reducing the risk of bedsores while supporting staff workflow.
Expansion of Customizable and Modular Room Designs
The shift toward modular and customizable patient rooms is gaining momentum in the Bariatric Patient Room Market. Healthcare facilities are prioritizing flexible layouts that accommodate a range of patient needs while ensuring structural durability. Architects and planners now focus on adaptable room configurations that support easy retrofitting. It allows hospitals to future-proof infrastructure and optimize space without compromising patient comfort. Wider doorways, reinforced wall structures, and scalable components are becoming standard. The market is responding with prefabricated modular solutions that simplify construction and enhance long-term value.
- For instance, The Miriam Hospital in Providence, Rhode Island, introduced a floor of 36 acuity-adaptable private rooms designed on a modular grid, allowing beds to serve as swing beds and rooms to be upgraded to critical care standards as needed.
Increased Focus on Ergonomics and Human-Centered Design
Human-centered design principles are playing a greater role in the Bariatric Patient Room Market. Facilities are redesigning spaces to ensure comfort, mobility, and dignity for bariatric patients. Ergonomically positioned fixtures, larger restrooms, and low-friction flooring are incorporated to reduce patient strain and enhance caregiver efficiency. It contributes to a safer and more inclusive care environment. Manufacturers are offering design-forward furniture and equipment that support both clinical function and aesthetic appeal. This focus on usability is setting new benchmarks across bariatric healthcare environments.
Sustainability and Infection Control in Room Materials
Sustainability and infection control are now key design priorities in the Bariatric Patient Room Market. Facilities are adopting antimicrobial surfaces, seamless flooring, and washable wall panels to improve hygiene and reduce infection risk. Eco-friendly, low-emission materials are being selected to support environmental goals without compromising strength. It reflects a dual commitment to patient safety and sustainability. The market is seeing growing demand for products that meet green building certifications. Hospitals are aligning room designs with both infection prevention standards and climate-conscious construction practices.
Market Challenges Analysis
High Capital Investment and Infrastructure Constraints
The Bariatric Patient Room Market faces significant challenges related to high initial investment and facility adaptation costs. Designing rooms with reinforced structures, wider layouts, and specialized equipment requires considerable financial resources. Many existing hospitals operate in space-constrained environments, making retrofitting complex and expensive. It limits rapid adoption, particularly in smaller or older facilities. Budget constraints and competing infrastructure priorities can delay bariatric room implementation. The market must address these barriers to ensure broader accessibility and scalability of specialized care environments.
Limited Staff Training and Operational Readiness
Operational challenges persist in the Bariatric Patient Room Market due to insufficient staff training and preparedness. Caring for bariatric patients requires specific protocols, handling techniques, and familiarity with specialized equipment. Without adequate training, caregivers face safety risks and reduced efficiency. It hampers the effectiveness of advanced room features and impacts patient outcomes. Institutions often struggle to align staff readiness with infrastructure upgrades. The market must emphasize ongoing education and support systems to ensure functional deployment and long-term care quality.
Market Opportunities
Growing Demand in Emerging Healthcare Markets
Expanding healthcare infrastructure in emerging economies presents strong growth opportunities for the Bariatric Patient Room Market. Rising obesity rates in Asia-Pacific, Latin America, and the Middle East are creating a need for specialized patient care solutions. Governments and private hospitals are increasing investment in modern facilities, which opens the door for advanced bariatric room installations. It enables market players to offer scalable, cost-effective designs suited for diverse hospital settings. Local partnerships and public health initiatives can accelerate market entry and adoption. The Bariatric Patient Room Market is well-positioned to serve this rising demand with region-specific innovations.
Expansion of Homecare and Long-Term Care Facilities
The shift toward decentralized care models offers a new growth path for the Bariatric Patient Room Market. Homecare and long-term care facilities are expanding services to accommodate bariatric patients outside traditional hospital settings. This trend requires compact, mobile, and easy-to-install solutions that support patient comfort and caregiver safety. It drives demand for portable lifts, modular furnishings, and smart monitoring systems tailored for non-hospital environments. Manufacturers have an opportunity to design specialized products for these care settings. The market can grow by addressing this under-served segment with adaptable, user-friendly room solutions.
Market Segmentation Analysis:
By Product Type
The Bariatric Patient Room Market is segmented by product type into bariatric beds, wheelchairs, lifts and transfer equipment, toilets and bathroom facilities, reinforced furniture, design solutions, and others. Bariatric beds and wheelchairs are essential for mobility and safety. Lifts, including ceiling and mobile options, assist in safe patient transfers. Reinforced furniture such as chairs, overbed tables, and bedside units support higher weight capacities. Scales and supportive accessories also enhance patient care and room functionality.
- For instance, Medline Industries expanded its bariatric product line to include heavy-duty mobility aids and patient transfer systems, specifically designed to improve comfort and safety for bariatric patients during hospital stays.
By End User
The Bariatric Patient Room Market by end user includes hospitals, specialty clinics, nursing homes, rehabilitation centers, and others. Hospitals dominate this segment due to high patient throughput and infrastructure capabilities. Specialty clinics, including weight loss and bariatric surgery centers, demand purpose-built solutions. Nursing homes and rehabilitation centers require long-term bariatric care. Home healthcare and government units represent emerging opportunities. It shows growing interest in modular, transportable equipment tailored for non-hospital care environments and diverse clinical settings.
- For instance, Hillrom launched the Compella™ Bariatric Bed, supporting higher weight capacities and advanced mobility features for acute and long-term care.
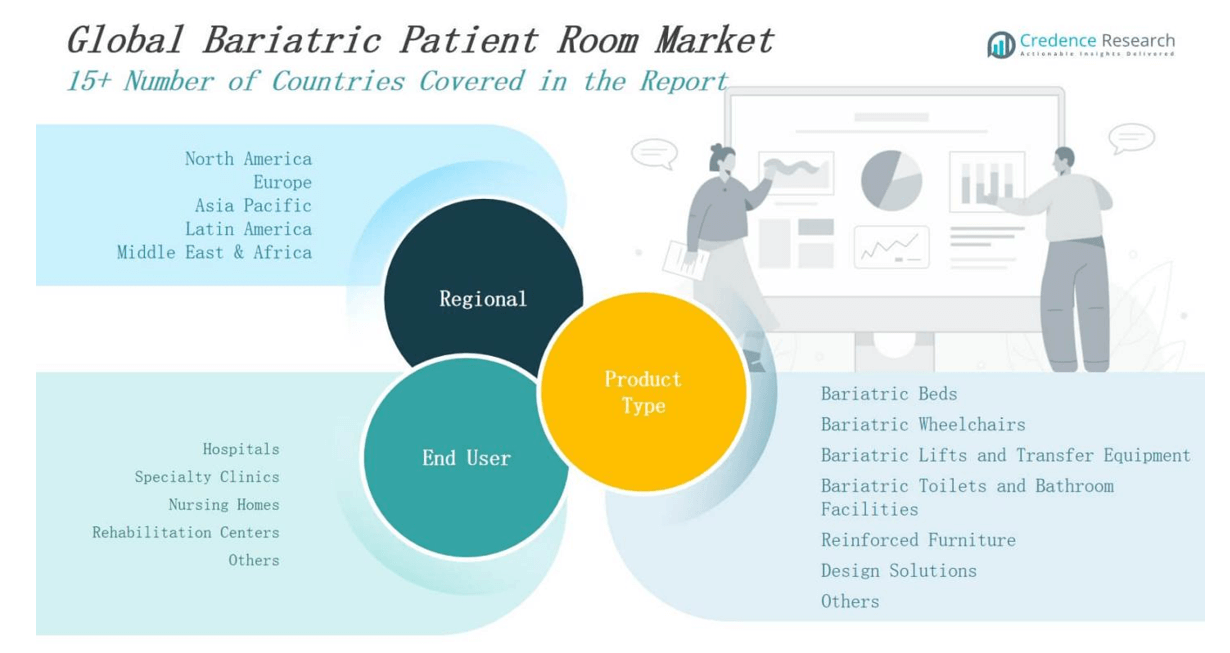
Segments:
Based on Product Type
- Bariatric Beds
- Bariatric Wheelchairs
- Bariatric Lifts and Transfer Equipment
- Ceiling lifts
- Mobile lifts
- Bariatric Toilets and Bathroom Facilities
- Reinforced Furniture
- Chairs
- Bedside tables
- Overbed tables
- Design Solutions
- Others
- Scales
- Supportive accessories
Based on End User
- Hospitals
- Specialty Clinics
- Weight loss centers
- Bariatric surgery facilities
- Nursing Homes
- Rehabilitation Centers
- Others
- Home healthcare
- Government medical units
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Bariatric Patient Room Market size was valued at USD 728.38 million in 2018 to USD 1,258.98 million in 2024 and is anticipated to reach USD 2,782.24 million by 2032, at a CAGR of 9.7% during the forecast period. North America holds the largest share in the global Bariatric Patient Room Market, contributing 35% of the total revenue. The United States leads adoption with advanced healthcare infrastructure, rising obesity rates, and strong regulatory compliance. Hospitals across the region are increasingly incorporating bariatric beds, lifts, and reinforced furniture to meet clinical demands. Canada and Mexico follow with rising investments in healthcare modernization and specialty clinics. It benefits from supportive reimbursement frameworks, innovation in room design, and high public healthcare spending.
Europe
The Europe Bariatric Patient Room Market size was valued at USD 306.65 million in 2018 to USD 504.90 million in 2024 and is anticipated to reach USD 1,006.07 million by 2032, at a CAGR of 8.3% during the forecast period. Europe holds a 24% share of the global market, driven by structured public healthcare systems and strict safety standards. Germany, France, and the UK lead in bariatric room implementation due to growing obesity rates and emphasis on hospital quality standards. Demand for ergonomic design and infection control solutions continues to increase. It benefits from initiatives to retrofit aging infrastructure and expand specialized treatment centers. European manufacturers are also active in offering sustainable and modular room solutions.
Asia Pacific
The Asia Pacific Bariatric Patient Room Market size was valued at USD 562.19 million in 2018 to USD 1,031.05 million in 2024 and is anticipated to reach USD 2,456.01 million by 2032, at a CAGR of 10.7% during the forecast period. Asia Pacific accounts for 30% of the global market, supported by rising obesity levels, growing healthcare investments, and expanding hospital networks. China, India, Japan, and Australia are key growth markets with increasing demand for bariatric-capable infrastructure. Public and private sector initiatives are driving the construction of advanced medical facilities. It is rapidly adopting modular room designs, patient safety technologies, and integrated equipment. Local production and government incentives are improving accessibility and reducing costs.
Latin America
The Latin America Bariatric Patient Room Market size was valued at USD 66.49 million in 2018 to USD 114.40 million in 2024 and is anticipated to reach USD 216.40 million by 2032, at a CAGR of 7.6% during the forecast period. Latin America represents 6% of the global market and shows growing interest in bariatric healthcare infrastructure. Brazil and Mexico are leading adoption through investments in public hospitals and bariatric surgery centers. Urbanization and increasing obesity prevalence are pushing demand for larger, better-equipped patient rooms. It is gradually incorporating international design standards and safety protocols. Supplier partnerships and foreign direct investments support the expansion of high-capacity hospital rooms across the region.
Middle East
The Middle East Bariatric Patient Room Market size was valued at USD 47.47 million in 2018 to USD 75.66 million in 2024 and is anticipated to reach USD 140.10 million by 2032, at a CAGR of 7.3% during the forecast period. The Middle East holds 4% of the global market, driven by rising healthcare expenditure and an increasing burden of obesity-related conditions. Gulf Cooperation Council (GCC) countries are investing in high-end bariatric units as part of hospital expansion projects. Saudi Arabia and the UAE are leading markets with strong emphasis on healthcare infrastructure. It benefits from government-backed health initiatives and rising demand for specialized surgical centers. The market is also adopting smart hospital room technologies to support patient monitoring and care efficiency.
Africa
The Africa Bariatric Patient Room Market size was valued at USD 18.00 million in 2018 to USD 36.35 million in 2024 and is anticipated to reach USD 56.93 million by 2032, at a CAGR of 5.0% during the forecast period. Africa contributes 1% to the global market and remains in the early stages of bariatric room adoption. South Africa leads regional demand, followed by Egypt and Nigeria. Public hospitals are slowly integrating bariatric facilities in response to rising obesity and comorbidity rates. It is challenged by limited budgets and infrastructure gaps but offers long-term potential through international aid and private investments. Local governments are beginning to prioritize obesity treatment through capacity-building and healthcare modernization programs.
Key Player Analysis
- Haelvoet
- GF Health Products, Inc.
- Direct Healthcare Group
- Medline Industries, LP
- LINET Group SE
- Joerns Healthcare
- Invacare Corporation
- Drive DeVilbiss Healthcare
- Gendron, Inc.
- Hillrom (a Baxter company)
- Arjo AB
- Stryker Corporation
Competitive Analysis
The Bariatric Patient Room Market features strong competition among global and regional players focusing on innovation, customization, and patient-centric design. Companies such as Hillrom (a Baxter company), Stryker Corporation, Arjo AB, and LINET Group SE lead the market with advanced bariatric beds, transfer systems, and integrated room solutions. It remains highly competitive due to increasing demand for safety, durability, and space optimization in patient care environments. Manufacturers are expanding portfolios with ergonomic designs, antimicrobial materials, and smart technologies. Regional players like Gendron, Inc. and Haelvoet compete by offering cost-effective, durable equipment tailored to local requirements. Medline Industries, Joerns Healthcare, and Drive DeVilbiss Healthcare focus on turnkey bariatric solutions for hospitals, clinics, and long-term care settings. The Bariatric Patient Room Market is witnessing strategic partnerships, product launches, and facility expansion as key players aim to strengthen distribution networks and serve diverse care settings across developed and emerging markets.
Recent Developments
- In February 2025, Stryker launched the ProCeed hospital bed, which is known for its durability and features like an IPX6-rated frame and a low-height design. The bed is designed to enhance patient safety and caregiver workflows by simplifying operations and improving ease of use.
- In 2023, Hillrom introduced the Progressa+ ICU bed, designed to support early mobility protocols and advanced skin protection in intensive care units .
- In 2025, Teleflex completed the acquisition of substantially all of Biotronik's Vascular Intervention business for €760 million, as announced on July 1, 2025. This acquisition is intended to enhance Teleflex's hospital-focused product portfolio, particularly in the cath lab and peripheral intervention markets.
- In 2024, Stryker expanded its MV3 Bariatric Bed with advanced fall-prevention features, including the iBed Awareness exit system and a low deck height for improved patient safety
Market Concentration & Characteristics
The Bariatric Patient Room Market is moderately concentrated, with a mix of global manufacturers and regional suppliers competing across key segments. Leading players such as Hillrom, Stryker, Arjo, and LINET dominate due to their advanced product portfolios, established distribution networks, and strong brand credibility. It features high entry barriers driven by the need for regulatory compliance, design expertise, and capital investment in specialized infrastructure. The market is characterized by growing demand for ergonomic equipment, modular room configurations, and smart technologies tailored to bariatric patient care. Companies compete by offering reinforced beds, motorized lifts, and space-efficient furniture with a focus on patient safety and caregiver efficiency. Regional players gain ground by delivering cost-effective, locally adapted solutions. The Bariatric Patient Room Market supports both retrofitting in legacy hospitals and construction of purpose-built facilities, reflecting demand from public and private healthcare institutions. Innovation, compliance, and customization remain the core attributes shaping competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising obesity rates will continue to drive demand for bariatric-specific patient care environments globally.
- Hospitals will increase investments in reinforced infrastructure to ensure patient safety and staff efficiency.
- Modular bariatric room designs will enable flexible layouts and faster installations in healthcare facilities.
- Smart technologies will support real-time monitoring, reducing risks and improving patient management outcomes.
- Retrofitting older hospitals with bariatric solutions will grow to meet updated regulatory compliance standards.
- Public and private sector partnerships will expand access to bariatric care across diverse healthcare systems.
- Manufacturers will prioritize ergonomic equipment that reduces physical strain on healthcare workers during patient handling.
- Healthcare expansion in emerging regions will open new opportunities for bariatric room adoption and customization.
- Portable bariatric furniture and transfer devices will support growing demand for home-based care solutions.
- Sustainable and hygienic materials will gain preference for improved safety and environmental compliance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Obesity Rates
The increasing prevalence of obesity worldwide is compelling healthcare providers to invest in specialized bariatric patient rooms equipped with reinforced beds, wider doorways, and high-capacity furniture to ensure patient safety and comfort.
Healthcare Infrastructure Modernization and Regulatory Compliance
Hospitals are upgrading and retrofitting facilities to comply with accessibility and safety regulations, such as ADA and Joint Commission standards, which mandate the inclusion of bariatric-friendly features and equipment.
Emphasis on Patient Safety and Staff Efficiency
The need to reduce injury risks for both patients and caregivers is driving the adoption of ceiling lifts, motorized beds, and ergonomic transfer aids, supporting safer and more efficient patient handling in bariatric care environments.
Technological Advancements and Smart Room Integration
The integration of smart technologies, such as real-time patient monitoring, automated controls, and IoT-enabled equipment, is enhancing operational efficiency, patient outcomes, and caregiver ergonomics in bariatric patient rooms.
Expansion of Healthcare Facilities in Emerging Markets
Rapid healthcare investment and hospital construction in Asia Pacific, Latin America, and the Middle East are creating new opportunities for bariatric patient room adoption, as these regions address rising obesity rates and modernize their medical infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bariatric Patient Room Market?
What are the key segments within the Bariatric Patient Room Market?
What are some challenges faced by the Bariatric Patient Room Market?
Who are the major players in the Bariatric Patient Room Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Specialty Clinics (Weight Loss Centers, Bariatric Surgery Facilities)
- 1.2.3 Nursing Homes
- 1.2.4 Rehabilitation Centers
- 1.2.5 Others (Home Healthcare, Government Medical Units)
- 1.3 By Product Type
- 1.3.1 Bariatric Beds
- 1.3.2 Bariatric Wheelchairs
- 1.3.3 Bariatric Lifts and Transfer Equipment
- 1.3.4 Bariatric Toilets and Bathroom Facilities
- 1.3.5 Reinforced Furniture
- 1.3.6 Design Solutions
- 1.3.7 Others (Scales, Supportive Accessories)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,021.33 million → 2032: USD 6,657.74 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bariatric Patient Room Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bariatric Patient Room Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bariatric Patient Room Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bariatric Patient Room Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bariatric Patient Room Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bariatric Patient Room Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bariatric Patient Room Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bariatric Patient Room Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,021.33 million → 2032: USD 6,657.74 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bariatric Patient Room Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Specialty Clinics (Weight Loss Centers, Bariatric Surgery Facilities)
- 12.3.7.3 Nursing Homes
- 12.3.7.4 Rehabilitation Centers
- 12.3.7.5 Others (Home Healthcare, Government Medical Units)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bariatric Beds
- 12.4.7.2 Bariatric Wheelchairs
- 12.4.7.3 Bariatric Lifts and Transfer Equipment
- 12.4.7.4 Bariatric Toilets and Bathroom Facilities
- 12.4.7.5 Reinforced Furniture
- 12.4.7.6 Design Solutions
- 12.4.7.7 Others (Scales, Supportive Accessories)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bariatric Patient Room End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bariatric Patient Room Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bariatric Patient Room Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bariatric Patient Room Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hillrom (a Baxter company)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stryker Corporation
- 18.4 Arjo AB
- 18.5 LINET Group SE
- 18.6 Invacare Corporation
- 18.7 Drive DeVilbiss Healthcare
- 18.8 Gendron, Inc.
- 18.9 Medline Industries
- 18.10 Joerns Healthcare
- 18.11 GF Health Products, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

