
Market Overview
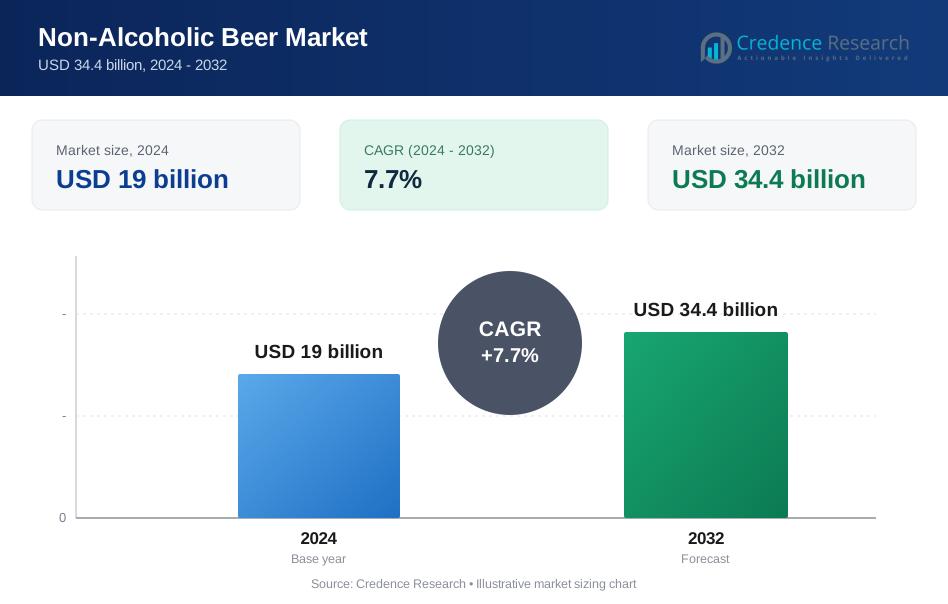
The Non-Alcoholic Beer Market size was valued at USD 19 million in 2024 and is projected to reach USD 34.4 million by 2032, expanding at a CAGR of 7.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Non-Alcoholic Beer Market Size 2024 | USD 19 Million |
| Non-Alcoholic Beer Market, CAGR | 7.7% |
| Non-Alcoholic Beer Market Size 2032 | USD 34.4 Million |
The Non-Alcoholic Beer Market grows through rising health consciousness, lifestyle shifts, and the preference for low-calorie alternatives. Consumers adopt non-alcoholic options for social occasions, sports recovery, and wellness-focused diets. Breweries expand portfolios with premium, craft-style, and flavored variants to match evolving tastes.
The Non-Alcoholic Beer Market demonstrates strong global presence, with significant growth in North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America leads adoption due to rising health awareness and cultural acceptance of alcohol-free options in social occasions, supported by growing retail and e-commerce distribution. Europe maintains steady demand, driven by traditional beer-producing nations such as Germany, the UK, and the Netherlands, where innovation in premium and flavored variants remains strong. Asia Pacific emerges as the fastest-growing region, supported by urbanization, rising disposable incomes, and increasing consumer openness to healthier beverages in China, Japan, and India. Latin America and the Middle East & Africa show steady expansion, influenced by lifestyle changes and regulatory factors promoting alcohol-free beverages. Key players such as Heineken N.V., Anheuser-Busch InBev, Carlsberg A/S, and Athletic Brewing Company drive competitiveness through product innovation, marketing strategies, and expanded distribution networks.
Market Insights
- The Non-Alcoholic Beer Market was valued at USD 19 billion in 2024 and is projected to reach USD 34.4 billion by 2032, growing at a CAGR of 7.7% during the forecast period.
- Growing health awareness and demand for low-calorie beverages drive adoption, with consumers seeking alternatives that support wellness without alcohol-related risks.
- Trends highlight rising interest in premium, craft-style, and flavored non-alcoholic beers, supported by innovation in brewing technologies that improve taste and authenticity.
- Competitive intensity remains strong with leading players such as Heineken N.V., Anheuser-Busch InBev, Carlsberg A/S, and Athletic Brewing Company expanding portfolios, launching new products, and investing in sustainability-focused strategies.
- High production costs, limited consumer awareness in emerging economies, and persistent perception challenges regarding taste quality act as key restraints for market growth.
- Regional analysis shows North America leading adoption through health-driven demand and e-commerce growth, Europe maintaining steady demand with strong brewery innovation, and Asia Pacific emerging as the fastest-growing region supported by urbanization and rising disposable incomes. Latin America and the Middle East & Africa continue gradual adoption influenced by cultural and regulatory dynamics.
- Long-term opportunities lie in expansion into functional beverages, integration with e-commerce and digital retail platforms, and wider penetration in untapped emerging economies where health trends and lifestyle shifts are reshaping consumer preferences.

Market Drivers
Growing Health and Wellness Awareness Among Consumers
The Non-Alcoholic Beer Market benefits from rising global health awareness and preference for low-calorie beverages. Consumers seek alternatives that reduce alcohol intake without sacrificing taste. Non-alcoholic beer offers vitamins, minerals, and isotonic properties that attract health-conscious buyers. Younger demographics and athletes adopt it for hydration and recovery. It appeals strongly to those avoiding alcohol for lifestyle or medical reasons. This demand strengthens market penetration across developed and emerging regions.
- For instance, Athletic Brewing Company reported sales surpassing USD 130 million in 2024, supported by its positioning as a wellness-oriented brand, and it doubled annual production capacity to nearly 1.2 million barrels with its San Diego brewery expansion.
Rising Acceptance of Non-Alcoholic Beverages in Social Occasions
The Non-Alcoholic Beer Market expands with greater acceptance of alcohol-free options in social and professional environments. Restaurants, bars, and event venues increase offerings to meet changing preferences. Consumers appreciate the ability to participate in social drinking culture without alcohol-related risks. Global campaigns on responsible drinking reinforce this adoption. It drives steady demand for premium and craft-style non-alcoholic beers. Wider availability in hospitality settings further boosts consumption trends.
- For instance, Heineken 0.0 was available in more than 110 countries by 2024, and the brand’s dedicated campaigns like “0.0 Reasons Needed” increased trial rates across global markets, with sales of Heineken’s no-alcohol range growing by 11% year-over-year in 2023.
Innovation in Brewing Technologies and Product Varieties
The Non-Alcoholic Beer Market advances through continuous innovations in brewing and de-alcoholization techniques. Brewers introduce improved flavor profiles and diverse options ranging from lagers to craft-inspired varieties. Technological improvements reduce bitterness and maintain original taste quality. Premium segments focus on enhancing mouthfeel and aroma to rival traditional beer. It increases consumer confidence in alcohol-free choices. This innovation pipeline sustains long-term growth momentum.
Government Support and Regulatory Encouragement for Low-Alcohol Products
The Non-Alcoholic Beer Market benefits from favorable policies promoting reduced alcohol consumption. Governments and health agencies encourage alcohol-free alternatives to address public health concerns. Retailers highlight these products in responsible consumption campaigns. Tax incentives in some regions lower retail prices for non-alcoholic options. It reinforces adoption across diverse consumer segments. Supportive regulation ensures consistent availability and rising visibility in mainstream markets.
Market Trends
Expansion of Premium and Craft-Style Non-Alcoholic Beers
The Non-Alcoholic Beer Market sees strong momentum in premium and craft-inspired product lines. Breweries emphasize quality ingredients and unique brewing processes to replicate authentic beer experiences. Craft segments introduce flavor-rich varieties like IPA, wheat, and dark lagers. Consumers respond positively to artisanal branding and authenticity cues. It highlights the shift from mass-produced products to premium alcohol-free alternatives. This trend strengthens brand differentiation in competitive markets.
- For instance, Carlsberg launched its Baltika 0 line with over 15 flavor variants in Russia, and in 2023 it brewed more than 200 million liters of alcohol-free beer across Europe, reinforcing its premium positioning in this segment.
Growing Influence of E-Commerce and Digital Retail Channels
The Non-Alcoholic Beer Market gains traction through expanding e-commerce and online retail platforms. Digital channels increase accessibility for consumers seeking diverse options. Subscription models and direct-to-consumer strategies enhance product reach. Online reviews and digital campaigns influence purchasing decisions. It drives higher engagement with health-focused and tech-savvy audiences. Retailers leverage data analytics to target non-alcoholic beer promotions effectively.
Focus on Sustainability and Eco-Friendly Packaging Solutions
The Non-Alcoholic Beer Market trends toward sustainable production and packaging methods. Breweries invest in recyclable cans, lightweight bottles, and eco-friendly supply chains. Consumers show growing preference for brands with strong environmental commitments. It pushes manufacturers to innovate in reducing carbon footprints. Partnerships with green logistics providers further reinforce this trend. Sustainability initiatives improve both market reputation and consumer loyalty.
Rising Demand Across Emerging Economies with Lifestyle Shifts
The Non-Alcoholic Beer Market expands across emerging economies experiencing urbanization and rising disposable incomes. Younger populations adopt alcohol-free alternatives that align with modern lifestyle choices. Distribution networks in Asia, Latin America, and the Middle East broaden availability. It supports wider acceptance in regions traditionally dominated by soft drinks or limited beverage categories. Cultural acceptance of alcohol-free beverages boosts market penetration. This demand enhances global growth prospects for manufacturers.
- For instance, in the Middle East and North Africa, brewers like Anheuser-Busch InBev and Carlsberg see increasing interest in alcohol-free brews. Anheuser-Busch InBev, for example, is actively expanding in the Middle East, promoting its non-alcoholic brand, Corona Cero, to audiences of the Olympic and Paralympic Games. This leverages its role as a global beer sponsor, aligning with responsible consumption messages to a global audience.
Market Challenges Analysis
High Production Costs and Technical Brewing Complexities
The Non-Alcoholic Beer Market faces challenges linked to high production costs and complex brewing requirements. Advanced de-alcoholization processes demand significant investment in technology and equipment. Small- and medium-sized brewers struggle to compete with larger players due to high operational expenses. Maintaining authentic taste while removing alcohol remains a technical hurdle for many producers. It creates barriers for new entrants looking to establish competitive positions. Limited economies of scale further restrict profitability in this segment.
Consumer Perception and Limited Awareness in Emerging Regions
The Non-Alcoholic Beer Market encounters challenges due to persistent consumer perception issues in certain regions. Some buyers associate alcohol-free beers with inferior taste compared to traditional options. Limited awareness in emerging markets slows adoption despite growing demand for healthier choices. Cultural preferences and restrictions also limit acceptance in specific geographies. It places pressure on companies to invest in branding and awareness campaigns. Strong marketing efforts are required to change consumer mindsets and highlight product benefits.
Market Opportunities
Expansion into Health-Conscious and Functional Beverage Segments
The Non-Alcoholic Beer Market holds strong opportunities in health-focused beverage categories. Producers can introduce variants enriched with vitamins, minerals, or plant-based ingredients. Functional offerings that support hydration, recovery, or low-calorie needs appeal to wellness-driven consumers. Growing demand for alcohol alternatives among athletes and younger demographics widens adoption. It creates a pathway for innovation that combines traditional brewing with nutritional benefits. This opportunity strengthens positioning against both alcoholic beers and soft drinks.
Growth Potential in Untapped Emerging Economies
The Non-Alcoholic Beer Market gains opportunities from rising disposable incomes and urbanization in emerging regions. Expanding retail networks in Asia, Latin America, and the Middle East improve access to alcohol-free products. Rising cultural acceptance and government initiatives supporting healthy lifestyles boost visibility. Premium and affordable product ranges can cater to different consumer segments in these markets. It encourages global brewers to localize flavors and packaging for regional preferences. Strong entry into untapped economies ensures long-term expansion for manufacturers.
Market Segmentation Analysis:
By Product
The Non-Alcoholic Beer Market demonstrates clear segmentation by product, with alcohol-free and low-alcohol beer leading consumption patterns. Alcohol-free beer attracts strong demand due to rising health awareness and consumer preference for beverages without intoxication effects. Low-alcohol beer maintains steady popularity in regions with moderate drinking cultures, offering a balance between flavor and reduced alcohol content. Global brewers invest in refining taste and aroma profiles to match traditional beers. It ensures both product types remain relevant to varying consumer lifestyles. This dual-product structure secures a broader market reach across multiple demographics.
- For instance, In 2023, Athletic Brewing Company sold over 258,000 barrels of alcohol-free beer, which amounts to more than 6 million gallons, from its facilities in Connecticut and California. The company's expansion was driven by a surge in U.S. consumer demand for non-alcoholic options, and it has since become the top-selling non-alcoholic beer brand in America.
By Category
The Non-Alcoholic Beer Market divides into plain and flavored categories, with flavored beer gaining notable traction. Fruit-infused, malt-based, and craft-inspired varieties appeal to younger consumers seeking unique taste experiences. Plain non-alcoholic beer retains strong appeal among traditional drinkers looking for close substitutes to regular beer. Breweries expand portfolios with seasonal and limited-edition flavors to attract repeat purchases. It demonstrates how diverse categories respond to changing palates across global markets. Continuous innovation in flavored options drives differentiation and brand recognition.
By Material
The Non-Alcoholic Beer Market segments by material, covering malt-based and other ingredient-driven options such as rice or corn. Malt-based non-alcoholic beers dominate due to their authentic brewing process and closer resemblance to conventional beer. Alternative bases grow in popularity in regions with dietary restrictions or demand for lighter taste profiles. Brewers experiment with mixed grains to enhance nutritional value and diversify product offerings. It supports growth by appealing to consumers with varied dietary and cultural needs. Material-based differentiation ensures that manufacturers cater to both traditional beer enthusiasts and health-conscious buyers.
- For instance, AB InBev invested €31 million in 2023 for technology to upgrade its brewing of malt-based non-alcoholic beers, enhancing bottling and optimizing dealcoholization systems.
Segments:
Based on Product
- Alcohol-free
- Low Alcohol
Based on Category
- Plain
- Flavored
Based on Material
- Malted Grains
- Hops
- Yeasts
- Enzymes
Based on Sales Channel
- Convenience Stores
- Liquor Stores
- Supermarkets
- Restaurants & Bars
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for nearly 32% of the global Non-Alcoholic Beer Market in 2024, establishing it as a key regional leader. The United States drives this dominance with a rising number of health-conscious consumers and expanding retail distribution. Growing cultural acceptance of alcohol-free beverages in both social and professional settings fuels market expansion. Canada contributes steadily, supported by growing demand for wellness-oriented products and premium non-alcoholic beer varieties. Mexico shows rising adoption, aided by changing consumption habits and increased availability in supermarkets and convenience stores. It reflects the region’s strong focus on innovation, premium branding, and wide consumer reach.
Europe
Europe represents around 30% of the global Non-Alcoholic Beer Market in 2024, driven by its deep-rooted beer culture and changing health trends. Germany leads adoption with a long history of producing alcohol-free beer that mirrors traditional brewing quality. The United Kingdom and France contribute through premium and flavored product innovations, which attract younger audiences. Nordic countries highlight strong demand, supported by strict alcohol regulations and rising health awareness. Breweries in Europe invest heavily in product diversification, including flavored and craft-style non-alcoholic beers. It secures Europe as a mature and innovation-driven market for alcohol-free alternatives.
Asia Pacific
Asia Pacific holds nearly 22% of the global Non-Alcoholic Beer Market in 2024, making it the fastest-growing region. China and Japan lead adoption with expanding urban populations and increasing preference for healthier beverages. India shows accelerating demand as awareness of wellness-oriented products spreads across middle-class consumers. South Korea and Australia add to growth with premium non-alcoholic beer offerings in urban retail and hospitality sectors. Expanding e-commerce platforms in the region improve accessibility and strengthen consumer engagement. It highlights Asia Pacific’s strong growth trajectory driven by urbanization, rising disposable incomes, and evolving lifestyle preferences.
Latin America
Latin America accounts for about 9% of the global Non-Alcoholic Beer Market in 2024, reflecting steady but growing adoption. Brazil leads regional demand, driven by urban populations seeking healthier beverage alternatives. Mexico contributes significantly, with cultural openness to alcohol-free products and rising penetration in hospitality sectors. Argentina and Chile also show consistent growth, supported by expanding retail presence and awareness campaigns. Premium and flavored options gain popularity among younger demographics across metropolitan areas. It demonstrates Latin America’s gradual but positive shift toward non-alcoholic beverage consumption.
Middle East and Africa (MEA)
The Middle East and Africa collectively represent nearly 7% of the global Non-Alcoholic Beer Market in 2024, making it the smallest yet promising segment. The Middle East shows strong demand due to cultural restrictions on alcoholic beverages, creating a favorable market for non-alcoholic alternatives. Countries such as Saudi Arabia and the United Arab Emirates adopt premium non-alcoholic beers widely, supported by hospitality and tourism growth. Africa contributes through rising urbanization and expanding consumer awareness, particularly in South Africa and Nigeria. Limited purchasing power in some markets remains a restraint, yet demand grows steadily through retail and hospitality channels. It underscores MEA’s role as an emerging market with high cultural and regulatory alignment for alcohol-free products.
Key Player Analysis
- Radeberger Gruppe
- Athletic Brewing Company
- Van Pur
- Feldschlosschen Getranke AG
- Carlsberg A/S
- Moscow Brewing Company
- Bundaberg Brewed Drinks
- Volfas Engelman
- Heineken N.V.
- Anheuser-Busch InBev
Competitive Analysis
The competitive landscape of the Non-Alcoholic Beer Market is defined by major players including Heineken N.V., Anheuser-Busch InBev, Carlsberg A/S, Athletic Brewing Company, Bundaberg Brewed Drinks, Radeberger Gruppe, Volfas Engelman, Van Pur, Feldschlosschen Getranke AG, and Moscow Brewing Company. These companies focus on expanding product portfolios with premium, craft-style, and flavored alcohol-free beers to meet evolving consumer preferences. Global leaders invest heavily in research and development to enhance taste quality and ensure closer resemblance to traditional beers through advanced de-alcoholization technologies. Strategic collaborations with retailers, e-commerce platforms, and hospitality chains strengthen distribution networks and ensure wider accessibility. Premiumization remains a key strategy, with brands introducing artisanal and limited-edition variants to attract younger demographics and health-conscious consumers. Regional players emphasize localized flavors and cost-effective offerings to secure market presence in emerging economies. Sustainability initiatives, including recyclable packaging and eco-friendly production methods, further enhance competitiveness and align with rising consumer demand for responsible brands. Marketing campaigns highlighting health benefits, lifestyle appeal, and social inclusivity strengthen brand positioning. Intense rivalry encourages continuous product innovation, while rising competition from startups and craft brewers introduces new dynamics to the global marketplace, ensuring a vibrant and fast-evolving industry landscape.
Recent Developments
- In July 2025, Anheuser-Busch InBev reported a 33% rise in revenue from its no-alcohol beer portfolio in Q2 2025, indicating strong momentum for non-alcoholic offerings in its balanced choice segment.
- In February 2025, Athletic Brewing Company formed a multi-year partnership to become the official non-alcoholic beer provider for over 100 Live Nation concert venues across the U.S., including iconic locations such as the Brooklyn Paramount and Shoreline Amphitheatre.
- In January 2025, Heineken N.V. launched its globally integrated "0.0 Reasons Needed" campaign during Dry January.
Report Coverage
The research report offers an in-depth analysis based on Product, Category, Material, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market growth continues strongly driven by increasing health awareness and shifting consumer habits.
- Premium and craft-style variants expand rapidly through innovation and better flavor delivery.
- On-premise offerings gain traction, with non-alcoholic beer now available on draft in more venues.
- Younger generations, especially Gen Z and millennials, drive demand for social yet sober beverage options.
- Flavored and alternative grain-based versions diversify product lines to appeal to varied tastes and dietary needs.
- Digital retail and subscription services enhance reach for non-alcoholic beer brands.
- Sustainability receives more attention, with brands using eco-conscious packaging and brewing processes.
- Functional enhancements (like added vitamins or electrolytes) create crossover products in wellness categories.
- Entry into emerging markets offers long-term growth as lifestyles modernize and retail access improves.
- Rising interest in zero-alcohol options in sports, fitness, and sober-curious communities supports broader normalization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health and Wellness Awareness Among Consumers
Increasing health consciousness and the desire for low-calorie, alcohol-free alternatives are driving consumers to choose non-alcoholic beer. This trend is particularly strong among younger demographics and athletes who seek hydration and recovery benefits without alcohol-related risks.
Rising Acceptance of Non-Alcoholic Beverages in Social Occasions
Non-alcoholic beer is gaining popularity in social and professional settings, as consumers look for ways to participate in social drinking culture without consuming alcohol. Restaurants, bars, and event venues are expanding their alcohol-free offerings, further boosting market growth.
Innovation in Brewing Technologies and Product Varieties
Advancements in brewing and de-alcoholization techniques have improved the taste and authenticity of non-alcoholic beers, making them more appealing to traditional beer drinkers. Breweries are also introducing a wider range of premium, craft-style, and flavored variants to cater to evolving consumer preferences.
Government Support and Regulatory Encouragement for Low-Alcohol Products
Favorable government policies and public health campaigns promoting reduced alcohol consumption are encouraging the adoption of non-alcoholic beer. Tax incentives and responsible consumption initiatives are making these products more accessible and visible in mainstream markets.
Expansion of Premium and Craft-Style Non-Alcoholic Beers
The market is seeing strong momentum in premium and craft-inspired non-alcoholic beers, with breweries focusing on quality ingredients and unique flavors. This premiumization trend is attracting younger consumers and differentiating brands in a competitive landscape.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Non-Alcoholic Beer, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Non-Alcoholic Beer Market projected to grow between 2025 and 2032?
Which Non-Alcoholic Beer Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Non-Alcoholic Beer Market?
Who are the leading companies in the Non-Alcoholic Beer Market?
Which region commanded the largest share of the Non-Alcoholic Beer Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Alcohol-free
- 1.2.2 Low Alcohol
- 1.3 By Category
- 1.3.1 Plain
- 1.3.2 Flavored
- 1.4 By Material
- 1.4.1 Malted Grains
- 1.4.2 Hops
- 1.4.3 Yeasts
- 1.4.4 Enzymes
- 1.5 By Sales Channel
- 1.5.1 Convenience Stores
- 1.5.2 Liquor Stores
- 1.5.3 Supermarkets
- 1.5.4 Restaurants & Bars
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19 billion → 2032: USD 34.4 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Non-Alcoholic Beer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Non-Alcoholic Beer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Non-Alcoholic Beer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Non-Alcoholic Beer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Non-Alcoholic Beer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Non-Alcoholic Beer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Non-Alcoholic Beer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Non-Alcoholic Beer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19 billion → 2032: USD 34.4 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Non-Alcoholic Beer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alcohol-free
- 12.3.7.2 Low Alcohol
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Category - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plain
- 12.4.7.2 Flavored
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Malted Grains
- 12.5.7.2 Hops
- 12.5.7.3 Yeasts
- 12.5.7.4 Enzymes
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Convenience Stores
- 12.6.7.2 Liquor Stores
- 12.6.7.3 Supermarkets
- 12.6.7.4 Restaurants & Bars
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Non-Alcoholic Beer Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Non-Alcoholic Beer Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Non-Alcoholic Beer Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Heineken N.V.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Anheuser-Busch InBev
- 17.4 Carlsberg A/S
- 17.5 Athletic Brewing Company
- 17.6 Radeberger Gruppe
- 17.7 Bundaberg Brewed Drinks
- 17.8 Van Pur
- 17.9 Feldschlosschen Getranke AG
- 17.10 Moscow Brewing Company
- 17.11 Volfas Engelman
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

