
Industrial lead-acid work still funds most rebuild shops
The global battery rebuild service market was valued at USD 4.11 billion in 2025 and is projected to increase from USD 4.36 billion in 2026 to USD 7.39 billion by 2035, registering a CAGR of 6.05% during 2026–2035. Demand comes from fleet owners, warehouses, telecom operators and drivers who restore a failing pack instead of paying for a new one, and from carmakers that repair batteries to cut warranty cost. North America held the largest regional share, 36.0% in 2025, because its large hybrid parc and forklift fleets support many independent rebuild shops. Asia Pacific is the fastest-growing region at 6.9% a year, as China's electric car parc ages and cell makers open their own repair centers. The main commercial change is the move from whole-pack replacement to cell and module repair, which turns a former scrap decision into a repair order for service providers that hold diagnostic data and certified high-voltage staff.
Repair orders now come from EV packs as well as forklifts
The market counts the value of services that restore used batteries to working capacity, including lead-acid cell replacement and reconditioning, lithium-ion and nickel-metal hydride module replacement and repacking, capacity testing, balancing and the related handling of failed cells. Buyers pay per job or per pack, and fleet operators often contract the work under maintenance agreements that cover inspection, repair and pick-up of failed units.
New replacement batteries, materials recycling for metal recovery and second-life energy storage products are excluded, although many rebuild shops sell all three. Value sits with service providers that own diagnostic equipment, high-voltage workshops and access to spare cells and modules, while cell makers and vehicle makers control much of the pack data and the supply of original parts.
Battery Rebuild Service Market Insights
- The global battery rebuild service market was valued at USD 4.11 billion in 2025 and is projected to reach USD 7.39 billion by 2035, growing at a 6.05% CAGR during 2026–2035.
- North America held 36.0% of 2025 value, supported by a large hybrid parc and by forklift and telecom fleets that recondition lead-acid batteries.
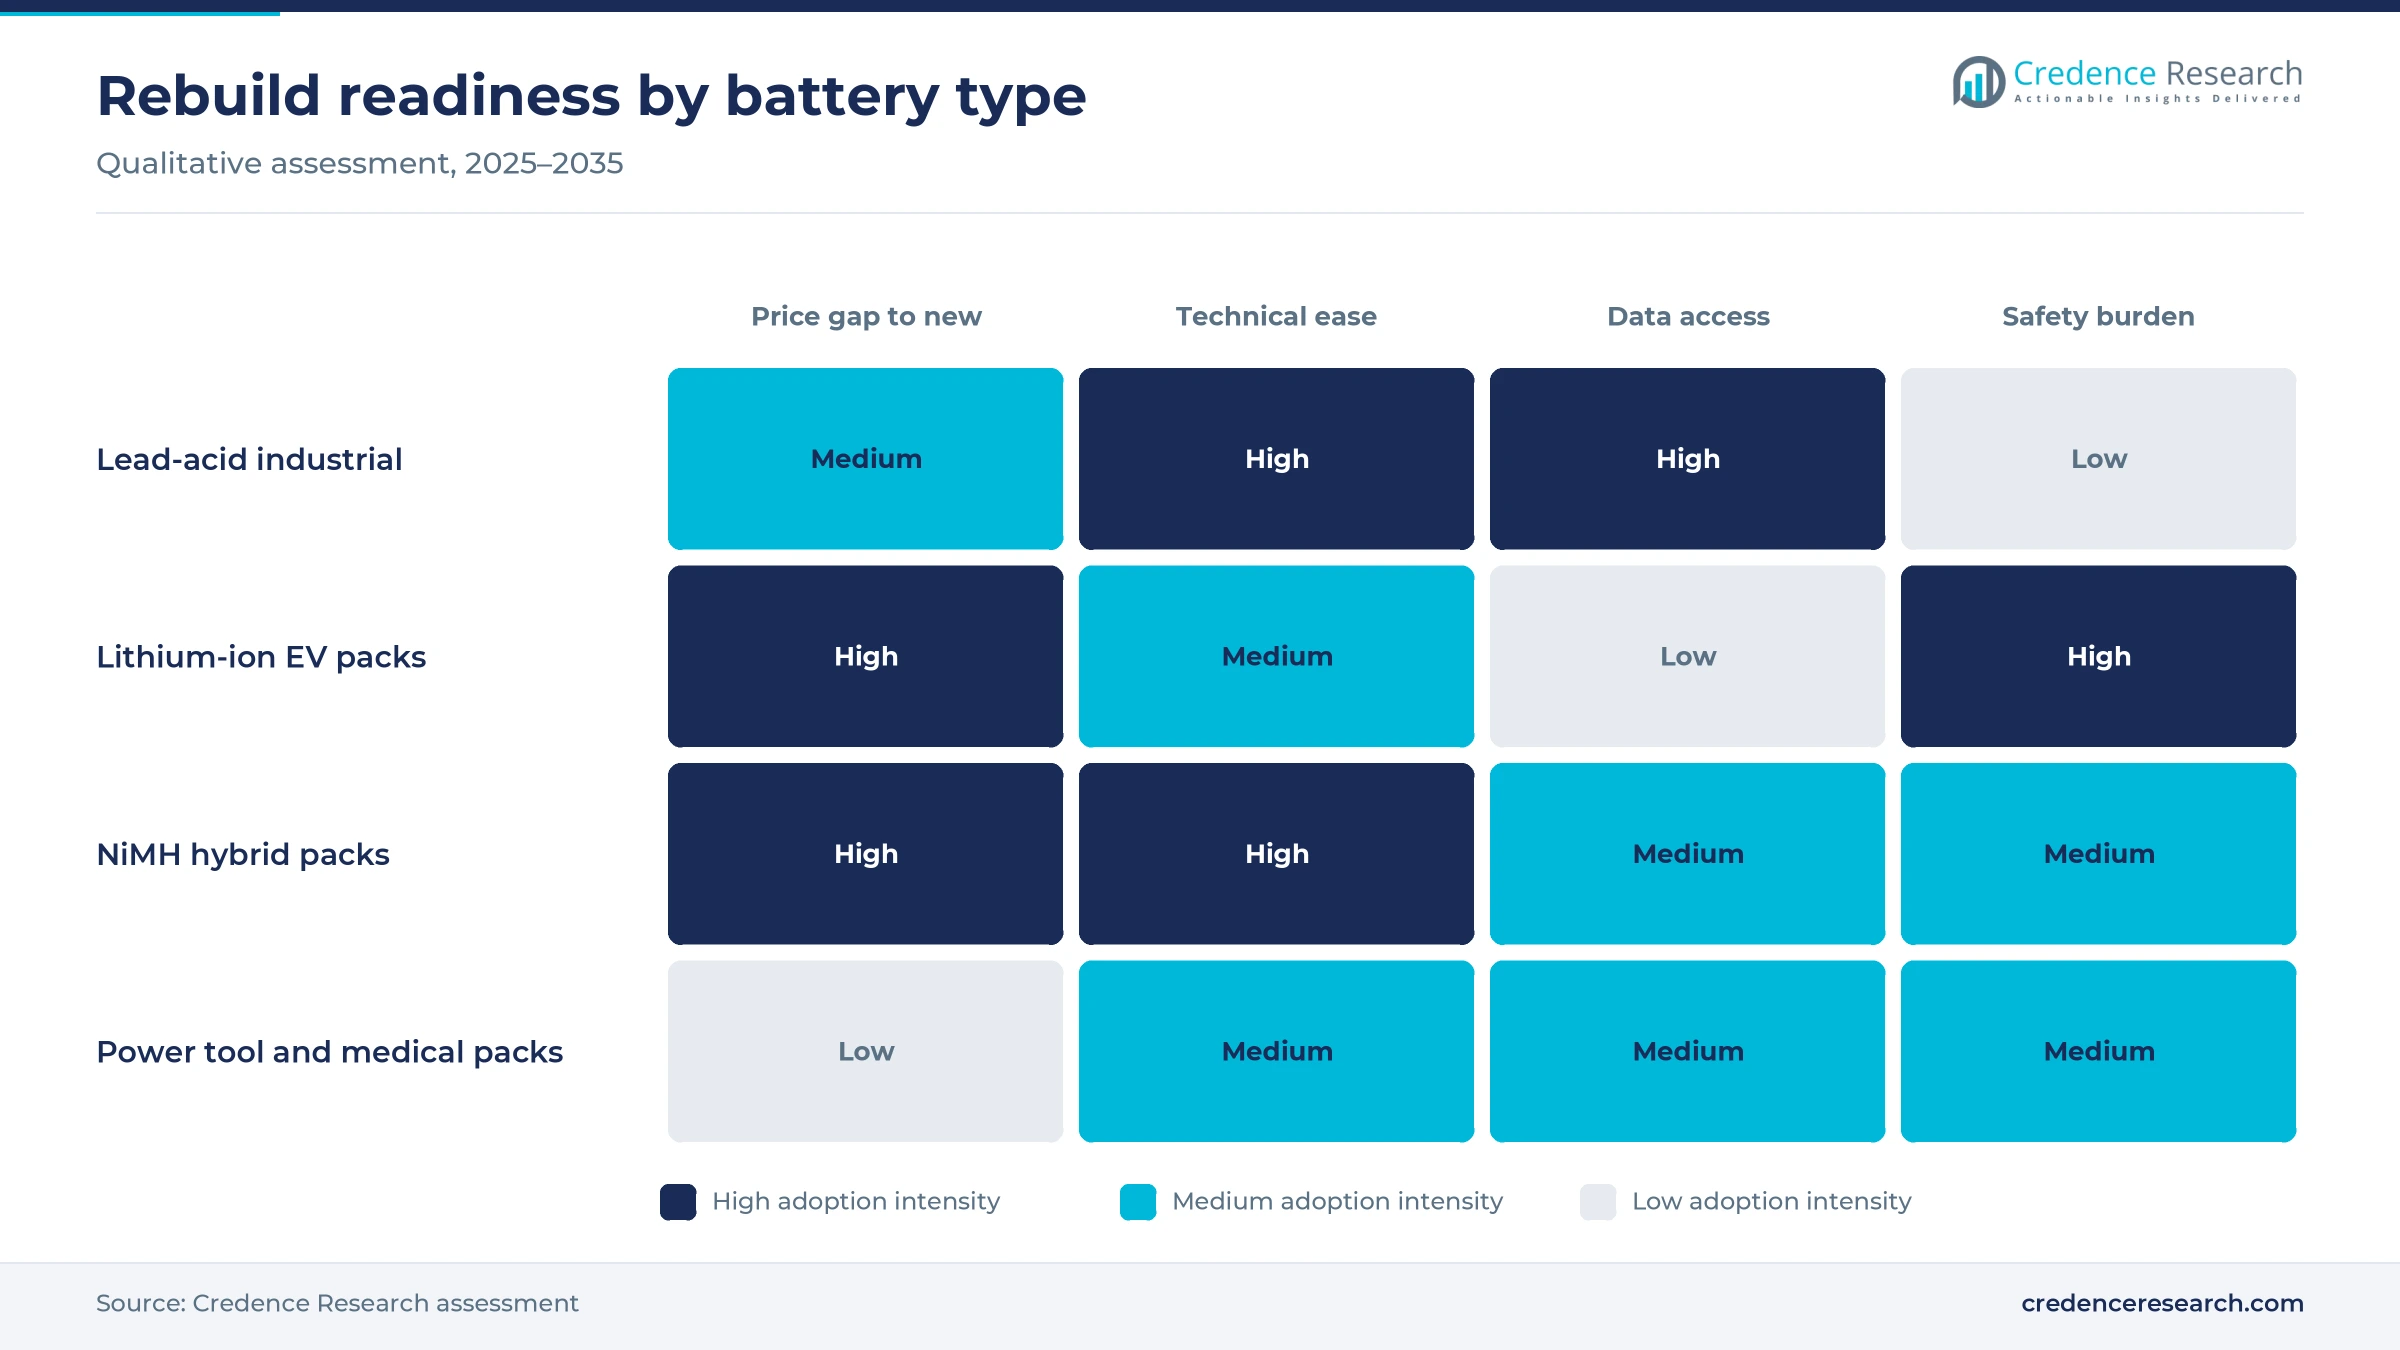
- Lead-acid batteries held 46.0% of 2025 value, because flooded industrial cells can be opened, replaced and refilled at a fraction of new cost.
- CATL said on Aug. 14, 2026 that it plans to extend its battery repair network to 100 cities and cut typical repair costs tenfold.
- Renault Group reconditioned about 3,000 electric and hybrid vehicle batteries at its Flins repair center in 2025, showing that carmakers now treat pack repair as routine service work.
Lead-acid leads value while lithium-ion packs grow fastest
Lead-acid holds the base as lithium-ion repair scales
Based on battery type, the market is categorized into lead-acid, lithium-ion, nickel-based (NiMH and NiCd) and other batteries. Lead-acid batteries led with 46.0% of 2025 value because flooded industrial cells in forklift trucks and standby systems can be opened and replaced cell by cell, and Sunlight Group advises service checks every three to six months for such batteries. Lithium-ion packs grow fastest at 7.7% a year as module repair becomes routine, with Autocraft EV Solutions designing a containerized center that remanufactures up to 2,000 EV packs a year.
Reconditioning leads while module replacement gains
Based on service type, the market is categorized into rebuild and reconditioning, repacking and module replacement, testing and diagnostics, and other services. Rebuild and Reconditioning led with 44.0% of 2025 value because low-cost lead-acid reconditioning reaches many small buyers, and Tesla Power India reported more than 500 ReStore refurbishing centers in operation in January 2024. Repacking and Module Replacement grows fastest at 7.2% a year as remarketers repair EV packs before resale, and BCA opened a Doncaster center in August 2026 that handles module replacement, cell balancing and insulation testing for all makes.
Industrial fleets lead and automotive work grows fastest
Based on end user, the market is categorized into industrial, automotive, consumer electronics and power tools, healthcare and other users. Industrial users led with 38.0% of 2025 value because forklift, telecom and backup battery fleets are large, and owners also rebuild packs for power tools and medical carts only in smaller lots. Automotive demand grows fastest at 7.0% a year, as bus makers add reconditioning to service contracts, and Daimler Buses began offering reworked NMC1 packs for its eCitaro in October 2025.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Battery Type | Lead-acid | 46.0% | Lithium-ion | 7.7% |
| By Service Type | Rebuild and Reconditioning | 44.0% | Repacking and Module Replacement | 7.2% |
| By End User | Industrial | 38.0% | Automotive | 7.0% |
Rebuilt packs sell at a fraction of new replacement prices
Rebuild pricing is set against the price of a new battery, because buyers compare the repair quote with a new pack and with the remaining life of the vehicle or machine. Independent hybrid shops list remanufactured Prius packs near USD 1,000, while GreenTec Auto says full hybrid battery replacement can cost from a few thousand dollars to more than USD 10,000. Shorter warranties on rebuilt units, often 12 months, keep that discount wide. Falling new-cell prices narrow the gap, so margins hold best on jobs where labor, diagnostics and pick-up logistics, rather than cells, make up most of the bill.
| Job or battery | Typical price or fee | Basis |
|---|---|---|
| Remanufactured hybrid pack, Toyota Prius 2004–2015 | USD 999 list price, 12-month warranty | GreenTec Auto list prices, 2026 |
| New lead-acid forklift battery, standard sizes | USD 2,950 to USD 5,000 | Forkliftaction guide sponsored by ROYPOW, May 2026 |
| Reconditioned forklift battery | Often 50% or more below new | Forkliftaction guide sponsored by ROYPOW, May 2026 |
| Refurbished lead-acid inverter battery, India | About 50% of a new battery's price | Tesla Power India, January 2024 |
| EV pack cell-level repair, China target | About CNY 10,000 versus CNY 100,000 before | CATL target reported by CarNewsChina, August 2026 |
| EV pack module repair, Europe and North America | USD 1,500 to USD 4,000 per job | Credence Research estimate; repair networks do not publish job prices |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Aging EV and hybrid fleets pull packs into repair lines
A larger EV parc leaves more packs outside warranty
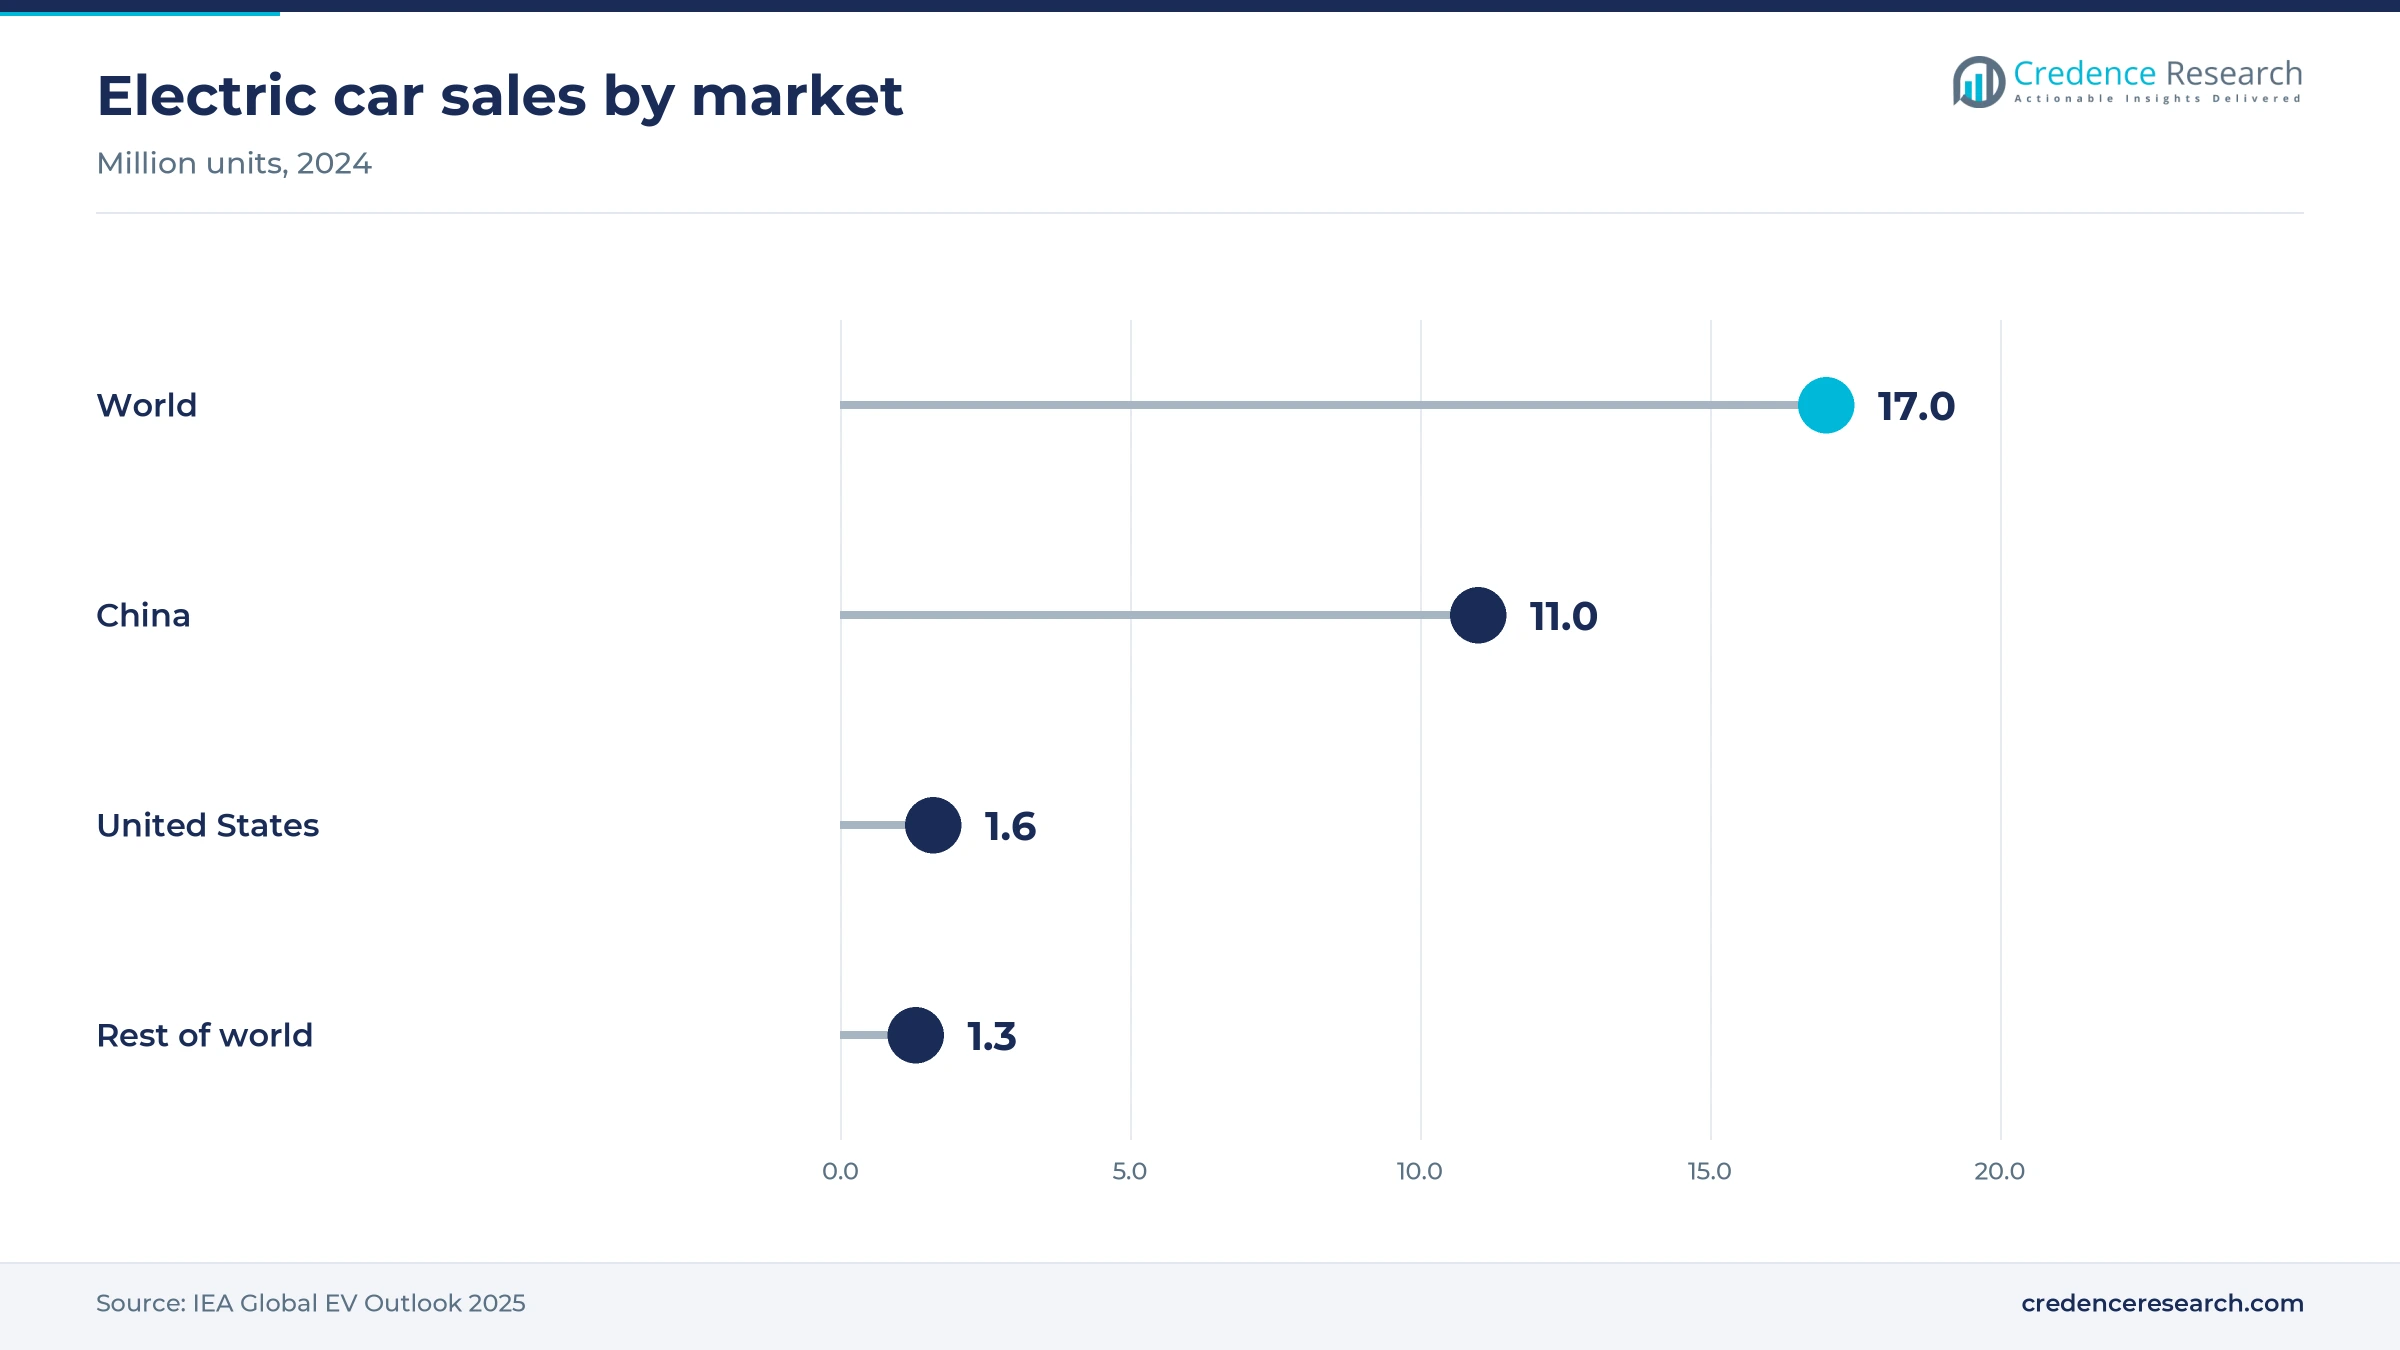
Growth in the electric car parc is the main new source of rebuild orders, because every pack that leaves its warranty becomes a repair-or-replace decision for its owner. Electric car sales topped 17 million in 2024, according to the IEA Global EV Outlook 2025, and China alone sold more than 11 million. The IEA also counts almost 58 million electric cars on the road at the end of 2024, a growing share of which will move outside original pack warranties during the forecast period. Asia Pacific grows fastest because that Chinese parc is now aging. Service providers with high-voltage workshops near large EV fleets gain first, while owners of early packs face the highest quotes for new replacements.
Carmakers repair packs to cut warranty and parts cost
Vehicle makers now repair batteries themselves, because a module swap costs far less than a new pack under warranty and lets them resell restored packs as service parts. Renault Group reconditioned about 3,000 electric and hybrid vehicle batteries at its Flins repair center in 2025, according to the company. Stellantis said in September 2026 that its SUSTAINera remanufactured high-voltage packs carry the same warranty as original Mopar parts and use up to 80% fewer raw materials than new units. Cox Automotive opened an EV battery center in Conyers, Georgia, that can handle about 9,000 packs at full capacity. Independent shops gain volume as subcontractors but lose pricing power where carmakers keep the work.
High replacement prices keep hybrid owners repairing
The price of a new pack keeps owners of aging hybrid electric vehicles in the rebuild channel, because many of these cars are worth less than a dealer battery. GreenTec Auto, which started in the Sacramento area in 2009, now runs more than 20 shops in the United States and offers mobile installation by hybrid-trained technicians. The company says a full hybrid battery replacement can cost more than USD 10,000, while it lists remanufactured Prius packs at USD 999. Dorman Products sells remanufactured hybrid drive battery packs under its OE FIX line through parts retailers, which brings rebuilt packs to general repair garages. Parts channels gain the volume, while dealers lose replacement sales on cars older than ten years.
EU battery rules make pack data available to repairers
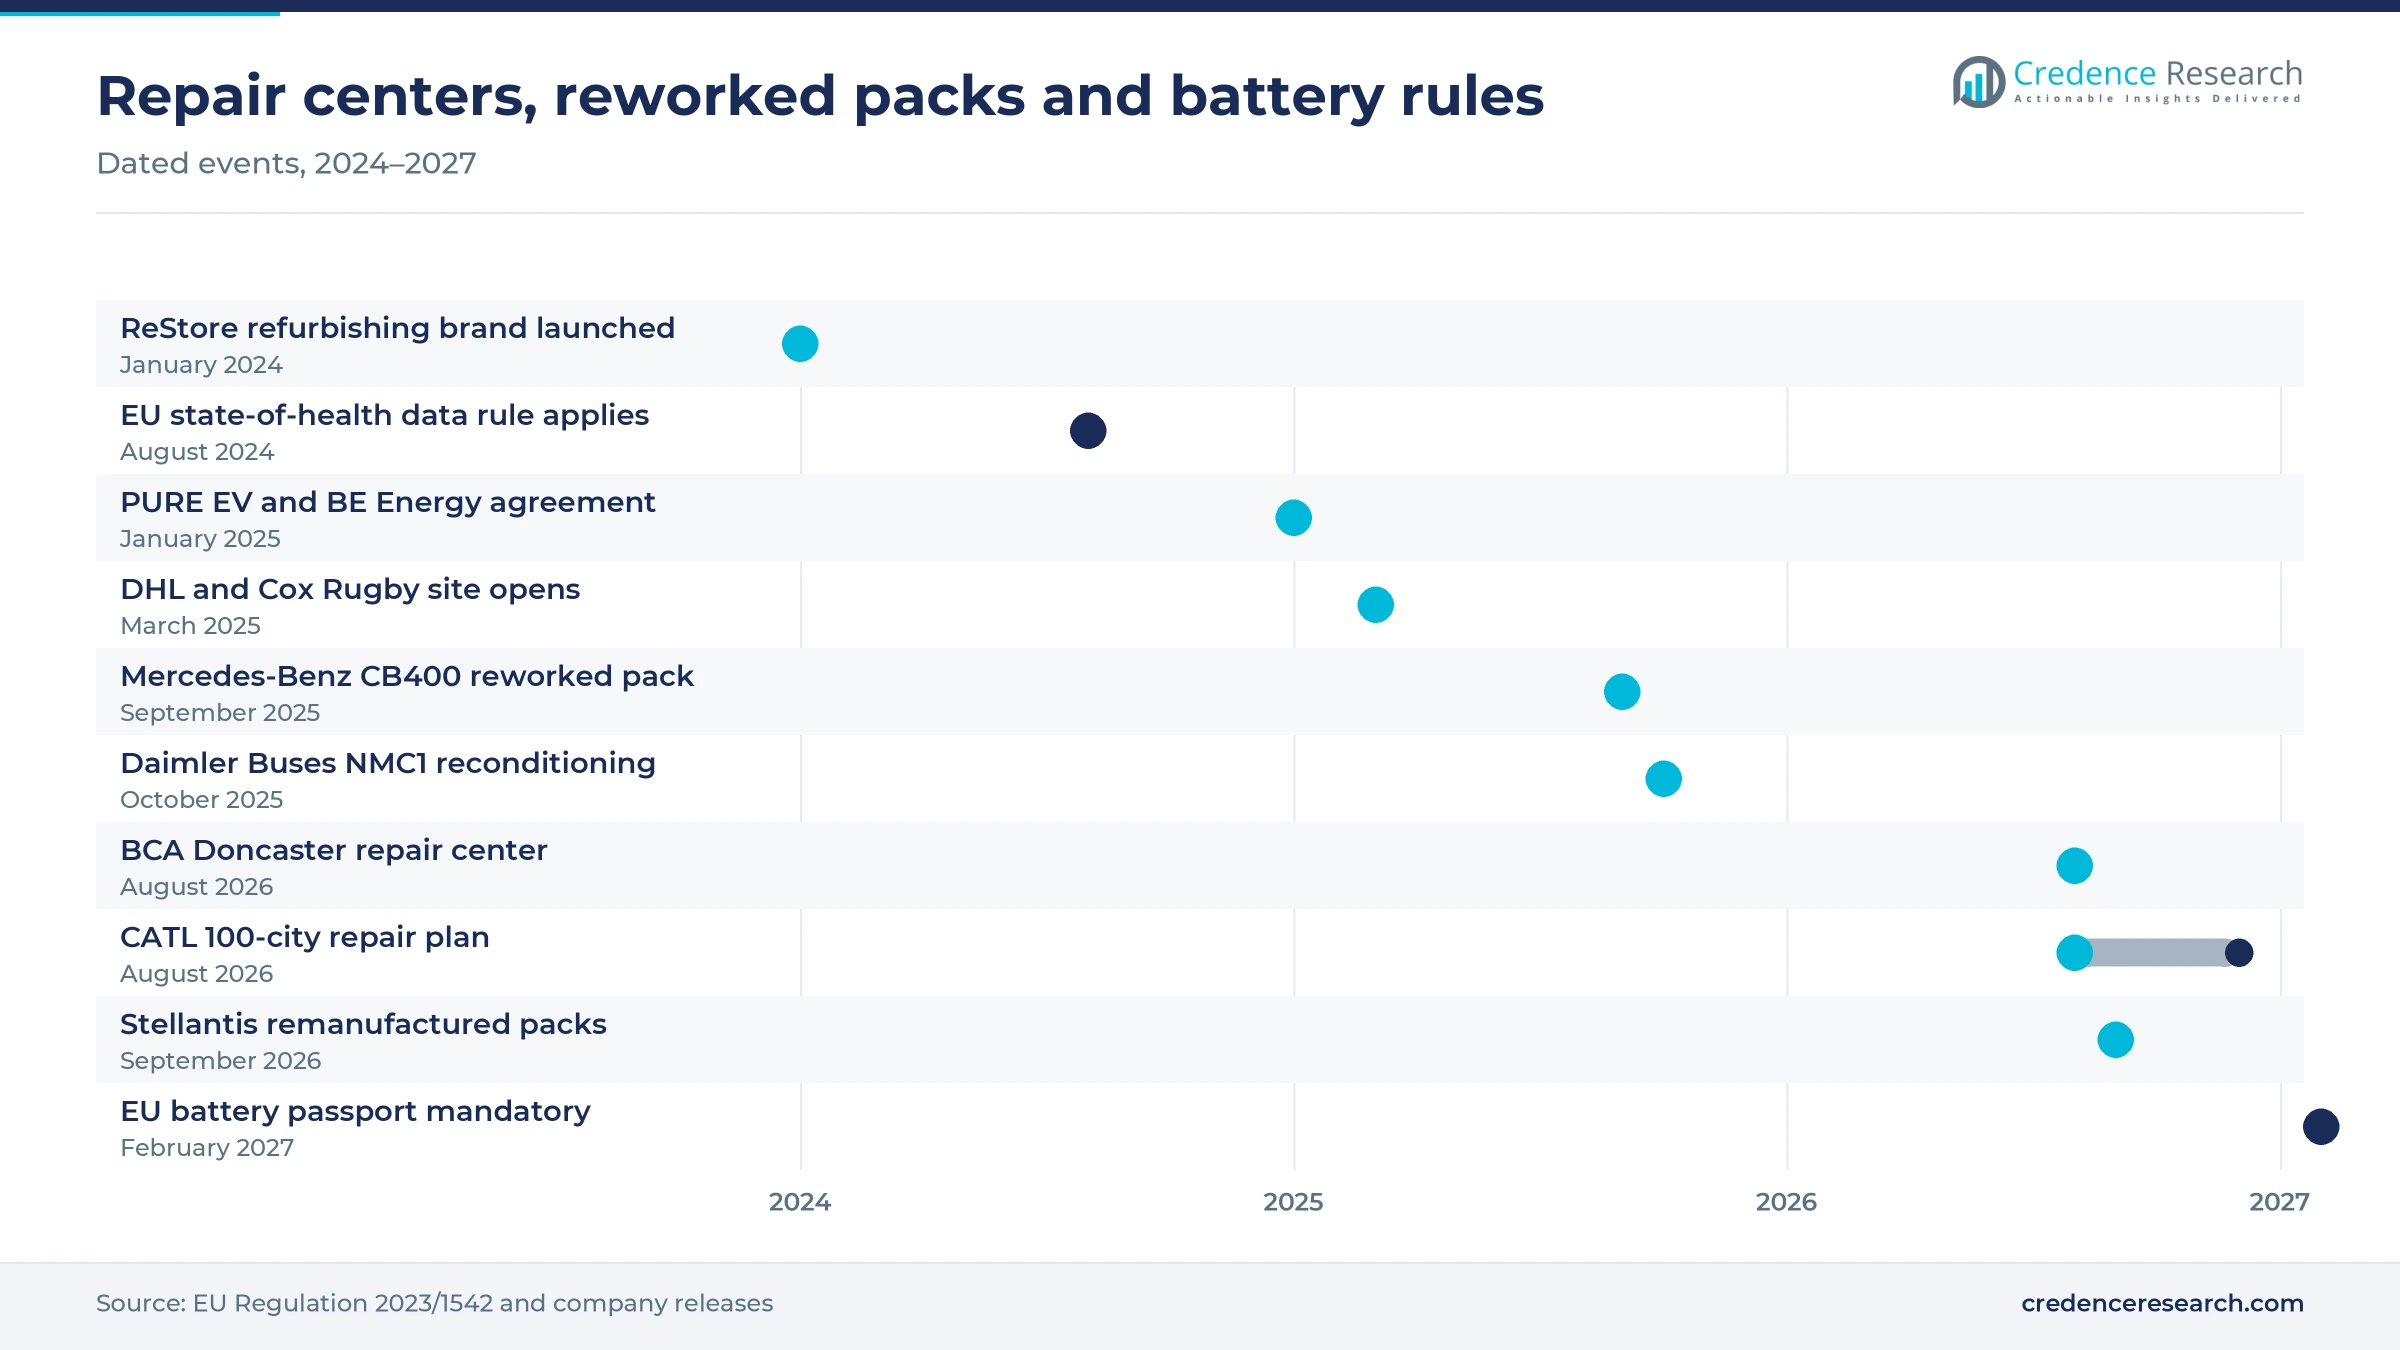
European law is opening the pack data and the legal role that rebuilders need, which lowers their cost of diagnosis. Regulation (EU) 2023/1542 has required battery management systems of EV, light-vehicle and stationary batteries to hold up-to-date state-of-health data since Aug. 18, 2024, under Article 14 of the regulation. The same regulation sets obligations from that date for operators that prepare batteries for re-use or remanufacturing. A digital battery passport becomes mandatory on Feb. 18, 2027 for EV batteries, light-vehicle batteries and industrial batteries above 2 kWh. Certified independents in Europe therefore gain the clearest legal access to pack data of any region.
Cell makers and carmakers are building repair networks
Cell makers are moving into after-sales repair
Battery manufacturers are shifting toward direct after-sales repair to keep control of their packs, creating openings for cell-level work across passenger cars and commercial fleets. CATL said on Aug. 14, 2026 that it plans to extend its Ning Service repair network to 100 cities worldwide, and it already runs eight centers in China plus sites in Norway and Istanbul. The network lists 1,376 franchised service centers in 84 countries, and its coverage of NEV models sold in China rose from 47% to 76.8%. CATL also targets repair times of 72 hours or less. Independent shops that cannot buy original cells face direct competition from the cell maker, which can price repairs as a warranty tool.
Truck and bus makers sell reworked packs as service parts
Commercial vehicle makers are shifting toward factory-reworked packs to keep electric fleets running beyond the first battery life, creating openings for module-level rework across trucks and buses. Mercedes-Benz Trucks launched its CB400 reworked battery for first-generation eActros and eEconic trucks in September 2025, reworking collected packs at its Mannheim center with module replacement and leak tests. The reworked unit carries the same parts warranty as a new one and cuts carbon emissions by about 33%. Daimler Buses plans to extend reconditioning from NMC1 to NMC2 and NMC3 packs across more than 120 European service centers, with NMC4 replacement packs carrying warranties of up to 12 years from 2026. Fleet operators gain lower replacement cost, while third-party shops lose this work to the OEM.
India and other markets open low-cost refurbishing
Price-sensitive markets offer an opening for low-cost refurbishing of inverter, UPS and two-wheeler batteries, where buyers cannot afford new packs and grid backup is common. Tesla Power India launched its ReStore brand in January 2024, saying refurbished inverter and UPS batteries sell for about 50% of the price of new ones and gain one to two years of life. The company reported more than 500 centers in operation and had planned 5,000 refurbishing centers across India by 2025. PURE EV and France's BE Energy agreed in January 2025 to bring lithium-ion reconditioning to India, with a first facility planned in Hyderabad during fiscal 2026. Equipment suppliers and franchise operators gain the most from this demand.
Graded packs can feed stationary storage after repair
Repair lines that test and grade every pack can sell units unfit for vehicles into stationary storage, which opens a second revenue stream for the same diagnostic work. Renault Group already uses more than 500 retired batteries at Flins to provide about 15 MWh of storage. Daimler Buses offers former bus batteries for grid peak loads and as buffer storage at solar and wind farms. DHL and Cox Automotive set up a 35,000 sq ft battery repair and storage space in Rugby, England, in March 2025, with equipment to discharge packs into site storage. Service providers that grade at intake capture both repair and storage buyers.
Fire risk, skills gaps and cheaper new packs cap volumes
Lithium-ion fire risk raises handling and insurance cost
Damaged lithium-ion packs raise fire risk at every step from pick-up to storage, which raises insurance, building and transport cost for rebuild shops. The U.S. EPA counted 245 lithium-ion battery fires at 64 waste and recycling facilities between 2013 and 2020, with the annual count rising to 65 fires at 16 facilities in 2020, a tally the EPA says is incomplete. Small independent shops are most exposed, because they lack fire-rated storage and certified transport, and larger networks can spread these costs over more packs.
Too few technicians are certified for high-voltage packs
High-voltage pack repair needs certified technicians, and the shortage limits how many jobs a workshop can accept. The Institute of the Motor Industry counted 66,788 EV-qualified technicians in the United Kingdom after the first quarter of 2025, about 28% of the workforce, and it projects a shortfall of 25,435 technicians by 2035. Independent garages without trained staff lose EV jobs to dealer and OEM centers, which can train in-house.
Cheaper new packs narrow the rebuild price advantage
Falling new-pack prices reduce the discount that makes a rebuild worth buying, especially for older lithium-ion packs. Battery pack prices fell by about 30% in China in 2024 and by about 10% to 15% in Europe and the United States, according to the IEA. Rebuilders of low-value packs in China face the strongest pressure, because a new pack there may cost little more than a full module rebuild with labor and testing. Shops respond by focusing on cell-level jobs and fleet contracts.
Lithium forklifts shrink the lead-acid reconditioning base
The move to lithium-ion forklift batteries reduces the flooded lead-acid fleet that gives rebuild shops their steadiest work, as sealed lithium packs need less service. New LiFePO4 forklift batteries cost about USD 6,000 to more than USD 25,000, according to the same ROYPOW-sponsored Forkliftaction guide, yet warehouses still buy them to cut charging time and watering labor. Shops that only replace lead-acid cells are most exposed, since the cells they remove feed lead-acid recycling, where Battery Council International reports a 99% recycling rate.
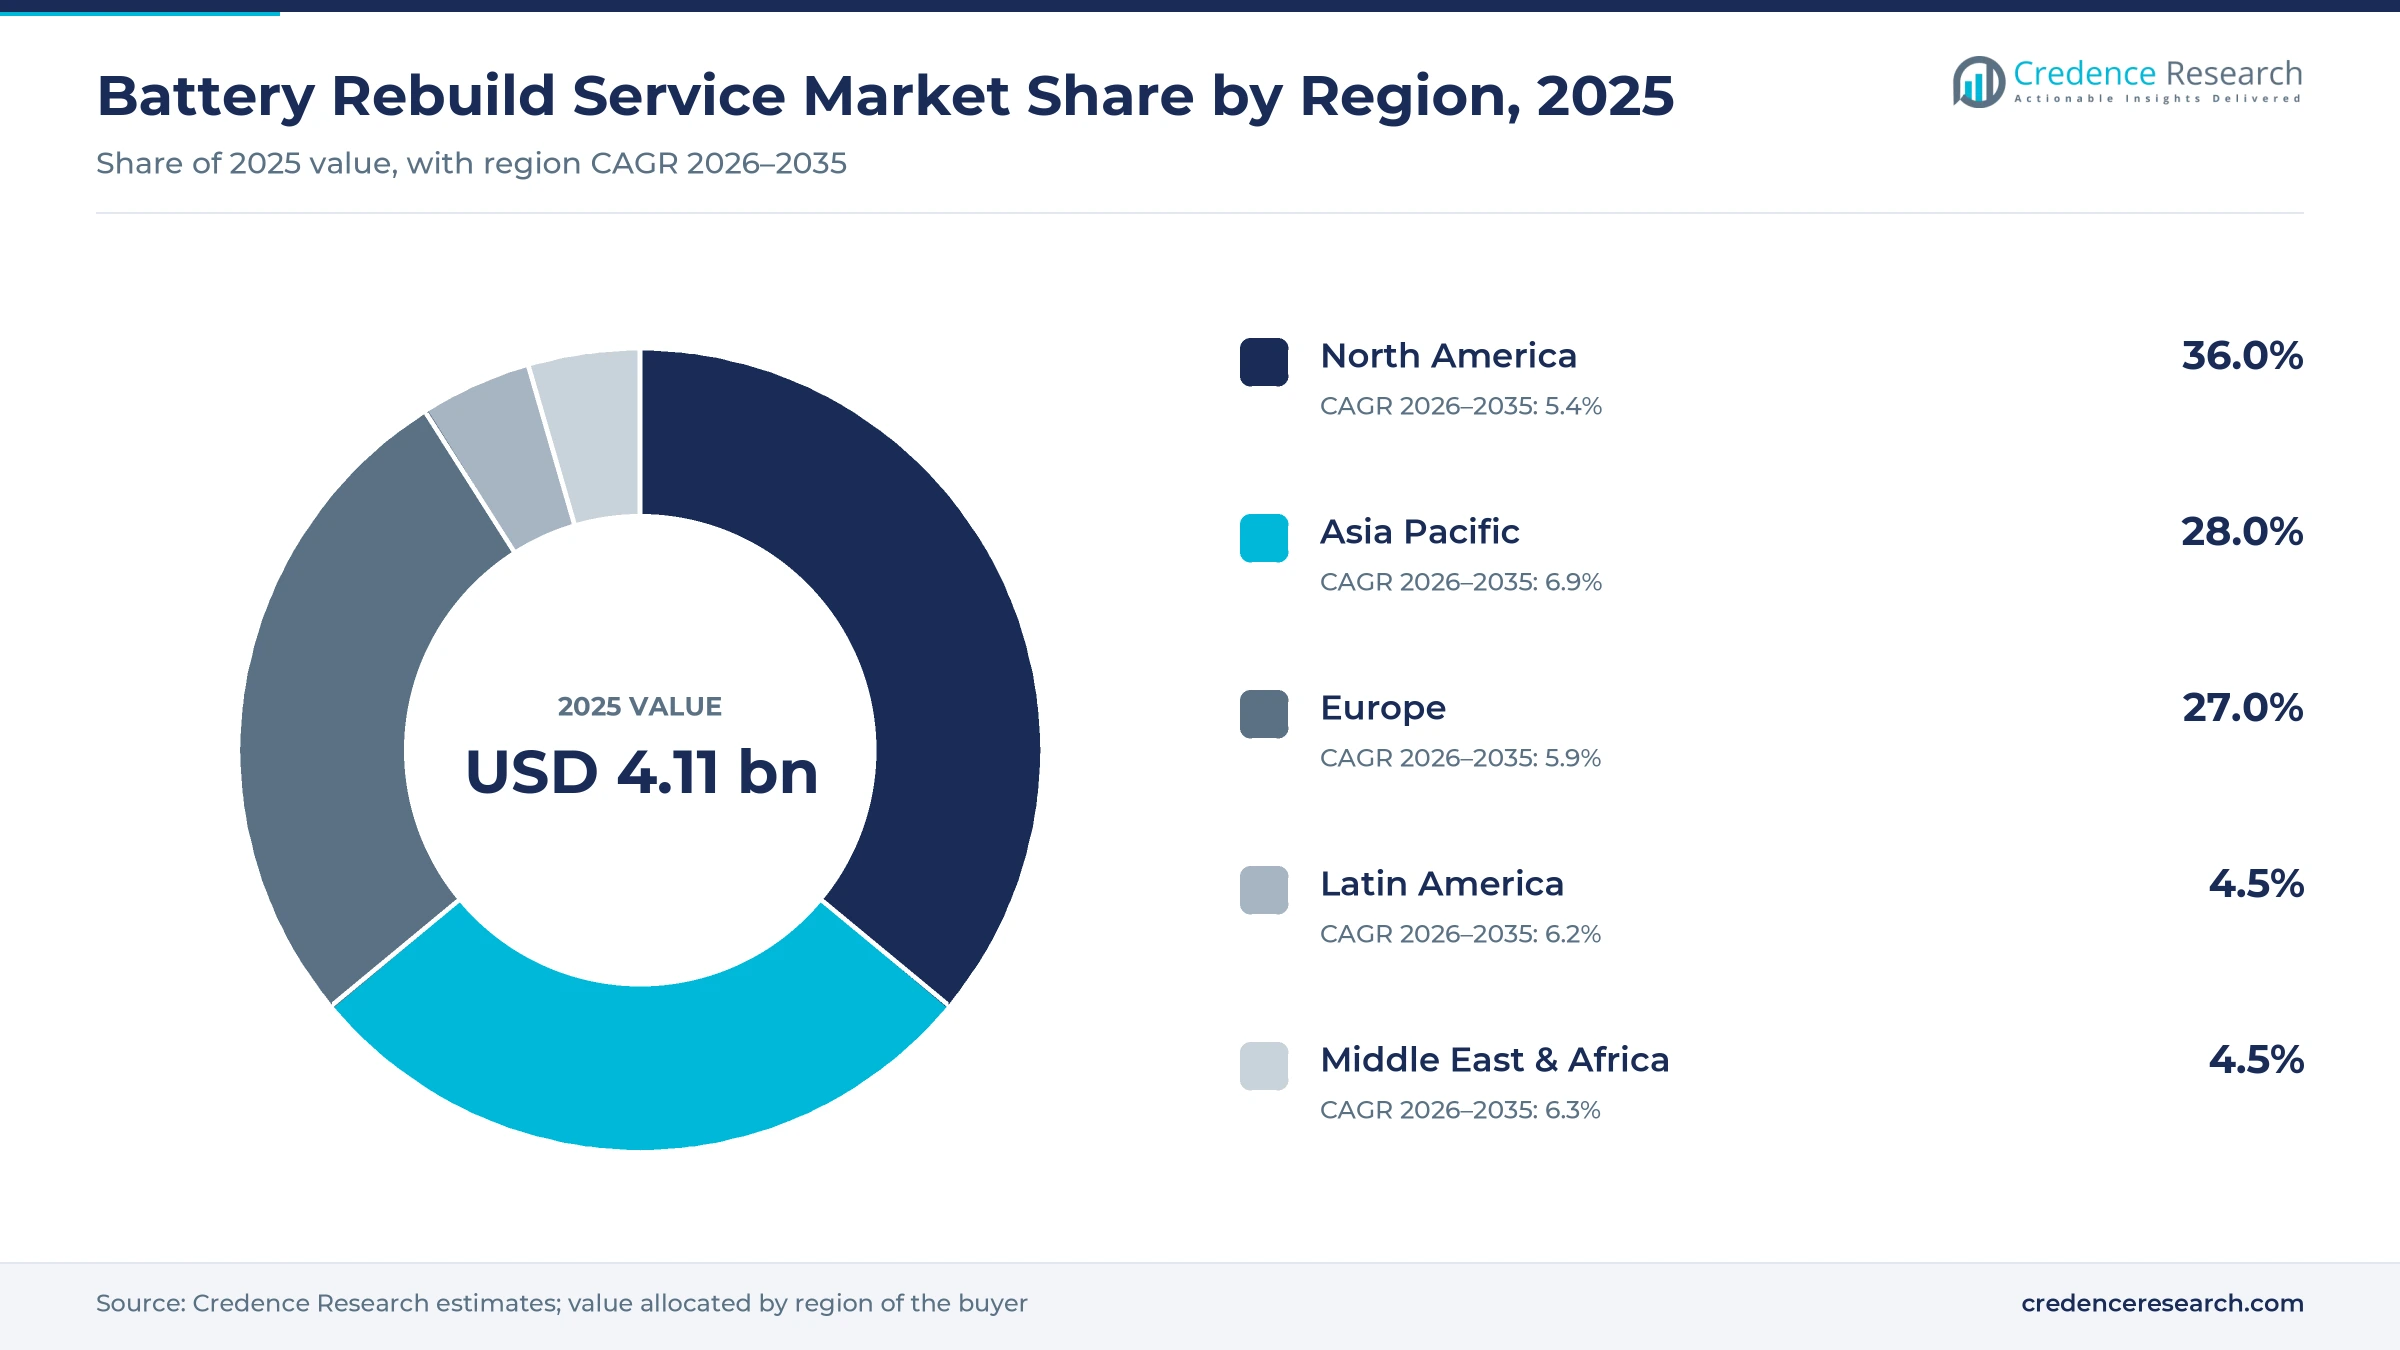
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 1.48 | 36.0% | 5.4% |
| Asia Pacific | 1.15 | 28.0% | 6.9% |
| Europe | 1.11 | 27.0% | 5.9% |
| Latin America | 0.18 | 4.5% | 6.2% |
| Middle East & Africa | 0.18 | 4.5% | 6.3% |
North America leads on hybrid parc and independent shops
North America held 36.0% of 2025 value and grows at 5.4% a year, the slowest rate among the three largest regions in the Credence Research estimates. The United States sold 1.6 million electric cars in 2024, according to the IEA, but most current rebuild jobs still come from hybrids and forklift fleets. Independent chains such as GreenTec Auto and parts suppliers such as Dorman Products serve that hybrid base, while Cox Automotive runs pack repair for dealers and fleet owners in Georgia.
Asia Pacific grows fastest as China repairs its own packs
Asia Pacific held 28.0% of 2025 value and grows at 6.9% a year, the fastest rate of any region. China accounts for most of that growth, because its electric car parc is the world's largest and CATL runs directly operated repair centers there. India adds a separate pool of lead-acid inverter and UPS refurbishing, and two-wheeler lithium-ion reconditioning is moving toward its first plant in Hyderabad. Japan and South Korea add hybrid and industrial work, though public data on their rebuild volumes are thin.
Europe grows on carmaker repair centers and EU battery law
Europe held 27.0% of 2025 value and grows at 5.9% a year, supported by carmaker repair sites and by the EU battery passport. Renault Group in France and Mercedes-Benz Trucks in Germany repair packs in-house, Stellantis sells remanufactured packs, and the United Kingdom adds DHL and Cox Automotive in Rugby and BCA in Doncaster. Most EV repair volume stays with carmakers and their partners, which leaves independent shops with older hybrids and industrial lead-acid work. Certified high-voltage staff remain the main constraint on repair capacity across the region.
Latin America relies on lead-acid and fleet battery work
Latin America held 4.5% of 2025 value and grows at 6.2% a year, with demand concentrated in automotive starter, forklift and telecom backup batteries rather than electric car packs. Mexico and Brazil host most of the region's industrial fleets, so their warehouses and telecom towers generate most reconditioning work. Published data on rebuild volumes, prices or service networks in the region are scarce, and these shares are Credence Research estimates built from fleet size rather than from reported service revenue.
Middle East & Africa gains early cell maker service sites
Middle East & Africa held 4.5% of 2025 value and grows at 6.3% a year, with most work tied to telecom, solar backup and generator batteries in hot climates that shorten battery life. CATL opened a service experience center in Riyadh in 2025, which gives Gulf fleet buyers a first original-maker repair contact. Electric car parcs in the region remain small, so lead-acid reconditioning is expected to stay the largest job type through the early forecast years.
Repair centers and reworked packs mark 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In September 2026, Stellantis began offering SUSTAINera remanufactured high-voltage packs for many of its electric and plug-in hybrid models. | Commercial launch; restored packs carry the same warranty as original Mopar parts and compete with independent rebuilds |
| In August 2026, CATL announced plans to extend its Ning Service repair network to 100 cities worldwide in the second half of 2026. | Plan announced; eight directly run centers in China and two abroad were operating at the time |
| In August 2026, BCA opened an EV and hybrid battery repair center at its Doncaster site for vehicles leaving manufacturer warranty. | Operational launch; the site performs module repair, cell balancing and insulation testing before remarketing |
| In September 2025, Mercedes-Benz Trucks launched the CB400 reworked battery for first-generation eActros and eEconic trucks. | Product launch; packs are reworked in Mannheim and carry the same parts warranty as new units |
| In March 2025, DHL and Cox Automotive opened a 35,000 sq ft EV battery repair, remanufacturing logistics and storage space in Rugby, England. | Operational launch; the site can handle thousands of EV batteries each year |
Diagnostics and module work decide what can be saved
- State-of-health diagnostics read cell voltages, internal resistance and battery management data to decide within hours whether a pack is worth repairing.
- Module and cell replacement swaps only the weak modules or cells, which keeps the casing, wiring and controls of an EV or hybrid pack in service.
- Cell balancing and capacity testing bring repaired cells to matched charge levels and confirm range before a pack returns to a vehicle or machine.
- Lead-acid reconditioning uses controlled charging, electrolyte correction and cell swaps to recover capacity in flooded and sealed industrial batteries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Carmakers, cell makers and independents split the work
Competition depends on who owns the pack data and the spare cells. Carmakers and cell makers compete on original parts, software access and warranty terms, as Stellantis and Mercedes-Benz Trucks do with reworked packs that carry new-part warranties. Cox Automotive and BCA compete on intake capacity and remarketing links, which give them steady flows of out-of-warranty vehicles. EnerSys and Sunlight Group sell repair, rebuild and maintenance work to forklift and backup battery fleets, while GreenTec Auto and Dorman Products compete on hybrid pack price and fast installation. In India, franchise networks such as Tesla Power India compete on price for inverter batteries. Independent providers win where they offer faster turnaround and lower labor cost, but they lose ground wherever carmakers restrict diagnostic data.
Who controls pack repair, and where margins sit
The supply side splits into three tiers with different access to parts. Carmakers and cell makers such as Renault Group, Stellantis, Mercedes-Benz Trucks and CATL hold original parts, pack software and warranty claims, so they keep most lithium-ion repair inside their own networks. Logistics and remarketing groups such as Cox Automotive, DHL and BCA run large intake and repair sites for dealers, fleets and auctions. Many independent shops, from hybrid chains to forklift battery servicers, work on lead-acid and older hybrid packs. Barriers are access to cells and diagnostic data, high-voltage certification and fire-safe storage, and margins sit highest in diagnostics and fleet contracts.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Cox Automotive | EV battery services network | Diagnoses, repairs and remanufactures EV packs at U.S. and U.K. centers |
| Contemporary Amperex Technology Co. Limited (CATL) | Cell maker with repair network | Repairs NEV packs at cell level through its Ning Service centers |
| Renault Group (The Future Is NEUTRAL) | Carmaker repair center | Reconditions electric and hybrid packs at its Flins repair center |
| Stellantis (SUSTAINera) | Carmaker remanufacturing unit | Sells remanufactured high-voltage packs for electric and plug-in hybrid models |
| Daimler Truck (Mercedes-Benz Trucks, Daimler Buses) | Truck and bus maker | Reworks truck and bus packs with module replacement and leak tests |
| EnerSys | Industrial battery maker and servicer | Repairs and maintains motive power and standby batteries for fleets |
| Sunlight Group | Industrial battery maker and servicer | Rebuilds, reconditions and repairs lead-acid and lithium forklift batteries |
| GreenTec Auto | Hybrid pack specialist | Sells and installs remanufactured hybrid packs through over 20 U.S. shops |
| Dorman Products | Aftermarket parts supplier | Supplies OE FIX remanufactured hybrid drive battery packs through parts retailers |
| BCA (Constellation Automotive Group) | Remarketing and repair | Repairs EV and hybrid packs at Doncaster before vehicle resale |
| Tesla Power India | Refurbishing franchise network | Refurbishes lead-acid inverter and UPS batteries through ReStore centers in India |
Pack repair at module level is where value is moving
Credence Research's view is that value in the Battery Rebuild Service market is moving from lead-acid reconditioning toward module-level repair of lithium-ion packs, and that carmakers and cell makers will capture much of it. The evidence is already visible in reworked packs sold with full warranties and in the repair networks of CATL and Cox Automotive. Independent providers keep a durable role in hybrids, forklifts and backup batteries, where data are open and cells are simple. Buyers should judge providers on diagnostic access, certified staff and fire-safe logistics more than on headline price.
Repair pools by battery type anchor the estimates
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which sizes separate repair pools for EV packs, hybrid packs, industrial lead-acid batteries and other packs from parc and fleet data, published list prices and service-network capacity. Regional and segment shares are Credence Research estimates built from these pools and from regional fleet data. Sources include IEA and EPA statistics, EU regulation summaries, the Institute of the Motor Industry and company releases and price lists, and no interviews or surveys are claimed for this edition.
Out-of-warranty EV packs shape demand toward 2035
The Battery Rebuild Service market is expected to grow at a steady pace to 2035, with the mix changing more than the total. Lead-acid reconditioning should keep the largest share early in the period, but out-of-warranty electric car packs will add most of the new value as the parc that sold from 2020 onward ages. Results will depend on whether pack data stay open to independents after the EU passport takes effect, on new-pack prices and on how quickly workshops train certified high-voltage staff.
Pack data access and new-pack prices set the range
The range depends on how open pack data become to independent repairers and on how fast new-pack prices keep falling. Wider data access under the EU battery passport and similar rules elsewhere would let more shops take lithium-ion jobs. Sharp further declines in new-pack prices would push owners toward replacement, while carmaker-only repair would hold volumes but lower prices paid to independent shops.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.8% | USD 6.67 billion | New-pack prices keep falling and carmakers lock pack data and spare cells |
| Base | 6.05% | USD 7.39 billion | Module repair spreads through OEM and remarketing networks at a steady pace |
| Upside | 7.3% | USD 8.25 billion | Open pack data and passport rules let certified independents repair lithium-ion packs widely |
Frequently Asked Questions
How big is the battery rebuild service market?
Which battery type leads battery rebuild services?
Can electric car batteries be repaired instead of replaced?
How much does a remanufactured hybrid battery cost?
Which region leads the battery rebuild service market?
Does the market include battery recycling and maintenance services?
What do car battery testing and repair services involve?
Who are the major companies in battery rebuild services?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Battery Type
- 1.2.1 Lead-acid
- 1.2.2 Lithium-ion
- 1.2.3 Nickel-based
- 1.2.4 Others
- 1.3 By Service Type
- 1.3.1 Rebuild and Reconditioning
- 1.3.2 Repacking and Module Replacement
- 1.3.3 Testing and Diagnostics
- 1.3.4 Others
- 1.4 By End User
- 1.4.1 Industrial
- 1.4.2 Automotive
- 1.4.3 Consumer Electronics and Power Tools
- 1.4.4 Healthcare
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.11 billion → 2035: USD 7.39 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Battery Rebuild Service Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Battery Rebuild Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Battery Rebuild Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Battery Rebuild Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Battery Rebuild Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Battery Rebuild Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Battery Rebuild Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Battery Rebuild Service Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.11 billion → 2035: USD 7.39 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Battery Rebuild Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Battery Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Lead-acid
- 12.3.6.2 Lithium-ion
- 12.3.6.3 Nickel-based
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Rebuild and Reconditioning
- 12.4.6.2 Repacking and Module Replacement
- 12.4.6.3 Testing and Diagnostics
- 12.4.6.4 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Industrial
- 12.5.6.2 Automotive
- 12.5.6.3 Consumer Electronics and Power Tools
- 12.5.6.4 Healthcare
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Battery Rebuild Service End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Battery Rebuild Service Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Battery Rebuild Service Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Battery Rebuild Service Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cox Automotive
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Contemporary Amperex Technology Co. Limited (CATL)
- 18.4 Renault Group (The Future Is NEUTRAL)
- 18.5 Stellantis (SUSTAINera)
- 18.6 Daimler Truck (Mercedes-Benz Trucks, Daimler Buses)
- 18.7 EnerSys
- 18.8 Sunlight Group
- 18.9 GreenTec Auto
- 18.10 Dorman Products
- 18.11 BCA (Constellation Automotive Group)
- 18.12 Tesla Power India
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

