
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Beauty Supply Stores Market Size 2024 | USD 526.89 million |
| Beauty Supply Stores Market, CAGR | 5.34% |
| Beauty Supply Stores Market Size 2032 | USD 823.51 million |
Market Overview
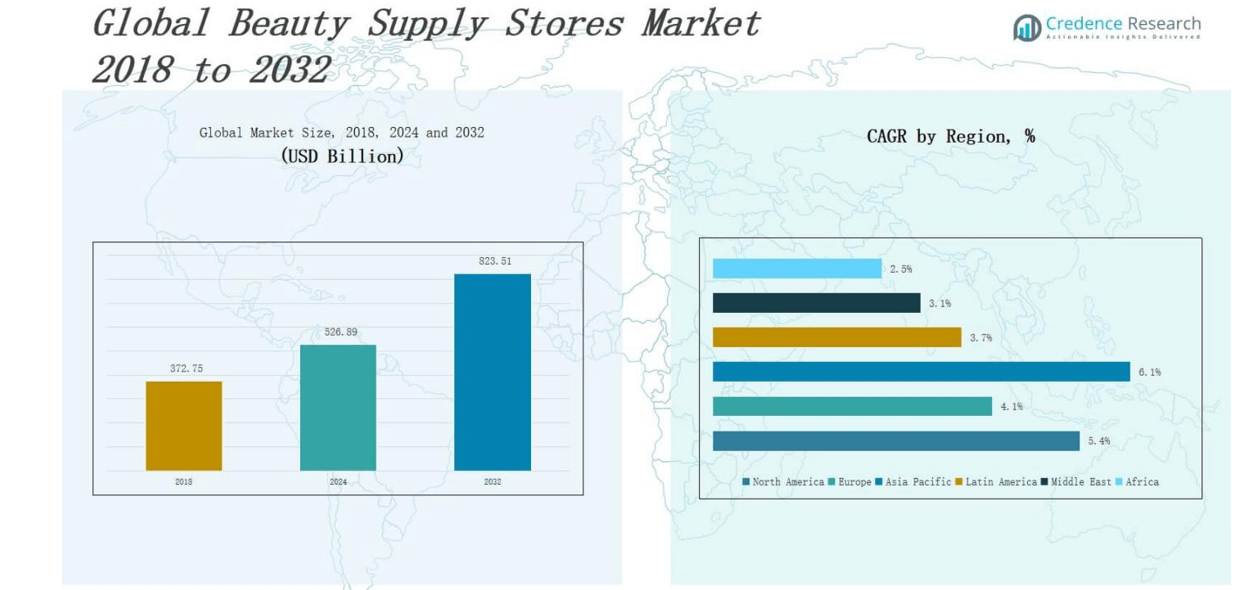
The Beauty Supply Stores Market size was valued at USD 372.75 million in 2018 to USD 526.89 million in 2024 and is anticipated to reach USD 823.51 million by 2032, at a CAGR of 5.34% during the forecast period.
The Beauty Supply Stores Market is experiencing steady growth driven by rising consumer demand for personal grooming, skincare, and haircare products across diverse demographics. The increasing emphasis on self-care, wellness, and aesthetic enhancement-especially among millennials and Gen Z-is fueling sales of premium and natural beauty products. Social media influence, beauty tutorials, and endorsements from influencers are further amplifying product visibility and brand awareness. Additionally, the expansion of multicultural beauty offerings caters to a broader customer base with varied skin and hair needs. Technological advancements, including AI-driven skin diagnostics and virtual try-ons, are enhancing the in-store and online shopping experience, boosting customer engagement. The trend toward sustainable and cruelty-free products is prompting retailers to stock eco-conscious brands. Moreover, strategic collaborations, private label expansions, and omni-channel retailing-integrating e-commerce with physical stores-are reshaping the competitive landscape. As consumers increasingly seek personalized beauty solutions, supply stores are evolving into experiential destinations offering expert advice and curated product selections.
The geographical analysis of the Beauty Supply Stores Market highlights strong growth across Asia Pacific, North America, and Europe, with emerging potential in Latin America, the Middle East, and Africa. Asia Pacific leads in market expansion, driven by high demand in China, Japan, South Korea, and India. North America remains a mature and high-value market, while Europe shows steady demand for sustainable and premium beauty products. Latin America, the Middle East, and Africa are witnessing gradual development due to rising urbanization and beauty awareness. Key players shaping the competitive landscape include Ulta Beauty, Sephora, Sally Beauty Holdings, CosmoProf, SalonCentric, L’Oréal Group, Estée Lauder Companies, Shiseido Company, Revlon, and Unilever. These companies leverage broad product portfolios, global reach, and strategic retail investments to capture market share and meet evolving consumer needs across diverse regional landscapes.
Market Insights
- The Beauty Supply Stores Market was valued at USD 372.75 million in 2018, reached USD 526.89 million in 2024, and is projected to hit USD 823.51 million by 2032, growing at a CAGR of 5.34%.
- Demand for personal care and grooming products is rising globally, with consumers prioritizing skincare, haircare, and wellness solutions that include natural and anti-aging formulas.
- Social media influence, beauty tutorials, and endorsements from influencers are driving brand visibility and encouraging consumers to explore new and niche products.
- Inclusive and multicultural product lines are expanding, helping retailers meet the beauty needs of diverse skin tones and hair types while boosting customer loyalty.
- Technology integration such as AI-powered skin diagnostics, virtual try-ons, and experiential in-store features is enhancing engagement and driving retail innovation.
- North America, Europe, and Asia Pacific lead the market, with Asia Pacific showing the fastest growth; Latin America, the Middle East, and Africa are emerging as potential growth zones.
- Key players include Ulta Beauty, Sephora, Sally Beauty Holdings, CosmoProf, SalonCentric, L’Oréal, Estée Lauder, Shiseido, Revlon, and Unilever, all leveraging digital channels and product innovation to maintain competitive advantage.
Market Drivers
Rising Demand for Personal Care and Grooming Products
The Beauty Supply Stores Market is expanding due to increasing consumer focus on personal hygiene, grooming, and wellness. Consumers are prioritizing skincare, haircare, and body care routines as essential parts of daily life. Demand for products with natural ingredients, anti-aging properties, and specialized treatments continues to grow. Men’s grooming is also gaining traction, further boosting category expansion. It reflects shifting lifestyle preferences and elevated awareness of self-care. Consumers are investing more in appearance-enhancing products and routines.
- For instance, Colgate re-launched its Strong Teeth, Active Salt, and Total toothpaste lines with science-backed formulas in 2023-24, while its Bright Smiles, Bright Futures program reached over 5.2 million children across 10,000+ schools to promote oral care habit.
Influence of Social Media and Beauty Influencers
The Beauty Supply Stores Market benefits from strong digital influence through social media platforms and beauty influencers. Viral beauty trends and influencer endorsements impact consumer choices and drive foot traffic. Visual content, product tutorials, and reviews provide engaging ways to discover and evaluate products. It encourages experimentation with new brands and niche offerings. Beauty content creators shape demand and improve brand visibility. This dynamic fuels both online and offline store growth.
- For instance, Glossier’s Instagram strategy, which includes sharing user-generated content and investing in photogenic packaging, has cultivated a loyal fanbase of 2 million followers, directly influencing product development and driving both digital and physical store traffic.
Expansion of Multicultural and Inclusive Product Lines
The Beauty Supply Stores Market is adapting to serve a diverse consumer base by offering inclusive products across skin tones, hair types, and cultural preferences. Retailers are expanding their assortments to meet the needs of underrepresented communities. It ensures wider product accessibility for all ethnicities. This inclusive approach fosters brand loyalty and broadens market reach. Consumers expect customized beauty solutions that reflect their identity. Stores must remain responsive to this growing demand for representation.
Innovation in Retail Experience and Technology Integration
The Beauty Supply Stores Market is evolving through the integration of technology and experiential retail strategies. In-store features like virtual try-ons, AI-powered skin analysis, and personalized consultations enhance shopper satisfaction. It helps bridge the gap between online convenience and tactile product testing. Retailers that adopt tech-enabled services attract more loyal customers. The focus on personalization improves engagement and retention. Beauty supply stores are becoming more interactive, creating tailored experiences for diverse customer profiles.
Market Trends
Surging Popularity of Clean and Sustainable Beauty Products
The Beauty Supply Stores Market is witnessing a growing preference for clean, green, and eco-conscious beauty products. Consumers are actively seeking formulations free from harmful chemicals, parabens, and synthetic additives. It reflects a broader awareness of health, environmental impact, and ethical sourcing. Brands with transparent labeling and cruelty-free certifications are gaining favor. Packaging made from recycled materials or biodegradable alternatives is becoming a selling point. Stores that prioritize sustainable options are attracting environmentally responsible buyers.
Shift Toward Hybrid Retail and Omnichannel Shopping Models
The Beauty Supply Stores Market is embracing a hybrid retail model that merges online and in-store experiences. Customers expect seamless transitions between digital browsing and physical purchasing. It enables better product exploration, easier comparisons, and more personalized shopping journeys. Beauty retailers are adopting click-and-collect services, mobile payment systems, and real-time inventory tracking. This trend supports convenience without compromising on experience. Retailers investing in digital infrastructure are strengthening their competitive position and customer retention.
- For instance, Birchbox, initially an online subscription service for beauty products, opened a physical store in New York after data revealed that local customers had three times the lifetime value compared to others, enabling personalized in-person experiences alongside its digital offerings.
Customization and Personalization of Beauty Solutions
The Beauty Supply Stores Market is responding to increasing demand for personalized beauty solutions tailored to individual needs. Shoppers are looking for products aligned with their unique skin types, hair textures, and lifestyle preferences. It reflects a departure from one-size-fits-all offerings. Retailers are using AI tools, data analytics, and diagnostic devices to recommend customized routines. Subscription boxes and curated product bundles are growing in appeal. Personalization builds trust and elevates brand differentiation in a crowded market.
Growing Influence of Indie and Niche Beauty Brands
The Beauty Supply Stores Market is being reshaped by the rise of indie and niche brands that emphasize innovation, storytelling, and authenticity. These brands often address specific concerns or underserved segments with targeted products. It allows consumers to discover unique and highly specialized items. Younger shoppers are especially drawn to smaller labels with bold identities and transparent practices. Store shelves are diversifying to include these fast-growing brands. This trend enhances variety and disrupts traditional brand dominance.
- For instance, PYT Beauty has built its reputation on clean, non-toxic formulas and eco-conscious packaging, offering vegan and cruelty-free cosmetics that appeal to consumers seeking ethical and sustainable options.
Market Challenges Analysis
Rising Competition from E-commerce Giants and Direct-to-Consumer Brands
The Beauty Supply Stores Market faces intense pressure from e-commerce platforms and direct-to-consumer (DTC) brands that offer convenience, speed, and competitive pricing. Major online retailers provide wide assortments and personalized recommendations, drawing customers away from traditional brick-and-mortar outlets. It forces physical stores to rethink inventory strategies and digital integration. DTC brands, with their strong social media presence and loyal followings, often bypass retail intermediaries entirely. These shifts challenge store profitability and long-term customer retention.
Inventory Management and Product Shelf Life Constraints
The Beauty Supply Stores Market struggles with inventory turnover and the limited shelf life of many beauty products. Retailers must carefully forecast demand while managing stock to prevent spoilage or obsolescence. It becomes particularly difficult with seasonal trends, rapid product innovation, and shifting consumer preferences. Overstocking leads to markdowns and reduced margins, while understocking results in lost sales. Balancing supply and demand remains a critical operational hurdle. Effective supply chain coordination is essential to stay competitive.
Market Opportunities
Expansion into Emerging Markets and Underserved Regions
The Beauty Supply Stores Market presents strong growth potential in emerging economies and underserved geographic regions. Rising disposable incomes, urbanization, and increasing beauty awareness are creating new demand centers. It enables retailers to introduce global and local brands tailored to cultural and demographic preferences. Regions in Asia, Latin America, and Africa offer untapped opportunities for retail expansion and franchising. Early market entry can help establish brand loyalty and local partnerships. Physical stores can succeed by aligning with regional trends and consumer behaviors.
Integration of Experiential Retail and Technological Innovation
The Beauty Supply Stores Market can capitalize on immersive in-store experiences and advanced technology to attract and retain customers. Interactive features like smart mirrors, diagnostic tools, and personalized consultations create memorable shopping journeys. It enhances customer satisfaction while encouraging product exploration and upselling. Integrating mobile apps, loyalty programs, and real-time promotions can deepen engagement. Retailers that blend entertainment with shopping can build stronger emotional connections with their audience. This approach differentiates stores from online-only competitors.
Market Segmentation Analysis:
By Product Type
The Beauty Supply Stores Market is segmented into cosmetics, hair care products, and beauty tools and accessories. Cosmetics remain the leading category, driven by demand for makeup, skincare, and anti-aging solutions. Hair care products, including shampoos, conditioners, and styling items, follow closely due to increasing attention to scalp health and textured hair needs. Beauty tools and accessories such as brushes, applicators, and grooming devices support these core categories and continue to expand shelf space. It benefits from seasonal trends and frequent product innovations.
- For instance, L'Oréal reported that its skincare segment accounted for over 40% of its global sales in 2023, reflecting the sustained consumer focus on facial care and anti-aging innovations.
By Customer Type
The Beauty Supply Stores Market caters to both salons and licensed professionals, as well as individual consumers. Professional buyers value bulk purchasing, exclusive product lines, and brand partnerships, contributing to stable wholesale demand. Individual consumers, influenced by beauty trends and online reviews, account for a growing share of sales. It reflects a shift toward DIY beauty care and personalized product choices. Retailers are adapting offerings and in-store experiences to serve both segments effectively.
- For instance, SalonCentric, a major distributor, partners with brands like L'Oréal Professionnel to offer salon-exclusive products and bulk discounts to licensed professionals, supporting consistent wholesale transactions.
By Distribution Channel
The Beauty Supply Stores Market operates through online retail and brick-and-mortar stores. Online platforms provide convenience, broader product access, and digital engagement, attracting a younger, tech-savvy audience. Brick-and-mortar stores remain essential for tactile product testing, in-person consultations, and immediate purchases. It leverages hybrid models, combining physical presence with digital tools, to enhance customer interaction. Retailers investing in omnichannel strategies are achieving stronger brand loyalty and market reach.
Segments:
Based on Product Type
- Cosmetics
- Hair Care Products
- Beauty Tools and Accessories
Based on Customer Type
- Salons and Licensed Professionals
- Individual Consumers
Based on Distribution Channel
- Online Retail
- Brick-and-Mortar Stores
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Beauty Supply Stores Market size was valued at USD 110.84 million in 2018 to USD 154.28 million in 2024 and is anticipated to reach USD 242.12 million by 2032, at a CAGR of 5.4% during the forecast period. The region holds a significant share of the global market due to high consumer spending on personal care and beauty products. It benefits from a strong retail infrastructure, growing demand for premium and organic beauty lines, and the presence of major players such as Ulta Beauty and Sally Beauty. The U.S. drives most of the regional revenue, with Canada and Mexico showing consistent growth. Consumers in this region prioritize high-quality formulations and innovative product offerings. Market players continue to invest in omni-channel experiences and loyalty programs to strengthen customer retention.
Europe
The Europe Beauty Supply Stores Market size was valued at USD 70.62 million in 2018 to USD 94.43 million in 2024 and is anticipated to reach USD 134.42 million by 2032, at a CAGR of 4.1% during the forecast period. The region accounts for a substantial share of the global market, supported by a strong beauty culture and rising demand for sustainable and cruelty-free products. It is led by countries such as the UK, Germany, and France, where consumers value premium skincare and dermatologically-tested cosmetics. Specialty retailers and pharmacies play a key role in distribution. European regulations around clean labeling and ingredient safety drive product development. Consumers are highly aware of brand ethics, influencing their purchase decisions.
Asia Pacific
The Asia Pacific Beauty Supply Stores Market size was valued at USD 158.17 million in 2018 to USD 232.08 million in 2024 and is anticipated to reach USD 385.50 million by 2032, at a CAGR of 6.1% during the forecast period. The region leads the global market in terms of growth rate, driven by expanding urban populations, rising disposable incomes, and a strong influence of K-beauty and J-beauty trends. It includes major consumer bases in China, Japan, South Korea, and India. Domestic and international brands are expanding physical and digital store footprints across urban centers. Consumers in Asia Pacific prioritize skin health, sun protection, and brightening products. The demand for personalized and innovative beauty experiences continues to shape retail strategies.
Latin America
The Latin America Beauty Supply Stores Market size was valued at USD 16.86 million in 2018 to USD 23.52 million in 2024 and is anticipated to reach USD 32.35 million by 2032, at a CAGR of 3.7% during the forecast period. The region contributes a modest share to the global market, supported by growing beauty consciousness and social media influence. Brazil is the dominant market, followed by Argentina and Colombia. It benefits from a rising middle class and cultural emphasis on beauty and personal grooming. Retailers are expanding into second-tier cities and offering localized product lines. Economic instability and import restrictions present challenges, but local brands and private labels continue to gain traction.
Middle East
The Middle East Beauty Supply Stores Market size was valued at USD 10.23 million in 2018 to USD 13.20 million in 2024 and is anticipated to reach USD 17.33 million by 2032, at a CAGR of 3.1% during the forecast period. The region has a niche yet growing market with increasing investment in luxury beauty and halal-certified products. It is driven by countries like the UAE and Saudi Arabia, where high-end retail formats and beauty tourism are expanding. Consumer interest in fragrance, skincare, and personal grooming remains strong. Beauty retailers are launching concept stores to attract affluent and trend-focused shoppers. It supports growth by offering curated assortments and in-store consultation services.
Africa
The Africa Beauty Supply Stores Market size was valued at USD 6.03 million in 2018 to USD 9.38 million in 2024 and is anticipated to reach USD 11.79 million by 2032, at a CAGR of 2.5% during the forecast period. The market remains in an emerging phase, supported by increasing urbanization and awareness of beauty standards. Nigeria and South Africa lead regional demand, with a growing number of local entrepreneurs entering the space. It faces challenges in supply chain logistics and price sensitivity. Demand for hair care, skin-lightening, and ethnic beauty products drives sales. Retailers who address affordability and accessibility are best positioned for future growth.
Key Player Analysis
- SalonCentric
- CosmoProf
- Ulta Beauty
- Sephora
- Sally Beauty Holdings
- L’Oréal Group
- Estée Lauder Companies
- Shiseido Company
- Revlon
- Unilever
Competitive Analysis
The Beauty Supply Stores Market is highly competitive, with a mix of global brands, regional chains, and niche retailers vying for consumer attention. Key players such as Ulta Beauty, Sephora, Sally Beauty Holdings, and SalonCentric lead the market through expansive product portfolios, strategic store placements, and robust digital platforms. It is shaped by evolving consumer preferences, requiring companies to innovate continuously and personalize offerings. Emerging brands and independent stores are capturing attention through unique product selections, ethical positioning, and influencer partnerships. Retailers are investing in omnichannel strategies and in-store experiences to strengthen brand loyalty and drive foot traffic. Private label expansion, loyalty programs, and tech-enabled tools further differentiate leading players. The Beauty Supply Stores Market rewards agility, customer insight, and brand trust, making innovation and engagement critical to gaining market share in an increasingly dynamic retail landscape.
Recent Developments
- In May 2025, e.l.f. Beauty announced its agreement to acquire Rhode, Hailey Bieber’s skincare brand, in a deal valued at up to $1 billion, which was finalized in July 2025.
- In June 2025, L’Oréal Group signed an agreement to acquire premium haircare brand Color Wow to expand its professional hair division.
- In April 2025, Ulta Beauty entered into an exclusive partnership with Cécred, Beyoncé’s prestige haircare line, with plans to offer the brand through its SalonCentric division and physical stores.
- In April 2025, Bread Beauty Supply was acquired by Cost of Doing Business, a new beauty venture launched by the founder of Topicals.
Market Concentration & Characteristics
The Beauty Supply Stores Market exhibits moderate to high market concentration, with a few major players holding significant market share while smaller regional and niche brands compete actively. It is characterized by a dynamic product mix, frequent innovation cycles, and strong brand-driven competition. Key companies such as Ulta Beauty, Sephora, Sally Beauty Holdings, and SalonCentric dominate through expansive store networks, exclusive partnerships, and integrated digital platforms. The market favors companies that adapt quickly to consumer trends, such as clean beauty, personalization, and multicultural inclusivity. It also shows strong responsiveness to social media influence and evolving retail formats, including omni-channel experiences and experiential store layouts. Pricing varies widely across product segments, catering to both premium and value-conscious consumers. Barriers to entry remain moderate due to high brand loyalty, inventory management complexities, and the need for diversified product portfolios. The Beauty Supply Stores Market continues to evolve with innovation, consumer engagement, and service differentiation at its core.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Customer Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for personalized beauty solutions will continue to drive innovation in product offerings and in-store experiences.
- Online retail will gain more traction, supported by mobile commerce, virtual try-ons, and digital loyalty programs.
- Beauty supply stores will expand their focus on sustainable and ethically sourced products to meet growing eco-conscious preferences.
- Technological integration, including AI-powered skin analysis and smart mirrors, will enhance the shopping journey.
- Independent and niche beauty brands will gain more shelf space due to their appeal among younger and trend-focused consumers.
- Retailers will invest in omni-channel strategies to ensure seamless transitions between digital and physical shopping experiences.
- Inclusive product lines catering to diverse skin tones and hair types will become standard across store assortments.
- Emerging markets in Asia Pacific, Latin America, and Africa will offer new growth opportunities for global and regional players.
- Private label beauty products will grow in popularity as retailers look to increase margins and brand loyalty.
- Strategic partnerships with influencers, salons, and content creators will shape marketing and product positioning efforts

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Personalization and Customization
Consumers are increasingly seeking beauty solutions tailored to their unique skin types, hair textures, and preferences, driving stores to offer personalized consultations, AI-powered diagnostics, and curated product selections.
Influence of Social Media and Beauty Influencers
Social media platforms and beauty influencers amplify product visibility, encourage experimentation with new brands, and drive both online and offline store traffic, significantly boosting market growth.
Expansion of Multicultural and Inclusive Product Lines
Retailers are broadening their assortments to serve diverse skin tones and hair types, fostering brand loyalty and expanding their customer base by meeting the needs of underrepresented communities.
Technological Integration and Experiential Retail
The adoption of virtual try-ons, AI-driven skin analysis, and interactive in-store features enhances the shopping experience, increases customer engagement, and differentiates physical stores from online-only competitors.
Shift Toward Clean, Sustainable, and Ethical Products
Growing consumer awareness of health, environmental impact, and ethical sourcing is prompting stores to stock eco-conscious, cruelty-free brands, attracting environmentally responsible buyers and supporting premium product sales.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Beauty Supply Stores Market?
What are the key segments within the Beauty Supply Stores Market?
What are some challenges faced by the Beauty Supply Stores Market?
Who are the major players in the Beauty Supply Stores Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Cosmetics
- 1.2.2 Hair Care Products
- 1.2.3 Beauty Tools and Accessories
- 1.3 By Customer Type
- 1.3.1 Salons and Licensed Professionals
- 1.3.2 Individual Consumers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 526.89 million → 2032: USD 823.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Beauty Supply Stores Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Beauty Supply Stores Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Beauty Supply Stores Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Beauty Supply Stores Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Beauty Supply Stores Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Beauty Supply Stores Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Beauty Supply Stores Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Beauty Supply Stores Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 526.89 million → 2032: USD 823.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Beauty Supply Stores Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cosmetics
- 12.3.7.2 Hair Care Products
- 12.3.7.3 Beauty Tools and Accessories
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Salons and Licensed Professionals
- 12.4.7.2 Individual Consumers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Beauty Supply Stores End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Beauty Supply Stores Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Beauty Supply Stores Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Beauty Supply Stores Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ulta Beauty
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sephora
- 18.4 Sally Beauty Holdings
- 18.5 CosmoProf
- 18.6 SalonCentric
- 18.7 L’Oréal Group
- 18.8 Estée Lauder Companies
- 18.9 Shiseido Company
- 18.10 Revlon
- 18.11 Unilever
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

