
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Benign Prostatic Hyperplasia Treatment Market Size 2024 | USD 2.12 Million |
| Benign Prostatic Hyperplasia Treatment Market, CAGR | 9.2% |
| Benign Prostatic Hyperplasia Treatment Market Size 2032 | USD 4.29 Million |
Market Overview:
Benign Prostatic Hyperplasia Treatment Market size was valued at USD 2.12 billion in 2024 and is anticipated to reach USD 4.29 billion by 2032, at a CAGR of 9.2% during the forecast period (2024-2032).
Key factors propelling the BPH treatment market include the expanding geriatric male population and the growing adoption of minimally invasive surgical procedures. As men age, the likelihood of developing BPH increases, with studies indicating that approximately 50% of men over 50 and up to 90% of men over 80 are affected. Additionally, the shift towards minimally invasive treatments, such as laser therapies and UroLift systems, is enhancing patient outcomes and reducing recovery times, thereby driving market demand. Furthermore, the increasing awareness and preference for outpatient procedures are also contributing to the market's expansion. Technological advancements, such as the development of more precise diagnostic tools, are expected to further boost the demand for effective BPH treatments, providing better patient outcomes with fewer side effects.
Regionally, North America dominates the BPH treatment market, accounting for a significant share due to advanced healthcare infrastructure, high healthcare expenditure, and a substantial elderly population. The United States, in particular, leads in market size and growth, driven by its robust healthcare system and increasing number of men seeking treatment for BPH. Europe follows, with countries like Germany and the United Kingdom exhibiting robust market activity, supported by a well-established healthcare network and increasing government support for elderly healthcare. The Asia-Pacific region is anticipated to witness the fastest growth, fueled by a rapidly aging population, increasing healthcare investments, and rising awareness about BPH. Additionally, the growing adoption of advanced medical technologies in countries such as Japan, China, and India is expected to accelerate market penetration in the region, creating significant growth opportunities for BPH treatment providers.
Market Insights:
- The global Benign Prostatic Hyperplasia (BPH) treatment market is expected to grow from USD 2.12 billion in 2024 to USD 4.29 billion by 2032, at a CAGR of 9.2%, driven by increasing demand for effective treatments due to the aging male population.
- Key market drivers include the rising prevalence of BPH, with studies indicating that 50% of men over 50 and up to 90% of men over 80 are affected, creating a growing patient base.
- Advancements in minimally invasive procedures, such as laser therapies and UroLift systems, are fueling market growth by offering quicker recovery times, fewer complications, and reducing the need for hospital stays.
- Technological innovations in diagnostic tools and treatment devices are enhancing the effectiveness of BPH treatments, allowing for more personalized approaches and improved patient outcomes.
- Increased awareness about BPH and the availability of treatment options is boosting demand, as public health campaigns and physician outreach programs encourage early diagnosis and intervention.
- High treatment costs remain a major restraint, particularly for advanced treatments like laser therapies and UroLift systems, which are often inaccessible in regions with limited healthcare budgets.
- Regional growth trends show North America holding a significant market share due to advanced healthcare infrastructure, while the Asia-Pacific region is expected to grow the fastest, fueled by an aging population and rising healthcare investments.
Market Drivers:
Growing Aging Male Population
One of the most significant drivers of the Benign Prostatic Hyperplasia (BPH) treatment market is the increasing aging population, particularly men over the age of 50. As men age, the likelihood of developing BPH rises, with an estimated 50% of men over the age of 50 and 90% of men over 80 experiencing symptoms of the condition. The growing number of elderly individuals globally is thus directly contributing to the rise in BPH diagnoses, driving demand for effective treatment options. The population shift towards an older demographic, especially in developed nations, is expected to increase the prevalence of BPH, subsequently boosting the need for both pharmaceutical and surgical treatments. This demographic trend is anticipated to be a primary market driver for BPH treatment solutions in the coming years.
Advancements in Minimally Invasive Procedures
The shift towards minimally invasive treatment options is another key driver propelling the BPH treatment market. Traditionally, BPH was treated with invasive surgeries such as prostatectomy. However, technological advancements have introduced a variety of minimally invasive procedures, including laser therapy, transurethral microwave therapy (TUMT), and UroLift systems. These treatments have gained widespread adoption due to their ability to provide effective relief with shorter recovery times, fewer complications, and reduced hospital stays. The preference for outpatient procedures is increasing, as patients seek treatments that allow them to return to their daily lives quickly. The growing popularity of these less invasive alternatives is driving the demand for modern BPH treatment options, thereby fueling the overall market growth.
Technological Innovations in Treatment Devices
Technological advancements in the development of treatment devices also play a pivotal role in the expansion of the BPH treatment market. The introduction of more precise diagnostic tools, such as advanced imaging techniques and urodynamic testing, has enabled better identification and monitoring of BPH. This, in turn, leads to more personalized treatment plans, improving the overall effectiveness of interventions. Furthermore, innovations in treatment technologies, such as high-powered lasers and newer drug delivery methods, have contributed to enhanced therapeutic outcomes for patients. For example, developments in holmium laser enucleation of the prostate (HoLEP) have allowed surgeons to perform effective outpatient surgeries. These technological improvements have enhanced the safety, efficiency, and success rates of various BPH treatments, increasing their adoption among both healthcare providers and patients. As technology continues to advance, the market for BPH treatment devices is expected to expand further, offering more effective and minimally invasive solutions.
Rising Awareness and Healthcare Access
An increase in awareness about BPH, coupled with improvements in healthcare access, is also significantly contributing to market growth. As more men become informed about BPH symptoms and the importance of early diagnosis, the demand for treatment is increasing. Public health campaigns and physician outreach programs have raised awareness about the condition, encouraging more individuals to seek medical advice and treatment options. Additionally, the expansion of healthcare infrastructure, particularly in developing regions, is making BPH treatment more accessible to a broader population. In North America, for example, the presence of specialized urology centers and advanced healthcare systems facilitates better access to both pharmaceutical and surgical treatments. With advancements in healthcare delivery and a growing number of specialized urology centers, patients have better access to treatment, thus driving the demand for effective BPH solutions. As healthcare systems continue to improve, the availability of both medical and surgical treatment options will support the ongoing growth of the BPH treatment market.
Market Trends:
Increased Adoption of Laser-Based Therapies
One of the prominent trends shaping the Benign Prostatic Hyperplasia (BPH) treatment market is the rising adoption of laser-based therapies. Procedures such as Holmium Laser Enucleation of the Prostate (HoLEP) and Photoselective Vaporization of the Prostate (PVP) are becoming increasingly popular due to their high efficacy and low complication rates. For instance, bibliometric studies have shown that Ho:YAG laser articles were cited the most between 2007 and 2018, highlighting its significance in clinical practice. These treatments are highly effective in reducing the size of the prostate, improving urinary flow, and minimizing patient recovery time compared to traditional surgical methods. The trend towards laser therapies is further driven by technological advancements, offering precision and better control during the procedure, which enhances patient outcomes. As more healthcare providers incorporate laser treatments into their practice, this trend is expected to significantly drive the growth of the BPH treatment market.
Focus on Minimally Invasive and Outpatient Procedures
The growing preference for minimally invasive procedures and outpatient treatments is another significant trend in the BPH treatment market. For example, the UroLift system has demonstrated durable, rapid symptom relief with a low retreatment rate of approximately 13.6% over five years, and its real-world effectiveness has been validated through over 145 peer-reviewed publications. These treatments do not require general anesthesia and can often be performed on an outpatient basis, reducing healthcare costs and improving convenience for patients. This trend is expected to continue as more patients opt for treatments that minimize hospital stays and offer quicker recovery times. Additionally, as the healthcare industry increasingly focuses on reducing patient costs and improving efficiency, minimally invasive treatments are likely to become the standard approach for managing BPH.
Personalized and Targeted Treatment Approaches
As the understanding of BPH continues to evolve, there is a growing trend toward personalized and targeted treatment approaches. Advances in urological diagnostics, such as genetic testing and molecular profiling, allow for better identification of BPH severity and the most appropriate treatment options for individual patients. Personalized treatments ensure that patients receive care tailored to their specific needs, improving treatment outcomes and reducing unnecessary side effects. This trend is expected to become more prevalent as precision medicine continues to make strides in various therapeutic fields, including urology. By focusing on individualized care, healthcare providers can deliver more effective treatments, enhancing both patient satisfaction and the overall success of BPH therapies.
Expansion of BPH Treatments in Emerging Markets
Another notable trend in the BPH treatment market is the expansion of treatment options into emerging markets, particularly in regions such as Asia-Pacific and Latin America. As these regions experience rapid urbanization, improvements in healthcare infrastructure, and an increase in the geriatric population, the demand for BPH treatments is growing. Many developing nations are witnessing a surge in the prevalence of BPH, which is driving the adoption of both pharmaceutical and surgical treatments. Additionally, greater awareness of BPH and its associated health risks is encouraging more individuals in these regions to seek medical care. As the market for BPH treatments in emerging economies continues to expand, it offers significant growth opportunities for manufacturers and healthcare providers, fueling the global growth of the BPH treatment market.
Market Challenges Analysis:
High Treatment Costs
One of the significant restraints affecting the growth of the Benign Prostatic Hyperplasia (BPH) treatment market is the high cost associated with advanced treatment options. Minimally invasive procedures such as laser therapies and UroLift systems, while effective, often come with a high price tag compared to traditional treatments. This can make such procedures inaccessible to a large portion of the patient population, especially in developing regions with limited healthcare budgets. High treatment costs may also place a financial burden on healthcare systems, further limiting the adoption of these advanced therapies. As a result, many patients continue to rely on less expensive pharmaceutical treatments, which may not provide long-term relief, thus impacting the overall growth of the market.
Lack of Awareness in Emerging Markets
A key challenge for the BPH treatment market is the lack of awareness surrounding the condition, particularly in emerging markets. For example, studies indicate that a large proportion of men in low-income regions have not undergone prostate screening due to limited awareness and financial constraints, despite a high willingness to get screened if informed. This lack of awareness often leads to delayed diagnosis and underutilization of advanced treatments. Additionally, in some regions, cultural stigmas associated with urological health problems may prevent patients from seeking medical advice, further hindering market growth. Efforts to educate the population about BPH and its treatments are essential to address this challenge and drive demand for more effective solutions in these regions.
Side Effects and Complications of Treatment
Another challenge that limits the widespread adoption of BPH treatments is the potential for side effects and complications associated with certain procedures. While minimally invasive treatments have lower complication rates than traditional surgeries, they are not without risks. Patients may experience adverse effects such as urinary incontinence, erectile dysfunction, or infection following surgery or laser therapy. These side effects can deter some patients from opting for these procedures, particularly those who fear post-treatment complications. As the market grows, manufacturers and healthcare providers must continue to focus on improving treatment safety profiles to mitigate these risks and enhance patient confidence in available therapies.
Market Opportunities:
The growing global geriatric population presents a significant opportunity for the Benign Prostatic Hyperplasia (BPH) treatment market. As the population of men over 50 continues to rise, the demand for BPH treatments is expected to increase substantially. With an aging demographic, more individuals will seek medical intervention to manage BPH symptoms, driving the need for both pharmaceutical and surgical treatments. The increasing recognition of the condition's impact on quality of life is also encouraging more patients to seek timely treatment, further expanding the market. This creates opportunities for both established and emerging companies to develop innovative treatment solutions that cater to this growing patient base.
Another key opportunity lies in the advancement of minimally invasive and outpatient treatment options, such as the UroLift system and laser therapies. These procedures offer significant benefits, including shorter recovery times, reduced complications, and fewer hospital stays, making them more appealing to patients. As awareness of these treatment options continues to grow, the market for minimally invasive BPH therapies is expected to expand. Additionally, the increasing shift towards outpatient care and same-day procedures presents a unique opportunity for healthcare providers to enhance patient satisfaction while reducing healthcare costs. Companies that innovate in this space and expand their offerings in emerging markets are well-positioned to capitalize on the growing demand for effective, less invasive BPH treatments.
Market Segmentation Analysis:
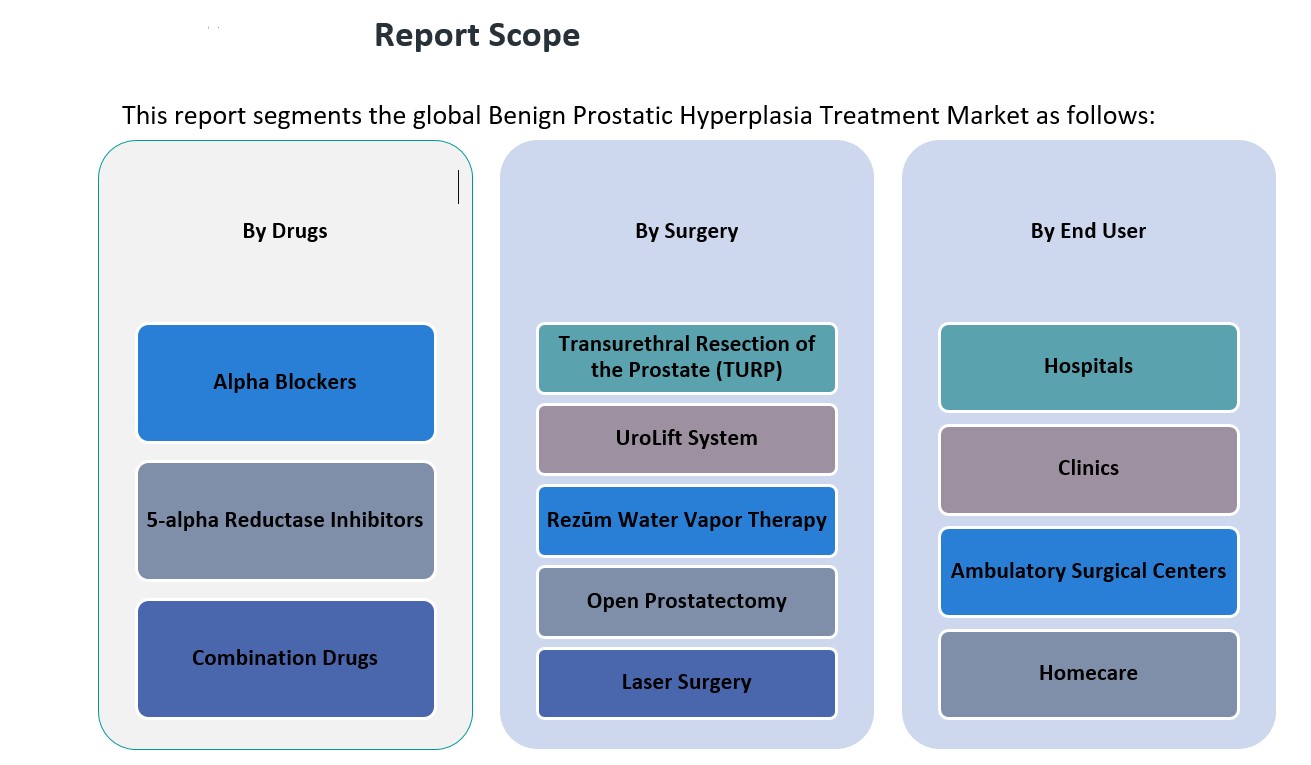
The Benign Prostatic Hyperplasia (BPH) treatment market is segmented across drugs, surgery, and end-users, each catering to distinct patient needs and treatment options.
By Drugs Segment: The market for BPH drugs is primarily dominated by three categories. Alpha blockers are widely used due to their ability to relax the muscles in the prostate and bladder neck, improving urine flow. 5-alpha reductase inhibitors are another common drug type, which reduce prostate size by blocking the hormone responsible for prostate growth. Combination drugs, which combine both of these treatment approaches, are gaining popularity due to their enhanced efficacy in managing symptoms and slowing disease progression.
By Surgery Segment: Surgical treatments for BPH include Transurethral Resection of the Prostate (TURP), which remains the gold standard for many patients with severe symptoms. The UroLift System is a newer, minimally invasive procedure that has gained traction for its effectiveness and minimal recovery time. Rezūm Water Vapor Therapy offers an innovative approach to shrink prostate tissue using steam. Open prostatectomy and laser surgery also provide options for patients with severe BPH, though these are typically reserved for more complicated cases.
By End-user Segment: The end-user segment is primarily divided into hospitals, clinics, ambulatory surgical centers, and homecare. Hospitals remain the leading venue for both drug prescriptions and surgical interventions, due to their capacity for handling more complex cases. Clinics and ambulatory surgical centers are increasingly adopting minimally invasive techniques, providing patients with quicker recovery times. Homecare is expanding, with patients seeking more flexible, less invasive treatment options at home.
Segmentation:
By Drugs Segment
- Alpha Blockers
- 5-alpha Reductase Inhibitors
- Combination Drugs
By Surgery Segment
- Transurethral Resection of the Prostate (TURP)
- UroLift System
- Rezūm Water Vapor Therapy
- Open Prostatectomy
- Laser Surgery
By End-user Segment
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Homecare
Regional Analysis:
The Benign Prostatic Hyperplasia (BPH) treatment market is experiencing varied growth across different regions, influenced by factors such as demographic trends, healthcare infrastructure, and technological advancements. North America currently holds the largest share of the global BPH treatment market, accounting for over 40% of the total market share. This dominance is driven by the high prevalence of BPH in the aging male population, coupled with advanced healthcare infrastructure and the availability of cutting-edge treatment options. In particular, the United States has witnessed significant growth due to the growing number of BPH cases and a strong emphasis on minimally invasive procedures. Additionally, the presence of leading medical device manufacturers and pharmaceutical companies in North America further bolsters market growth, as innovations in treatment technologies continue to enhance patient outcomes.
Europe follows closely, capturing a significant portion of the BPH treatment market with a share of around 30%. Countries such as Germany, the United Kingdom, and France exhibit high levels of market activity due to well-established healthcare systems and increasing government initiatives aimed at improving healthcare for the elderly population. The European market is also seeing a steady rise in the adoption of minimally invasive treatment procedures like laser therapies and UroLift, which offer a favorable treatment experience for patients. Furthermore, the aging population in Europe is expected to continue driving demand for BPH treatments, ensuring sustained market growth in the region over the coming years.
In the Asia-Pacific region, the BPH treatment market is expected to experience the fastest growth, This rapid growth is largely attributed to the increasing elderly population in countries like Japan, China, and India, where healthcare infrastructure is improving. While the market share for the Asia-Pacific region is currently smaller compared to North America and Europe, the rising awareness about BPH and growing demand for advanced treatment options are expected to significantly contribute to market expansion. The increasing adoption of minimally invasive procedures and greater access to healthcare services are key drivers of this growth.
The Rest of the World (RoW), which includes regions such as Latin America, the Middle East, and Africa, accounts for a smaller share of the BPH treatment market, estimated at around 10%. However, these regions are expected to see gradual growth due to increasing healthcare investments and improvements in medical technologies. While challenges such as limited access to advanced healthcare services and lower awareness of BPH persist, the expanding elderly population and the rising demand for effective treatment options will drive market development in these regions in the long term.
Key Player Analysis:
- GlaxoSmithKline plc
- Pfizer Inc.
- Eli Lilly and Company
- Abbott Laboratories
- Boston Scientific Corporation
- Teleflex Incorporated
- Medtronic plc
- Olympus Corporation
- Lumenis Ltd.
- Urologix, LLC
Competitive Analysis:
The Benign Prostatic Hyperplasia (BPH) treatment market is highly competitive, with several key players operating across the pharmaceutical, medical device, and healthcare sectors. Leading companies such as Boston Scientific, Medtronic, and Abbott Laboratories dominate the market by offering a wide range of BPH treatment solutions, including minimally invasive devices, surgical treatments, and pharmaceutical therapies. Boston Scientific, for example, is a prominent player with its UroLift system, which has gained widespread adoption due to its effectiveness and minimal recovery time. Additionally, pharmaceutical companies like Eli Lilly and Pfizer contribute significantly to the market by providing medications such as alpha-blockers and 5-alpha-reductase inhibitors, which help manage BPH symptoms. The market is also witnessing increasing competition from emerging players who focus on innovative treatment options, such as laser therapies and novel drug formulations, aimed at improving patient outcomes. As the market continues to evolve, companies must prioritize innovation, patient-centric solutions, and regulatory compliance to maintain a competitive edge.
Recent Developments:
- In January 2025, Pfizer Inc. partnered with the American Urological Association Education and Research, Inc. (AUAER) to launch a $1.5 million Request for Proposals (RFP) aimed at advancing care for patients with advanced prostate cancer, which is closely related to BPH management. This collaboration focuses on funding innovative quality improvement projects to optimize treatment and reduce disparities in advanced prostate cancer care.
- In July 2023, GlaxoSmithKline PLC entered into a significant partnership with Recordati to commercialize Avodart (dutasteride) and Combodart/Duodart (dutasteride/tamsulosin) across 21 countries, primarily in Europe. This agreement excludes countries where GSK already has existing distribution arrangements, thereby expanding the reach of these key benign prostatic hyperplasia (BPH) treatments to new markets and strengthening GSK’s presence in the BPH sector.
Market Concentration & Characteristics:
The Benign Prostatic Hyperplasia (BPH) treatment market exhibits moderate concentration, with a few key players commanding a significant share due to their established presence, extensive product portfolios, and strong brand recognition. Leading companies such as Boston Scientific, Medtronic, and Abbott Laboratories dominate the market by offering advanced medical devices and pharmaceutical therapies. These companies benefit from economies of scale, robust research and development (R&D) capabilities, and established distribution networks, ensuring their products' availability and accessibility across various regions. Despite the dominance of large players, the market also presents opportunities for smaller companies and emerging players, particularly those focusing on innovative, minimally invasive treatments and novel drug formulations. The market is characterized by continuous technological advancements, patient-centric solutions, and evolving regulatory landscapes. As a result, competition is expected to intensify as companies strive to introduce new, effective treatments that offer improved patient outcomes and address unmet needs in BPH care.
Report Coverage:
The research report offers an in-depth analysis based on Drugs, Surgery and End-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The BPH treatment market is expected to witness steady growth due to the increasing aging male population globally.
- Advancements in minimally invasive procedures, such as UroLift and laser therapies, will drive greater adoption among patients seeking faster recovery.
- Technological innovations in medical devices and drug formulations will enhance treatment precision and improve patient outcomes.
- Rising awareness of BPH symptoms and available treatments will increase early diagnoses and intervention rates.
- Expansion of healthcare infrastructure in emerging markets will facilitate broader access to BPH treatments.
- The growing preference for outpatient treatments will lead to a shift in market dynamics toward more cost-effective, non-surgical options.
- Increasing collaborations between pharmaceutical companies and medical device manufacturers will foster the development of comprehensive treatment solutions.
- Regulatory approvals for new drugs and devices will create new opportunities for market players to expand their offerings.
- The demand for personalized medicine and targeted therapies will lead to more individualized treatment approaches for BPH patients.
- Competitive pressure will drive innovation, as companies seek to differentiate themselves through improved safety profiles and superior patient satisfaction.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Aging Male Population
The increasing number of men over the age of 50 globally is leading to a higher prevalence of BPH, directly expanding the patient pool and driving demand for both pharmaceutical and surgical treatment options.
Advancements in Minimally Invasive Procedures
Technological progress has enabled the development and adoption of minimally invasive treatments such as laser therapies and UroLift systems, which offer faster recovery, fewer complications, and greater patient preference, boosting market growth.
Technological Innovations in Treatment Devices
The introduction of advanced diagnostic tools and more precise treatment devices, such as high-powered lasers and improved drug delivery systems, is enhancing treatment outcomes and expanding the range of effective BPH therapies.
Rising Awareness and Healthcare Access
Increased public health campaigns and physician outreach are improving awareness of BPH symptoms and treatment options, while expanding healthcare infrastructure - especially in emerging markets - is making treatments more accessible to a broader population.
Preference for Outpatient and Cost-Effective Treatments
The shift toward outpatient and minimally invasive procedures is reducing hospital stays and overall treatment costs, making BPH therapies more attractive to both patients and healthcare providers, and accelerating market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Benign Prostatic Hyperplasia Treatment Market?
What factors are driving the growth of the Benign Prostatic Hyperplasia Treatment Market?
What are the key segments within the Benign Prostatic Hyperplasia Treatment Market?
What are some challenges faced by the Benign Prostatic Hyperplasia Treatment Market?
Who are the major players in the Benign Prostatic Hyperplasia Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drugs Segment
- 1.2.1 Alpha Blockers
- 1.2.2 5-alpha Reductase Inhibitors
- 1.2.3 Combination Drugs
- 1.3 By Surgery Segment
- 1.3.1 Transurethral Resection of the Prostate (TURP)
- 1.3.2 UroLift System
- 1.3.3 Rezūm Water Vapor Therapy
- 1.3.4 Open Prostatectomy
- 1.3.5 Laser Surgery
- 1.4 By End-user Segment
- 1.4.1 Hospitals
- 1.4.2 Clinics
- 1.4.3 Ambulatory Surgical Centers
- 1.4.4 Homecare
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.12 billion → 2032: USD 4.29 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Benign Prostatic Hyperplasia Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Benign Prostatic Hyperplasia Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Benign Prostatic Hyperplasia Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Benign Prostatic Hyperplasia Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Benign Prostatic Hyperplasia Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Benign Prostatic Hyperplasia Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Benign Prostatic Hyperplasia Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Benign Prostatic Hyperplasia Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.12 billion → 2032: USD 4.29 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Benign Prostatic Hyperplasia Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drugs Segment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alpha Blockers
- 12.3.7.2 5-alpha Reductase Inhibitors
- 12.3.7.3 Combination Drugs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Surgery Segment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transurethral Resection of the Prostate (TURP)
- 12.4.7.2 UroLift System
- 12.4.7.3 Rezūm Water Vapor Therapy
- 12.4.7.4 Open Prostatectomy
- 12.4.7.5 Laser Surgery
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Clinics
- 12.5.7.3 Ambulatory Surgical Centers
- 12.5.7.4 Homecare
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Benign Prostatic Hyperplasia Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Benign Prostatic Hyperplasia Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Benign Prostatic Hyperplasia Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Benign Prostatic Hyperplasia Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GlaxoSmithKline plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pfizer Inc.
- 18.4 Eli Lilly and Company
- 18.5 Abbott Laboratories
- 18.6 Boston Scientific Corporation
- 18.7 Teleflex Incorporated
- 18.8 Medtronic plc
- 18.9 Olympus Corporation
- 18.10 Lumenis Ltd.
- 18.11 Urologix, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

