
Bile Duct Cancer Treatment Market Overview:
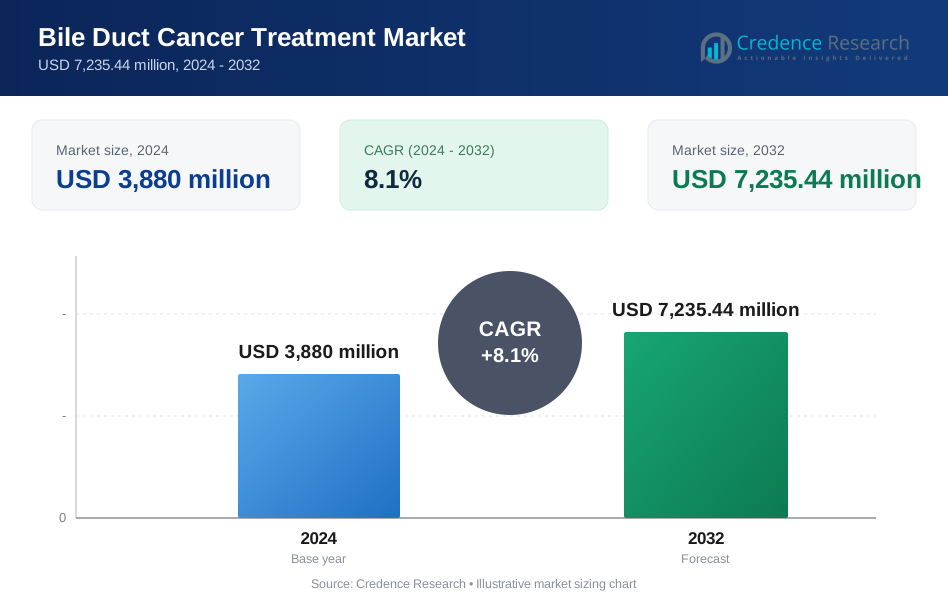
Bile Duct Cancer Treatment Market size was valued USD 3880 million in 2024 and is anticipated to reach USD 7235.44 million by 2032, at a CAGR of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bile Duct Cancer Treatment Market Size 2024 | USD 3880 million |
| Bile Duct Cancer Treatment Market, CAGR | 8.1% |
| Bile Duct Cancer Treatment Market Size 2032 | USD 7235.44 million |
Bile Duct Cancer Treatment Market Insights
- Market growth is strongly supported by increasing adoption of targeted therapies and immunotherapies, with targeted therapy emerging as the leading treatment segment holding an estimated around 42% share, due to higher efficacy in genetically defined patient populations.
- Precision oncology trends, including routine molecular profiling and biomarker-based treatment selection, are reshaping clinical decision-making and improving treatment outcomes across advanced and early-stage cases.
- Competitive dynamics focus on robust clinical pipelines, orphan drug strategies, and combination regimens, while high development costs, limited patient pools, and delayed diagnosis continue to restrain faster market penetration.
- Regionally, North America leads with an exact 38% market share, supported by advanced oncology infrastructure and reimbursement strength, while Asia-Pacific shows the fastest growth due to rising incidence and expanding treatment access.

Bile Duct Cancer Treatment Market Segmentation Analysis:
By Type
By type, extrahepatic bile duct cancer (eCCA) represents the dominant sub-segment, accounting for an estimated 58% market share, primarily due to its higher clinical detection rate and more defined anatomical presentation compared to intrahepatic forms. eCCA cases are more frequently diagnosed at a resectable stage because symptoms such as jaundice appear earlier, driving higher intervention rates. In contrast, intrahepatic bile duct cancer (iCCA) continues to grow steadily, supported by rising incidence linked to chronic liver disease, hepatitis infections, and cirrhosis. However, delayed diagnosis and diffuse tumor growth patterns limit treatment accessibility, keeping iCCA secondary in overall market contribution.
- For instance, Incyte Corporation advanced precision treatment for iCCA through pemigatinib, evaluated in the Phase II FIGHT-202 trial involving 107 previously treated patients with FGFR2 fusions or rearrangements, where 38 patients achieved confirmed objective tumor responses and median response duration exceeded 7 months, highlighting targeted therapy progress despite diagnostic challenges.
By Treatment
By treatment, chemotherapy dominates the market with an approximate 46% market share, driven by its broad applicability across early-stage unresectable and advanced bile duct cancer cases. Gemcitabine-based combination regimens remain the standard of care, supporting widespread clinical adoption. Surgery follows as a critical curative option but is limited by low eligibility rates due to late-stage diagnosis. Targeted therapy and immunotherapy are rapidly emerging segments, supported by molecular profiling advancements and biomarker-driven treatment selection, while radiation therapy maintains a supportive role in adjuvant and palliative settings, contributing incrementally to overall treatment utilization.
- For instance, AbbVie Inc. has advanced its oncology portfolio through the development of venetoclax, a first-in-class BCL-2 inhibitor, while boldly expanding its research footprint into solid tumors.
By Treatment Provider
By treatment provider, hospitals hold the dominant position with an estimated 64% market share, supported by their advanced surgical infrastructure, multidisciplinary oncology teams, and access to complex diagnostic and treatment modalities. Hospitals are the primary centers for surgical resections, combination chemotherapy, and radiation therapy delivery. Oncology centers and specialty clinics are expanding steadily, driven by increased focus on precision oncology and outpatient chemotherapy administration. Meanwhile, ambulatory surgical centers (ASCs) remain a smaller segment, as bile duct cancer management often requires inpatient care, advanced imaging, and post-procedural monitoring beyond typical ASC capabilities.
Key Growth Drivers
Rising Incidence and Improved Diagnosis of Cholangiocarcinoma
The bile duct cancer treatment market continues to expand due to the rising global incidence of cholangiocarcinoma, particularly intrahepatic bile duct cancer, driven by risk factors such as chronic liver disease, hepatitis infections, primary sclerosing cholangitis, and metabolic disorders. Simultaneously, advances in diagnostic imaging, molecular pathology, and biomarker testing have improved early and accurate detection rates. Enhanced diagnostic precision increases the proportion of patients eligible for active treatment, including surgery, systemic therapy, and targeted interventions, thereby directly supporting sustained demand growth across multiple treatment modalities.
- For instance, QED Therapeutics has advanced precision oncology through infigratinib (BGJ398), an oral FGFR1–3 inhibitor, evaluated in a Phase II study involving 108 patients with FGFR2 fusion–positive cholangiocarcinoma, where 25 patients achieved confirmed objective responses and molecular eligibility was established using centralized genomic testing, underscoring how biomarker-driven diagnostics directly translate into targeted treatment access.
Advancements in Targeted and Immuno-Oncology Therapies
Rapid progress in targeted therapies and immuno-oncology has emerged as a major growth driver for the bile duct cancer treatment market. Novel agents targeting FGFR2 fusions, IDH1 mutations, and HER2 alterations have demonstrated improved clinical outcomes in selected patient populations. In parallel, immune checkpoint inhibitors are increasingly evaluated in combination regimens for advanced and unresectable disease. These therapeutic innovations address historically poor survival outcomes, expand treatment options beyond conventional chemotherapy, and drive higher adoption of precision medicine approaches in both first-line and refractory settings.
- For instance, Fresenius Kabi is leading the EASYGEN consortium, funded with 8 million from the Innovative Health Initiative, to develop a modular, hospital-based CAR-T cell manufacturing platform targeted to reduce production time from weeks to just a few days, leveraging its Lovo and Cue automated cell processing systems originally developed by Fresenius Kabi.
Expansion of Oncology Infrastructure and Access to Specialized Care
The expansion of oncology care infrastructure, particularly in emerging economies, significantly contributes to market growth. Increased investments in tertiary hospitals, dedicated cancer centers, and specialty oncology clinics have improved access to advanced diagnostics, multidisciplinary tumor boards, and complex treatment regimens. Improved reimbursement frameworks and inclusion of novel oncology drugs in national formularies further support treatment uptake. As awareness among clinicians and patients improves, referral rates for specialized bile duct cancer management continue to rise, strengthening overall market penetration.
Key Trends & Opportunities
Shift Toward Precision Medicine and Biomarker-Driven Treatment
A key trend shaping the bile duct cancer treatment market is the shift toward biomarker-driven precision medicine. Comprehensive genomic profiling is increasingly adopted to identify actionable mutations, enabling personalized treatment selection. This trend creates strong opportunities for pharmaceutical companies developing companion diagnostics and targeted therapies. Precision medicine not only improves clinical efficacy but also optimizes treatment sequencing, positioning molecular testing as a standard component of bile duct cancer management and reinforcing long-term demand for innovative targeted drugs.
- For instance, Pfizer Inc. significantly advanced precision oncology through its expanded investigational antibody-drug conjugate (ADC) and targeted therapy platforms, presenting data from more than 45 company-sponsored and collaborative research abstracts across diverse tumor types at the European Society for Medical Oncology (ESMO) Congress.
Growing Clinical Pipeline and Combination Therapy Strategies
The expanding clinical pipeline represents a significant opportunity, with numerous late- and mid-stage trials evaluating novel agents and combination regimens. Pharmaceutical companies increasingly focus on combining targeted therapies, immunotherapies, and chemotherapy to enhance response rates and durability. These combination strategies aim to overcome resistance mechanisms and improve outcomes in advanced-stage disease. Successful trial outcomes are expected to accelerate regulatory approvals, diversify treatment options, and create sustained revenue opportunities across multiple lines of therapy.
Increased Focus on Early-Stage Intervention and Adjuvant Therapy
Another emerging trend is the growing focus on early-stage intervention and adjuvant therapy following surgical resection. Clinical evidence supporting adjuvant chemotherapy and targeted approaches is strengthening, encouraging earlier therapeutic intervention. This trend expands the treatable patient population beyond late-stage disease and increases treatment duration per patient. As survival improves, long-term disease management strategies are expected to gain importance, further supporting market expansion.
- For instance, Genentech, Inc. and collaborators are advancing individualized mRNA-based adjuvant immunotherapies such as Autogene cevumeran, an investigational personalized neoantigen vaccine platform; in a Phase I trial enrolling 34 patients with resectable pancreatic cancer, 28 underwent surgery and 16 subsequently received the vaccine post-resection, demonstrating feasibility of post-surgical immunomodulation where up to 20 unique patient-specific neoantigens were encoded per vaccine formulation, illustrating how early-stage, adjuvant precision platforms are being operationalized within Genentech’s oncology pipeline.
Key Challenges
Limited Patient Pool and Disease Heterogeneity
A major challenge in the bile duct cancer treatment market is the relatively small patient population combined with significant disease heterogeneity. Variations in tumor location, molecular profile, and disease stage complicate clinical trial design and limit broad therapeutic applicability. This heterogeneity often necessitates highly specific treatment approaches, increasing development complexity and cost. For manufacturers, achieving scalable commercialization remains difficult, particularly for therapies targeting narrow genetic subgroups within an already rare cancer indication.
High Treatment Costs and Uneven Global Access
High treatment costs pose a significant barrier to widespread adoption, especially for novel targeted and immunotherapy agents. In many regions, limited reimbursement coverage and budget constraints restrict patient access to advanced treatments. Disparities in healthcare infrastructure further exacerbate access challenges between developed and emerging markets. These cost and access constraints can delay treatment initiation, reduce therapy adherence, and ultimately limit market growth despite strong clinical innovation and unmet medical need.
Regional Analysis
North America
North America dominates the bile duct cancer treatment market with an estimated 38% market share, supported by advanced oncology infrastructure, high awareness, and early adoption of novel therapies. The United States drives regional growth due to strong clinical research activity, rapid uptake of targeted therapies and immunotherapies, and favorable reimbursement for complex oncology treatments. High availability of specialized cancer centers and multidisciplinary care teams improves diagnosis and treatment outcomes. Ongoing clinical trials in cholangiocarcinoma, coupled with FDA approvals for targeted agents addressing FGFR and IDH mutations, continue to expand therapeutic options and sustain regional market leadership.
Europe
Europe accounts for approximately 27% of the global bile duct cancer treatment market, driven by robust public healthcare systems and growing adoption of precision oncology. Countries such as Germany, France, the UK, and Italy lead regional demand due to well-established oncology networks and increasing access to molecular diagnostics. European regulatory support for orphan drugs and rare cancer therapies accelerates market penetration of targeted and immuno-oncology treatments. Rising incidence of intrahepatic cholangiocarcinoma and expanding cross-border clinical research collaborations further support growth, while cost-containment policies moderate the pace of premium therapy adoption.
Asia-Pacific
Asia-Pacific holds nearly 23% market share and represents the fastest-growing regional market due to high disease prevalence, particularly in China, Thailand, South Korea, and Japan. Endemic risk factors such as liver fluke infections and chronic liver disease significantly increase bile duct cancer incidence. Rapid expansion of oncology infrastructure, improving access to chemotherapy and targeted therapies, and growing government investment in cancer care drive market growth. Japan and South Korea lead in advanced treatment adoption, while China and India contribute through large patient volumes and increasing availability of cost-effective oncology drugs.
Latin America
Latin America represents around 7% of the bile duct cancer treatment market, supported by gradual improvements in cancer diagnosis and treatment accessibility. Brazil and Mexico dominate regional demand due to relatively advanced healthcare infrastructure and rising oncology expenditure. Chemotherapy remains the primary treatment modality, while adoption of targeted therapies and immunotherapy is growing slowly due to cost and reimbursement limitations. Increasing awareness of hepatobiliary cancers, expansion of private oncology centers, and improving access to diagnostic imaging contribute to steady market expansion, although disparities in healthcare access remain a key regional challenge.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% of the global market, reflecting limited access to advanced cancer therapies in several countries. Gulf Cooperation Council (GCC) nations drive regional growth through investments in modern oncology hospitals, improved diagnostic capabilities, and access to innovative treatments. In contrast, many African countries rely on chemotherapy and palliative care due to infrastructure and funding constraints. Rising cancer awareness, gradual healthcare modernization, and international collaborations are improving treatment availability, supporting modest but consistent growth across the region.
Bile Duct Cancer Treatment Market Segmentations:
By Type:
- Extrahepatic bile duct cancer (eCCA)
- Intrahepatic bile duct cancer (iCCA)
By Treatment:
- Surgery
- Chemotherapy
By Treatment Provider:
- Oncology centers & specialty clinics
- Ambulatory surgical centers (ASCs)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the bile duct cancer treatment market players such as Incyte Corporation, AbbVie Inc., QED Therapeutics, GlaxoSmithKline plc., Fresenius SE & Co. KGaA, Pfizer Inc., Genentech, Inc., Eli Lilly and Company, Merck & Co., Inc., and F. Hoffmann-La Roche AG. the bile duct cancer treatment market is characterized by intense innovation, driven by the growing focus on precision oncology and targeted therapeutic approaches. Market participants compete primarily on the strength of their clinical pipelines, regulatory progress, and ability to address genetically defined patient subgroups such as FGFR- and IDH-mutated cholangiocarcinoma. Companies emphasize accelerated approval pathways, orphan drug designations, and companion diagnostics to shorten development timelines and improve treatment personalization. Combination regimens integrating targeted therapies with immunotherapy or chemotherapy are gaining traction as differentiation strategies. In addition, expanded global clinical trials, real-world evidence generation, and strategic collaborations with research institutions enhance competitive positioning. Strong manufacturing capabilities, global commercialization infrastructure, and lifecycle management strategies remain critical to sustaining long-term competitiveness in this specialized oncology market.
Key Player Analysis
- Incyte Corporation
- AbbVie Inc.
- QED Therapeutics
- GlaxoSmithKline plc.
- Fresenius SE & Co. KGaA
- Pfizer Inc.
- Genentech, Inc.
- Eli Lilly and Company
- Merck & Co., Inc.
- Hoffmann-La Roche AG
Recent Developments
- In April 2024, President of India, Droupadi Murmu, launched India's first home produced CAR T-cell therapy for cancer treatment. The NexCAR19 therapy, developed by IIT Bombay and Tata Memorial Centre, represents a significant breakthrough that will substantially reduce treatment costs.
- In March 2024, City of Hope launched its Cell Therapy Program and Blood and Marrow Transplantation at City of Hope Cancer Center Atlanta.
- In January 2024, Apollo Cancer Centers has launched India's first AI-precision oncology Centre. This Centre will aid oncologists, patients, and caregivers in achieving optimal results promptly, harnessing the extensive capabilities of AI.
Report Coverage
The research report offers an in-depth analysis based on Type, Treatment, Treatment Provider and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Precision oncology will increasingly guide treatment selection through expanded use of molecular profiling and biomarker-driven therapies.
- Targeted therapies and immunotherapies will gain wider adoption as clinical evidence strengthens across multiple disease stages.
- Combination treatment strategies integrating targeted agents, immunotherapy, and chemotherapy will improve response rates and durability.
- Earlier diagnosis supported by advanced imaging and genomic testing will expand the treatable patient population.
- Orphan drug designations and accelerated regulatory pathways will continue to support faster market entry of novel therapies.
- Real-world evidence will play a growing role in treatment optimization and post-approval decision-making.
- Expansion of clinical trial networks in emerging regions will improve patient access to innovative treatments.
- Improved tolerability and patient-centric dosing regimens will enhance adherence and quality of life.
- Strategic collaborations between pharmaceutical companies and research institutions will accelerate innovation.
- Gradual harmonization of treatment guidelines across regions will reduce care variability and support broader adoption of advanced therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Bile Duct Cancer Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Bile Duct Cancer Treatment Market projected to grow between 2024 and 2032?
Which Bile Duct Cancer Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Bile Duct Cancer Treatment Market?
Who are the leading companies in the Bile Duct Cancer Treatment Market?
Which region commanded the largest share of the Bile Duct Cancer Treatment Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bile Duct Cancer Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bile Duct Cancer Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,880 million → 2032: USD 7,235.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bile Duct Cancer Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bile Duct Cancer Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bile Duct Cancer Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bile Duct Cancer Treatment Market Drivers
- 3.3 Bile Duct Cancer Treatment Market Restraints & Challenges
- 3.4 Bile Duct Cancer Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bile Duct Cancer Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bile Duct Cancer Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bile Duct Cancer Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bile Duct Cancer Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bile Duct Cancer Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bile Duct Cancer Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bile Duct Cancer Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bile Duct Cancer Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bile Duct Cancer Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bile Duct Cancer Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bile Duct Cancer Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bile Duct Cancer Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bile Duct Cancer Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bile Duct Cancer Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bile Duct Cancer Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bile Duct Cancer Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bile Duct Cancer Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bile Duct Cancer Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bile Duct Cancer Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
