
Market Overview:
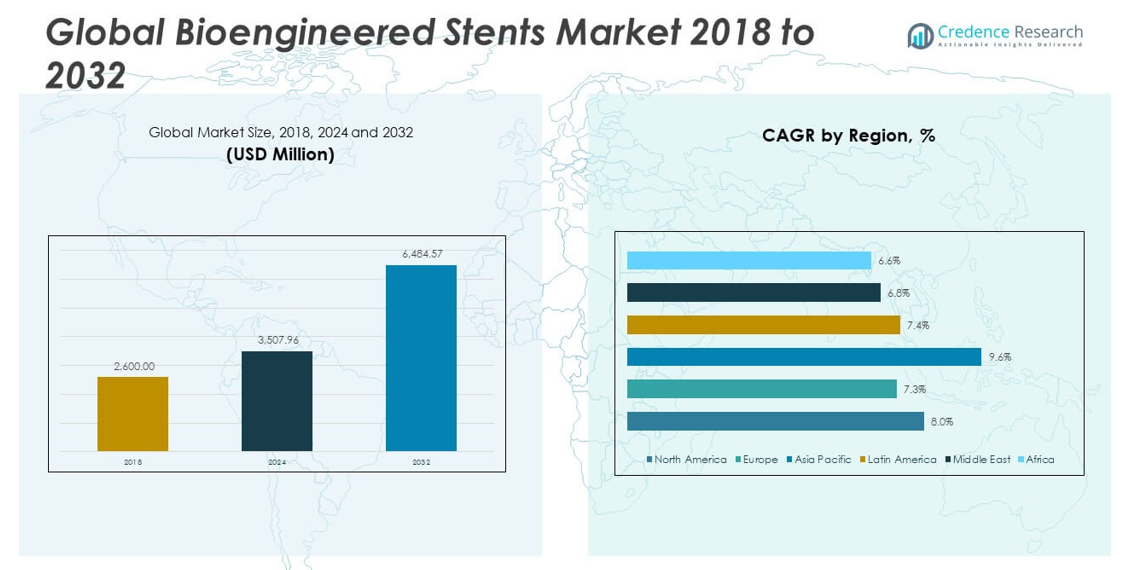
The Bioengineered Stents Market size was valued at USD 2,600.00 million in 2018 to USD 3,507.96 million in 2024 and is anticipated to reach USD 6,484.57 million by 2032, at a CAGR of 8.03% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bioengineered Stents Market Size 2024 | USD 3,507.96 million |
| Bioengineered Stents Market, CAGR | 8.03% |
| Bioengineered Stents Market Size 2032 | USD 6,484.57 million |
The growth of the Bioengineered Stents Market is fueled by several interrelated drivers. Chief among them is the rising global prevalence of cardiovascular and peripheral arterial diseases, driven by aging populations, sedentary lifestyles, and increasing rates of obesity, hypertension, and diabetes. This trend is significantly boosting the demand for effective interventional cardiology solutions. Additionally, advances in material science and biomedical engineering are enabling the development of stents with improved drug-eluting properties, controlled biodegradation, and enhanced endothelial healing, which offer superior outcomes over conventional devices. The growing preference for minimally invasive procedures is another contributing factor, as patients and clinicians increasingly favor technologies that reduce recovery time and minimize surgical risks. Furthermore, rising healthcare investments, both public and private, are supporting greater clinical adoption and research into bioengineered vascular solutions.
Regionally, North America holds the dominant share of the Bioengineered Stents Market, supported by a well-established healthcare infrastructure, early adoption of cutting-edge technologies, and a high burden of cardiovascular conditions. The United States, in particular, leads in terms of both product development and procedure volumes, driven by favorable reimbursement frameworks and a strong focus on clinical innovation. Europe follows closely, benefiting from robust research activities, strategic collaborations among medtech companies, and widespread awareness of advanced cardiac care options. Meanwhile, the Asia Pacific region is emerging as the fastest-growing market, attributed to improving healthcare access, rapid urbanization, rising incomes, and government initiatives to enhance cardiovascular treatment capacities. Countries like China, India, and Japan are witnessing increased deployment of advanced stenting solutions, bolstered by expanding hospital networks and favorable regulatory reforms. Although Latin America, the Middle East, and Africa represent relatively smaller shares, these regions are gradually gaining momentum as medical infrastructure develops and awareness of minimally invasive cardiovascular therapies improves.
Market Insights:
- The Bioengineered Stents Market was valued at USD 2,600 million in 2018 and is projected to reach USD 6,484.57 million by 2032, growing at a CAGR of 8.03%.
- Increasing global prevalence of cardiovascular diseases, driven by aging populations and sedentary lifestyles, continues to boost demand for advanced stenting solutions.
- Technological advancements in biomaterials, such as bioresorbable polymers and drug-eluting coatings, are improving clinical outcomes and encouraging product adoption.
- The strong shift toward minimally invasive cardiac procedures is expanding the use of bioengineered stents in hospitals, outpatient clinics, and surgical centers.
- Regulatory support from agencies like the FDA and EMA is accelerating product approvals, while rising healthcare investments strengthen innovation pipelines.
- Market growth faces challenges from high manufacturing costs, complex regulatory processes, and limited reimbursement policies, especially in emerging economies.
- North America holds the largest market share due to robust healthcare infrastructure, while Asia Pacific is the fastest-growing region driven by expanding access and government initiatives.
Market Drivers:
Increasing Cardiovascular Disease Prevalence Drives the Need for Advanced Treatment Solutions
The global surge in cardiovascular diseases, including coronary artery disease and peripheral artery disease, is a significant factor fueling the demand for bioengineered stents. Sedentary lifestyles, poor dietary habits, aging populations, and rising diabetes and hypertension cases contribute to the growing cardiac burden. Healthcare systems are under pressure to provide faster and more effective interventional options. The Bioengineered Stents Market addresses these needs by offering advanced alternatives to traditional stents, enhancing patient recovery and long-term outcomes. Hospitals and cardiac centers are adopting bioengineered devices that reduce complications like restenosis and thrombosis. This demand is growing steadily as healthcare providers prioritize solutions that improve patient safety and minimize repeat procedures.
- For example, according to the American Heart Association’s (AHA) 2024 Heart Disease and Stroke Statistics, cardiovascular diseases accounted for nearly 1 million deaths worldwide in 2023, with CAD responsible for approximately 10.2 millionof these fatalities.
Technological Advancements in Biomaterials and Stent Design Enhance Clinical Performance
The development of innovative biomaterials and stent engineering techniques has significantly improved the functionality of bioengineered stents. These advancements include the use of bioresorbable polymers, hybrid metal-polymer combinations, and drug-eluting coatings that promote vessel healing. Enhanced mechanical strength and optimized resorption timelines make these stents more reliable in diverse clinical conditions. The Bioengineered Stents Market benefits from continuous R&D investments focused on improving flexibility, deliverability, and biocompatibility. Researchers are creating next-generation scaffolds that provide mechanical support during critical healing phases while eventually dissolving safely in the body. It strengthens patient trust in minimally invasive procedures and encourages widespread adoption across healthcare systems.
- For example, Boston Scientific’s Synergy® stentuses a bioabsorbable poly(D,L-lactide-co-glycolide) (PLGA) polymer, completely resorbing in 3–4 months post-deployment, with 75% stent thrombosis at 5 years.
Growing Preference for Minimally Invasive Interventions Boosts Market Expansion
The shift toward less invasive treatment procedures is accelerating the adoption of bioengineered stents across global healthcare settings. Patients and physicians increasingly favor options that minimize surgical trauma, reduce hospital stays, and lower post-operative risks. It supports the broader trend in interventional cardiology toward procedures that offer high efficacy with reduced long-term complications. The Bioengineered Stents Market aligns well with this shift, as it offers products designed for optimal deployment with reduced inflammatory responses. Demand for such technologies is particularly strong in outpatient surgical centers and specialized cardiac hospitals. Increased procedural volumes are reinforcing the importance of minimally invasive innovations in vascular care.
Rising Healthcare Expenditure and Favorable Regulatory Support Encourage Innovation
Governments and private sector stakeholders are investing heavily in cardiovascular care infrastructure, contributing to the market’s sustained growth. Clinical trials and academic research centers are receiving more funding to explore bioengineered technologies, creating opportunities for new product approvals. The Bioengineered Stents Market is gaining momentum due to favorable regulatory pathways that expedite approval of high-performing devices. Agencies such as the FDA and EMA support evidence-based innovation, enabling companies to bring advanced solutions to market more efficiently. It fosters a competitive environment where medtech firms prioritize quality, safety, and therapeutic outcomes. The increased flow of capital into this space reinforces the long-term outlook for growth and technological advancement.
Market Trends:
Integration of Artificial Intelligence and Imaging Technologies Enhances Precision in Stent Deployment
The integration of artificial intelligence (AI) and advanced imaging tools is transforming cardiovascular procedures and improving outcomes. AI-guided imaging enables precise visualization of arterial blockages, helping physicians make informed decisions during stent placement. These tools support accurate assessment of vessel size, lesion characteristics, and stent positioning. It improves the effectiveness of bioengineered stents by reducing procedural errors and ensuring optimal deployment. The Bioengineered Stents Market is experiencing increased collaboration between device manufacturers and digital health companies to develop AI-powered diagnostic support systems. Real-time imaging analytics also support clinical research and post-market surveillance, strengthening the market’s value proposition.
Strategic Partnerships Between Medtech Companies and Research Institutions Accelerate Innovation
Leading medical device manufacturers are forming strategic alliances with research institutions to accelerate the development of next-generation stents. These partnerships combine industrial manufacturing capabilities with academic expertise in biomaterials and vascular biology. It allows faster innovation cycles and helps companies bring clinically validated products to market efficiently. The Bioengineered Stents Market is seeing growth in collaborative product development, especially in early-phase trials and translational research. These alliances reduce the risk associated with solo R&D investments and promote a pipeline of differentiated solutions. Joint ventures and licensing agreements are becoming standard practice among players seeking to secure long-term competitive advantage.
- For instance, Abbott’s ABSORB GT1 bioresorbable stent co-developed with the Cardiovascular Research Foundation (CRF) demonstrated a target lesion failure rate of 3.3% at three yearsin the ABSORB IV trial, a benchmarked improvement over earlier iterations.
Patient-Centric Designs Are Shaping the Evolution of Stent Customization
There is a growing trend toward designing bioengineered stents that align with individual patient anatomy and risk profiles. Customization in stent dimensions, coating formulations, and resorption timelines enhances treatment efficacy and patient comfort. It reflects the broader healthcare movement toward personalized medicine, where therapeutic devices are tailored for optimal compatibility and results. The Bioengineered Stents Market is witnessing investments in modular and adaptive stent designs that support physician flexibility in diverse clinical scenarios. These innovations improve procedural success rates and reduce the incidence of adverse events. Companies are incorporating feedback from clinicians and patients to refine design features and usability.
- For example, Biotronik’s Orsiro stent incorporates bioabsorbable polymer matrices with programmable resorption rates (3–24 months), validated in the BIOSCIENCE RCT for superior event-free survival at 5 years.
Sustainability and Green Manufacturing Practices Are Gaining Strategic Importance
Environmental sustainability is emerging as a key trend across the medical device industry, and stent manufacturing is no exception. Manufacturers are adopting eco-friendly production practices, reducing material waste, and using recyclable packaging in response to regulatory and stakeholder expectations. It reflects a shift toward responsible manufacturing that balances patient care with environmental stewardship. The Bioengineered Stents Market is starting to recognize sustainability as a factor influencing purchasing decisions among hospitals and procurement bodies. Green certifications and life-cycle assessments are being included in tenders and product evaluations. The industry is responding by aligning operational strategies with global sustainability standards.
Market Challenges Analysis:
Regulatory Complexity and Approval Delays Restrict Market Entry for Innovative Products
Navigating the regulatory environment remains a critical challenge for companies operating in the bioengineered stent space. Stringent clinical evaluation standards and lengthy approval timelines can delay product launches and inflate development costs. Regulatory agencies require comprehensive data on safety, biocompatibility, and long-term efficacy, which increases the burden on manufacturers. Smaller firms and startups face greater obstacles due to limited resources and technical expertise in regulatory affairs. The Bioengineered Stents Market must address these hurdles by investing in robust clinical trials and engaging with regulators early in the development process. It also requires strategic planning to balance innovation speed with compliance demands, which directly affects time-to-market and profitability.
High Manufacturing Costs and Limited Reimbursement Policies Hinder Commercial Scalability
Producing bioengineered stents involves complex processes, advanced materials, and stringent quality controls, which significantly increase production costs. These high costs often translate into premium pricing that may not align with reimbursement structures in many healthcare systems. Limited insurance coverage and inconsistent reimbursement policies discourage adoption, especially in price-sensitive markets. Hospitals and clinics hesitate to invest in advanced stents without clear cost-effectiveness data or reimbursement assurance. The Bioengineered Stents Market faces a challenge in demonstrating economic value alongside clinical benefits to secure broader market access. It must bridge the gap between innovation and affordability to achieve sustainable growth across diverse geographies.
Market Opportunities:
Emerging Economies Offer Strong Growth Potential Through Expanding Healthcare Access
Rising healthcare investments and infrastructure development in emerging markets present a major opportunity for bioengineered stent manufacturers. Countries across Asia Pacific, Latin America, and the Middle East are expanding public and private cardiovascular care services. These regions report high unmet needs for advanced interventional treatments due to increasing cardiovascular disease prevalence. The Bioengineered Stents Market can benefit from this growth by introducing cost-effective, scalable solutions tailored to local regulatory and clinical frameworks. It allows companies to diversify their revenue base and strengthen global market presence. Strategic partnerships with regional distributors and healthcare providers will be key to capitalizing on this potential.
Personalized Medicine and Digital Integration Enable Advanced Therapeutic Solutions
The global shift toward personalized medicine supports demand for customizable and adaptive stent technologies. Innovations in 3D imaging, patient-specific modeling, and AI-guided diagnostics create pathways for individualized treatment plans. The Bioengineered Stents Market has an opportunity to lead in integrating these capabilities into next-generation product design. It can enhance clinical precision and support superior patient outcomes. Companies that align device innovation with data-driven treatment protocols will be better positioned to meet evolving medical standards. These opportunities reinforce the market’s relevance in a technology-centric healthcare landscape.
Market Segmentation Analysis:
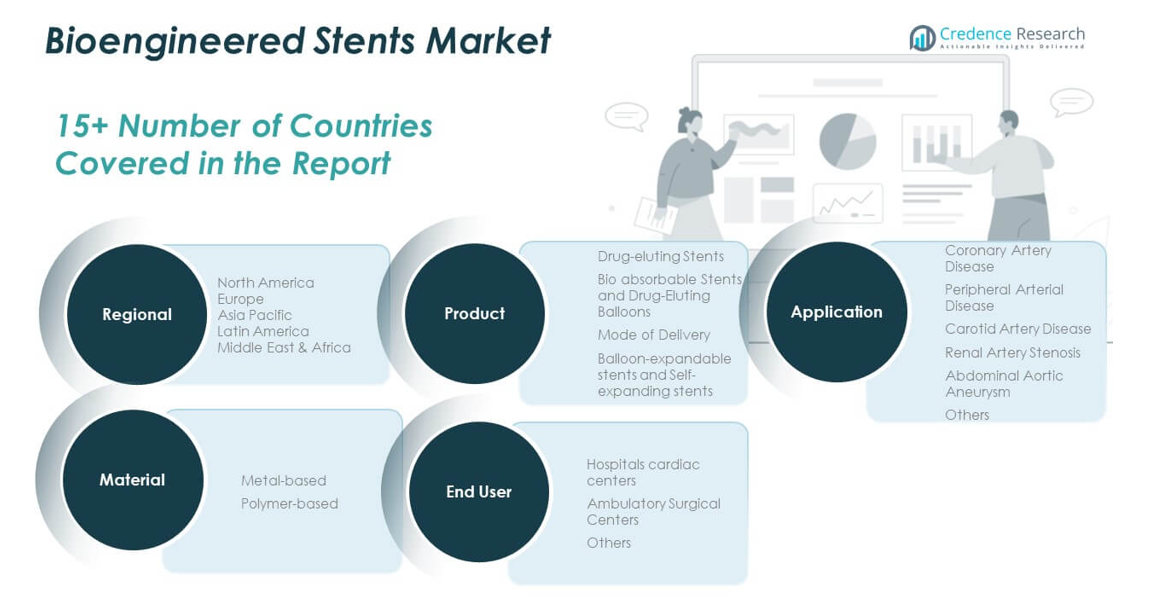
The Bioengineered Stents Market is segmented by product, application, material, and end user, reflecting a diverse and evolving landscape.
By product types, drug-eluting stents dominate due to their efficacy in reducing restenosis. Bioabsorbable stents and drug-eluting balloons are gaining attention for their ability to dissolve after vessel healing. Balloon-expandable stents remain widely used in stable lesions, while self-expanding stents are preferred in tortuous or diseased vessels.
By application, coronary artery disease accounts for the largest market share due to high global prevalence and procedural volumes. Peripheral arterial disease and carotid artery disease represent significant growth areas due to rising diagnosis rates. The market also sees increasing use in renal artery stenosis and abdominal aortic aneurysm interventions, driven by advances in imaging and delivery systems.
By material, metal-based stents lead in adoption, offering strong mechanical support, while polymer-based stents are expanding rapidly due to their biodegradable properties and improved biocompatibility.
- For example, Abbott’s Xience Sierra(cobalt-chromium alloy) has a radial strength of 1.4 MPa and a strut thickness of 81 µm, enabling durability in calcified lesions.
By end user Hospitals and cardiac centers hold the largest share in the end user segment, supported by high patient footfall and advanced infrastructure. Ambulatory surgical centers are expanding their role in stent deployment, offering cost-effective and minimally invasive solutions. The market also includes other specialized clinics that serve growing outpatient demand.
- For example, Cleveland Clinic, consistently ranked among the top heart hospitals in the U.S., reports performing a high volume of PCI procedures annually, supported by dedicated hybrid catheterization labs designed for complex cases. Ambulatory surgical centers (ASCs) are seeing increasing adoption of cardiac technologies.
Segmentation:
By Product:
- Drug-eluting Stents
- Bioabsorbable Stents and Drug-Eluting Balloons
- Mode of Delivery
- Balloon-expandable Stents
- Self-expanding Stents
By Application:
- Coronary Artery Disease
- Peripheral Arterial Disease
- Carotid Artery Disease
- Renal Artery Stenosis
- Abdominal Aortic Aneurysm
- Others
By Material:
- Metal-based Stents
- Polymer-based Stents
By End User:
- Hospitals and Cardiac Centers
- Ambulatory Surgical Centers
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Bioengineered Stents Market size was valued at USD 1,046.76 million in 2018 to USD 1,396.85 million in 2024 and is anticipated to reach USD 2,578.93 million by 2032, at a CAGR of 8.0% during the forecast period. North America holds the largest market share, accounting for nearly 32% of the global market in 2024. The region benefits from well-established healthcare infrastructure, early adoption of advanced technologies, and high expenditure on cardiovascular care. The Bioengineered Stents Market in North America continues to expand due to the growing burden of coronary artery disease and favorable reimbursement policies. The United States leads regional demand, supported by strong clinical research and a high volume of interventional procedures. It also benefits from the presence of major medical device manufacturers actively launching innovative stent platforms. Strategic collaborations and regulatory support further drive sustained growth across the region.
Europe
The Europe Bioengineered Stents Market size was valued at USD 666.38 million in 2018 to USD 863.21 million in 2024 and is anticipated to reach USD 1,508.65 million by 2032, at a CAGR of 7.3% during the forecast period. Europe represents approximately 20% of the global market in 2024, driven by advancements in interventional cardiology and a strong emphasis on quality healthcare. The region benefits from coordinated regulatory frameworks, especially through the European Medicines Agency (EMA), which accelerates innovation adoption. The Bioengineered Stents Market in Europe shows robust demand in countries like Germany, France, and the UK, where awareness of advanced treatment options is high. It also gains traction from active government support for R&D and public-private healthcare partnerships. Growing geriatric populations and a rise in chronic diseases continue to influence market expansion in the region.
Asia Pacific
The Asia Pacific Bioengineered Stents Market size was valued at USD 476.32 million in 2018 to USD 680.70 million in 2024 and is anticipated to reach USD 1,415.13 million by 2032, at a CAGR of 9.6% during the forecast period. Asia Pacific accounts for nearly 16% of the global market in 2024 and represents the fastest-growing region. Rapid urbanization, rising disposable incomes, and increasing cardiovascular disease prevalence are major growth drivers. The Bioengineered Stents Market in Asia Pacific benefits from expanding hospital networks and improving access to interventional care in countries like China, India, and Japan. It also attracts foreign direct investments and partnerships aimed at boosting local manufacturing. Government initiatives to reduce treatment costs and improve cardiac care access further accelerate growth.
Latin America
The Latin America Bioengineered Stents Market size was valued at USD 242.32 million in 2018 to USD 324.80 million in 2024 and is anticipated to reach USD 571.10 million by 2032, at a CAGR of 7.4% during the forecast period. Latin America holds approximately 7.5% of the global market share in 2024, with steady demand growth expected in coming years. Rising awareness of cardiovascular health and growing healthcare investments are key factors supporting market development. The Bioengineered Stents Market in Latin America benefits from the adoption of advanced devices in private hospitals and specialty centers. Countries such as Brazil, Mexico, and Argentina are central to regional growth. It still faces challenges in regulatory consistency and healthcare infrastructure disparity, but the overall outlook remains positive.
Middle East
The Middle East Bioengineered Stents Market size was valued at USD 112.32 million in 2018 to USD 143.10 million in 2024 and is anticipated to reach USD 241.91 million by 2032, at a CAGR of 6.8% during the forecast period. The region contributes nearly 3.3% of global market share in 2024. Increasing healthcare expenditure and the development of advanced cardiac care centers are supporting regional market expansion. The Bioengineered Stents Market in the Middle East shows steady uptake in countries such as Saudi Arabia, UAE, and Qatar. It benefits from medical tourism and growing partnerships with global medtech firms. Government focus on modernizing healthcare infrastructure is further propelling market activity across the region.
Africa
The Africa Bioengineered Stents Market size was valued at USD 55.90 million in 2018 to USD 99.29 million in 2024 and is anticipated to reach USD 168.85 million by 2032, at a CAGR of 6.6% during the forecast period. Africa accounts for just over 2% of the global market in 2024, reflecting limited but gradually increasing adoption. The region faces significant challenges in access, affordability, and infrastructure development. However, the Bioengineered Stents Market in Africa is gaining interest through pilot programs and donor-funded initiatives targeting cardiac care. South Africa and Egypt are key regional hubs with growing medical device import volumes. It offers long-term growth potential as awareness and access to life-saving cardiovascular interventions improve across the continent.
Key Player Analysis:
- Boston Scientific Corporation
- Abbott Laboratories
- Biotronik SE & Co. KG
- Braun Melsungen AG
- Terumo Corporation
- MicroPort Scientific Corporation
- Stentys SA
- Meril Life Sciences Pvt. Ltd
- Vascular Concepts
Competitive Analysis:
The Bioengineered Stents Market features a competitive landscape led by global medical device manufacturers focused on innovation and clinical performance. Key players such as Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, and Biotronik SE & Co. KG maintain strong market positions through extensive product portfolios and continuous R&D investments. It sees rising competition from emerging companies introducing next-generation stents with enhanced bioresorbable materials and drug-delivery capabilities. Strategic collaborations, licensing agreements, and regulatory approvals are central to gaining market share. Companies are also investing in clinical trials to validate efficacy and safety, which helps strengthen their global presence. The Bioengineered Stents Market rewards firms that prioritize product differentiation, cost-effectiveness, and physician trust. Competitive dynamics are evolving, with regional players entering high-growth markets and multinational corporations expanding their geographic reach through partnerships and acquisitions. It remains an innovation-driven sector where success depends on technological leadership and regulatory agility.
Recent Developments:
- In July 2025, Boston Scientific Corporation received FDA approval for expanded labeling of the FARAPULSE™ Pulsed Field Ablation System, which, while focused on ablation, also positions the company to reinforce its status in minimally invasive cardiovascular therapies, complementing its existing bioengineered stents portfolio.
- In July 2025, Biotronik SE & Co. KG’s Vascular Intervention business was acquired by Teleflex Incorporated. This acquisition included bioengineered vascular products such as drug-eluting and covered stents, and the Freesolve sirolimus-eluting resorbable magnesium scaffold (RMS), which had recently achieved CE Mark approval and is under clinical evaluation.
Market Concentration & Characteristics:
The Bioengineered Stents Market exhibits moderate to high market concentration, with a few multinational corporations dominating global revenue. It is characterized by high entry barriers due to complex regulatory requirements, substantial R&D investments, and the need for clinical validation. The market relies heavily on technological innovation, with a strong focus on biocompatibility, bioresorbable materials, and targeted drug delivery. It remains highly competitive, with established players continuously enhancing product performance and expanding portfolios through acquisitions and partnerships. The market also reflects a growing demand for customized and patient-specific solutions, encouraging niche innovation alongside large-scale manufacturing. It supports both high-margin premium devices and cost-effective alternatives targeting emerging regions.
Report Coverage:
The research report offers an in-depth analysis based on product, application, material, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global cardiovascular disease burden will continue to drive long-term demand for advanced stent technologies.
- Expansion of healthcare infrastructure in emerging economies will open new revenue streams for manufacturers.
- Advancements in biodegradable materials will improve clinical outcomes and boost product adoption.
- Growing focus on personalized medicine will accelerate the development of patient-specific stent solutions.
- Integration of AI and real-time imaging will enhance precision in stent deployment and procedural success.
- Strategic collaborations between medtech firms and research institutions will fuel innovation pipelines.
- Increasing regulatory support for high-efficacy devices will shorten approval timelines in key markets.
- Cost-reduction efforts and local manufacturing will make premium devices more accessible in price-sensitive regions.
- Investment in sustainable manufacturing practices will influence procurement decisions across developed markets.
- Ongoing clinical trials and product upgrades will reinforce physician trust and market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The increasing global incidence of cardiovascular and peripheral arterial diseases, driven by aging populations, sedentary lifestyles, and rising rates of diabetes and hypertension, is significantly boosting demand for advanced bioengineered stents as effective interventional solutions.
Technological Advancements in Biomaterials and Stent Design
Continuous innovation in biomaterials, such as bioresorbable polymers and drug-eluting coatings, is improving the safety, efficacy, and adoption of bioengineered stents by offering better clinical outcomes and reducing complications like restenosis and thrombosis.
Growing Preference for Minimally Invasive Procedures
Patients and clinicians are increasingly favoring minimally invasive cardiac interventions, which bioengineered stents enable, due to reduced recovery times, lower surgical risks, and improved patient comfort, thereby expanding procedural volumes and market demand.
Favorable Regulatory Support and Healthcare Investments
Supportive regulatory frameworks from agencies like the FDA and EMA, along with rising public and private healthcare investments, are accelerating product approvals and fostering innovation, making advanced stent technologies more accessible across global markets.
Expansion of Healthcare Infrastructure in Emerging Markets
Rapid improvements in healthcare access, infrastructure, and government initiatives in regions such as Asia Pacific and Latin America are creating new opportunities for bioengineered stent manufacturers to penetrate high-growth markets and diversify revenue streams.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bioengineered Stents Market?
What are the key segments within the Bioengineered Stents Market?
What are some challenges faced by the Bioengineered Stents Market?
Who are the major players in the Bioengineered Stents Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Drug-eluting Stents
- 1.2.2 Bioabsorbable Stents and Drug-Eluting Balloons
- 1.2.3 Balloon-expandable Stents
- 1.2.4 Self-expanding Stents
- 1.3 By End User
- 1.3.1 Hospitals and Cardiac Centers
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Others
- 1.4 By Material
- 1.4.1 Metal-based Stents
- 1.4.2 Polymer-based Stents
- 1.5 By Application
- 1.5.1 Coronary Artery Disease
- 1.5.2 Peripheral Arterial Disease
- 1.5.3 Carotid Artery Disease
- 1.5.4 Renal Artery Stenosis
- 1.5.5 Abdominal Aortic Aneurysm
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,507.96 million → 2032: USD 6,484.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bioengineered Stents Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bioengineered Stents Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bioengineered Stents Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bioengineered Stents Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bioengineered Stents Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bioengineered Stents Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bioengineered Stents Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bioengineered Stents Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,507.96 million → 2032: USD 6,484.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bioengineered Stents Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drug-eluting Stents
- 12.3.7.2 Bioabsorbable Stents and Drug-Eluting Balloons
- 12.3.7.3 Balloon-expandable Stents
- 12.3.7.4 Self-expanding Stents
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals and Cardiac Centers
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metal-based Stents
- 12.5.7.2 Polymer-based Stents
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Coronary Artery Disease
- 12.6.7.2 Peripheral Arterial Disease
- 12.6.7.3 Carotid Artery Disease
- 12.6.7.4 Renal Artery Stenosis
- 12.6.7.5 Abdominal Aortic Aneurysm
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bioengineered Stents End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bioengineered Stents Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bioengineered Stents Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bioengineered Stents Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Boston Scientific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 Biotronik SE & Co. KG
- 18.5 B. Braun Melsungen AG
- 18.6 Terumo Corporation
- 18.7 MicroPort Scientific Corporation
- 18.8 Stentys SA
- 18.9 Meril Life Sciences Pvt. Ltd
- 18.10 Vascular Concepts
- 18.11 Medtronic plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

